
 Europe Pharmaceutical Cold Chain Logistics Market | 2026-2036
Europe Pharmaceutical Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Cold Chain Logistics Market Insights
Biopharmaceutical manufacturers are redrawing Europe's cold chain procurement priorities, shifting volume toward outsourced temperature-controlled logistics partners that can validate lane integrity across multiple jurisdictions. Kuehne + Nagel anchors its position through dedicated pharma facilities in Belgium and the Netherlands with GDP-certified warehousing. DHL Supply Chain leverages real-time telemetry networks to sustain end-to-end visibility for cell and gene therapy shipments. DSV competes on Nordic-Baltic lane density, where its integrated road-air model covers secondary distribution into remote hospital pharmacies.
Europe pharmaceutical cold chain logistics encompasses the temperature-controlled movement, storage, and monitoring of medicinal products requiring strict thermal bands to preserve molecular stability, with validated cold rooms maintaining 2°C to 8°C for standard vaccines and ultra-low freezers hitting -80°C for mRNA-based therapeutics. Its commercial purpose centers on preventing potency degradation that would trigger batch destruction, patient safety incidents, or regulatory non-conformity. Biologics and plasma products command the deepest cold chain investment due to protein fragility and narrow stability windows, while the -40°C to -30°C band represents the fastest-growing temperature segment as advanced therapy medicinal products proliferate. Monitoring services capture expanding margin pools because sensor redundancy and cloud-based excursion alerting now feature in most tender evaluations.
EMA's Good Distribution Practice mandates temperature mapping and qualification across all EU member states, while the F-Gas Regulation phases down hydrofluorocarbon refrigerants and pushes fleet operators toward CO2-based or cryogenic alternatives. REACH compliance adds material traceability requirements for insulating foams and phase-change materials used in thermal packaging. Stakeholders must decide whether to absorb refrigerant transition costs or restructure lane economics around shorter hub-to-hub segments with electric last-mile handoffs.
Market Dynamics
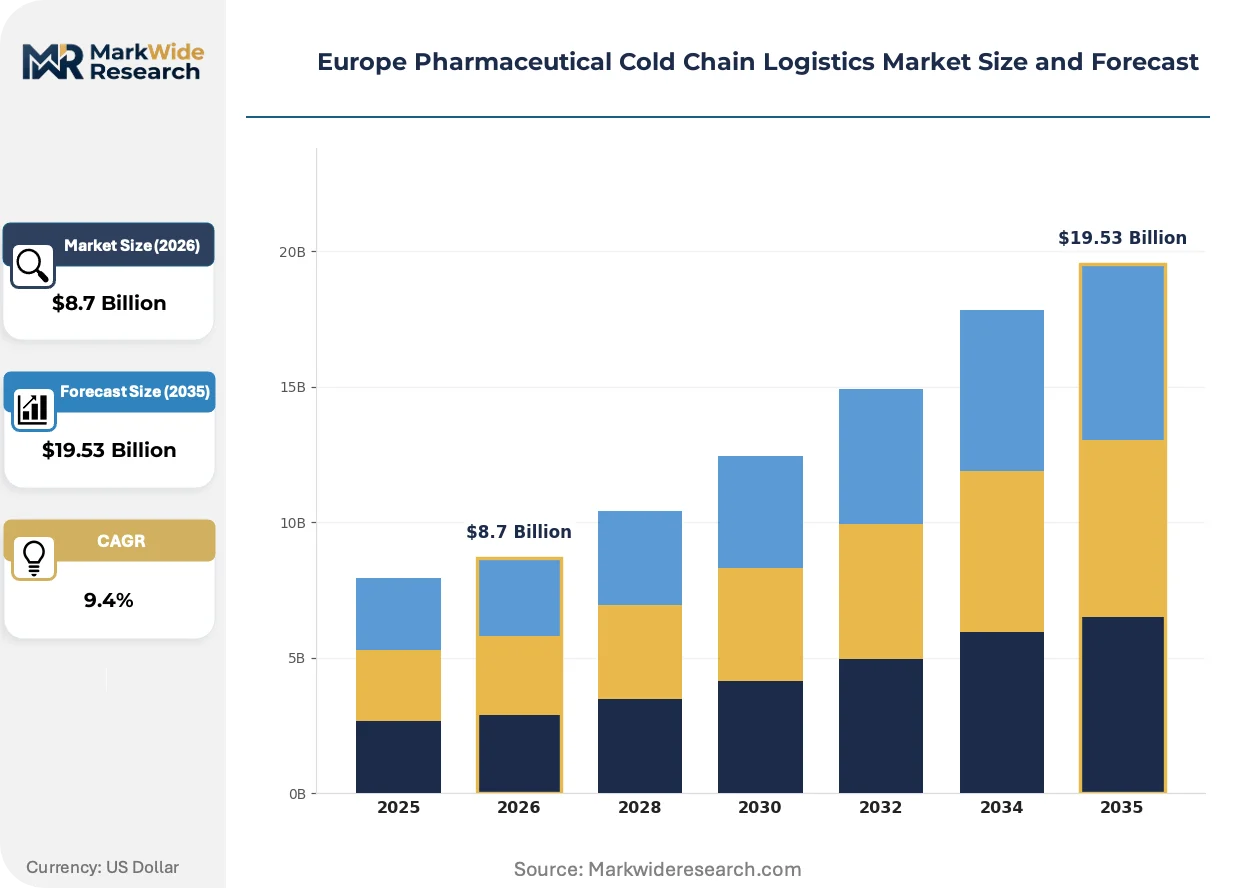
Europe's pharmaceutical cold chain logistics sector is restructuring around the EU F-Gas Regulation's phase-down of hydrofluorocarbon refrigerants, forcing fleet operators and warehouse developers to rebuild thermal infrastructure around CO2-based and cryogenic cooling systems before 2030 mandates take full effect.
Growth Catalysts
- Advanced Therapy Medicinal Products:Cell and gene therapies requiring -80°C to -150°C storage are multiplying across Belgium, the Netherlands, and Germany, pulling in specialized ultra-low freezer capacity and validated lane infrastructure.
- EMA Good Distribution Practice:The 2013/C 343/01 guidelines mandate continuous temperature monitoring and qualification documentation, compelling manufacturers to outsource to GDP-certified logistics partners rather than self-operate.
- Cross-border distribution density:Germany's central European geography and highway network concentration enable hub-and-spoke models that reduce transit time variability for temperature-sensitive biologics moving into Nordic and Eastern European markets.
Market Restraints
- Refrigerant transition costs:The F-Gas Regulation's stepped reduction schedule forces cold storage operators to replace HFC-based systems with transcritical CO2 or ammonia alternatives, compressing margins on legacy facilities.
- Insulating material compliance:REACH restrictions on certain phase-change materials and polyurethane foams limit thermal packaging options, requiring reformulation of validated shipper designs.
- Specialized fleet scarcity:Refrigerated truck capacity with dual-temperature zones and real-time telemetry remains concentrated among a narrow supplier base in the Nordic-Baltic corridor, creating lane availability bottlenecks.
Strategic Opportunities
- Secondary distribution in Eastern Europe:Hospital pharmacy networks in Poland, Hungary, and Romania remain underserved by GDP-validated last-mile providers, opening territory for temperature-controlled parcel services.
- Real-time visibility convergence:Integration of IoT sensor networks with blockchain-based chain-of-custody records is creating premium service tiers that command higher margins in tender evaluations.
- Electric last-mile handoffs:Urban low-emission zones in Amsterdam, Brussels, and Paris are accelerating demand for refrigerated electric vans with swap-body capabilities for final delivery to clinical sites.
Industry Challenges
- Qualified personnel scarcity:GDP auditors and temperature mapping specialists with pharmaceutical-specific validation experience are in short supply across the region, extending commissioning timelines for new facilities.
- Multi-jurisdiction qualification complexity:Each EU member state maintains distinct national competent authority interpretations of EMA guidelines, forcing redundant documentation for cross-border lanes.
- Sensor calibration drift:Wireless data logger accuracy degrades in ultra-low freezer environments, creating excursion alert false positives that strain customer trust and operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Cold Chain Logistics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Biologics, Plasma Products, Temperature-Sensitive Drugs Temperature Range: 2°C to 8°C, -20°C to -10°C, -40°C to -30°C, Ambient Temperature Service Type: Transportation, Packaging, Monitoring, Distribution End User: Pharmacies, Hospitals, Clinics, Research Laboratories |
| Companies Covered | DB Schenker, A.P. Moller – Maersk, DHL Supply Chain, Geodis, UPS, Kuehne + Nagel, CEVA Logistics, Yusen Logistics, DSV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Cold Chain Logistics Market Trends and Innovations
Digital instrumentation and refrigerant chemistry are converging to redefine temperature assurance standards, compressing the gap between warehouse-controlled environments and last-mile thermal performance.
Passive thermal packaging systems using vacuum-insulated panels and phase-change materials are displacing active refrigerated containers for high-value cell therapy shipments between Belgium's manufacturing clusters and hospital pharmacies. Biologics manufacturers in the Antwerp-Rotterdam corridor are adopting these lighter systems to reduce air freight dimensional weight charges. The shift is displacing traditional compressor-based active units on lanes under 48 hours, restructuring equipment procurement priorities toward thermal mass engineering.
The EU F-Gas Regulation's 2024 stepped reduction targets are accelerating adoption of transcritical CO2 refrigeration in new Dutch and German distribution centers. Cold storage developers must now engineer systems around global warming potential limits that disqualify conventional HFC refrigerants. The pharmaceutical warehouse segment is responding fastest, driven by EMA GDP requirements that link environmental compliance to facility qualification status.
Buyer consolidation among hospital pharmacy groups is compressing tender cycles and unbundling after-sales monitoring services from core logistics contracts. Large German hospital networks now separately procure real-time telemetry dashboards from specialized software vendors rather than accepting bundled 3PL offerings. This unbundling is most visible in the Rhine-Ruhr metropolitan region, where purchasing cooperatives represent 40-plus hospital sites in consolidated cold chain tenders.
Europe Pharmaceutical Cold Chain Logistics Market Segmentation
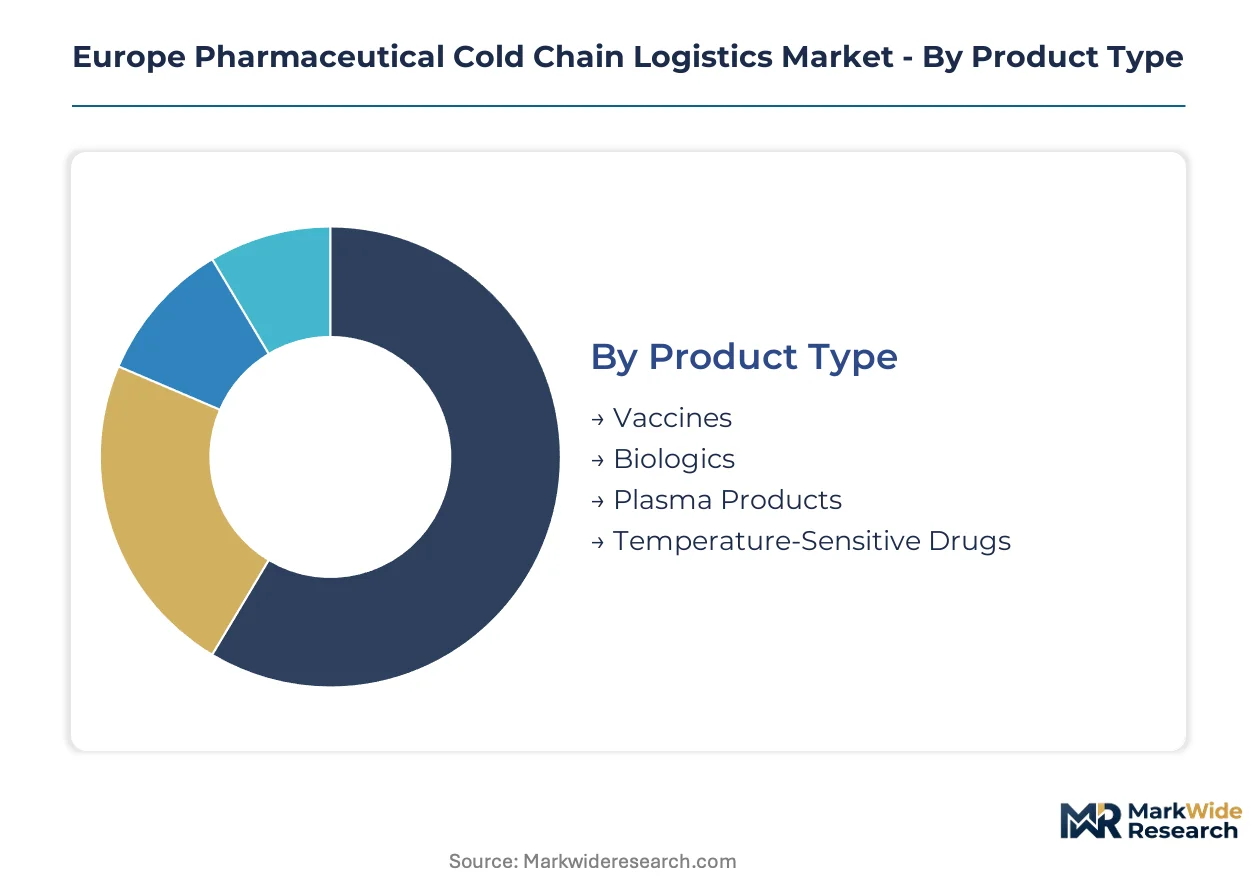
Segmentation in Europe's pharmaceutical cold chain logistics market reveals distinct operational requirements across temperature bands and service types. Biologics and cell therapies demand specialized infrastructure that reshapes procurement priorities for 3PL providers. Understanding these divisions exposes where margin pools concentrate and where compliance complexity escalates.
Product Type:
Domestic European manufacturing clusters in Belgium and Germany anchor demand for biologics and plasma products, while vaccine distribution pulls cross-border volume into export corridors serving Eastern European markets.
- Vaccines:Standard 2°C to 8°C handling dominates volume, with mRNA platforms requiring -80°C ultra-low chains. German and Dutch distribution hubs manage bulk procurement for national immunization programs across the region.
- Biologics:Monoclonal antibodies and recombinant proteins command premium logistics spend due to protein instability and narrow stability windows. Belgian manufacturing corridors generate concentrated outbound flows to hospital pharmacies in France and Germany.
- Plasma Products:Fractionated plasma derivatives require frozen storage at -20°C to -30°C with validated thaw protocols. Demand clusters around centralized fractionation facilities in Germany and Austria.
- Temperature-Sensitive Drugs:Small-molecule therapies with defined thermal limits represent high-volume, lower-margin business. Generic manufacturers in Eastern Europe drive cost-competitive tendering for these lanes.
Biologics commands the established base. The steepest expansion runs through vaccines as mRNA manufacturing scales across the Benelux corridor.
Temperature Range:
Cost tiers separate segments sharply, with ultra-low infrastructure requiring capital investment five to ten times standard cold room economics.
- 2°C to 8°C:The standard pharmaceutical cold chain band covers most vaccines and biologics. GDP-certified warehouse capacity in the Netherlands and Germany absorbs the majority of regional volume, with lane density highest on Rhine corridor routes.
- -20°C to -10°C:Frozen storage for certain biologics and plasma derivatives. Facilities in Austria and Switzerland specialize in these bands for clinical trial material distribution.
- -40°C to -30°C:Advanced therapy medicinal products and specialized biologics drive infrastructure investment here. Belgian cell therapy manufacturing clusters are commissioning dedicated -40°C validated lanes into German hospital networks.
- Ambient Temperature:Controlled room temperature bands of 15°C to 25°C for stable small molecules. This segment competes on cost efficiency rather than technical specialization, with Polish and Romanian distributors capturing share through price aggressive tendering.
Standard refrigeration holds volume leadership. Ultra-low bands below -30°C are climbing the fastest as ATMP manufacturing expands.
Service Type:
Customer procurement patterns unbundle monitoring from core logistics, creating standalone software revenue streams alongside physical handling contracts.
- Transportation:Refrigerated trucking with real-time telemetry underpins lane integrity. Nordic-Baltic corridors suffer capacity scarcity, pushing shippers toward multimodal rail alternatives for bulk pharmaceutical movements.
- Packaging:Passive thermal systems using vacuum-insulated panels displace active containers on sub-48-hour lanes. Dutch and Belgian shippers lead adoption to reduce air freight dimensional weight exposure.
- Monitoring:Cloud-based excursion alerting and sensor redundancy now feature in most tender evaluations. German hospital purchasing cooperatives separately procure dashboard services from specialized vendors.
- Distribution:Hub-and-spoke warehouse networks with GDP qualification anchor regional supply chains. Central European geography favors German facilities for cross-border secondary distribution into Poland and Czechia.
Transportation and distribution retain the revenue base. Monitoring services are gaining share fastest as buyers unbundle telemetry from bundled 3PL contracts.
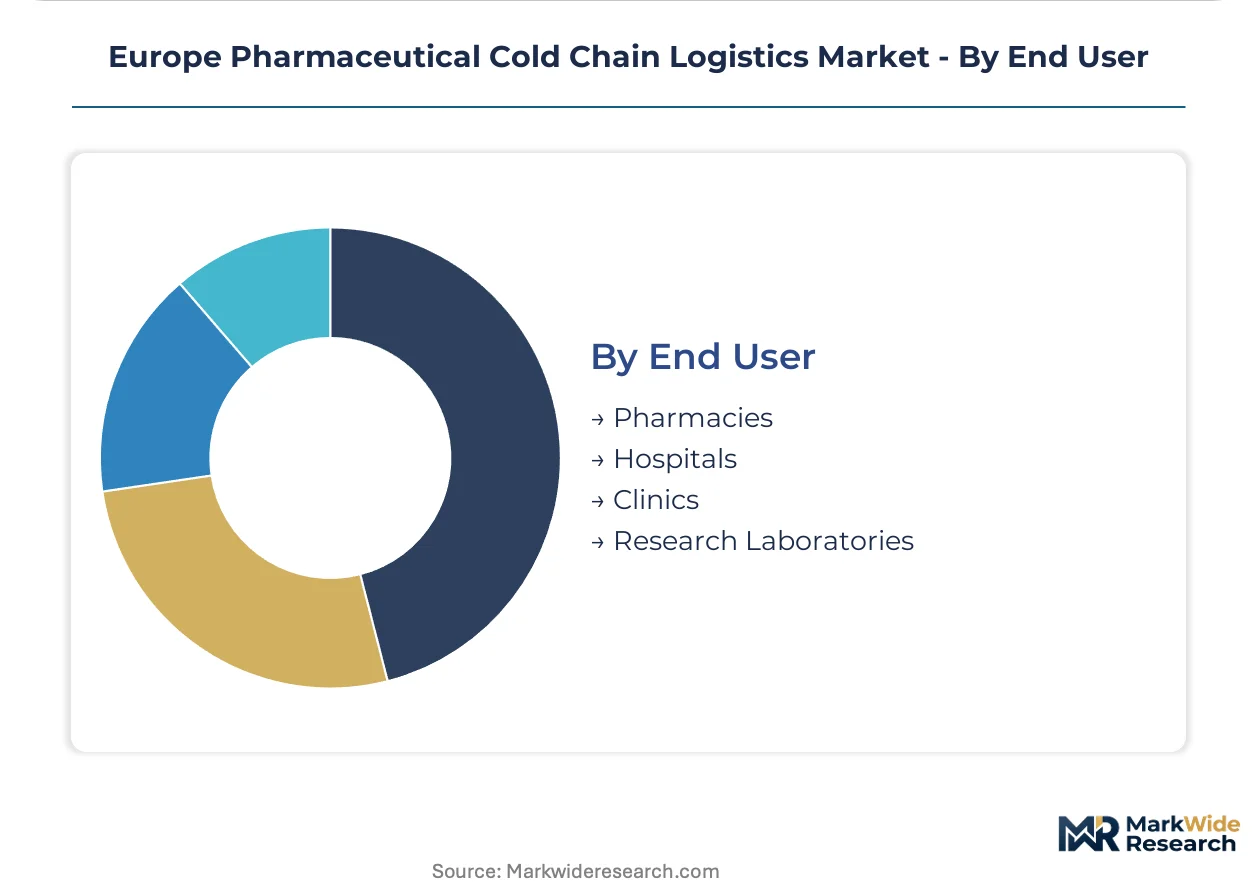
End User:
Facility scale and regulatory exposure differentiate end users, with large hospital networks driving standardization while research laboratories demand customization.
- Pharmacies:Hospital pharmacy networks consolidate purchasing power through cooperatives. The Rhine-Ruhr metropolitan cluster represents 40-plus sites in unified cold chain tenders.
- Hospitals:Tertiary care centers with in-house compounding require validated last-mile delivery. Urban low-emission zones in Amsterdam, Brussels, and Paris accelerate demand for refrigerated electric vans.
- Clinics:Smaller clinical sites with limited storage capacity depend on frequent, small-batch deliveries. Eastern European outpatient networks remain underserved by GDP-validated parcel services.
- Research Laboratories:Clinical trial material logistics demands chain-of-custody documentation and temperature qualification. Belgian and Dutch trial hubs generate specialized inbound flows from global manufacturing sites.
Hospital networks command procurement volume. Research laboratories are expanding most quickly as cell therapy trials proliferate across the Benelux corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium exports cell therapy materials to German hospital networks through validated -80°C lanes, while Dutch distribution hubs handle cross-border vaccine procurement for Eastern European immunization programs.
Germany
Monoclonal antibody manufacturing in the Rhine-Ruhr corridor and centralized plasma fractionation facilities drive specialized cold storage demand. The F-Gas Regulation forces warehouse operators toward transcritical CO2 systems before 2030 deadlines. Bavaria's Munich-Ingolstadt pharma cluster commissions dedicated GDP-qualified facilities for ATMP distribution.
Belgium
Cell and gene therapy production in the Antwerp-Leuven corridor requires ultra-low freezer infrastructure and validated lane networks. EMA guidelines mandate continuous temperature monitoring across all outbound shipments. The Port of Antwerp anchors multimodal cold chain corridors serving French and German hospital pharmacies.
Netherlands
Vaccine bulk storage and distribution for national immunization programs concentrate around Rotterdam and Schiphol logistics zones. REACH compliance restricts phase-change materials in thermal packaging, forcing shipper redesigns. Dutch 3PLs lead adoption of passive vacuum-insulated panel systems to reduce air freight dimensional weight exposure.
France
Hospital pharmacy networks in the Paris-Saclay biocluster demand validated last-mile delivery with real-time telemetry. Urban low-emission zones in Paris and Brussels accelerate procurement of refrigerated electric vans for final delivery. The Île-de-France region hosts specialized clinical trial material logistics serving global pharmaceutical sponsors.
Poland
Secondary distribution into hospital pharmacy networks remains underserved by GDP-validated providers, creating territory for temperature-controlled parcel services. National interpretations of EMA guidelines require redundant documentation for cross-border lanes from Germany. Warsaw and Kraków clinical sites increasingly source biologics through validated hub-and-spoke models.
Europe Pharmaceutical Cold Chain Logistics Market Competitive Landscape
Player mix skews toward integrated 3PL networks with dedicated pharmaceutical divisions rather than pure-play cold chain specialists. Market structure concentrates among five to seven operators with GDP-certified warehouse networks spanning multiple EU jurisdictions. Two strategic archetypes dominate: asset-heavy operators with owned refrigerated fleets and facility networks, and asset-light coordinators leveraging partner capacity for lane coverage. Competitive moves center on M&A for specialized ATMP handling capabilities and strategic partnerships for last-mile electric vehicle deployment in urban low-emission zones.
Within the integrated 3PL tier, Kuehne + Nagel, DHL Supply Chain, and DSV occupy positions defined by geographic lane density and temperature band specialization. Kuehne + Nagel anchors Benelux corridor coverage through dedicated pharmaceutical facilities. DHL Supply Chain exemplifies real-time telemetry integration for cell therapy visibility requirements. DSV represents Nordic-Baltic lane concentration with multimodal road-air capabilities.
| Leading Market Players |
|---|
| DB Schenker |
| A.P. Moller – Maersk |
| DHL Supply Chain |
| Geodis |
| UPS |
| Kuehne + Nagel |
| CEVA Logistics |
| Yusen Logistics |
| DSV |
| Others |
Pricing and Supply Chain Analysis
Facility scale economies in German GDP-certified warehousing compress unit costs for cross-border biologics distribution, concentrating pricing power among operators with multi-temperature infrastructure while elevating price floors for specialized -80°C lanes serving Belgian cell therapy manufacturers.
Pricing Analysis
Prior-generation HFC-based refrigeration systems trade at 30-40% discounts to transcritical CO2 installations, while next-generation cryogenic cooling commands premiums for ultra-low ATMP handling. Three-tier pricing structure across GDP-certified premium, standard cold-chain, and economy ambient bands dominates contract structures. Price differentiation hinges on EMA certification tier and real-time telemetry bundling. Cost compression in standard 2°C to 8°C lanes is intensifying because Polish and Romanian distributors compete aggressively on Eastern European secondary distribution. Generic pharmaceutical manufacturers exhibit highest price sensitivity; cell therapy sponsors show lowest.
Supply Chain Analysis
Belgium and the Netherlands anchor European pharmaceutical cold chain infrastructure through Antwerp-Rotterdam corridor manufacturing clusters and Schiphol-anchored air freight gateways. German distribution hubs feed from these nodes, drawing from specialized ultra-low freezer capacity and vacuum-insulated panel packaging inputs. Single-source vulnerability concentrates in Nordic-Baltic refrigerated trucking capacity, where dual-temperature fleet scarcity creates lane bottlenecks. Distribution runs through hub-and-spoke warehouse networks with GDP-qualified secondary handoffs into hospital pharmacy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat business where EMA Good Distribution Practice certification creates switching costs that entrench incumbent positions and extend contract tenures.
For Market Incumbents: Consolidate specialized ATMP handling capabilities through targeted facility investments in Bavaria's Munich-Ingolstadt corridor, where cell therapy manufacturing is clustering. Acquire GDP-auditor talent pools to compress commissioning timelines for new transcritical CO2 warehouses ahead of F-Gas Regulation deadlines. Vertical integration into passive thermal packaging engineering reduces exposure to REACH-restricted phase-change material reformulation costs. For New Entrants and Emerging Players: EMA GDP certification fast-tracks in Poland and Romania open white-space territory where hospital pharmacy networks remain underserved by validated last-mile providers. Target temperature-controlled parcel services for Eastern European outpatient clinics with limited storage capacity. Pursue strategic partnerships with Dutch vacuum-insulated panel manufacturers to differentiate on dimensional weight savings for air freight lanes. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among monitoring-services specialists serving German hospital purchasing cooperatives, where telemetry dashboards unbundle from core logistics contracts. Five-to-ten-year viability favors asset-light coordinators with blockchain-integrated visibility platforms over pure fleet operators. Watch for inflection when electric refrigerated van deployment accelerates in Amsterdam, Brussels, and Paris low-emission zones.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | EMA-mandated qualification documentation creates contractual barriers to substitution for biologics manufacturers. |
| Cryogenic Infrastructure Buildout | Belgian cell therapy corridors require -80°C to -150°C validated lanes that command premium service tiers. |
| Passive Thermal Packaging Adoption | Vacuum-insulated panel systems reduce air freight dimensional weight charges on sub-48-hour Benelux routes. |
| Real-Time Telemetry Integration | Cloud-based excursion alerting unbundles from bundled 3PL contracts into standalone software revenue streams. |
| Electric Last-Mile Deployment | Urban low-emission zones in Amsterdam, Brussels, and Paris mandate refrigerated electric van procurement for clinical site delivery. |
Research Methodology
Operator-level perspectives from cold chain logistics directors, EMA GDP auditors, hospital pharmacy procurement managers, and thermal packaging engineers anchored the qualitative base. Primary interviews combined with secondary validation from EMA guidance documents, EU F-Gas Regulation filings, REACH substance restriction databases, and customs trade data for pharmaceutical movements. Bottom-up facility capacity counts triangulated against top-down market sizing from 3PL revenue disclosures.
Sensitivity analysis tested forecast outputs across refrigerant transition cost scenarios and ATMP manufacturing expansion rates over the projection horizon. Segmentation dimensions modeled include temperature band, service type, product category, and regional regulatory cluster. CAGRs derived from compound growth trajectory analysis applied to base-year capacity and throughput estimates. Industry-specific inputs incorporated F-Gas Regulation phase-down schedules and EMA GDP inspection frequency trends.
Decision-makers should treat outputs as directional under assumptions of sustained biologics outsourcing and stable EMA enforcement intensity; material deviation in refrigerant technology economics or GDP interpretation harmonization would warrant model refresh. Recalibration cycles align with material shifts in F-Gas Regulation implementation timelines and ATMP clinical trial approval velocities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Global Ambulatory Services Market
Healthcare Services
Assisted Living Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Global Infusion Pharmacy Management Market
Healthcare Services
Retail Clinics Market
Healthcare Services
Medical Social Working Services Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Global Hospital Services Market
Healthcare Services
Global Corporate Wellness Solutions Market
Healthcare Services
Hospital Command Center Operations Market
Healthcare Services
US Hospice Market