
 Media and Entertainment Storage Market | 2026-2036
Media and Entertainment Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Media and Entertainment Storage Market Outlook
Premium all-flash arrays and commodity tape archives is restructuring into parallel supply chains with diverging margin profiles and service expectations. NetApp specializes in high-performance NAS for real-time video editing workflows. Dell Technologies anchors enterprise SAN deployments across major broadcasting companies. Seagate Technology dominates high-capacity HDD manufacturing for cold archival tiers.
Media and entertainment storage encompasses tiered data infrastructure engineered for sequential throughput exceeding 500 MB/s, petabyte scalability, and multi-decade retention cycles required by uncompressed video masters and distribution intermediates. Cloud Storage leads technology adoption as studios offload secondary copies to hyperscale platforms. Tape Storage sustains the lowest cost-per-gigabyte for long-form archival despite flash encroachment. Solid State Drives command premium pricing in live streaming and real-time editing where latency tolerance measures below one millisecond.
FCC content preservation rules, EU GDPR data localization mandates, and ISO 27001 information security standards collectively shape procurement specifications and cross-border deployment architectures. The EPA Energy Star program and EU Green Deal efficiency thresholds are pressuring data center operators to prioritize power-optimized storage configurations. Stakeholders must weigh capital intensity against operational flexibility as resolution standards advance and regulatory fragmentation deepens across jurisdictions.
Market Dynamics
Resolution escalation from 4K to 8K and 16K uncompressed masters is forcing infrastructure replacement cycles faster than depreciation schedules allow, compressing vendor decision windows and fragmenting procurement across parallel tape, disk, and cloud tiers.
Growth Catalysts
- EU AI Act data residency mandates:Studios must maintain primary copies within European Economic Area boundaries, triggering hyperscale cloud region buildouts and local storage procurement across Ireland, Germany, and France.
- Live sports streaming workflows:Broadcasters demand sub-millisecond latency for instant replay and multi-angle synchronization, pulling all-flash arrays into production environments previously served by hybrid disk.
- India:Domestic OTT platform expansion and local language content explosion is driving petabyte-scale archival investments in Mumbai and Hyderabad media hubs.
Market Restraints
- Neodymium and rare earth magnet supply:HDD actuator motor manufacturing concentrates in Chinese processing facilities, exposing archival tier pricing to export control volatility.
- LTO tape format lock-in:Linear Tape-Open roadmap discontinuities between generations 9 and 10 create migration risk for decade-long retention contracts.
- EPA Energy Star 3.0 standby power thresholds:Spinning disk arrays face compliance retrofit costs that erode total cost of ownership advantages against solid-state alternatives.
Strategic Opportunities
- Saudi Arabia:Neom media city and Riyadh production zone buildouts lack established storage infrastructure, creating greenfield deployment opportunities for integrated cloud-archive solutions.
- AI-generated content provenance tracking:Emerging requirement for immutable audit trails of synthetic media training data is converging blockchain timestamping with object storage architectures.
- Direct-to-cloud editing workflows:Post-production houses in South Korea are piloting frame-accurate remote collaboration over 5G networks, bypassing local NAS infrastructure entirely.
Industry Challenges
- Legacy MAM integration:Media asset management systems built for tape-centric hierarchies require expensive API middleware to address cloud-native object stores.
- ISO 27001 certification timelines:Studio security audits now mandate encryption key segregation across geographic zones, extending vendor onboarding from weeks to quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Media and Entertainment Storage Market |
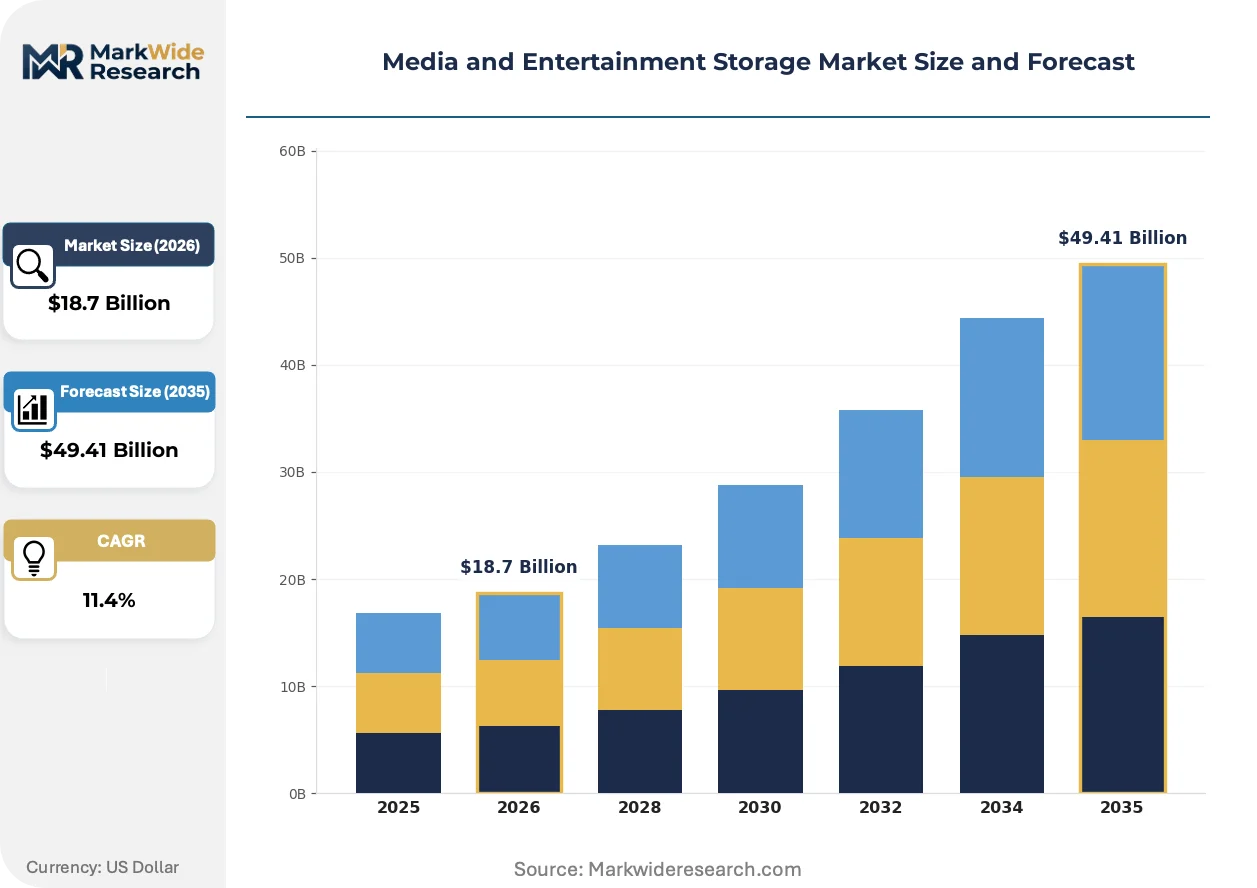
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Storage, NAS, SAN, Direct Attached Storage End User: Broadcasting Companies, Film Studios, Streaming Services, Content Creators Product Type: Hard Disk Drives, Solid State Drives, Tape Storage, Flash Storage Application: Video Editing, Archiving, Media Distribution, Live Streaming |
| Companies Covered | NetApp, International Business Machines Corporation, Amazon Web Services, Western Digital Corporation, Seagate Technology, Dell Technologies, Cisco Systems, Pure Storage, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Media and Entertainment Storage Market Strategic Shifts
Computational storage and intelligent data placement algorithms are redistributing workloads across edge, core, and cloud tiers without human intervention, collapsing traditional hierarchical storage management into autonomous pipelines.
Computational storage drives with embedded processing cores are automating transcoding and checksum validation at the device level, eliminating server CPU bottlenecks. Major post-production facilities in Los Angeles and London are deploying these units for dailies processing. This architecture is automating the ingest-to-archive pipeline, reducing operator touchpoints by compressing multiple workflow stages into silicon.
GDPR Article 17 right-to-erasure enforcement is compelling studios to implement granular deletion capabilities across petabyte-scale archives previously optimized for write-once retention. The EU AI Act adds training data lineage requirements that conflict with anonymization obligations. European broadcasters are responding by segmenting storage architectures into jurisdiction-specific cells with independent key management.
Subscription-based capacity pricing is displacing capital-intensive ownership models among mid-tier production companies. Managed service providers in Germany and Japan now bundle storage, disaster recovery, and compliance attestation into single contracts. This shift is most visible in documentary and unscripted verticals where project-based financing cannot support infrastructure depreciation.
Media and Entertainment Storage Market Segmentation
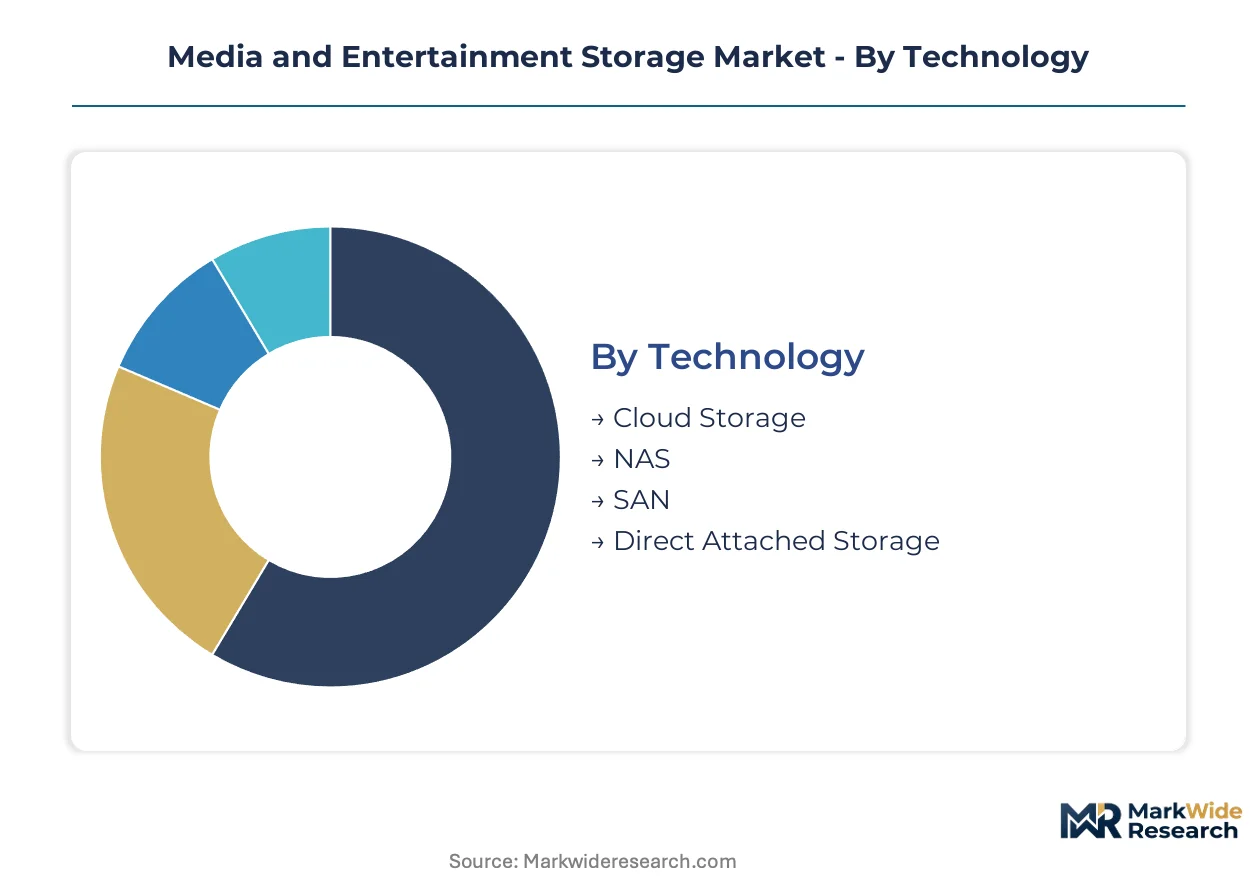
Storage procurement in media and entertainment diverges sharply by workflow latency requirements and retention economics. Capital allocation decisions separate real-time production infrastructure from archival tiers with decade-long depreciation horizons.
Technology:
Cloud Storage and SAN deployments demand the heaviest upfront capital commitment due to redundant networking fabric and software licensing stacks.
- Cloud Storage:Hyperscale object storage with erasure coding and geo-redundancy built into service contracts. Studios in Germany and France are expanding contracted capacity to satisfy EU AI Act data residency mandates requiring primary copies within European Economic Area boundaries.
- SAN:Fibre Channel or NVMe-oF block storage delivering sub-millisecond latency for concurrent 8K timeline scrubbing. Major broadcasting companies anchor enterprise deployments with dedicated fabric switches and host bus adapters.
- NAS:File-level access protocols serving collaborative editorial teams; NFS and SMB mounts dominate post-production houses.
- Direct Attached Storage:Local RAID arrays for on-set DIT carts and mobile grading suites; lowest software overhead but limited sharing capabilities.
Cloud Storage absorbs the bulk of installed capacity; SAN is expanding most quickly among broadcasters upgrading for live sports workflows.
End User:
Procurement scale separates petabyte-scale studio operators from project-based content creators with episodic capacity needs.
- Streaming Services:Global platform operators managing multi-exabyte libraries across primary, backup, and disaster recovery tiers. Resolution escalation from 4K to 8K masters is forcing infrastructure replacement cycles faster than depreciation schedules allow.
- Film Studios:Major production entities requiring immutable audit trails for uncompressed camera negatives with multi-decade retention obligations. FCC content preservation rules and ISO 27001 certification timelines extend vendor onboarding from weeks to quarters.
- Broadcasting Companies:Linear and digital channels with live production requirements; EPA Energy Star 3.0 standby power thresholds pressure spinning disk retrofit decisions.
- Content Creators:Independent producers and YouTube-native studios; subscription-based capacity pricing is displacing capital-intensive ownership models in documentary and unscripted verticals.
Streaming Services command the largest aggregate capacity footprints; Content Creators are gaining share fastest as cloud-native tools democratize infrastructure access.
Product Type:
Margin profiles diverge between commodity magnetic media and premium solid-state tiers with specialized controller architectures.
- Hard Disk Drives:Shingled magnetic recording and helium-sealed designs pushing 20+ terabyte per spindle. Neodymium and rare earth magnet supply concentration in Chinese processing facilities exposes archival tier pricing to export control volatility.
- Solid State Drives:NVMe NAND flash with custom firmware for sustained write workloads; commands premium pricing in live streaming and real-time editing where latency tolerance measures below one millisecond.
- Tape Storage:Linear Tape-Open format sustaining lowest cost-per-gigabyte for cold archival despite flash encroachment; roadmap discontinuities between generations 9 and 10 create migration risk for decade-long retention contracts.
- Flash Storage:All-flash arrays with inline deduplication and compression for high-performance tiers; computational storage drives with embedded processing cores are automating transcoding at the device level.
Hard Disk Drives retain the dominant share of exabytes under management; Solid State Drives are climbing the fastest as all-flash configurations penetrate editing workflows.
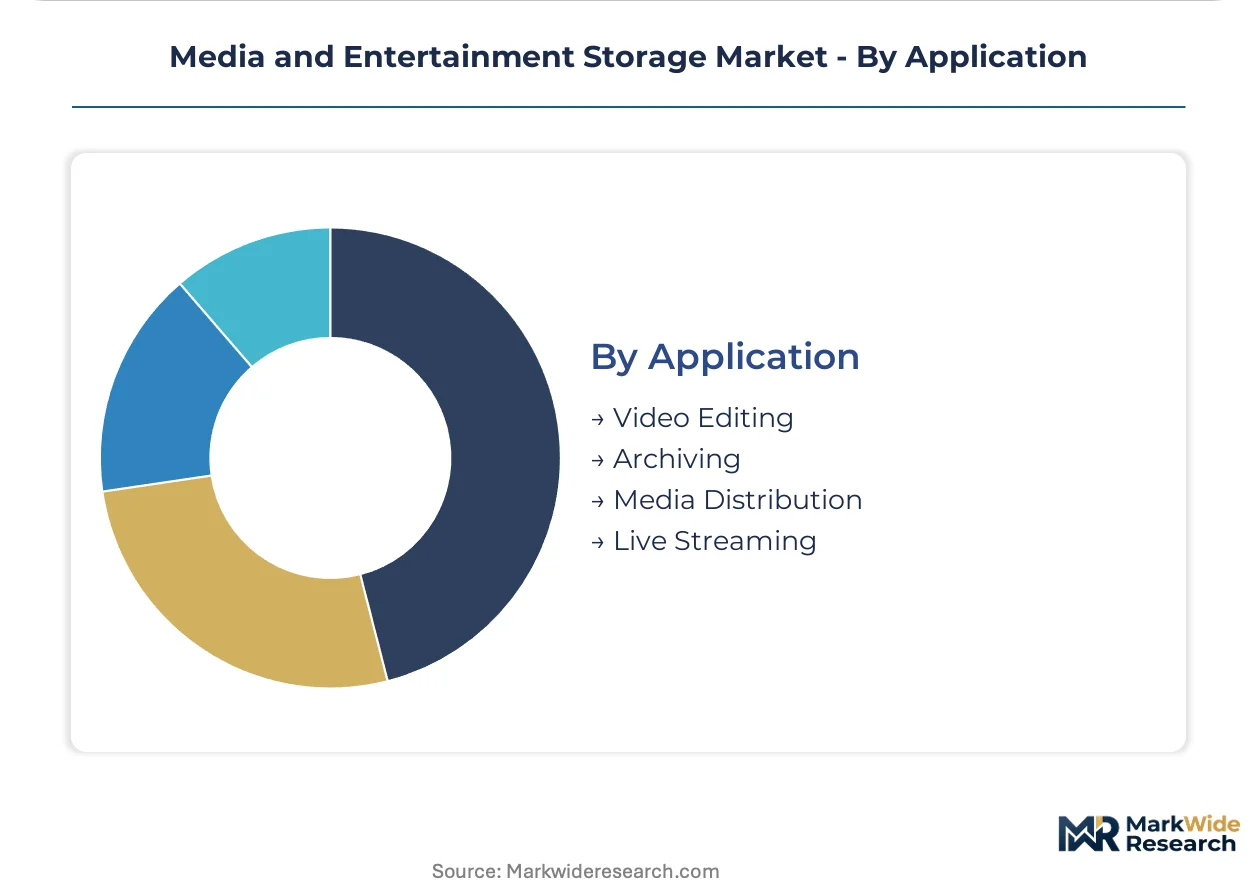
Application:
Throughput requirements stratify from sequential streaming workloads to random-access editorial operations with divergent hardware specifications.
- Video Editing:Non-linear editing systems demanding 500+ MB/s sequential throughput for uncompressed 8K playback. Post-production facilities in Los Angeles and London are deploying computational storage units for dailies processing.
- Archiving:Write-once retention with multi-decade durability specifications; GDPR Article 17 right-to-erasure enforcement is compelling granular deletion capabilities across petabyte-scale archives previously optimized for immutable storage.
- Live Streaming:Sub-second latency delivery with edge caching; broadcasters demand sub-millisecond latency for instant replay and multi-angle synchronization.
- Media Distribution:Content delivery network origination and transcoding farm storage; direct-to-cloud editing workflows in South Korea are piloting frame-accurate remote collaboration over 5G networks.
Archiving holds the largest installed base by raw capacity; Video Editing is gaining share fastest as resolution standards advance and real-time collaboration requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors petabyte-scale storage deployments for major studios and post-production facilities managing uncompressed 8K masters. The concentration of streaming platform headquarters and hyperscale cloud regions in Southern California drives infrastructure investment cycles faster than traditional depreciation schedules permit.
United States
Major broadcasting companies and streaming services demand sub-millisecond latency for live sports workflows and instant replay systems. FCC content preservation rules mandate multi-decade retention of uncompressed camera negatives, extending vendor certification timelines. Georgia's production tax credits have attracted filming activity to Atlanta, triggering local storage infrastructure buildouts for dailies processing and editorial collaboration.
Germany
EU AI Act data residency requirements and GDPR Article 17 right-to-erasure obligations are compelling studios to maintain primary copies within European Economic Area boundaries. The country's national media regulator enforces strict content localization standards for broadcasters. Frankfurt and Munich media hubs are expanding contracted hyperscale cloud capacity to satisfy cross-border data governance mandates.
India
Domestic OTT platform expansion and local language content explosion are driving petabyte-scale archival investments. TRAI regulations on data localization for streaming services are accelerating infrastructure procurement. Mumbai and Hyderabad production clusters lack legacy tape-centric hierarchies, enabling direct adoption of cloud-native object storage architectures for new studio facilities.
Saudi Arabia
Neom media city and Riyadh production zone buildouts lack established storage infrastructure, creating greenfield deployment opportunities. SFDA and national media authority guidelines on content provenance tracking are converging with emerging blockchain timestamping requirements. The Eastern Province is attracting post-production joint ventures seeking to serve Middle Eastern and North African distribution markets.
South Korea
Post-production houses are piloting frame-accurate remote collaboration over 5G networks, bypassing local NAS infrastructure entirely. MFDS and national broadcasting standards on synthetic media disclosure are driving demand for immutable audit trails of AI-generated content training data. Seoul Capital Area facilities are deploying computational storage drives with embedded processing cores for automated transcoding at the device level.
Media and Entertainment Storage Market Competitive Environment
Capital-heavy producers compete with asset-light designers across diverging margin profiles in media and entertainment storage. The vendor base separates into parallel supply chains serving real-time production workflows versus cold archival tiers with decade-long retention economics. Three archetypes dominate: hyperscale cloud operators with erasure-coded object storage, enterprise storage specialists with Fibre Channel fabric expertise, and component manufacturers pushing areal density limits in magnetic recording. Competitive moves center on strategic partnerships between cloud platforms and post-production software vendors, plus geographic expansion into emerging media production zones lacking legacy infrastructure.
Within the enterprise storage tier, NetApp and Dell Technologies exemplify high-performance NAS and SAN specialists respectively. Seagate Technology occupies a position as a capacity-driven component supplier for cold archival tiers. These three anchors illustrate the market's structural segmentation between premium workflow infrastructure and commodity magnetic media.
| Leading Market Players |
|---|
| NetApp |
| International Business Machines Corporation |
| Amazon Web Services |
| Western Digital Corporation |
| Seagate Technology |
| Dell Technologies |
| Cisco Systems |
| Pure Storage |
| Microsoft Corporation |
| Others |
Value Chain & Pricing Dynamics
EU AI Act data residency mandates are forcing studios to procure primary storage within European Economic Area boundaries, compelling hyperscale cloud operators to build out Frankfurt and Paris regions and shifting pricing power toward vendors with certified EU-sovereign infrastructure.
Pricing Analysis
Throughput-based pricing anchors storage procurement decisions, with sub-millisecond latency arrays commanding premiums against archival tiers. Three-tier pricing structure across premium, standard, and economy levels separates all-flash configurations for live sports workflows from helium-sealed HDD pools and LTO tape libraries. Cost compression in cold archival tiers is intensifying because Chinese rare earth export controls are inflating HDD actuator motor input costs. Streaming services exhibit lowest price sensitivity given multi-exabyte scale and regulatory compliance obligations, while independent content creators face acute budget constraints driving subscription-based capacity adoption.
Supply Chain Analysis
ISO 27001 certification timelines and FCC content preservation audits are gating vendor qualification, extending onboarding from weeks to quarters and concentrating procurement among pre-certified incumbents. Magnetic recording media manufacturing concentrates in China, Japan, and the United States, with neodymium processing facilities in Chinese provinces feeding HDD spindle motor assembly. Supply chains draw from rare earth magnet dependencies, NAND flash wafers, and specialized Fibre Channel switching fabric. Single-source vulnerability in Chinese rare earth export licensing exposes archival tier pricing to geopolitical disruption. Distribution runs through direct enterprise sales for petabyte-scale studio deployments and managed service provider channels for mid-tier production houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase as computational storage with embedded processing cores automates transcoding pipelines previously requiring discrete server infrastructure, collapsing ingest-to-archive workflows into silicon.
For Market Incumbents: Anticipate margin compression in cold archival tiers as hyperscale cloud operators erode tape library economics with erasure-coded object storage. Defensive consolidation through backward integration into rare earth magnet recycling or captive NAND flash supply agreements will secure input cost stability. Prioritize certification investment for EU AI Act data sovereignty compliance to maintain access to Frankfurt and Munich procurement pipelines. For New Entrants and Emerging Players: Cloud-native MAM middleware offers the most penetrable white-space target, bridging legacy tape-centric hierarchies to object storage APIs for post-production facilities locked into decade-old asset management systems. Saudi Arabia's Neom media city and Riyadh production zones present greenfield deployment opportunities without incumbent infrastructure entrenchment. Lead with subscription-based capacity pricing bundled with compliance attestation to displace capital-intensive ownership models among documentary and unscripted verticals. For Investors and Strategic Acquirers: Re-rating potential sits with computational storage specialists given AI-generated content provenance tracking requirements converging blockchain timestamping with object storage architectures. Long-term viability over a five-to-ten year window favors vendors with autonomous data placement algorithms redistributing workloads across edge, core, and cloud tiers. Monitor hyperscaler capex disclosures for cloud region buildout velocity as the inflection indicator for infrastructure replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Post-production software vendors embedding cloud storage APIs collapses MAM middleware layers. |
| Geographic Expansion | Greenfield deployment in Saudi Arabia's Neom media city bypasses legacy tape infrastructure entrenchment. |
| Strategic Partnership | Hyperscale cloud operators aligning with 5G carriers enable frame-accurate direct-to-cloud editing workflows. |
| Acquisition of Specialist Firm | Computational storage vendors with embedded transcoding cores automate dailies processing pipelines. |
| Product Launch | All-flash arrays with sub-millisecond latency capture live sports instant replay procurement cycles. |
Study Parameters
Multi-period observation of hyperscaler capex disclosures, studio infrastructure procurement announcements, and LTO tape format roadmap milestones anchored the trend analysis, supplemented by interviews with CTOs at post-production facilities, storage procurement directors at streaming platforms, broadcast engineering leads, and data center operators. Secondary validation drew from hyperscaler infrastructure investment filings, FCC content preservation rulemaking dockets, EU AI Act implementation guidance, and ISO 27001 certification registry data. Bottom-up capacity deployment tracking across Los Angeles, Frankfurt, Mumbai, and Seoul production clusters was triangulated against top-down vendor revenue segmentation.
Input-output matrices modeled storage demand as a function of resolution standard adoption curves, regulatory compliance cost burdens, and cloud migration velocity across the projection horizon. Segmentation dimensions included technology tier, end-user scale, product type margin profile, and application throughput requirement. CAGRs were derived from fitted adoption curves rather than linear extrapolation, incorporating 8K and 16K uncompressed master growth assumptions and GDPR Article 17 granular deletion capability penetration rates as industry-specific forecast inputs.
Inputs from hyperscaler infrastructure disclosures and studio procurement announcements were available through the study window; gaps in private cloud capacity contract terms introduce uncertainty bands around subscription-based pricing trajectory assumptions. Forecasts reflect documented assumptions regarding EU AI Act enforcement timing and rare earth export licensing stability. A model refresh is warranted upon material change in hyperscaler cloud region buildout velocity or LTO format roadmap discontinuity resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Denmark Data Center Storage Market
Storage Solutions
Network File System Market
Storage Solutions
Global All-Flash Array Market
Storage Solutions
Sweden Data Center Storage Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Disk-Based Backup System Market
Storage Solutions
Austria Data Center Storage Market
Storage Solutions
Cloud Storage Gateways Market