
 Enterprise File Sync and Share Platform Market | 2026-2036
Enterprise File Sync and Share Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise File Sync and Share Platform Market Foresight
North American cloud infrastructure build-out is narrowing the deployment gap between hyperscale and regional providers. Microsoft Corporation leverages its Azure stack to anchor hybrid cloud deployments across regulated industries. Dropbox, Inc competes through consumer-grade usability translated into enterprise governance controls. Box, Inc specializes in vertical-specific compliance certifications that dominate financial services procurement.
Enterprise File Sync and Share Platforms are software systems that synchronize files across endpoints, enforce version control, and provide encrypted access through web, desktop, and mobile interfaces with configurable retention policies and granular permission architectures. Their primary commercial purpose is to replace legacy file servers and email attachments with auditable, scalable content collaboration. The public cloud deployment segment leads in volume but faces margin compression from commodity storage pricing, while hybrid cloud configurations capture expanding margin pools as organizations segment data between regulated on-premise repositories and elastic cloud tiers. Managed services within the service type dimension sustain premium pricing through embedded security operations and 24/7 incident response.
The US HIPAA Security Rule and SEC cybersecurity disclosure requirements shape product roadmaps for domestic vendors by mandating access logging, encryption at rest and in transit, and breach notification automation. The EU GDPR and NIS2 Directive enforce data localization and cross-border transfer impact assessments that constrain pure public cloud architectures. Stakeholders must monitor the divergence between US federal zero-trust mandates and European data sovereignty frameworks when architecting multi-tenant platform strategies.
Market Dynamics
Zero-trust security mandates from US federal agencies and EU data sovereignty frameworks are bifurcating vendor architectures, forcing simultaneous investment in sovereign cloud infrastructure and cross-border encryption protocols.
Growth Catalysts
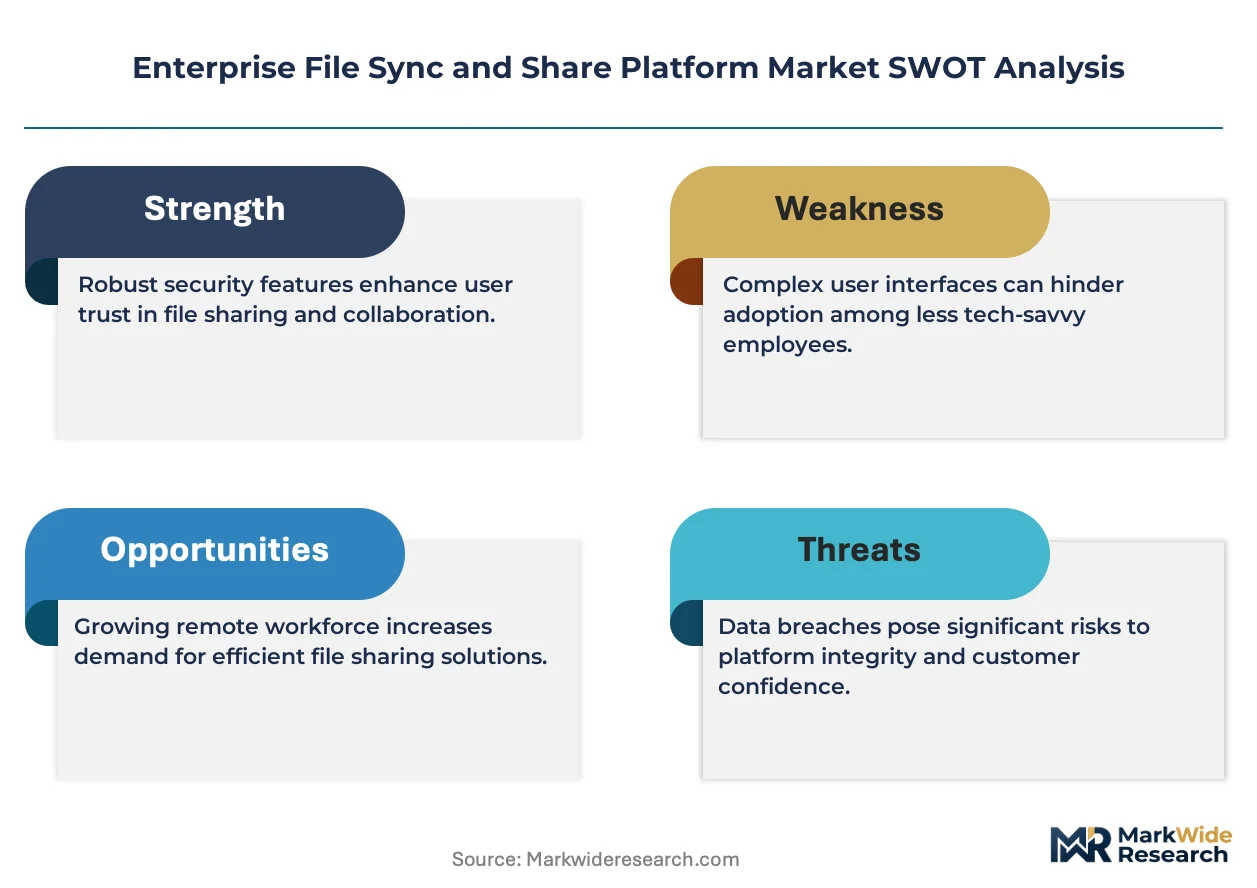
- Healthcare digitization:HIPAA Security Rule enforcement drives hospital systems toward encrypted clinical document exchange with automated breach notification workflows.
- GDPR Article 44:Cross-border transfer impact assessments compel enterprises to deploy localized data residency controls within EU member states.
- Edge computing convergence:Manufacturing facilities sync terabyte-scale design files between factory floor systems and cloud repositories with sub-50ms latency requirements.
Market Restraints
- Commodity storage pricing:Hyperscale object storage from Amazon Web Services and Microsoft Azure compresses margins for pure public cloud file sync vendors.
- Technical debt:Legacy on-premise SharePoint and Windows file server installations block cloud-native migration paths for regulated financial institutions.
- Substitution threat:Real-time collaboration platforms including Slack and Microsoft Teams embed lightweight file sharing that displaces standalone sync tools for informal workflows.
Strategic Opportunities
- Underpenetrated verticals:Construction and engineering firms in Germany deploy hybrid cloud configurations to synchronize building information modeling files across distributed project sites.
- EU AI Act compliance:Documentation trail requirements for high-risk AI systems create demand for immutable audit logs and version-controlled training data repositories.
- API-first architectures:Embedded file sync capabilities within vertical SaaS applications open distribution through Salesforce AppExchange and similar marketplaces.
Industry Challenges
- Cybersecurity talent scarcity:Shortage of cloud security architects with zero-trust implementation experience delays enterprise deployment timelines.
- Multi-cloud integration complexity:Enterprises operating across AWS, Azure, and Google Cloud platforms require unified policy enforcement across heterogeneous environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise File Sync and Share Platform Market |
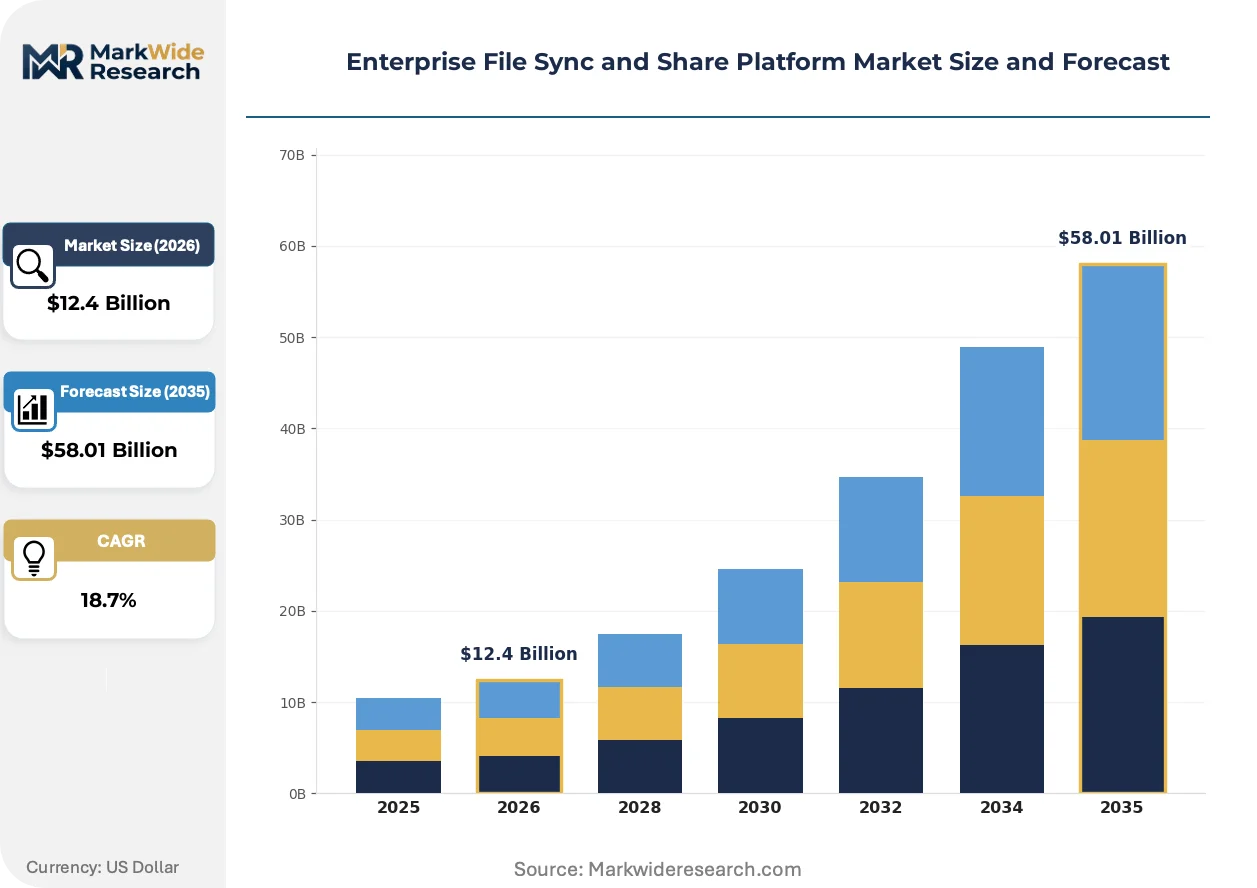
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Service Type: Basic Services, Advanced Services, Managed Services, Custom Solutions User Type: Individual Users, Small Business, Enterprises, Educational Institutions Integration Level: APIs, SDKs, Third-Party Tools, Native Integrations |
| Companies Covered | Microsoft Corporation, Box, Inc., Dropbox, Inc, Google, Egnyte, Inc., Citrix Systems, Inc., IBM, VMware, Syncplicity LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise File Sync and Share Platform Market Shifts & Advancements
Artificial intelligence is embedding into file management workflows, transforming static repositories into intelligent systems that automate classification, enforce policy, and surface content through natural language interfaces.
Confidential computing using hardware-based trusted execution environments is digitizing sensitive data processing for regulated industries. Healthcare providers in the United States deploy Intel SGX and AMD SEV enclaves to analyze patient records without exposing plaintext to cloud operators. This architecture compresses the compliance burden for HIPAA-covered entities while preserving elastic compute economics.
The EU AI Act's risk-based classification system mandates technical documentation and human oversight protocols for high-risk AI applications. File sync platforms serving algorithmic trading and credit scoring workflows must implement immutable audit trails and model versioning. German automotive manufacturers are restructuring data governance to satisfy these documentation requirements ahead of enforcement deadlines.
Subscription fatigue among mid-market enterprises is compressing procurement cycles for standalone file sync tools. Buyers increasingly demand bundled security operations and incident response rather than discrete storage capacity. This pattern is most visible in France and the Netherlands, where CFOs scrutinize overlapping SaaS expenditures across collaboration categories.
Enterprise File Sync and Share Platform Market Segmentation
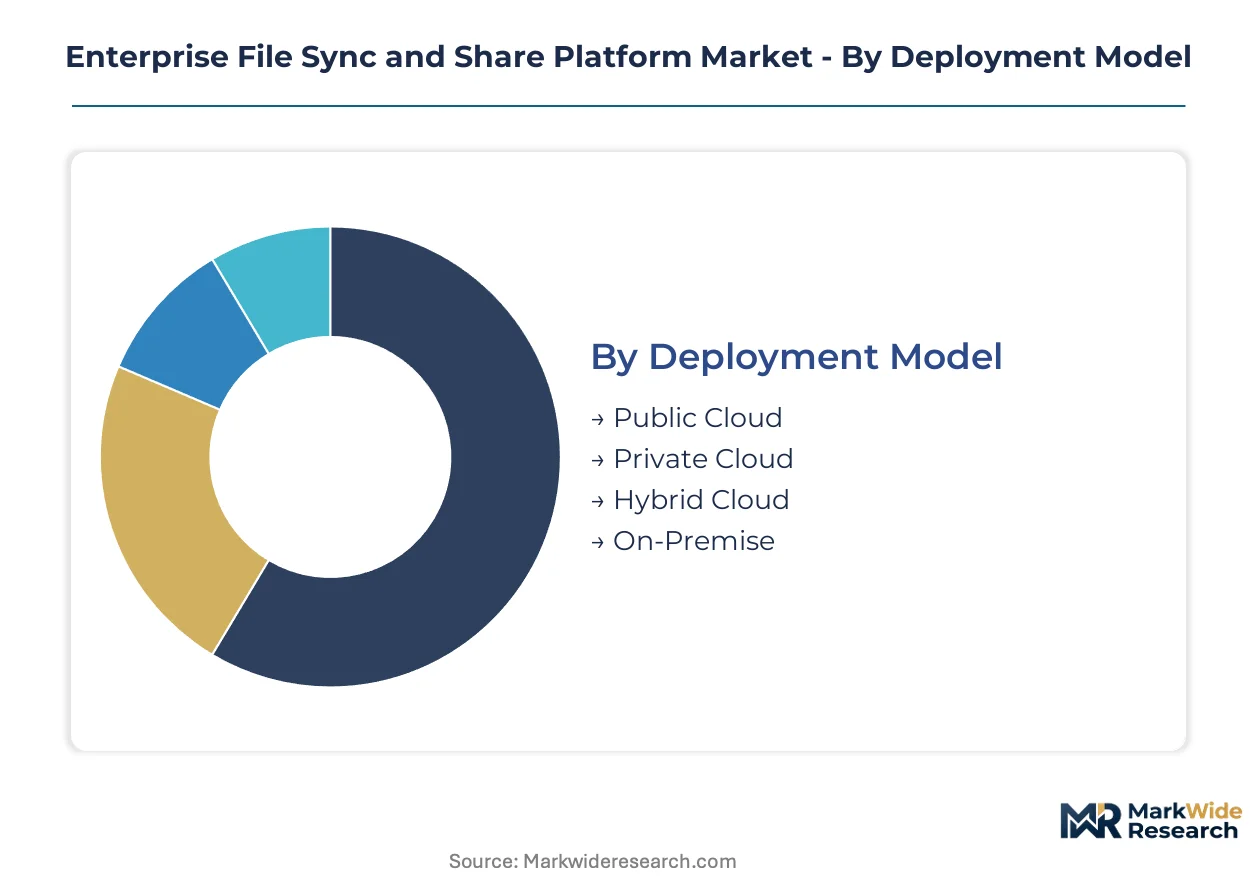
Enterprise file sync and share platforms segment across deployment architecture, service sophistication, user scale, and integration depth. Each dimension shapes procurement criteria, margin structures, and vendor competitive positioning in distinct ways.
Deployment Model:
Deployment architecture determines where encryption keys reside, which regulators have jurisdiction, and how latency-sensitive workloads perform.
- Public Cloud:Multi-tenant infrastructure delivers elastic capacity without capital expenditure. Healthcare systems in the United States deploy this tier for non-PHI collaboration, though GDPR Article 44 transfer assessments constrain its viability for EU patient data.
- Hybrid Cloud:Policy-driven data placement splits regulated records across on-premise vaults and cloud tiers. German automotive manufacturers favor this architecture to satisfy EU AI Act documentation requirements while preserving cloud scalability for engineering simulations.
- Private Cloud:Single-tenant dedicated infrastructure with customer-managed encryption. Financial services firms in Switzerland deploy this tier to satisfy FINMA outsourcing guidelines.
- On-Premise:Air-gapped installations with no external connectivity. Defense contractors and classified government facilities mandate this deployment for export-controlled technical data.
Public cloud holds installed capacity. Hybrid cloud is rotating up the share rankings.
Service Type:
Service tiers align pricing with operational responsibility, from self-managed subscriptions to fully outsourced security operations.
- Basic Services:Core file synchronization with standard encryption and retention policies. Individual users and small businesses in France select this tier amid CFO scrutiny of overlapping SaaS expenditures.
- Advanced Services:Enhanced capabilities including e-discovery, legal hold, and granular access analytics. Law firms in the United Kingdom deploy these features for Solicitors Regulation Authority compliance.
- Managed Services:Embedded security operations with 24/7 incident response and threat hunting. Mid-market enterprises in the Netherlands procure this tier to address cybersecurity talent scarcity without building internal SOCs.
- Custom Solutions:Bespoke deployments with specialized compliance certifications and dedicated infrastructure. Pharmaceutical manufacturers negotiate these arrangements for FDA 21 CFR Part 11 validation.
Managed services command premium pricing expansion. Custom solutions are climbing the fastest among regulated verticals.
User Type:
Organizational scale dictates feature requirements, with procurement authority shifting from IT administrators to procurement departments as size increases.
- Individual Users:Consumer-grade subscriptions with limited administrative controls. Freelance designers and independent consultants in Italy utilize this segment for client deliverable exchange.
- Small Business:Team-oriented plans with centralized billing and basic governance. Construction subcontractors in Spain adopt these offerings for project document coordination.
- Enterprises:Multi-department deployments with SSO integration, DLP policies, and audit logging. Fortune 500 manufacturers across Poland and Czechia standardize on this tier for supply chain collaboration.
- Educational Institutions:Federated identity support for transient student populations and research data management. Universities in Belgium deploy these configurations for Horizon Europe consortium document sharing.
Enterprises anchor vendor revenue concentration. Educational institutions are gaining share fastest as research digitization accelerates.
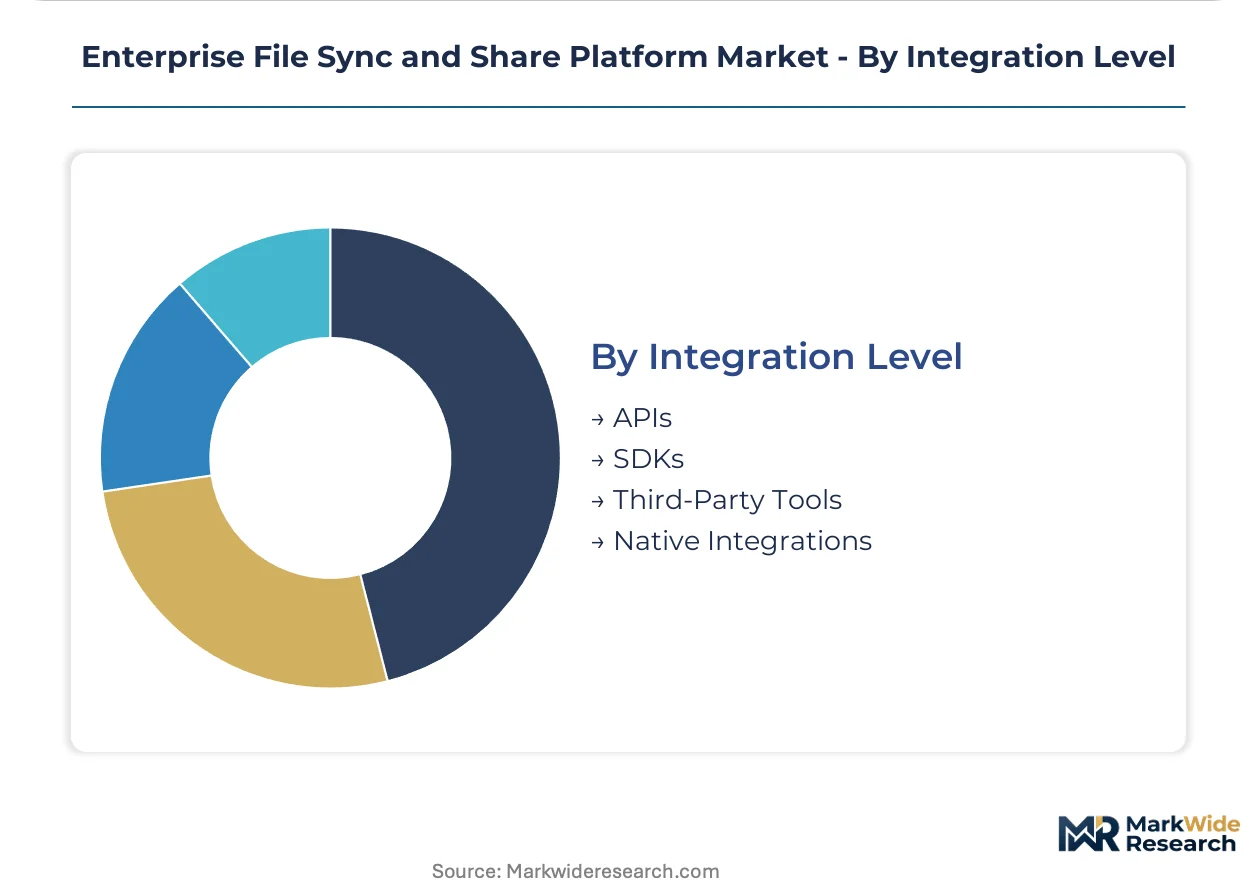
Integration Level:
Connectivity architecture determines whether file sync operates as a standalone application or embedded capability within broader workflows.
- APIs:RESTful and GraphQL endpoints enabling programmatic access and workflow automation. DevOps teams in Sweden integrate these interfaces into CI/CD pipelines for infrastructure-as-code artifact management.
- SDKs:Native development libraries for iOS, Android, and desktop application embedding. Healthcare software vendors in Denmark utilize these kits to build clinical document capture into EHR interfaces.
- Third-Party Tools:Pre-built connectors for productivity suites, CRM systems, and communication platforms. Sales organizations in Norway deploy these integrations to synchronize contract versions between Salesforce and email threads.
- Native Integrations:Deep operating system and application embedding without separate authentication. Creative agencies in Austria prefer this seamless experience for Adobe Creative Cloud asset synchronization.
APIs dominate developer-centric procurement. Native integrations are rotating up the share rankings as user experience expectations intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HIPAA enforcement in the United States shapes product roadmaps for vendors serving healthcare systems, while GDPR Article 44 transfer assessments constrain pure public cloud architectures across European markets.
United States
Hospital systems deploy encrypted clinical document exchange with automated breach notification workflows. The HIPAA Security Rule mandates access logging and encryption standards that vendors must embed. Healthcare clusters in Boston and Nashville drive procurement of hybrid configurations for PHI segmentation.
Germany
Automotive manufacturers prioritize localized data residency for EU AI Act documentation requirements. The BSI (Federal Office for Information Security) issues technical guidelines for cloud security certification. Engineering teams in Stuttgart and Munich synchronize building information modeling files across distributed project sites.
United Kingdom
Law firms procure advanced e-discovery and legal hold capabilities for Solicitors Regulation Authority compliance. The UK GDPR maintains cross-border transfer rules post-Brexit. Financial and legal services clusters in London and Edinburgh drive demand for granular access analytics.
France
CFO scrutiny of overlapping SaaS expenditures compresses procurement cycles for standalone file sync tools. The CNIL enforces data localization requirements for sensitive processing. Mid-market enterprises in Paris and Lyon select bundled security operations over discrete storage capacity.
Netherlands
Cybersecurity talent scarcity pushes mid-market enterprises toward managed services with embedded SOC capabilities. The Dutch Data Protection Authority coordinates with EU-wide NIS2 implementation. Technology firms in Amsterdam and Eindhoven standardize on 24/7 incident response tiers.
Enterprise File Sync and Share Platform Market Competitive Landscape
Hyperscale cloud providers and vertical-specialist vendors split the market between elastic infrastructure dominance and compliance-certified depth. Microsoft Corporation leverages Azure stack integration to anchor hybrid deployments across regulated industries, while Box, Inc and Dropbox, Inc compete on governance controls and consumer-grade usability translation respectively. The vendor base organizes around three archetypes: infrastructure-integrated platforms, standalone collaboration specialists, and compliance-focused vertical players. Dominant competitive moves include strategic partnerships with productivity suites and geographic expansion through sovereign cloud infrastructure.
Among infrastructure-integrated platforms, Microsoft Corporation exemplifies the hyperscale archetype through Azure-anchored hybrid configurations. Box, Inc occupies a position within the compliance-specialist tier, with certifications targeting financial services procurement requirements. Dropbox, Inc represents the usability-translation archetype, converting consumer-grade interfaces into enterprise governance frameworks.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Box, Inc. |
| Dropbox, Inc |
| Egnyte, Inc. |
| Citrix Systems, Inc. |
| IBM |
| VMware |
| Syncplicity LLC |
| Others |
Supply & Pricing Matrix
Transatlantic fiber routes between Frankfurt and Ashburn carry encryption key synchronization traffic that concentrates pricing power among hyperscale cloud operators while compressing margins for standalone sync vendors dependent on commodity storage arbitrage.
Pricing Analysis
Geographic price spreads between German sovereign cloud deployments and US public cloud tiers reach three-to-one multiples for equivalent managed service tiers. Subscription pricing stratifies across premium managed security, standard compliance-certified, and economy self-service levels. Price differentiation hinges on GDPR certification grade and embedded SOC operational coverage. Cost compression in the public cloud tier is intensifying because AWS S3 and Azure Blob storage pricing erodes per-gigabyte margins. Mid-market enterprises in France exhibit highest price sensitivity, while Swiss private banking institutions show lowest elasticity due to FINMA outsourcing mandate rigidity.
Supply Chain Analysis
Tariff exposure between US and Chinese semiconductor equipment constrains hardware security module availability for confidential computing deployments. Supply concentration centers on Taiwan for advanced encryption processors, Ireland for EU data center infrastructure, and the United States for zero-trust authentication hardware. Raw material dependencies span gallium nitride for high-performance networking, rare earth elements for server manufacturing, and specialized optical fiber for low-latency synchronization. Single-source vulnerability in Intel SGX and AMD SEV enclave supply creates bottleneck risk for healthcare confidential computing rollouts. Distribution runs through direct enterprise sales with hyperscaler marketplace attach, supplemented by systems integrator channels for regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in enterprise file sync are shifting from standalone storage subscriptions toward embedded workflow capabilities, driven by Microsoft Teams and Salesforce ecosystem interoperability demands that collapse procurement into broader collaboration budgets.
For Market Incumbents: Insulate hybrid cloud margin pools by accelerating sovereign infrastructure deployment in Germany and France ahead of EU AI Act enforcement. Fortify certification moats through BSI and CNIL security audits that emerging entrants cannot replicate within compliance windows. Counter substitution threat from Slack and Teams embedded file sharing by embedding sync capabilities into vertical SaaS workflows through API-first architectures.
For New Entrants and Emerging Players: German construction and engineering verticals remain underpenetrated by specialized BIM-synchronization tools that incumbent generalists have not tailored. Target mid-market managed service tiers in the Netherlands where cybersecurity talent scarcity creates procurement urgency without incumbent lock-in. Pursue distribution through Autodesk and Bentley Systems partner marketplaces rather than direct enterprise sales cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compliance-specialist vendors with EU sovereign cloud footprints over pure public cloud scale players. Long-term viability rests on regulatory divergence between US zero-trust mandates and European data residency frameworks that sustain pricing power for dual-jurisdiction architectures. Monitor Intel and AMD confidential computing hardware roadmaps as inflection signal for healthcare and financial services adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Expansion | Localized German data centers satisfy BSI certification and GDPR Article 44 transfer assessment requirements. |
| Confidential Computing Integration | Intel SGX and AMD SEV enclaves enable HIPAA-covered entities to process PHI without cloud operator exposure. |
| Vertical API Ecosystem Embedding | Salesforce AppExchange distribution captures procurement budgets within existing CRM workflow commitments. |
| Managed Security Service Bundling | 24/7 SOC capabilities address Dutch mid-market talent scarcity without internal buildout costs. |
| EU AI Act Documentation Compliance | Immutable audit trails and model versioning satisfy German automotive manufacturer governance restructuring. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with CISOs, cloud procurement officers, compliance auditors, and healthcare IT directors; and secondary validation through SEC 10-K filings, hyperscaler capex disclosures, BSI technical guideline publications, and CNIL enforcement precedent databases. Bottom-up sizing triangulated deployment model adoption rates against top-down market value reconstruction across public, hybrid, private, and on-premise architecture tiers.
Forecast inputs encompassed deployment model migration velocity, service tier mix shifts, and vertical penetration rates across healthcare, financial services, manufacturing, and professional services segments. The analytical framework modeled organization scale, integration complexity, and regional regulatory cluster effects throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion boundaries, with confidential computing hardware availability and EU AI Act enforcement timeline uncertainty incorporated as scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive sovereign cloud investment by AWS and Azure or accelerated confidential computing commoditization would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Sweden Data Center Storage Market
Storage Solutions
Global Virtual Data Storage Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Multi Cloud Storage Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
Hybrid Cloud Storage Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
Disk-Based Backup System Market
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Storage Software Market