
 Network File System Market | 2026-2036
Network File System Market Size, Share, and Industry Trends Forecast 2026-2036
Network File System Market Foresight
Enterprise storage distribution is rewriting competitive dynamics as direct-to-cloud channels displace traditional hardware resale. NetApp leverages its ONTAP platform to sustain hybrid cloud relevance across Fortune 500 accounts. Dell Technologies anchors its position through integrated PowerScale systems that dominate high-performance computing deployments. IBM Corporation competes via parallel file system expertise inherited from Red Hat's storage portfolio.
A Network File System constitutes a distributed file system protocol enabling client computers to access files over a network with local-like semantics, operating primarily over TCP/IP with stateless server design for fault tolerance. NFSv4.2 introduces pNFS parallel access and server-side copy operations, serving the primary purpose of consolidating unstructured data across heterogeneous compute clusters in enterprise and cloud environments. Deployment models reveal cloud-based implementations capturing the fastest expansion as object storage integration reshapes margin pools, while on-premises installations retain dominance in regulated sectors requiring data sovereignty controls. File system type segmentation shows NFS protocol variants maintaining protocol leadership, though SMB/CIFS persists in Microsoft-centric enterprise stacks.
NIST cybersecurity frameworks and SEC disclosure rules govern enterprise storage procurement in the United States, mandating encryption-at-rest and access logging that elevate certified product demand. ISO 27001 and SOC 2 Type II compliance requirements further constrain vendor qualification for financial services and healthcare buyers. Stakeholders must monitor zero-trust architecture mandates and quantum-resistant encryption standards as these will determine protocol evolution and replacement cycles.
Market Dynamics
Containerized workload density is forcing protocol-layer reinvention across enterprise storage architectures, as stateless NFS designs strain under persistent volume demands from Kubernetes-orchestrated microservices.
Growth Catalysts
- Zero-trust architecture mandates:NIST cybersecurity frameworks require encryption-at-rest and access logging that elevate certified NFS product demand across federal contractors.
- Hyperscale data center construction:Cloud service providers in the United States standardize on NFSv4.2 pNFS parallel access for unstructured data consolidation.
- Container storage interface adoption:Kubernetes-native persistent volume provisioning pulls enterprise storage toward cloud-native NFS implementations.
Market Restraints
- Silicon supply concentration:NAND flash controller fabrication concentrates in Taiwan, exposing storage array pricing to geopolitical disruption risk.
- Latency penalties of TCP/IP:Stateless NFS server design introduces round-trip delays that limit high-frequency trading and real-time analytics adoption.
- Data sovereignty fragmentation:Divergent national cloud residency laws force redundant infrastructure deployment, compressing margin pools for cross-border service providers.
Strategic Opportunities
- Quantum-resistant encryption standards:NIST post-quantum cryptography mandates will drive protocol replacement cycles and certified product upgrades.
- Edge computing clusters:Distributed manufacturing sites and autonomous vehicle testbeds require localized NFS caching layers with intermittent cloud sync.
- Object storage convergence:NFS-over-S3 gateway architectures enable hybrid tiering that bridges legacy file semantics with cloud-native cost structures.
Industry Challenges
- Parallel file system expertise scarcity:pNFS deployment and tuning require specialized storage engineering skills that outpace university pipeline output.
- Legacy POSIX compliance verification:Financial services buyers demand ISO 27001 and SOC 2 Type II certification timelines that extend sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network File System Market |
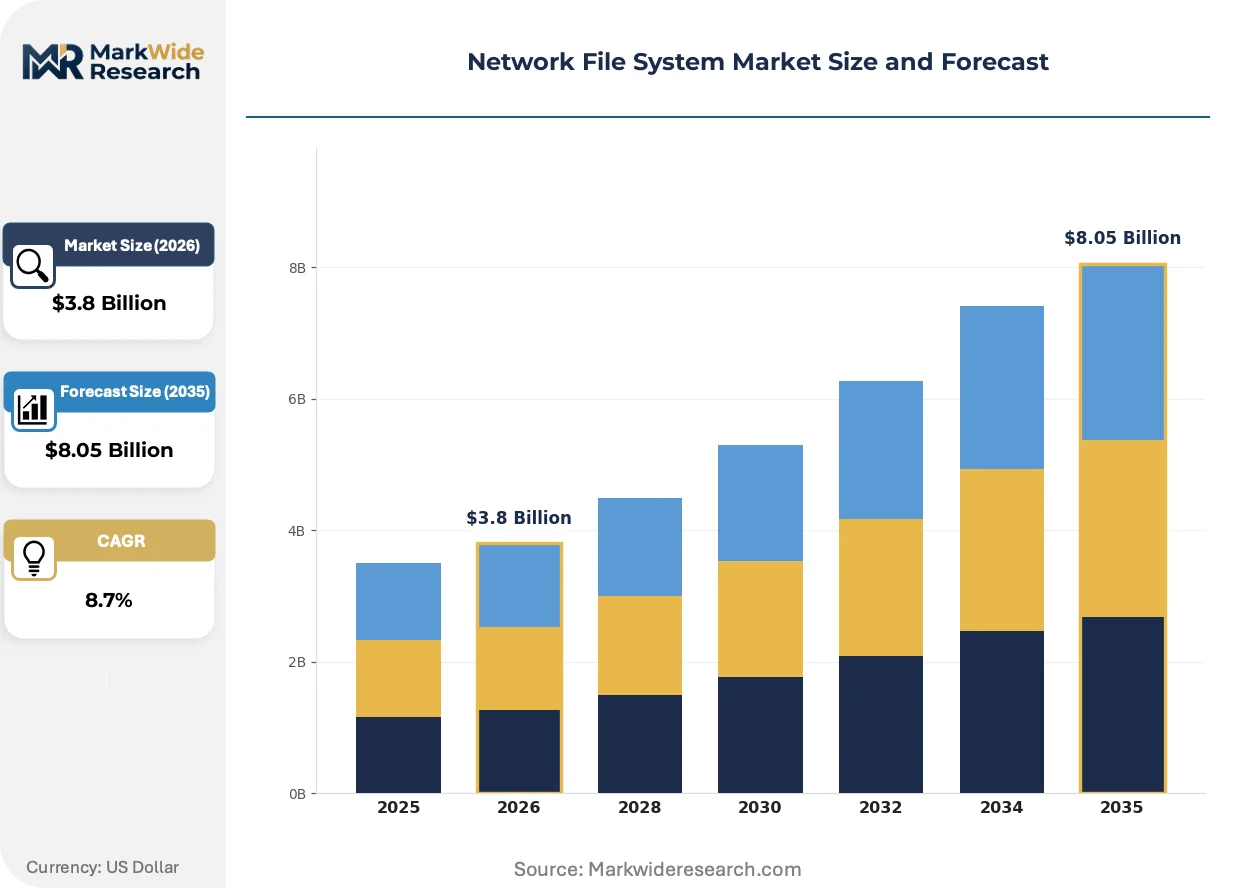
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | File System Type: NFS, SMB/CIFS, AFS, DFS Deployment Model: On-Premises, Cloud-Based, Hybrid, Private End User: Small Enterprises, Large Enterprises, Government, Education Technology: Object Storage, Block Storage, Distributed Storage, File Storage |
| Companies Covered | NetApp, IBM Corporation, Dell Technologies, Hitachi Vantara, Western Digital Corporation, QNAP Systems, Synology, Cisco Systems, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network File System Market Shifts & Advancements
Protocol abstraction layers are decoupling file system semantics from underlying hardware, enabling software-defined storage controllers to virtualize NFS endpoints across heterogeneous infrastructure pools without physical array lock-in.
NFSv4.2 server-side copy operations eliminate client-side data movement for intra-storage migrations, reducing network congestion in hyperscale environments. Cloud service providers deploy these primitives to optimize container image layering and snapshot deduplication. The technology is migrating from high-performance computing niches into general-purpose enterprise virtualization stacks.
SEC disclosure rules and state-level privacy statutes in California and New York impose audit logging requirements that reshape procurement specifications. Financial services buyers now mandate immutable access logs with cryptographic verification. Healthcare verticals face parallel HIPAA technical safeguard enforcement that elevates certified encryption module demand.
Enterprise buyers increasingly unbundle hardware procurement from software licensing, favoring subscription-based protocol controllers deployable on commodity servers. Channel partners respond with professional services wrappers around open-source NFS implementations. This pattern concentrates in North American mid-market accounts with limited dedicated storage engineering staff.
Network File System Market Segmentation
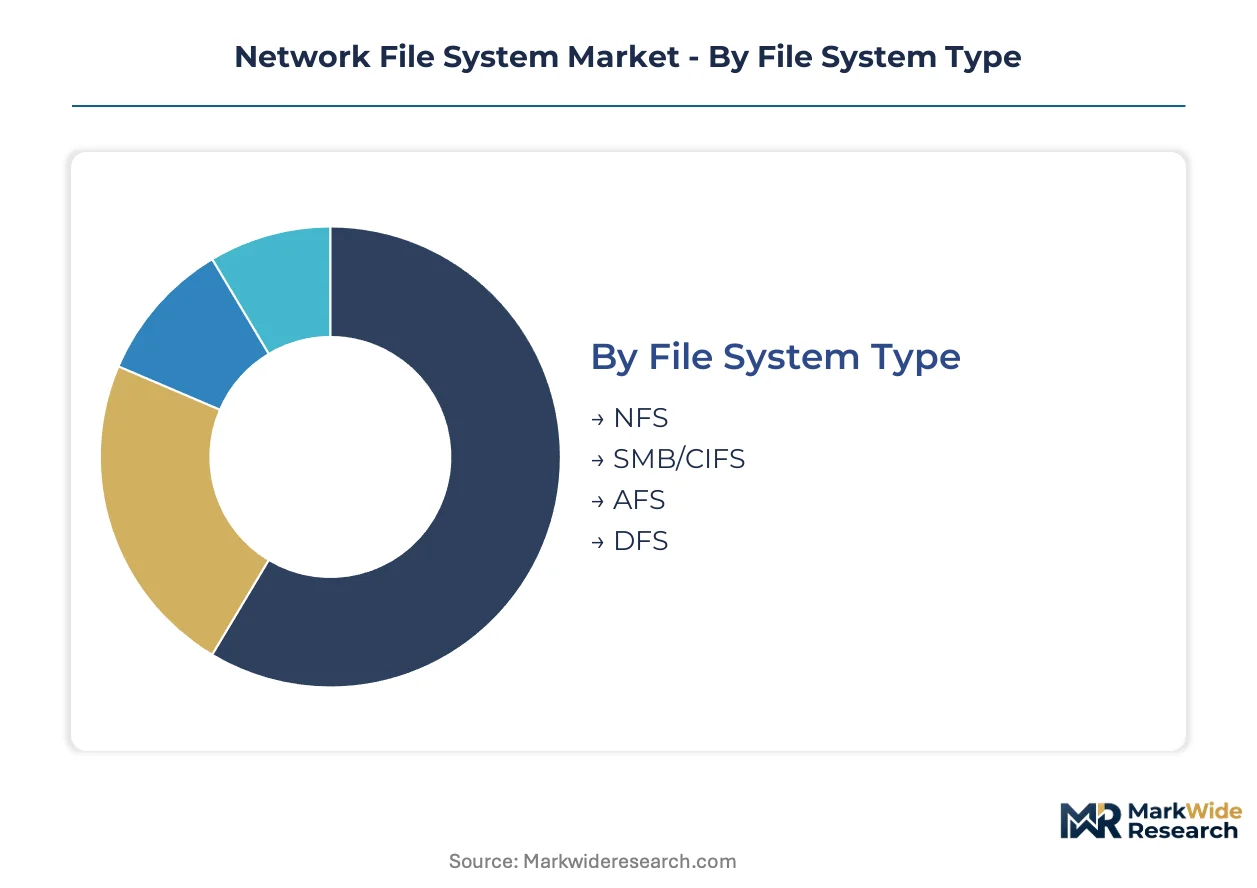
Network File System procurement patterns fragment sharply across infrastructure maturity levels, with each segment demanding distinct post-deployment support intensity. Vendor profitability hinges on matching service architectures to these heterogeneous operational requirements rather than forcing uniform engagement models.
File System Type:
After-sales-service intensity escalates dramatically for protocol variants requiring specialized tuning expertise, creating divergent margin profiles across vendor portfolios.
- NFS:Stateless server architecture operates over TCP/IP with fault-tolerant design for heterogeneous compute clusters. Demand concentrates in United States hyperscale data centers where NIST cybersecurity frameworks mandate encryption-at-rest and access logging for federal contractors.
- SMB/CIFS:Microsoft's Server Message Block protocol dominates Windows-centric enterprise stacks with integrated Active Directory authentication. Large financial services buyers in New York and London drive procurement for legacy application compatibility despite latency penalties.
- AFS:Andrew File System's distributed cell architecture supports cross-organizational file sharing with Kerberos security integration.
- DFS:Microsoft's Distributed File System provides namespace aggregation and replication for geographically dispersed branch offices.
NFS holds the largest share; momentum sits with SMB/CIFS in Microsoft-dependent verticals.
Deployment Model:
Cost tier stratification separates capital-intensive perpetual licenses from consumption-based operational expenditures reshaping procurement committee composition.
- On-Premises:Physical storage arrays with dedicated hardware controllers maintain dominance in regulated sectors requiring data sovereignty controls. Healthcare systems across Germany and Switzerland cite HIPAA and Swissmedic technical safeguards to justify localized infrastructure despite higher total cost of ownership.
- Cloud-Based:Managed NFS endpoints from hyperscale providers capture expanding share as Kubernetes-native persistent volume provisioning matures. United States cloud service providers standardize on NFSv4.2 pNFS parallel access for containerized workload consolidation.
- Hybrid:Tiered data placement across on-premises and cloud pools enables workload portability without full migration.
- Private:Single-tenant cloud deployments address defense contractors and intelligence community requirements.
On-Premises retains revenue concentration; Cloud-Based deployments are climbing the fastest.
End User:
Customer type determines sales cycle length and certification burden, with procurement sophistication varying across organizational scale.
- Small Enterprises:Limited dedicated storage engineering staff favor subscription-based protocol controllers deployable on commodity servers. North American mid-market accounts increasingly unbundle hardware from software licensing.
- Large Enterprises:Fortune 500 accounts demand hybrid cloud relevance with integrated professional services wrappers. NetApp's ONTAP platform and Dell's PowerScale systems anchor competitive positioning through direct-to-cloud channel displacement.
- Government:Federal contractors face zero-trust architecture mandates and SEC disclosure rules governing storage procurement specifications.
- Education:Research institutions require pNFS parallel access for high-performance computing workloads with specialized tuning expertise.
Large Enterprises command the deepest vendor relationships; Government verticals show steepest expansion trajectory.
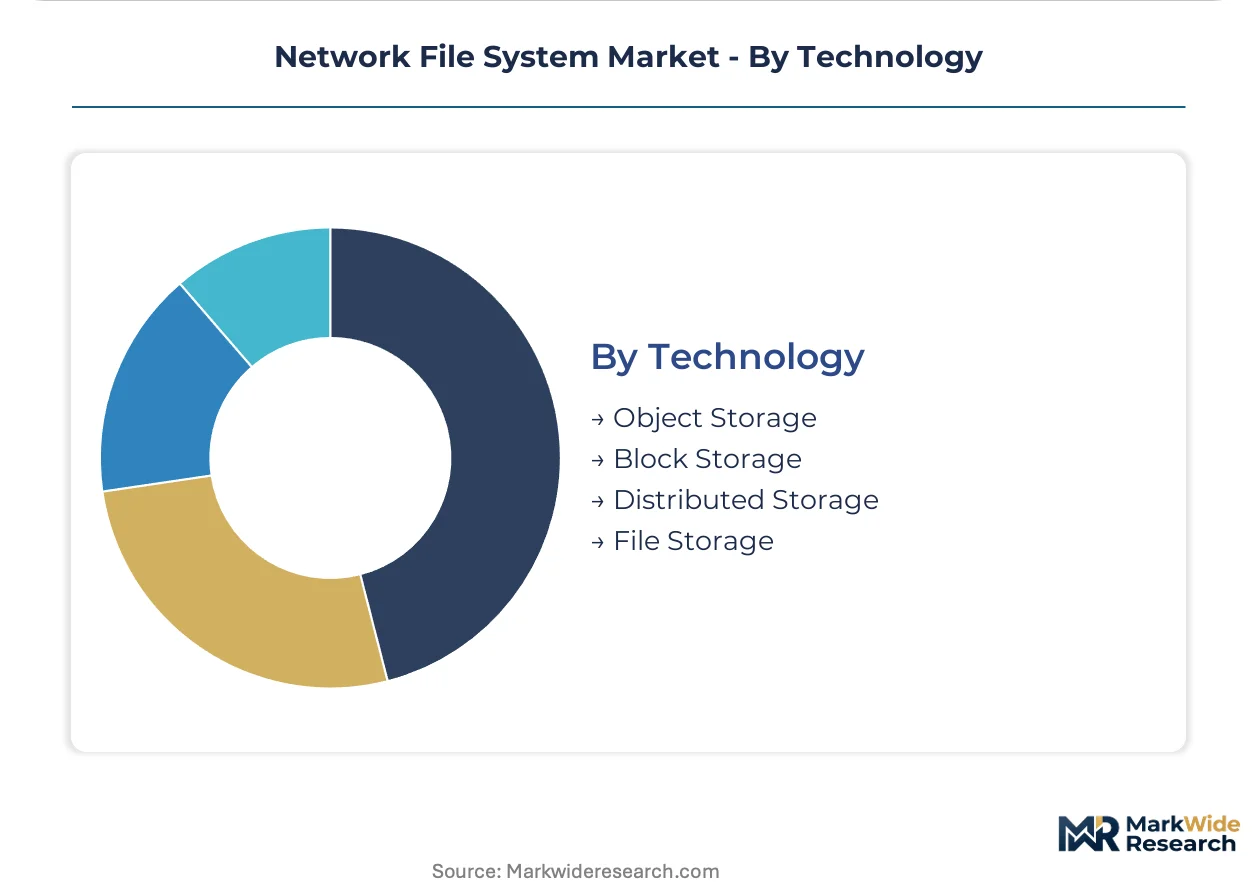
Technology:
Application workload characteristics dictate storage abstraction layer selection, with protocol semantics decoupling from underlying hardware pools.
- Object Storage:S3-compatible APIs with NFS-over-S3 gateway architectures bridge legacy file semantics with cloud-native cost structures. Financial services buyers mandate immutable access logs with cryptographic verification under state-level privacy statutes.
- File Storage:POSIX-compliant namespace with hierarchical directory structures persists for enterprise content management and home directory consolidation. Manufacturing sites across Japan's automotive clusters deploy localized caching layers with intermittent cloud sync.
- Block Storage:Raw volume presentation for database workloads and virtual machine disk images.
- Distributed Storage:Erasure-coded redundancy across commodity nodes without single points of failure.
File Storage maintains protocol leadership; Object Storage convergence is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NIST cybersecurity frameworks and zero-trust architecture mandates in the United States are accelerating protocol standardization across federal contractors. Cloud service providers in hyperscale data centers drive NFSv4.2 adoption for containerized workloads. Procurement patterns fragment across data sovereignty requirements in Germany, Switzerland, Japan, and Australia.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth anchors domestic demand for parallel file system deployments. SEC disclosure rules and HIPAA technical safeguards govern enterprise storage procurement specifications for financial services and healthcare verticals. Fortune 500 accounts in New York and Chicago unbundle hardware from software licensing, favoring subscription-based protocol controllers.
Germany
Automotive manufacturing clusters in Bavaria and Baden-Württemberg require localized NFS caching layers for autonomous vehicle testbeds and smart factory implementations. The country's national data protection authority enforces GDPR-compliant encryption-at-rest mandates that elevate certified product demand. Healthcare systems across Berlin and Hamburg cite data sovereignty controls to justify on-premises infrastructure despite higher operational expenditures.
Switzerland
Swissmedic technical safeguards and banking secrecy regulations sustain dominance of private cloud deployments among Zurich and Geneva financial institutions. Precision manufacturing sites in Basel deploy tiered data placement across on-premises and cloud pools for pharmaceutical research workloads. The country's pharmaceutical regulator mandates immutable access logs with cryptographic verification for clinical trial data management.
Japan
Automotive clusters in Toyota City and Yokohama deploy edge computing implementations with intermittent cloud synchronization for distributed manufacturing sites. METI industrial policy promotes domestic hyperscale data center construction to reduce reliance on foreign cloud infrastructure. Research institutions in Tsukuba require pNFS parallel access expertise for high-performance computing workloads with specialized engineering support.
Australia
Financial services buyers in Sydney and Melbourne mandate SOC 2 Type II certification timelines that extend enterprise storage sales cycles. The country's national privacy regulator enforces state-level privacy statutes requiring audit logging specifications that reshape procurement patterns. Mining and resources sectors in Perth deploy object storage convergence architectures for unstructured data consolidation across remote operational sites.
Network File System Market Competitive Landscape
On the supply side, the industry is consolidating around integrated storage platform vendors with hybrid cloud relevance. Tiered competitive dynamics separate hyperscale cloud-native implementations from on-premises hardware specialists. Three archetypes dominate: legacy enterprise storage vendors with protocol expertise, cloud service providers with managed NFS endpoints, and open-source software-defined storage specialists. Dominant competitive moves include strategic partnerships for Kubernetes-native persistent volume provisioning and portfolio diversification into quantum-resistant encryption modules.
Within the legacy enterprise tier, NetApp and Dell Technologies exemplify integrated platform strategies, while IBM Corporation occupies a position emphasizing parallel file system expertise. NetApp represents the hybrid cloud relevance archetype through its ONTAP platform deployments across Fortune 500 accounts. Dell Technologies anchors the high-performance computing segment with scale-out system implementations. IBM Corporation sits within the specialized engineering tier, leveraging inherited storage portfolio capabilities for research and government verticals.
| Leading Market Players |
|---|
| NetApp |
| IBM Corporation |
| Dell Technologies |
| Hitachi Vantara |
| Western Digital Corporation |
| QNAP Systems |
| Synology |
| Cisco Systems |
| SAP |
| Others |
Supply & Pricing Matrix
Taiwan's NAND flash controller fabrication concentration exposes storage array pricing to geopolitical disruption risk while simultaneously compressing margin pools for vendors dependent on single-source semiconductor procurement. This chokepoint determines both the spread between certified enterprise tiers and commodity server deployments and the geographic reshaping of supply networks as buyers seek qualification diversity.
Pricing Analysis
Certification level creates the primary spread across Network File System procurement, with ISO 27001 and SOC 2 Type II compliance elevating enterprise-grade subscriptions substantially above open-source implementations on commodity hardware. Three-tier pricing structure across premium, standard, and economy levels segments by encryption module certification, after-sales engineering intensity, and Kubernetes-native integration depth. Pricing pressure stems from hyperscale cloud providers internalizing protocol controllers and bypassing traditional vendor markup. Small enterprises exhibit highest price sensitivity, while government contractors facing NIST mandates absorb premium tiers without elasticity.
Supply Chain Analysis
Export-control regimes on advanced NAND fabrication equipment limit technology flows to Chinese memory foundries, constraining supply elasticity for high-density storage arrays. Manufacturing concentrates in Taiwan, South Korea, and Japan, with controller logic and flash memory wafers drawing from concentrated semiconductor fabrication. Raw material dependencies span silicon substrates, rare-earth elements for magnetics, and cobalt for battery-backed cache modules. Single-source vulnerability in Taiwan's controller foundry ecosystem threatens pricing stability. Distribution runs through direct-to-cloud channels displacing traditional hardware resale, with hyperscale providers and systems integrators capturing margin compression.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container storage interface adoption is forcing protocol-layer reinvention that rewards vendors with Kubernetes-native persistent volume expertise while punishing hardware-centric incumbents. NIST post-quantum cryptography mandates will trigger replacement cycles that favor early movers in quantum-resistant encryption certification.
For Market Incumbents: Pre-empt margin erosion by accelerating backward integration into NAND controller supply through strategic foundry partnerships or captive design capabilities. Anchor Fortune 500 relationships through integrated ONTAP-equivalent platforms that bundle professional services wrappers around hybrid cloud deployments. Counter hyperscale cloud provider displacement by certifying quantum-resistant encryption modules ahead of NIST mandate deadlines.
For New Entrants and Emerging Players: Edge computing clusters in Germany's automotive manufacturing corridors present underpenetrated demand for localized NFS caching with intermittent cloud synchronization. Target research institutions requiring pNFS parallel access expertise where specialized engineering scarcity extends sales cycles and elevates service attach rates. Deploy subscription-based protocol controllers on commodity servers to capture North American mid-market accounts unbundling hardware from software licensing.
For Investors and Strategic Acquirers: NIST post-quantum cryptography mandates reshape the acquisition landscape toward vendors with encryption certification pipelines and federal contractor relationships. Long-term viability favors software-defined storage specialists with Kubernetes-native architectures over hardware-dependent legacy platforms. Target acquisition archetypes include open-source NFS implementation vendors with channel partner ecosystems. Monitor SEC disclosure rule enforcement timelines as signal for certified product demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Encryption Certification | NIST post-quantum mandates will drive federal contractor procurement toward certified vendors. |
| Kubernetes-Native Persistent Volume Integration | Container storage interface adoption pulls enterprise storage toward cloud-native NFS implementations. |
| Backward Integration into Controller Supply | Taiwan fabrication concentration creates strategic imperative for supply qualification diversity. |
| Edge Computing Caching Layer Deployment | German automotive clusters require localized infrastructure with intermittent cloud synchronization. |
| Professional Services Capability Buildout | pNFS expertise scarcity elevates vendor margin through post-deployment support intensity. |
Research Methodology
The analysis maps file system protocol variants, deployment models, and end-user segments, each validated through storage engineering directors, federal procurement officers, and hyperscale infrastructure architects. Primary interviews with Kubernetes platform engineers, channel sales heads at systems integrators, and healthcare IT compliance leads combined with secondary validation against hyperscaler capex disclosures, NIST cybersecurity framework publications, and SEC disclosure rule filings. Bottom-up and top-down triangulation cross-validated vendor shipment data against enterprise storage procurement patterns.
Assumptions held NIST mandate timelines and hyperscale data center construction trajectories fixed while varying containerized workload density and quantum-resistant encryption standard adoption rates across the projection horizon. Segmentation dimensions modeled include file system type, deployment architecture, organization scale, technology abstraction layer, and regional regulatory cluster. CAGRs derived from installed base evolution and replacement cycle analysis incorporating NAND flash cost curves and protocol upgrade elasticity. Industry-specific forecast inputs encompass Kubernetes persistent volume provisioning rates and federal contractor certification timelines.
Practitioners should monitor export-control regime expansions and post-quantum cryptography standard finalization for early signals of supply constraint or procurement specification shifts. Forecasts reflect assumptions regarding hyperscale provider internalization rates and edge computing deployment velocities. Material shifts in Taiwan semiconductor access or NIST mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Global Personal Cloud Storage Market
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
Cloud Block Storage Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
Global Cloud Storage Software Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
Nigeria Data Center Storage Market