
 Global Canned Meat Market | 2026-2036
Global Canned Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Canned Meat Market Foresight
Asset-light contract manufacturing and third-party retort processing is reconfiguring capital requirements for new entrants in the canned meat sector. JBS leverages integrated cattle-to-can operations in South America to sustain cost advantages. Hormel Foods Corporation anchors its position through specialized shelf-stable pork portfolios. Danish Crown differentiates via vertically controlled cold-chain-to-retort quality systems.
Canned meat comprises thermally stabilized animal proteins sealed in hermetic containers and processed at temperatures exceeding 121 degrees Celsius to achieve commercial sterility. The category serves institutional buyers requiring extended shelf life without refrigeration. Chicken and pork categories dominate volume due to lower raw material costs and faster retort cycle times. Pouch packaging is gaining share as food service customers seek reduced shipping weights and improved cube utilization. Military rations and emergency food supply applications command premium pricing through specification-grade tendering.
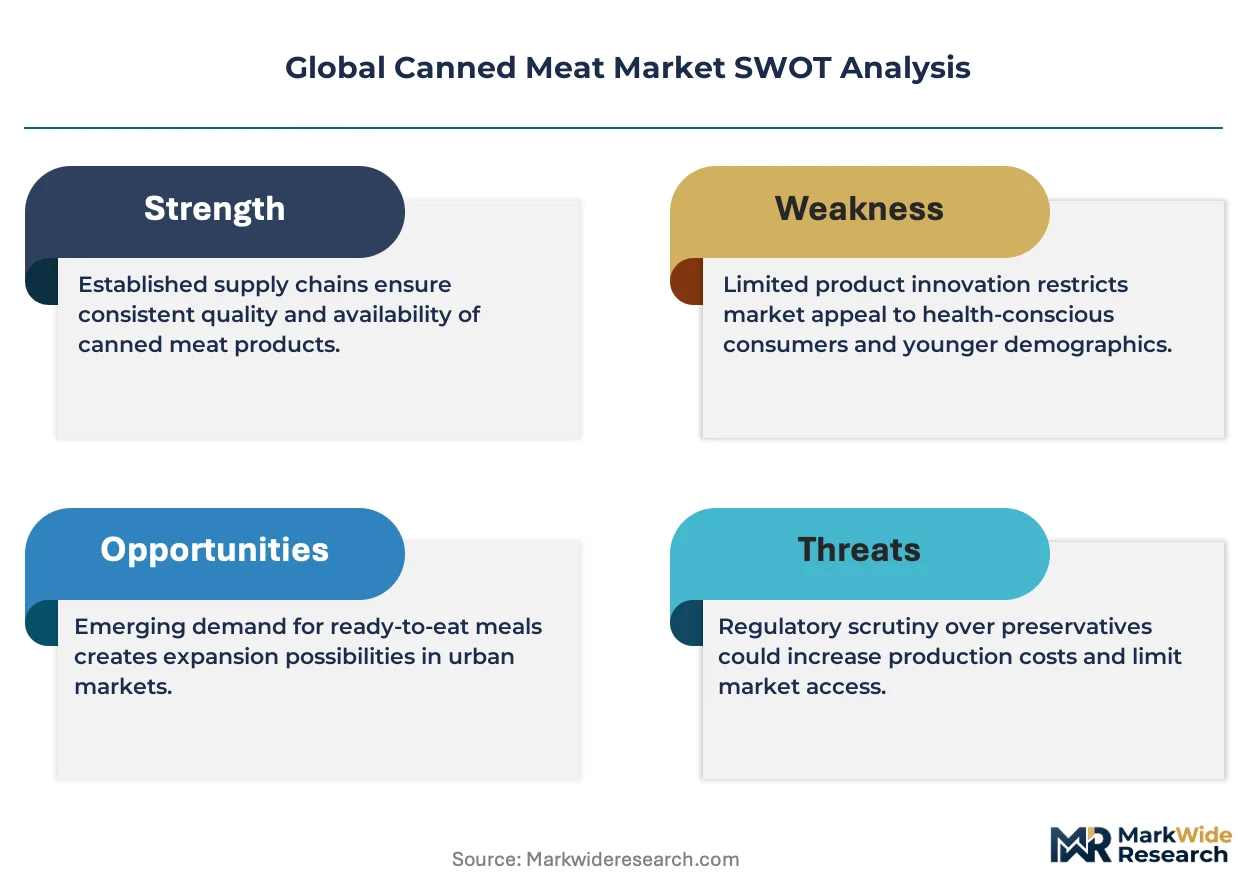
FDA regulations in the United States mandate scheduled process filing for low-acid canned foods, while EFSA and EU MDR frameworks govern additive thresholds and labeling across European markets. Brazil's ANVISA enforces microbiological standards that directly determine export eligibility for Mercosur trade. Stakeholders must monitor evolving retort energy standards and alternative protein labeling requirements as these will determine facility investment priorities and market access conditions.
Market Dynamics
Retort pouch technology is compressing capital requirements and reshaping competitive entry barriers across military and food service procurement channels. Thermal processing equipment upgrades now determine facility compliance rather than container material alone.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain-to-retort facilities in Europe face refrigerant phase-down mandates. Pouch packaging eliminates refrigeration dependency entirely.
- Military shelf-stable protein contracts:NATO member states are expanding multi-year procurement programs for field rations with 5+ year shelf life specifications.
- Brazilian export clusters:Integrated cattle processing regions in Mato Grosso and Paraná concentrate retort capacity serving Mercosur trade corridors.
Market Restraints
- Tinplate input volatility:Steel coil prices and coating material costs fluctuate with energy-intensive smelting operations in China and India.
- Retort equipment supplier concentration:European and Japanese thermal processing machinery vendors control 80% of high-capacity autoclave installations.
- Alternative protein substitution:Plant-based shelf-stable proteins from pea and mycoprotein sources compete for institutional contract slots.
Strategic Opportunities
- Indonesian archipelago logistics:Island supply chains lacking cold-chain infrastructure create demand for ambient-stable protein distribution.
- Humanitarian aid stockpiling:UN World Food Programme and NGO pre-positioning requirements favor long-shelf-life protein formats.
- Retort-pouch food service adoption:Airline catering and offshore energy platforms seek reduced shipping weight versus traditional tinplate.
Industry Challenges
- Scheduled process validation:FDA low-acid canned food filing requirements demand thermal death time studies that extend product launch timelines.
- Retort operator skill scarcity:Qualified thermal processing technicians with FDA Better Process Control School certification command premium wages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Canned Meat Market |
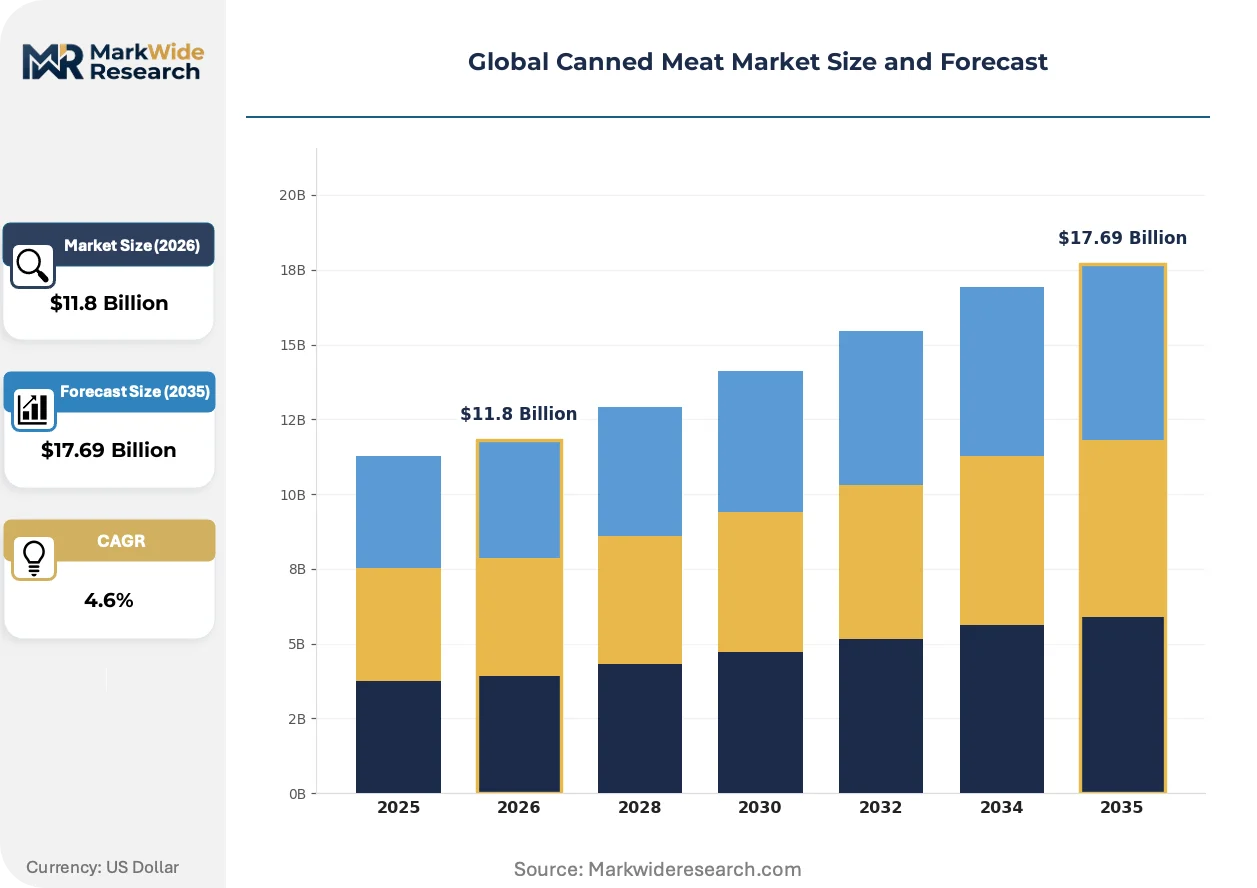
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken, Pork, Beef, Turkey, Lamb, Game Meat Packaging Type: Can, Pouch, Vacuum Pack, Tetra Pak, Jar Application: Food Service, Household Consumption, Military Rations, Emergency Food Supply, Outdoor Activities Customer Type: Retail Chains, Wholesalers, Hospitality Providers, Food Manufacturers, Online Retailers |
| Companies Covered | JBS, Bolton Group, Hormel Foods Corporation, Danish Crown, Smithfield Foods, Conagra Brands, Nestlé, BRF, Tyson Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Canned Meat Market Shifts & Advancements
Packaging material science and thermal processing automation are converging to redefine shelf-stable protein economics. Military and institutional buyers now specify performance criteria rather than container type.
Retort pouch laminates combining aluminum oxide barrier layers with polyester films are migrating from niche military applications toward mainstream food service procurement. Airlines and offshore catering operators adopt these formats to achieve 40% shipping weight reduction. Traditional three-piece tinplate cans face margin compression as pouch lines achieve comparable throughput with lower energy input.
The EU F-Gas Regulation mandates hydrofluorocarbon phase-downs across refrigerated supply chains by 2030. Food manufacturers serving European markets accelerate ambient-stable format development to circumvent cold-chain infrastructure dependency. Retort pouch production lines in Spain and Poland receive priority capital allocation over refrigerated tinplate expansion.
Institutional buyers consolidate supplier relationships around integrated packaging-sterilization-service offerings. Single-source contracts covering raw material, thermal processing, and logistics displace fragmented multi-vendor arrangements. Defense procurement agencies in the United States and United Kingdom lead this consolidation, requiring vendors to assume shelf-life liability across the distribution chain.
Global Canned Meat Market Segmentation
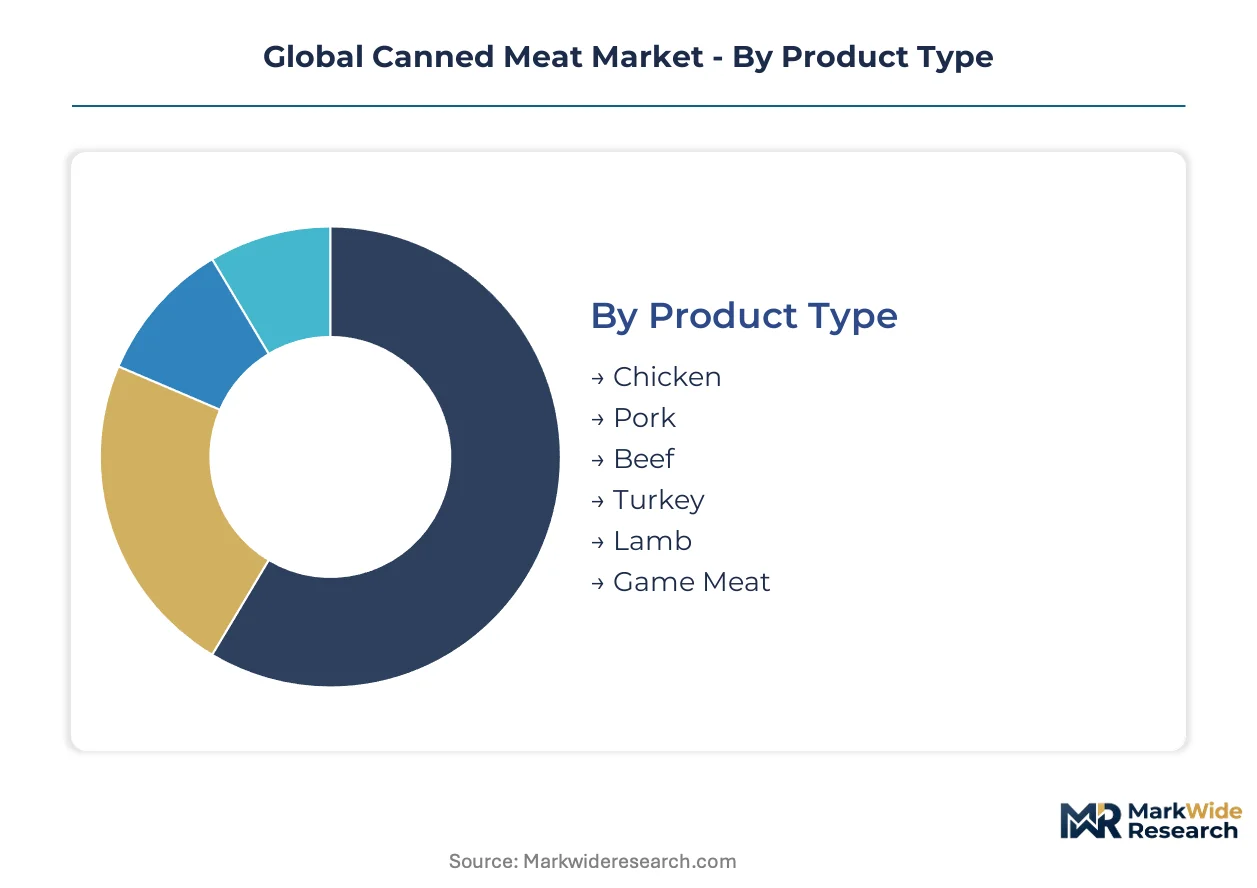
Canned meat segmentation reveals divergent capital intensity and margin profiles across protein types and packaging formats. Military procurement cycles, retail replenishment velocities, and food service contract durations create distinct operating rhythms for each segment cluster.
Product Type:
Chicken and pork command the shortest retort cycle times, turning inventory fastest through thermal processing facilities. Beef and lamb require extended heating profiles that constrain throughput and tie up autoclave capacity.
- Chicken:White meat formulations achieve commercial sterility at reduced thermal death time thresholds, enabling higher line speeds. Demand clusters in Southeast Asian food service channels where Halal-certified poultry dominates institutional tenders.
- Pork:Specialized shelf-stable pork portfolios anchor Hormel Foods Corporation's position in North American retail. European F-Gas Regulation compliance drives substitution toward ambient-stable formats in German and Polish cold-chain-dependent regions.
- Beef:Extended retort cycles and higher raw material costs compress margins versus poultry alternatives.
- Turkey:Lean protein positioning serves health-conscious retail segments and military nutrition specifications.
- Lamb:Niche positioning in Middle Eastern and Mediterranean export corridors with limited volume scale.
- Game Meat:Premium positioning for outdoor activity and specialty retail channels with irregular demand patterns.
Chicken dominates installed base. Pork is where expansion concentrates.
Packaging Type:
Capital deployment intensity varies sharply: tinplate can lines demand heavy foundry-linked infrastructure while pouch formats enable asset-light contract manufacturing entry.
- Can:Three-piece tinplate construction remains the default for military specification-grade tenders requiring 5+ year shelf life validation. Brazilian export clusters in Mato Grosso concentrate canning capacity serving Mercosur trade corridors.
- Pouch:Retort pouch laminates achieve 40% shipping weight reduction versus tinplate, penetrating airline catering and offshore energy platform procurement. EU F-Gas Regulation refrigerant phase-downs accelerate European pouch line investments in Spain and Poland.
- Vacuum Pack:Modified atmosphere formats serve shorter-shelf-life retail segments with refrigeration dependency.
- Tetra Pak:Aseptic processing applications for liquid-containing meat preparations with limited thermal stability requirements.
- Jar:Premium positioning for household consumption in European and Japanese gift-oriented retail channels.
Can formats anchor current revenue. Pouch configurations are climbing the fastest.
Application:
Contract duration and specification rigor separate institutional buyers from discretionary consumer channels.
- Food Service:High-volume procurement from centralized kitchen operators and airline caterers prioritizes cube utilization and shipping efficiency. Retort pouch adoption concentrates here.
- Household Consumption:Retail shelf placement and promotional velocity drive replenishment cycles with seasonal concentration.
- Military Rations:Multi-year NATO procurement programs command premium pricing through specification-grade tendering with extended shelf life requirements.
- Emergency Food Supply:UN World Food Programme and NGO pre-positioning requirements favor proven can formats with decades of field validation.
- Outdoor Activities:Lightweight pouch formats penetrate camping and expedition segments with portability premiums.
Household consumption holds the largest volume position. Military rations deliver the steepest expansion trajectory.
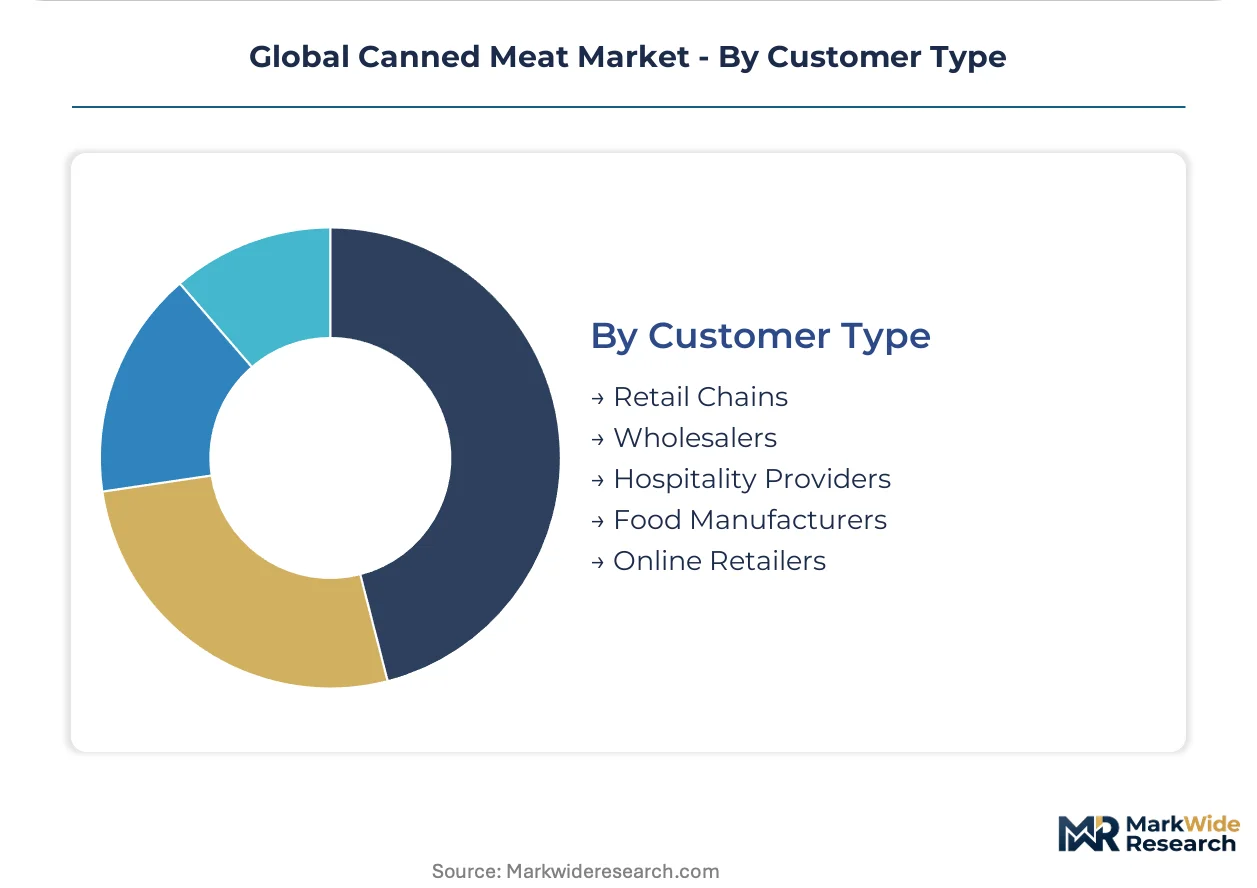
Customer Type:
Consolidation patterns and procurement sophistication determine margin capture across the value chain.
- Retail Chains:Private label concentration and promotional funding requirements compress supplier margins in North American and European markets.
- Wholesalers:Inventory holding functions in fragmented distribution systems across Indonesian archipelago logistics and African import corridors.
- Hospitality Providers:Food service procurement consolidation favors integrated packaging-sterilization-service vendors.
- Food Manufacturers:Ingredient-grade canned meat inputs for further processed product formulations.
- Online Retailers:Direct-to-consumer fulfillment models with subscription mechanics for emergency preparedness segments.
Retail chains control the broadest reach. Hospitality providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation refrigerant phase-down mandates are accelerating ambient-stable protein investments across European processing facilities. Military procurement expansion in NATO member states is redirecting capital toward shelf-stable capacity. Brazilian export clusters leverage integrated cattle-to-can operations for Mercosur trade dominance.
United States
Defense procurement agencies drive specification-grade tendering for field rations with extended shelf life validation. FDA low-acid canned food regulations mandate scheduled process filings that extend product launch timelines. Midwestern meatpacking corridors concentrate retort capacity serving military and institutional channels.
Brazil
Integrated cattle processing regions anchor export-oriented production clusters for Mercosur trade corridors. ANVISA microbiological standards directly determine cross-border eligibility for shelf-stable protein exports. Mato Grosso and Paraná states concentrate tinplate and pouch retort installations serving Atlantic shipping routes.
Germany
Cold-chain-to-retort facility conversions accelerate under F-Gas Regulation hydrofluorocarbon phase-down deadlines. EFSA additive thresholds and labeling frameworks govern formulation compliance across domestic and export markets. Bavarian and North Rhine-Westphalian processing zones prioritize pouch line investments over refrigerated tinplate expansion.
China
Steel coil input costs for tinplate manufacturing fluctuate with energy-intensive smelting operations in northern industrial zones. SAMR and national food safety standards enforce thermal processing compliance for low-acid canned foods. Yangtze River Delta clusters concentrate domestic retort capacity serving food service and emergency supply stockpiling.
Indonesia
Archipelago logistics lacking cold-chain infrastructure create sustained demand for ambient-stable protein distribution across island supply chains. National food security programs prioritize shelf-stable procurement for remote population centers. Java-based processing facilities expand pouch packaging capacity to serve maritime shipping routes.
Global Canned Meat Market Competitive Landscape
On the supply side, the industry is consolidating around integrated packaging-sterilization-service offerings that displace fragmented multi-vendor arrangements. Tiered competitive structure separates scale-driven protein processors from specialized retort operators and asset-light contract manufacturers. Dominant competitive moves include backward integration into captive cattle supply and strategic partnerships with military procurement agencies.
Within the scale-driven tier, JBS and Tyson Foods exemplify integrated cattle-to-can operators leveraging South American and North American protein supply chains. Hormel Foods Corporation occupies a position representing specialized shelf-stable pork portfolio concentration. Danish Crown anchors the vertically controlled quality systems archetype spanning cold-chain-to-retort operations.
| Leading Market Players |
|---|
| JBS |
| Bolton Group |
| Hormel Foods Corporation |
| Danish Crown |
| Smithfield Foods |
| Conagra Brands |
| Nestlé |
| BRF |
| Tyson Foods |
| Others |
Supply & Pricing Matrix
Mato Grosso cattle-to-retort clusters anchor global shelf-stable protein supply, with capacity utilization rates directly transmitting into NATO military contract pricing power. Brazilian integrated processors leverage captive raw material flows to sustain margin premiums against Asian tinplate-dependent competitors.
Pricing Analysis
Certification level (FDA Better Process Control School-grade versus standard commercial thermal processing) creates the primary spread between specification-grade military tenders and food service spot contracts. Three-tier pricing structure across specification-validated, commercial-retort, and private-label economy levels stratifies buyer segments. Cost compression in tinplate-input tiers is intensifying because steel coil volatility from Chinese smelting operations feeds directly into can-format cost bases. Military procurement agencies exhibit lowest price sensitivity due to shelf-life liability requirements, while Asian airline caterers drive hardest bargain on pouch-format cube-utilization metrics.
Supply Chain Analysis
Export-control regimes on high-capacity autoclave technology from European and Japanese machinery vendors constrain retort capacity expansion in emerging production zones. Geographic supply concentration centers on Brazil, the United States, and Germany for integrated protein-to-package operations. Raw material flows draw from Mato Grosso cattle herds, Midwestern pork processing corridors, and Danish Crown cold-chain livestock networks. Single-source vulnerability sits with Japanese thermal processing equipment suppliers controlling eighty percent of high-throughput installations. Distribution runs through Atlantic shipping routes for Mercosur exports, NATO military logistics depots, and Indonesian archipelago inter-island ferry networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified thermal processing technicians with FDA certification credentials represent the binding constraint on capacity expansion, with training pipeline gaps widening faster than automation can offset. This capability scarcity rewards early movers who lock in operator talent pools before competitor facility buildouts.
For Market Incumbents: Pre-empt alternative protein substitution threats by accelerating retort-pouch format R&D investments and securing exclusive military shelf-life liability contracts. Backward integration into captive cattle supply in Paraná state insulates against Brazilian live cattle price volatility. Channel control through single-source packaging-sterilization-service offerings displaces fragmented multi-vendor arrangements favored by institutional buyers. For New Entrants and Emerging Players: Indonesian archipelago logistics lacking cold-chain infrastructure represent the most penetrable entry point for ambient-stable protein distribution. Humanitarian aid stockpiling channels through UN World Food Programme tenders offer specification-grade validation pathways without retail slotting fee barriers. Go-to-market execution should prioritize asset-light contract manufacturing partnerships with existing European F-Gas Regulation-compliant pouch lines rather than greenfield autoclave investments. For Investors and Strategic Acquirers: Long-term, this sits as a defensive infrastructure play because shelf-stable protein demand from military and emergency supply channels exhibits countercyclical stability versus discretionary food service exposure. Acquisition targets should screen for integrated packaging-sterilization capabilities with existing NATO vendor qualification status. The signal to watch is EU F-Gas Regulation enforcement acceleration triggering cold-chain-to-retort conversion capex announcements from German and Polish processors.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Pouch Line Investment | EU F-Gas Regulation compliance eliminates refrigeration dependency for European market access. |
| Military Vendor Qualification | NATO shelf-life liability contracts command premium pricing through specification-grade tendering. |
| Backward Integration into Cattle Supply | JBS and Tyson Foods models demonstrate margin protection against live protein price volatility. |
| Contract Manufacturing Partnership | Asset-light entry reduces capital requirements for new retort pouch market participants. |
| Thermal Processing Technician Training | FDA Better Process Control School certification scarcity constrains competitor capacity expansion. |
Research Methodology
Cross-validation between primary interviews with thermal processing facility managers, military procurement officers, and airline catering procurement leads anchors the qualitative findings against secondary validation from FDA scheduled process filings, ANVISA microbiological standards, and EU F-Gas Regulation implementation guidance. Bottom-up capacity assessments across Mato Grosso, Paraná, and Midwestern processing corridors triangulate against top-down military and humanitarian aid contract value analysis. Trade flow data from Mercosur customs records and NATO logistics procurement disclosures provide shipment-volume calibration.
Calibration against historical capacity expansion patterns and protein input cost cycles shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include protein type, packaging format, application channel, and customer procurement sophistication tier. CAGRs derive from installed base growth rates, military contract award trajectories, and retort equipment order backlogs from European and Japanese machinery vendors. Forecast inputs incorporate F-Gas Regulation phase-down deadlines and alternative protein shelf-stable format competitive intensity.
Stress conditions across steel coil price volatility, autoclave equipment delivery lead times, and FDA scheduled process validation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding military procurement continuity and Mercosur trade corridor stability. Material shifts in EU refrigerant phase-down enforcement velocity or Brazilian ANVISA export standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Hams Market
Meat Products
Europe Meat Products Market
Meat Products
North America Bacon Market
Meat Products
GCC Red Meat Market
Meat Products
North America Canned Meat Market
Meat Products
Bacon Slicers Market
Meat Products
Chicken Fat Market
Meat Products
Europe Processed Meat Market
Meat Products
North America Edible Meat Market
Meat Products
Organic Eggs Market
Meat Products
Reconstituted Meat Market
Meat Products
Global Poultry Meat Market
Meat Products
Canned Beef Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Grassfed Jerky Market
Meat Products
US Meat Market