
 Africa Anti Caking Agent Market | 2026-2036
Africa Anti Caking Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Anti Caking Agent Market Outlook
South Africa's updated food additive regulations under the Department of Health is shifting procurement priorities toward compliant silica-based formulations. Evonik Industries AG leverages its synthetic amorphous silica expertise to serve pharmaceutical and food-grade buyers across Southern Africa. Merck KGaA sustains a strong position in analytical and high-purity grades for laboratory and pharmaceutical applications. Clariant AG specializes in surface-modified silicas that perform under extreme humidity, a critical parameter for West African salt processors.
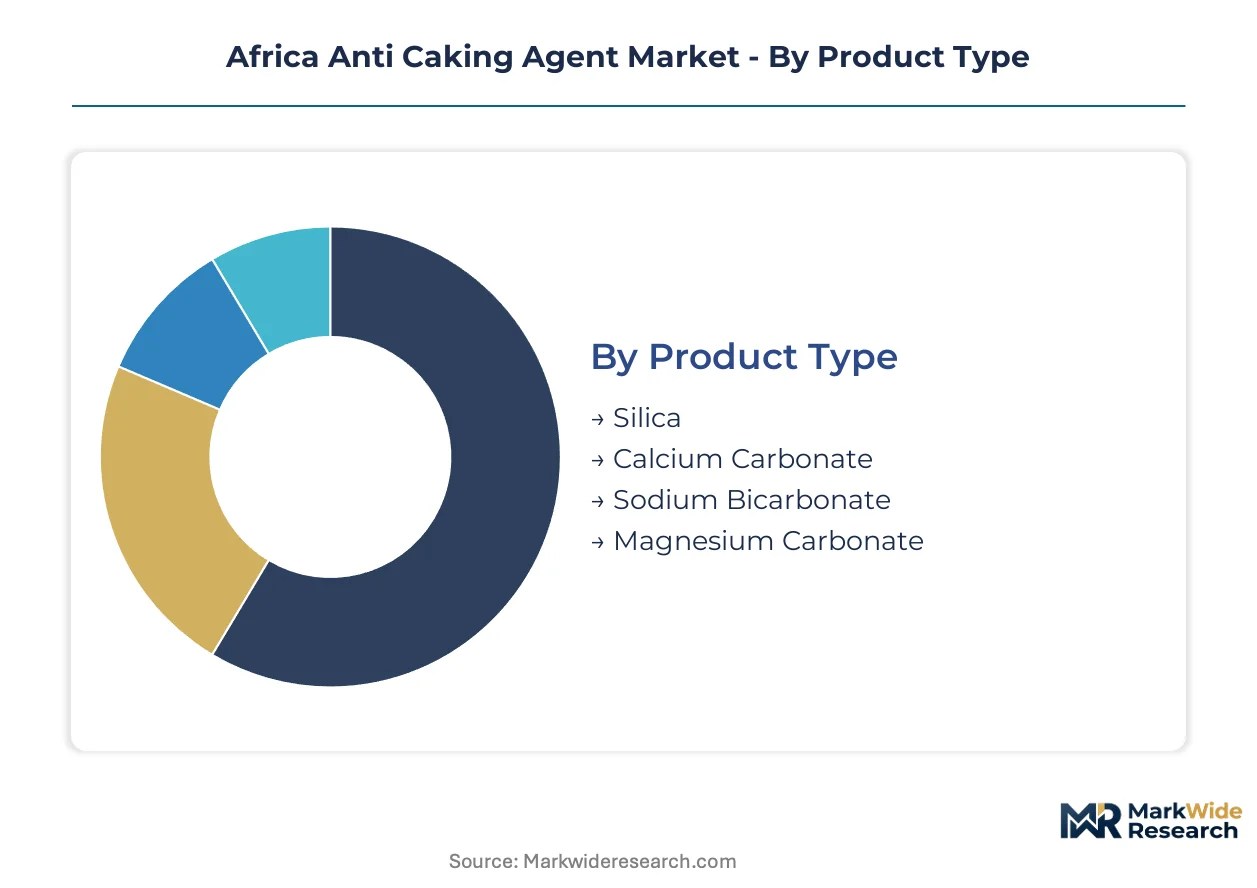
An anti-caking agent is a food-grade or industrial additive, typically composed of silica, calcium carbonate, or magnesium salts, that absorbs moisture and coats particle surfaces to prevent agglomeration during storage and transport. These agents maintain free-flowing properties in hygroscopic powders at dosage levels generally below two percent by weight. Silica-based formulations lead the product type landscape due to their superior moisture absorption capacity and broad regulatory acceptance across African food authorities. The food additives application segment commands the deepest margin pools, while agriculture represents the fastest structural expansion as commercial farming scales up fertilizer blending operations in Kenya and Ethiopia. Powder form dominates current volume, though granule demand is accelerating among large-scale fertilizer distributors seeking reduced dust exposure.
Nigeria's National Agency for Food and Drug Administration and Control sets maximum residue limits that directly determine which silica grades achieve market access. South Africa's Department of Health and the country's Bureau of Standards enforce compositional standards that favor synthetic over mineral-sourced anti-caking materials. Kenya's Pharmacy and Poisons Board extends oversight to pharmaceutical excipient grades, creating a dual-track compliance environment. Stakeholders must monitor how harmonization efforts among African regional economic communities reshape cross-border formulation approvals and testing requirements.
Market Dynamics
Humidity-driven spoilage in bulk powder storage is forcing African processors to upgrade from basic mineral fillers to certified synthetic silica grades, compressing procurement cycles and tightening supplier qualification standards across the continent's food and fertilizer corridors.
Growth Catalysts
- Synthetic Silica Substitution:South Africa's Department of Health labeling mandates are accelerating displacement of mineral-sourced anti-caking agents with certified synthetic grades in packaged foods.
- Fertilizer Blending Expansion:Commercial farming scale-up in Kenya and Ethiopia is pulling demand for flow agents in bulk NPK compound production and regional distribution networks.
- NAFDAC Maximum Residue Limits:Nigeria's regulatory enforcement is filtering non-compliant silica sources from the northern grain belt salt and grain processing clusters.
Market Restraints
- Soda Ash Price Volatility:Sodium carbonate feedstock fluctuations squeeze margin structures for domestic calcium silicate producers in Egypt and Morocco.
- European Import Concentration:High-purity synthetic silica supply concentrates among specialized German and Dutch chemical exporters, exposing buyers to euro-denominated cost pass-through.
- Mineral Silica Technical Ceiling:Natural diatomaceous earth grades face moisture absorption limits that disqualify them from pharmaceutical excipient applications under Kenya's Pharmacy and Poisons Board standards.
Strategic Opportunities
- Ethiopian Fertilizer Industrial Parks:Government-backed blending facility construction near the Awash Valley creates captive demand for granule-format flow agents with reduced dust profiles.
- Regional Harmonization:East African Community mutual recognition protocols for food additive approvals could streamline cross-border silica grade registrations.
- Pharmaceutical Excipient Tier:Rising local tablet manufacturing in Nigeria and South Africa opens premium positioning for high-purity colloidal silica meeting pharmacopeia standards.
Industry Challenges
- Certification Timeline Compression:South Africa's Bureau of Standards testing backlogs delay new silica grade market entry by six to nine months.
- Analytical Capability Gaps:Limited in-country particle size distribution and surface area testing infrastructure forces reliance on European laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Anti Caking Agent Market |
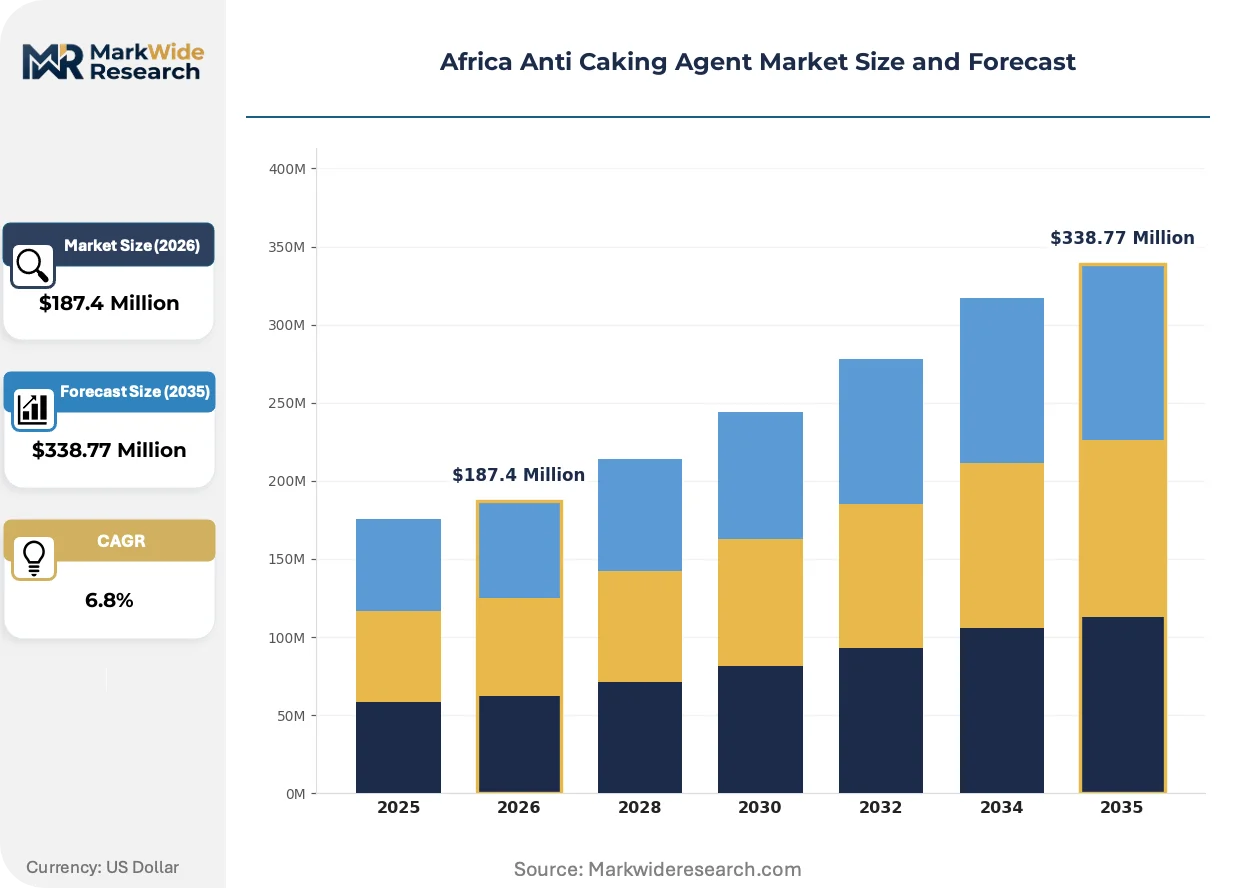
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica, Calcium Carbonate, Sodium Bicarbonate, Magnesium Carbonate Application: Food Additives, Pharmaceuticals, Agriculture, Personal Care End User: Food Processing, Chemical Manufacturing, Cosmetic Industry, Animal Feed Form: Powder, Granules, Liquid, Pellets |
| Companies Covered | Merck KGaA, Evonik Industries AG, PPG Industries, Solvay, PQ Corporation, ArrMaz, Brenntag AG, Univar Inc., Clariant AG, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Anti Caking Agent Market Strategic Shifts
Moisture management technologies are pivoting from passive absorption to surface-engineered particle coatings, while regulatory fragmentation across African economic communities forces suppliers to maintain multiple formulation portfolios.
Surface-modified precipitated silica is decentralizing quality control in West African salt processing. Clariant AG and regional distributors are deploying humidity-stable silane-treated grades that eliminate the need for climate-controlled warehousing in Lagos and Port Harcourt port zones. Mid-size salt refiners now source directly through technical service partnerships rather than commodity traders, compressing the traditional three-tier supply structure.
REACH-equivalent substance registration requirements under South Africa's Department of Health are restructuring import documentation. Manufacturers must now submit full compositional disclosure for synthetic amorphous silica, favoring suppliers with existing EU dossiers. Food-grade buyers in Cape Town and Durban are consolidating procurement around pre-qualified vendors to avoid customs detention risks.
Granule-format preference is displacing powder dominance among Kenyan and Ethiopian fertilizer cooperatives. Large-scale distributors specify dust-suppressed silica carriers to meet occupational exposure standards in open-air blending operations. This specification shift rewards suppliers with compaction and prilling capabilities, squeezing basic powder traders from commercial farming supply chains.
Africa Anti Caking Agent Market Segmentation
Anti-caking agent procurement in Africa fragments across certification regimes that vary sharply by end-use. Food-grade silica faces NAFDAC residue limits in Nigeria, pharmaceutical excipients answer to Kenya's Pharmacy and Poisons Board, and fertilizer flow agents navigate less stringent but volume-driven specifications.
Product Type:
Certification burdens fall heaviest on synthetic silica grades, which must satisfy food authority compositional standards across multiple jurisdictions, while mineral-sourced alternatives operate under lighter documentation requirements in industrial applications.
- Silica:Synthetic amorphous silica dominates moisture absorption performance with surface areas exceeding 200 m²/g. South Africa's Department of Health labeling mandates are accelerating displacement of mineral alternatives in Cape Town and Durban packaged food corridors.
- Calcium Carbonate:A cost-effective mineral filler with moderate hygroscopic control, favored in Egyptian and Moroccan domestic production where soda ash price volatility squeezes margin structures. Local producers face technical ceilings against synthetic grades in premium applications.
- Sodium Bicarbonate:Dual-function leavening and flow agent serving bakery processors in Nigeria's northern grain belt with simpler regulatory pathways than silica-based alternatives.
- Magnesium Carbonate:Lightweight mineral grade with niche positioning in pharmaceutical tablet manufacturing, constrained by limited African sourcing and import dependency.
Leading the category by volume: Silica. Expanding most quickly: Calcium Carbonate in North African domestic manufacturing.
Application:
Margin structures diverge sharply across this dimension, with pharmaceutical excipients commanding premium pricing tiers while agricultural volumes scale through bulk fertilizer blending economics.
- Food Additives:The deepest margin pool in African anti-caking demand, requiring synthetic silica grades that satisfy Bureau of Standards compositional standards. Humidity-driven spoilage in West African salt processing drives specification upgrades.
- Agriculture:Commercial farming scale-up in Kenya and Ethiopia pulls granule-format demand for NPK compound production. Open-air blending operations specify dust-suppressed carriers to meet occupational exposure standards.
- Pharmaceuticals:High-purity colloidal silica for tablet manufacturing faces Kenya's Pharmacy and Poisons Board excipient standards, creating dual-track compliance with food-grade pathways.
- Personal Care:Cosmetic formulations utilize surface-modified silicas for powder flow in Lagos and Port Harcourt manufacturing zones, with lighter regulatory burdens than ingestible grades.
Capturing the largest revenue share: Food Additives. Gaining share fastest: Agriculture through Ethiopian fertilizer industrial park development.
End User:
Procurement sophistication varies dramatically by buyer type, from multinational food processors with pre-qualified vendor lists to fragmented animal feed compounders operating through commodity traders.
- Food Processing:Salt refiners and grain processors across Nigeria's northern belt and East African corridors drive certified silica demand. Technical service partnerships are compressing traditional three-tier supply structures.
- Chemical Manufacturing:Fertilizer blenders in the Awash Valley and Kenyan cooperatives specify granule formats with reduced dust profiles, rewarding suppliers with compaction capabilities.
- Cosmetic Industry:Personal care manufacturers in South African urban centers source surface-modified grades for powder formulations, with procurement consolidating around REACH-equivalent documentation.
- Animal Feed:Price-sensitive compounders in fragmented West African markets favor mineral-grade fillers with minimal certification overhead, limiting synthetic silica penetration.
Commanding procurement volume: Food Processing. Showing steepest expansion trajectory: Chemical Manufacturing through regional fertilizer blending scale-up.
Form:
Physical format selection increasingly reflects occupational health specifications rather than pure technical performance, with dust exposure regulations reshaping large-scale agricultural procurement.
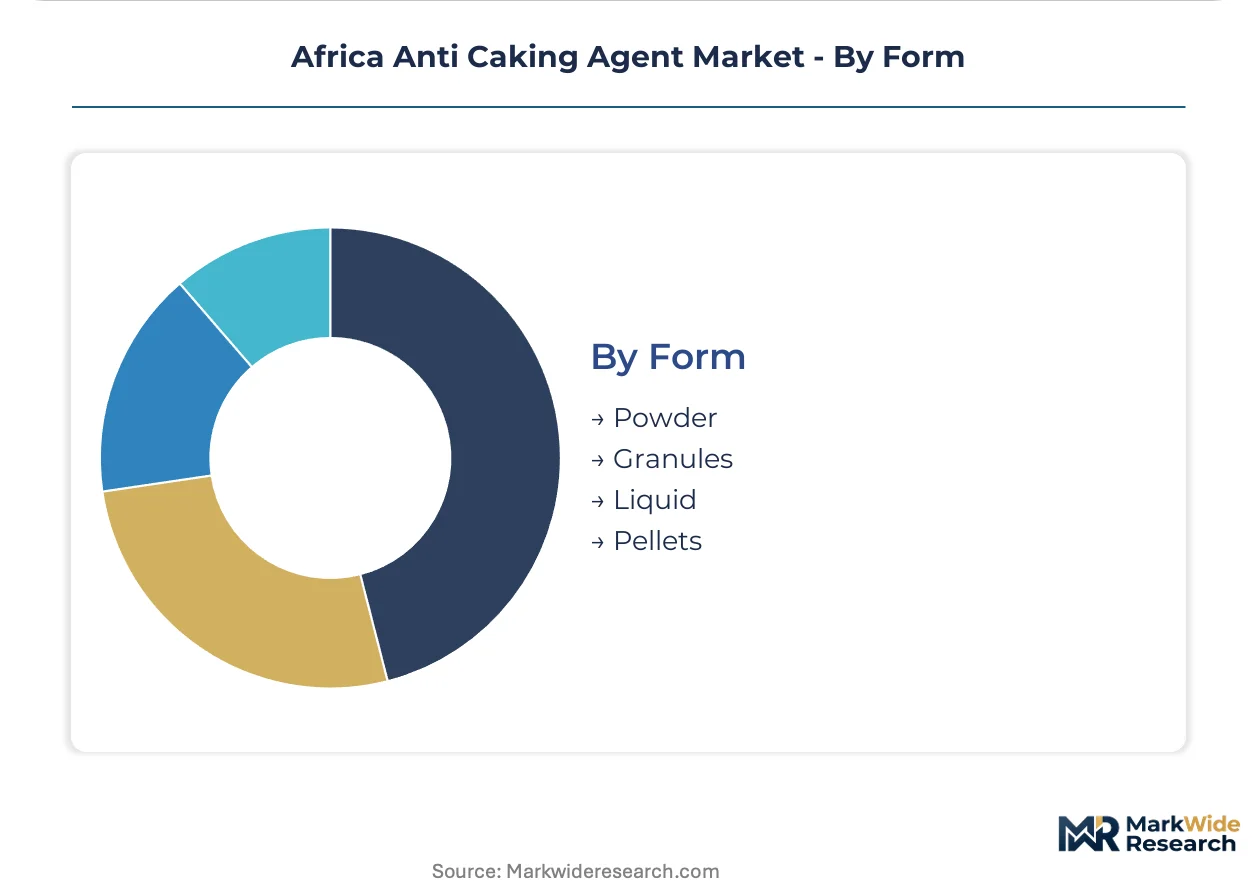
- Powder:Traditional dominant format with superior dispersion characteristics in food and pharmaceutical applications. Retains share in climate-controlled warehousing environments.
- Granules:Dust-suppressed compaction products specified by Kenyan and Ethiopian fertilizer distributors for open-air blending operations, displacing powder in commercial farming supply chains.
- Liquid:Niche suspension formats for specialized coating applications in personal care manufacturing, limited by shipping cost economics in African distribution.
- Pellets:High-density flow agents for automated fertilizer handling systems in Ethiopian government-backed industrial parks, emerging as a format for captive supply arrangements.
Current volume leader: Powder. Climbing the fastest: Granules through occupational exposure standard adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos and Port Harcourt anchor West African anti-caking demand through salt processing clusters and port-side warehousing that require humidity-stable silica grades.
South Africa
Synthetic amorphous silica procurement concentrates in Cape Town and Durban packaged food corridors. The Department of Health enforces compositional standards that favor synthetic over mineral-sourced materials. Bureau of Standards testing backlogs delay new grade market entry by six to nine months.
Nigeria
Bulk salt and fertilizer distribution networks across the northern grain belt drive certified silica demand. NAFDAC maximum residue limits filter non-compliant sources from processing clusters. Kano and Kaduna refiners source directly through technical service partnerships rather than commodity traders.
Kenya
Commercial farming scale-up pulls granule-format demand for NPK compound production. The Pharmacy and Poisons Board extends oversight to pharmaceutical excipient grades, creating dual-track compliance. Nairobi-based cooperatives specify dust-suppressed carriers for open-air blending operations.
Ethiopia
Government-backed blending facility construction near the Awash Valley creates captive demand for pellet-format flow agents. Large-scale distributors seek reduced dust exposure for occupational health compliance. Addis Ababa procurement offices consolidate around pre-qualified vendors.
Egypt
Domestic calcium silicate production serves North African markets where soda ash price volatility squeezes margin structures. Local producers face technical ceilings against synthetic grades in premium applications. Alexandria and Cairo chemical corridors favor cost-effective mineral fillers for industrial use.
Africa Anti Caking Agent Market Competitive Environment
The competitive structure tilts toward specialty chemical multinationals with established regulatory dossiers. Synthetic silica supply concentrates among German and Dutch exporters, exposing African buyers to euro-denominated cost pass-through. Three archetypes dominate: integrated silica manufacturers with pharmaceutical-grade capabilities, regional distributors with technical service partnerships, and commodity traders serving price-sensitive mineral-grade segments. Competitive moves center on pre-qualification vendor consolidation and surface-modified formulation licensing.
Within the integrated manufacturing tier, Evonik Industries AG and Merck KGaA occupy positions anchored by synthetic amorphous silica expertise and analytical-grade portfolios. Clariant AG represents the surface-engineering specialist archetype, with silane-treated grades targeting humidity-extreme applications. Among distribution-focused players, Brenntag AG and Univar Inc. exemplify the technical service partnership model that compresses traditional three-tier supply structures in West African salt processing.
| Leading Market Players |
|---|
| Merck KGaA |
| Evonik Industries AG |
| PPG Industries |
| Solvay |
| PQ Corporation |
| ArrMaz |
| Brenntag AG |
| Univar Inc. |
| Clariant AG |
| Others |
Value Chain & Pricing Dynamics
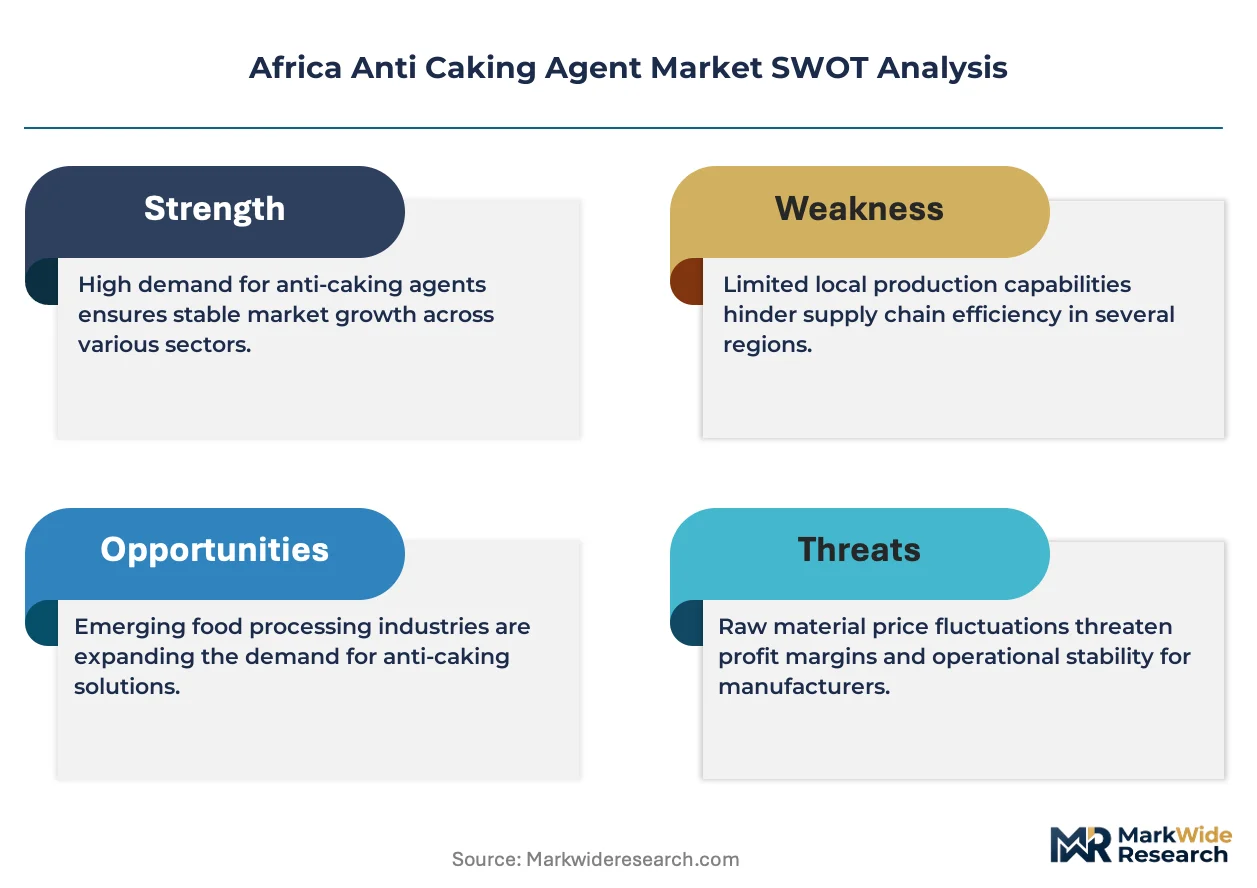
NAFDAC-mandated residue limit compliance across Nigeria's northern grain belt is compressing procurement cycles toward certified synthetic silica grades, forcing supply consolidation around pre-qualified European exporters and transmitting euro-denominated cost pass-through into African buyer budgets.
Pricing Analysis
Yield-guarantee pricing in fertilizer blending applications anchors value-based contracts where flow agent performance directly correlates with NPK compound throughput. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial mineral grades reflects certification burden differentials under South Africa's Bureau of Standards and Kenya's Pharmacy and Poisons Board. Cost compression in mineral-sourced calcium carbonate runs through Egyptian and Moroccan domestic production as soda ash feedstock volatility squeezes margin structures. Animal feed compounders in fragmented West African markets exhibit highest price sensitivity, while pharmaceutical excipient buyers in Lagos and Cape Town accept premium positioning for pharmacopeia-compliant colloidal silica.
Supply Chain Analysis
Specialized chemical manufacturing workforce availability in Germany and the Netherlands anchors synthetic amorphous silica production for African export markets. Supply concentrates among Rhine-Ruhr chemical corridor producers and Dutch specialty chemical exporters, with raw material dependencies on sodium silicate feedstocks and energy-intensive precipitation processes. Single-source vulnerability from eurozone production concentration exposes buyers to currency fluctuation and logistics chokepoint risks at Rotterdam and Hamburg port zones. Distribution runs through technical service partnerships that compress traditional trader-mediated supply tiers in West African salt processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic surface-modified silica formulations are displacing legacy mineral diatomaceous earth grades across humidity-extreme African storage environments, creating technology-transition arbitrage for positioned suppliers.
For Market Incumbents: Anchor defensive positioning through backward integration into sodium silicate feedstock security and accelerated Bureau of Standards pre-certification for new synthetic grades. Mineral silica substitution threats from Kenyan and Ethiopian fertilizer cooperatives demand granule-format compaction capability investments to retain commercial farming supply chain access. Certification timeline compression at South Africa's testing facilities represents a margin defense lever through dedicated regulatory affairs staffing. For New Entrants and Emerging Players: The premium-to-economy price-point gap in pharmaceutical excipient grades opens white-space targeting for high-purity colloidal silica producers meeting Kenya's Pharmacy and Poisons Board standards. Ethiopian government-backed fertilizer industrial parks near the Awash Valley offer the most penetrable geography for pellet-format flow agent introductions. Direct technical service partnerships with mid-size salt refiners in Kano and Kaduna bypass entrenched commodity trader networks. For Investors and Strategic Acquirers: The window for entry favors surface-engineering specialists with silane-treatment intellectual property and existing REACH-equivalent dossiers. Long-term viability rests on regulatory harmonization execution across East African Community mutual recognition protocols. The signal to watch is NAFDAC enforcement intensity in Nigeria's northern grain belt as a demand-pull inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate Feedstock | Captive supply security insulates margin structures from soda ash volatility in North African production zones. |
| Surface Modification Technology Licensing | Silane-treated silica patents unlock humidity-stable positioning for West African port-side warehousing applications. |
| Granule Format Compaction Capacity Expansion | Dust-suppressed carrier production meets Kenyan and Ethiopian occupational exposure standard adoptions. |
| Bureau of Standards Pre-Certification Investment | Accelerated grade registration compresses six-to-nine month market entry delays in South African corridors. |
| Technical Service Partnership Model Deployment | Direct refiner relationships displace three-tier supply structures in Nigeria's northern salt processing belt. |
Study Parameters
Independent corroboration across regulatory affairs directors at specialty chemical manufacturers, procurement leads at Nigerian salt refiners, and distribution channel partners in East African fertilizer cooperatives underwrites the qualitative findings. Secondary validation drew from NAFDAC additive registration databases, South African Bureau of Standards compositional disclosure records, and East African Community harmonization protocol documents. Bottom-up demand modeling from end-use procurement patterns and top-down supply capacity assessments were cross-referenced for triangulation.
Rate-of-change decomposition across the analysis window separated volume growth from price-mix effects in synthetic silica substitution trends. Segmentation dimensions modeled include product grade tier, application end-use, physical format specification, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation with scenario-weighted adjustments. Forecast inputs incorporated Bureau of Standards testing backlog durations and Ethiopian industrial park construction timelines as industry-specific variables.
Inputs from NAFDAC registration filings and Kenyan Pharmacy and Poisons Board excipient approvals were available through the study window; gaps in real-time customs transaction data introduce uncertainty bands around import volume estimates. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and regional harmonization progress. Material deviation in NAFDAC maximum residue limit implementation intensity or East African Community mutual recognition protocol ratification warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Argentina Food Colorants Market
Food Additives and Ingredients
Natural Food Additives Market
Food Additives and Ingredients
Lactylated Monoglyceride Market
Food Additives and Ingredients
India Food Enzymes Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
South America Food Emulsifiers Market