
 Meat Mincers Market | 2026-2036
Meat Mincers Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Mincers Market Foresight
Modular attachment systems is decoupling grinder heads from motor bases, letting butcher shops swap components rather than replace entire units. Hobart leverages its commercial kitchen installed base to cross-sell grinder attachments through existing slicer and mixer accounts. Paul KOLBE GmbH anchors its position with precision-ground worm gears and hardened steel cutting assemblies engineered for Central European sausage traditions. Sirman SpA competes through compact footprint designs that suit Mediterranean retail counters where space constraints dominate layout decisions.
A meat mincer is a mechanical food-processing device that forces meat through a rotating auger and perforated cutting plate, typically achieving throughput rates from 100 kg/hour in compact models to over 3,000 kg/hour in industrial configurations, with plate perforation diameters determining final particle size for specific sausage or ground-meat applications. Electric units dominate volume sales across restaurant chains and central kitchens where labor efficiency governs procurement, while heavy-duty stainless steel configurations command margin premiums in regulatory-intensive environments due to corrosion resistance and clean-in-place compatibility. Manual mincers retain niche demand among home users and artisanal butcher shops where batch control and traditional texture preservation outweigh speed requirements.
NSF International standards govern food-contact surface sanitation in the United States, while ECHA REACH restrictions limit certain alloy compositions in European-manufactured cutting components, and CE marking under the EU Machinery Directive mandates emergency-stop integration and guarding specifications for commercial units. These frameworks elevate engineering compliance costs but simultaneously lock out uncertified imports, protecting incumbent supplier positions. Stakeholders must weigh certification maintenance expenses against the defensive moat that regulatory adherence creates in fragmented regional markets.
Market Dynamics
Modular grinder architecture is fragmenting replacement demand across butcher shops and central kitchens, forcing suppliers to defend installed bases through attachment ecosystems rather than full-unit refresh cycles.
Growth Catalysts
- NSF/ANSI Sanitation Standards:Tightened hygiene specifications for food-contact surfaces in North American commercial kitchens are accelerating equipment replacement cycles among regulated foodservice operators.
- Artisanal Butchery Resurgence:Premium meat retail formats in Germany and Italy sustain demand for precision-ground cutting assemblies engineered to traditional sausage specifications.
- Clean-in-Place Compatibility:Corrosion-resistant stainless steel configurations with integrated washdown protocols are capturing margin premiums in regulatory-intensive hospital and institutional catering environments.
Market Restraints
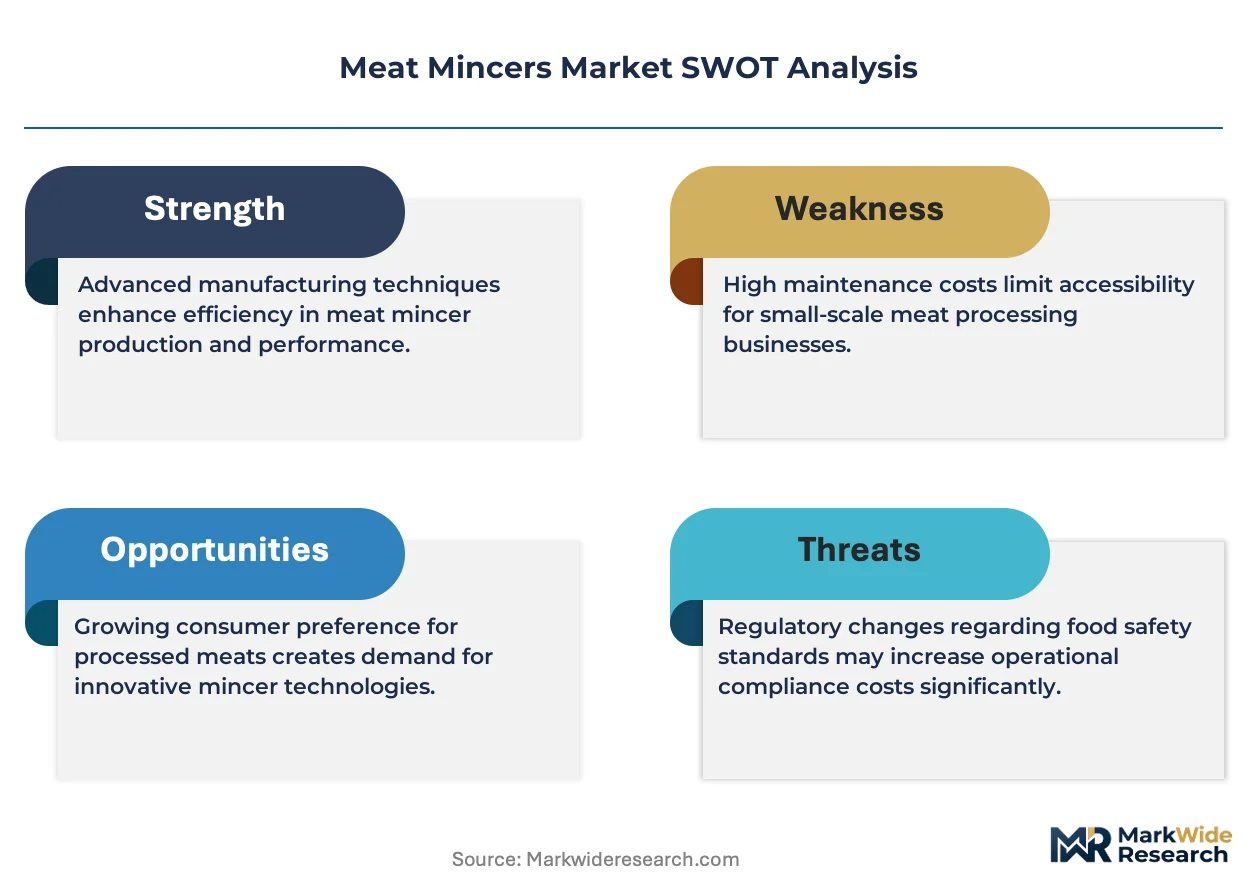
- Alloy Composition Restrictions:ECHA REACH limitations on certain cutting component alloys in European manufacturing are elevating raw material substitution costs and compressing supplier margins.
- Input Cost Volatility:Fluctuations in food-grade stainless steel and hardened tool steel prices are destabilizing procurement planning for mid-scale equipment fabricators.
- Manual Unit Substitution:Compact hand-crank mincers retain entrenched demand among home users and small-batch artisanal processors where speed requirements remain secondary to texture control.
Strategic Opportunities
- CE Marking Convergence:Emergency-stop integration and guarding specification mandates under the EU Machinery Directive are creating defensive moats for certified European suppliers against uncertified import competition.
- Supermarket Meat Department Modernization:Equipment refresh programs in US and Italian grocery retail chains present attach-rate opportunities for grinder-slicer cross-selling.
- Compact Footprint Design:Space-constrained Mediterranean retail counters are driving specification demand for reduced-dimension units that preserve counter workflow efficiency.
Industry Challenges
- Certification Timeline Compression:Multi-jurisdictional compliance with NSF International, CE marking, and ISO food safety standards is extending product development cycles and delaying revenue recognition.
- Legacy System Integration Friction:Modular attachment protocols often conflict with proprietary motor base architectures from established kitchen equipment platforms, complicating retrofit sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Mincers Market |
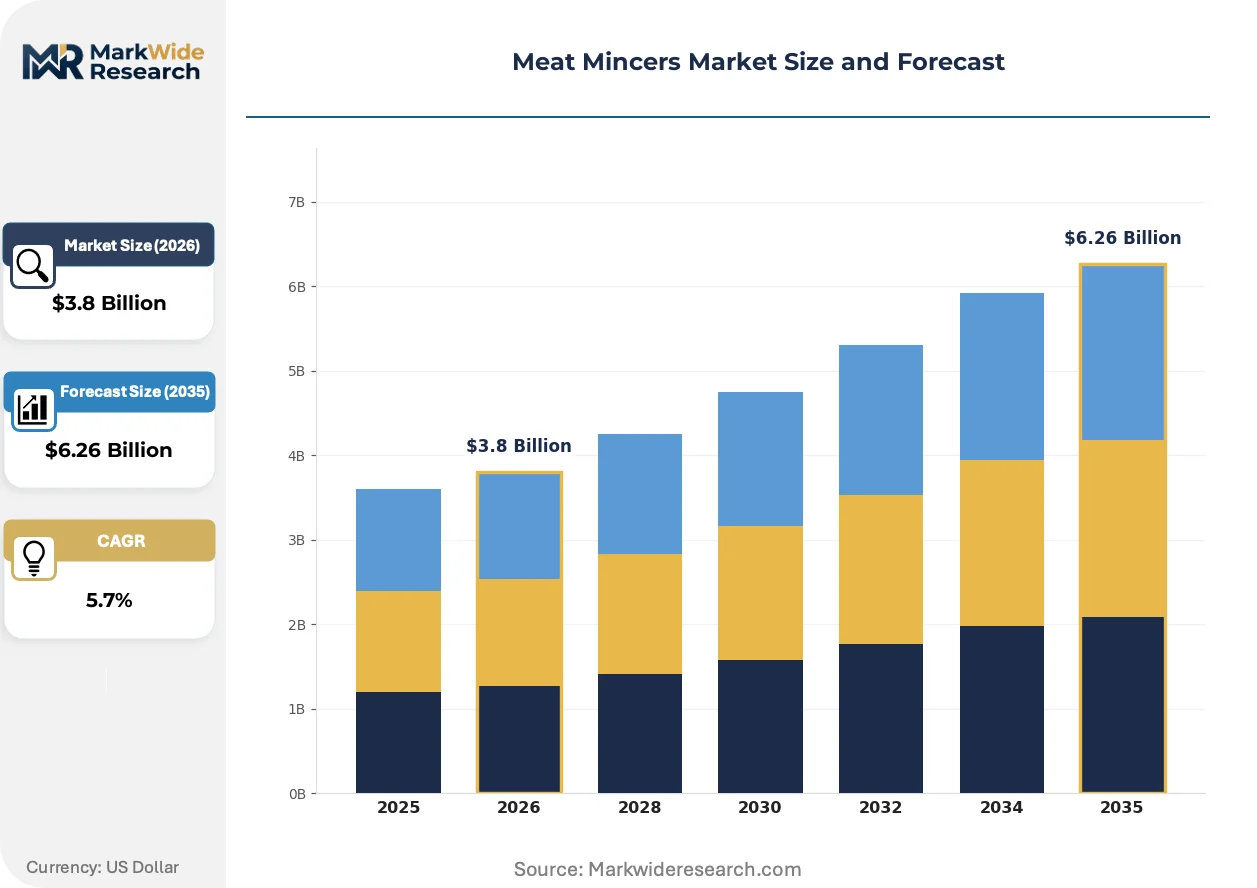
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Industrial, Heavy-Duty End User: Restaurants, Butcher Shops, Supermarkets, Home Users Material: Stainless Steel, Aluminum, Plastic, Cast Iron Size: Compact, Medium, Large, Extra-Large |
| Companies Covered | Hobart, Paul KOLBE GmbH, Braher Internacional, Butcher Boy Machines International LLC, ITW Food Equipment Group, Biro Manufacturing Company, Bizerba USA Inc., Sirman SpA, Globe Food Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Mincers Market Shifts & Advancements
Equipment architecture is pivoting from monolithic units toward componentized systems, while regulatory compliance is becoming a primary design constraint rather than a post-hoc certification step.
Precision-ground worm gear assemblies with hardened steel cutting matrices are expanding into high-throughput central kitchens serving restaurant chains and institutional foodservice. These configurations achieve particle size consistency critical to sausage emulsion stability. The technology is compressing tolerance for lower-grade cutting components in volume-oriented procurement specifications.
EU Machinery Directive guarding mandates and emergency-stop integration requirements are elevating engineering compliance costs for commercial unit certification. This regulatory friction is locking out uncertified imports from Asian manufacturing hubs. European incumbent suppliers are reinforcing defensive positions through proactive conformity assessment investments.
Buying patterns among butcher shops and supermarket meat departments are rotating toward component-level refresh rather than full-system replacement. Attachment cross-compatibility is displacing single-vendor lock-in as a procurement priority. This behavioral shift is most visible in German and US markets where established slicer and mixer installed bases create grinder attachment attach-rate opportunities.
Meat Mincers Market Segmentation
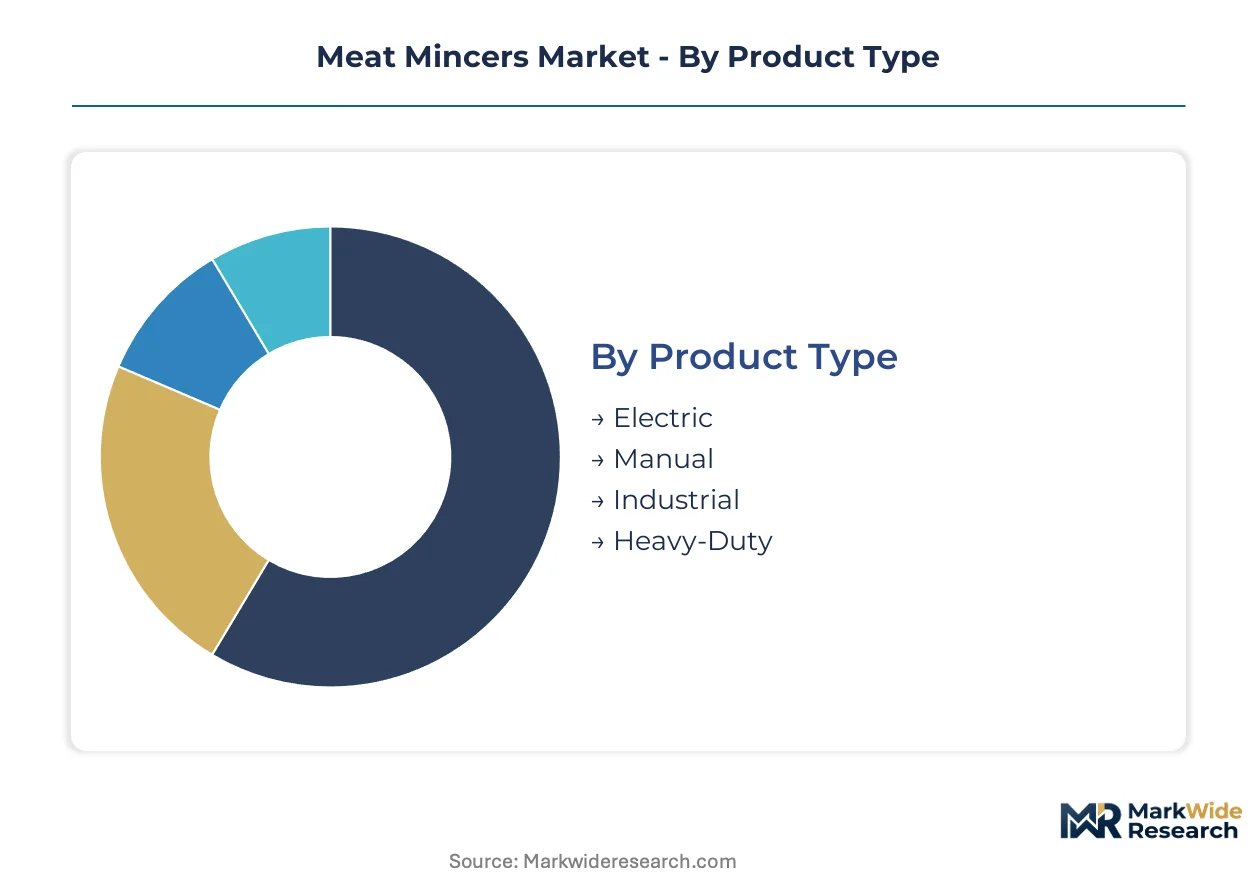
Equipment specification diversity in meat mincers reflects divergent buyer priorities across regulatory environments, throughput requirements, and durability expectations. Procurement committees weigh sanitation certification grades against capital expenditure constraints when segmenting vendor shortlists. Understanding these trade-offs clarifies why certain configurations command margin premiums while others compete on replacement-cycle economics.
Product Type:
Throughput requirements and labor cost structures determine whether buyers prioritize motorization, manual control, or industrial-scale capacity.
- Electric:Motor-driven auger systems deliver 100 kg/hour to 3,000 kg/hour throughput rates with consistent particle size distribution. Restaurant chains and central kitchens in the United States specify these units where labor efficiency governs procurement decisions and NSF/ANSI sanitation certification is mandatory for regulatory compliance.
- Industrial:Continuous-feed configurations with hardened steel cutting matrices serve high-volume sausage production lines and institutional catering operations. Demand concentrates in Germany and Italy where precision-ground worm gear assemblies support traditional emulsion stability requirements in artisanal butchery.
- Manual:Hand-crank mechanisms preserve batch-level texture control for small-batch artisanal processors. Home users and specialty butcher shops in Mediterranean markets retain demand where speed requirements remain secondary to traditional preparation methods.
- Heavy-Duty:Reinforced motor housings and corrosion-resistant contact surfaces withstand washdown protocols in hospital and regulatory-intensive foodservice environments. Clean-in-place compatibility commands specification priority in institutional procurement.
Electric configurations lead on scale; Industrial units lead on momentum in premium meat retail expansion.
End User:
Facility type dictates equipment durability standards, footprint constraints, and attachment ecosystem requirements.
- Restaurants:Mid-capacity electric units with modular grinder heads dominate back-of-house specifications where cross-compatibility with existing slicer and mixer platforms reduces vendor lock-in. Chains prioritize NSF-certified stainless steel configurations to satisfy health department inspection protocols.
- Butcher Shops:Precision cutting assemblies with interchangeable plate perforation diameters support sausage variety production. German and Italian artisanal operators specify hardened steel worm gears engineered to traditional texture specifications.
- Supermarkets:Compact footprint designs suit retail counter layouts where space constraints dominate layout decisions. Equipment refresh programs in US and Italian grocery chains create attach-rate opportunities for grinder-slicer cross-selling.
- Home Users:Manual and small-capacity electric units serve residential kitchens where batch sizes remain limited and capital expenditure thresholds are low.
Restaurants lead on scale; Supermarkets lead on momentum through meat department modernization programs.
Material:
Contact surface composition determines corrosion resistance, cleanability certification, and regulatory acceptance across jurisdictions.
- Stainless Steel:Food-grade 304 and 316 alloys deliver corrosion resistance and clean-in-place compatibility required by FDA food-contact surface regulations. Hospital and institutional catering procurement mandates this material grade exclusively.
- Aluminum:Lightweight housings reduce shipping costs and countertop load requirements for compact electric units. ECHA REACH restrictions on certain alloy compositions in European manufacturing elevate raw material substitution costs for suppliers serving EU markets.
- Plastic:Polymer components reduce unit weight and manufacturing cost for entry-level home user segments. Durability limitations restrict commercial adoption despite price competitiveness.
- Cast Iron:Traditional material retains niche demand among manual mincer collectors and heritage equipment enthusiasts. Seasoned surfaces require maintenance protocols incompatible with modern sanitation standards.
Stainless steel leads on scale; Aluminum faces headwinds from regulatory substitution costs.
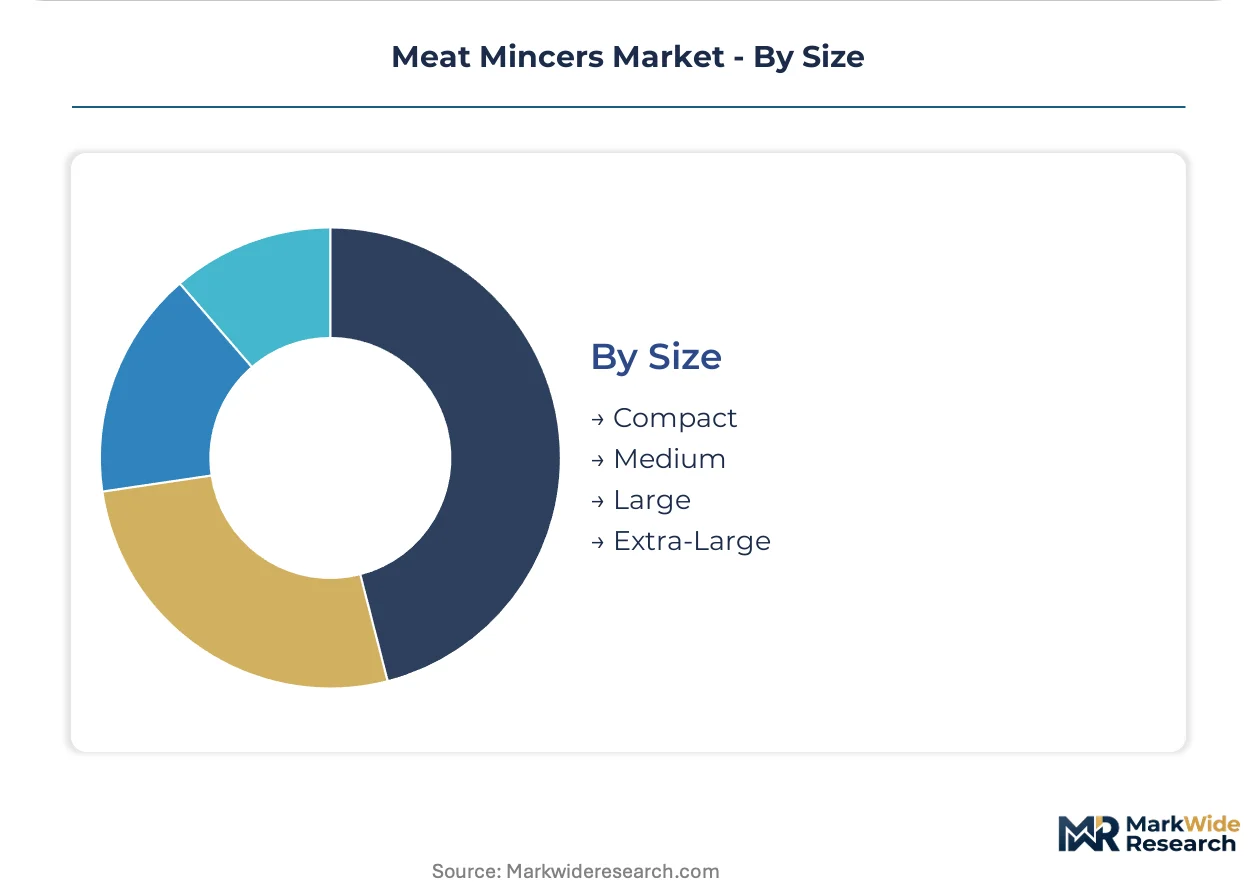
Size:
Physical dimensions and throughput capacity align with workspace constraints and batch volume requirements.
- Compact:Reduced-dimension units preserve counter workflow efficiency in Mediterranean retail counters and small restaurant kitchens. Sirman SpA competes through footprint-optimized designs for space-constrained environments.
- Medium:Balanced capacity-to-footprint ratios serve independent butcher shops and mid-scale restaurant operations. This segment captures the broadest cross-section of commercial demand.
- Large:Elevated throughput rates support central kitchen and commissary operations feeding multiple restaurant locations. Motor base power requirements increase proportionally with auger diameter.
- Extra-Large:Continuous-feed industrial configurations achieve maximum throughput for sausage production facilities and institutional foodservice. Componentized architecture allows grinder head replacement without full-system refresh.
Medium configurations lead on scale; Compact units lead on momentum in urban retail format expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial meat processing machinery originated in Central European metalworking centers during the late nineteenth century, with German and Italian engineering traditions establishing the precision standards that persist in artisanal butchery equipment today. Contemporary demand geography reflects this manufacturing heritage alongside North American commercial kitchen scale.
Germany
Artisanal sausage traditions sustain specification demand for precision-ground worm gear assemblies in Bavaria and Baden-Württemberg. CE marking under the EU Machinery Directive mandates emergency-stop integration and guarding specifications that elevate engineering compliance costs. The Stuttgart industrial cluster anchors production of hardened steel cutting components engineered to traditional emulsion stability requirements.
United States
Restaurant chains and central kitchens specify NSF/ANSI-certified electric units where labor efficiency governs procurement decisions. FDA food-contact surface regulations enforce stainless steel configurations in hospital and institutional catering environments. Chicago and Dallas-Fort Worth metro areas concentrate meat department equipment refresh programs among grocery retail chains.
Italy
Mediterranean retail counter space constraints drive specification demand for compact footprint designs in Lombardy and Emilia-Romagna. ECHA REACH restrictions on certain alloy compositions elevate raw material substitution costs for domestic fabricators. The Bologna machinery district maintains engineering specialization in precision cutting assemblies for traditional cured meat production.
France
Premium meat retail formats in Île-de-France and Auvergne-Rhône-Alpes sustain demand for modular grinder attachment systems. EU Machinery Directive conformity assessment investments reinforce defensive positions against uncertified import competition. Lyon anchors a cluster of stainless steel fabrication specialists serving institutional foodservice procurement.
United Kingdom
Independent butcher shops in London/Southeast and the Midlands specify interchangeable plate perforation diameters for sausage variety production. Post-Brexit regulatory divergence from EU CE marking requirements is extending product certification timelines. Sheffield retains metalworking heritage in hardened tool steel component supply for commercial equipment manufacturers.
Meat Mincers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and material-durability dimensions. The vendor base organizes into three tiers: integrated kitchen equipment platforms with cross-selling ecosystems, precision-engineering specialists serving traditional butchery specifications, and regional fabricators competing on replacement-cycle economics. Two dominant competitive moves are reshaping positioning: modular attachment protocol development to capture component-level refresh demand, and proactive multi-jurisdictional certification investments to construct regulatory moats against uncertified imports.
Within the precision-engineering tier, Paul KOLBE GmbH and Sirman SpA exemplify divergent geographic specializations. Hobart anchors the integrated platform archetype through its commercial kitchen installed base. Braher Internacional occupies a position among Mediterranean-focused fabricators serving space-constrained retail formats. Butcher Boy Machines International LLC represents North American heritage manufacturers with established distribution in central kitchen and institutional segments.
| Leading Market Players |
|---|
| Hobart |
| Paul KOLBE GmbH |
| Braher Internacional |
| Butcher Boy Machines International LLC |
| ITW Food Equipment Group |
| Biro Manufacturing Company |
| Bizerba USA Inc. |
| Sirman SpA |
| Globe Food Equipment |
| Others |
Supply & Pricing Matrix
Backward integration into hardened steel cutting component production anchors margin control for European precision-engineering specialists serving German and Italian artisanal butchery markets. This upstream control over worm gear and cutting assembly manufacturing insulates premium-tier suppliers from ECHA REACH alloy substitution volatility while sustaining pricing power against commodity fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies according to NSF/ANSI certification grade and stainless steel material specification. Premium configurations with clean-in-place compatibility command substantial uplifts in hospital and institutional procurement, while standard electric units face compression from mid-scale fabricators competing on replacement-cycle economics. Home user segments exhibit highest price sensitivity, prioritizing compact electric units over manual heritage alternatives despite durability trade-offs.
Supply Chain Analysis
Freight cost escalation on food-grade stainless steel shipments from German and Italian metalworking clusters is compressing landed costs for North American distributors. Component sourcing draws from hardened tool steel specialists in Sheffield, precision gear manufacturers in Stuttgart, and aluminum housing fabricators in Northern Italy. Single-source vulnerability concentrates in CE-marked motor base assemblies, where EU Machinery Directive compliance investments lock out Asian alternatives. Distribution runs through commercial kitchen equipment distributors with established slicer and mixer account relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The meat mincers market functions as a stable compounder where regulatory certification requirements create persistent defensive moats against import competition and sustain incumbent pricing power.
For Market Incumbents: Cement multi-jurisdictional certification portfolios spanning NSF International, CE marking, and ISO food safety standards to deepen regulatory moats against uncertified Asian imports. Prioritize modular attachment protocol development to capture component-level refresh demand from butcher shops rotating away from full-unit replacement cycles. Investment in clean-in-place compatible stainless steel configurations secures institutional catering procurement mandates. For New Entrants and Emerging Players: Commercial kitchen equipment distributors with established slicer and mixer installed bases represent the most accessible channel for grinder attachment cross-selling without competing head-to-head against integrated platform incumbents. Target Mediterranean supermarket meat departments where compact footprint specifications and space-constrained counter layouts create specification openings absent in saturated North American chain accounts. White-space exists in mid-capacity electric units with simplified CE marking pathways for regional European markets. For Investors and Strategic Acquirers: Roll-up economics work for precision-engineering specialists with captive cutting component manufacturing because ECHA REACH compliance investments and artisanal butchery specification expertise create non-replicable intangible assets. Long-term viability centers on five-to-ten year equipment refresh cycles in commercial foodservice and sustained premium meat retail format expansion in Central Europe. Monitor supermarket meat department modernization program announcements as inflection indicators for grinder-slicer cross-selling attach-rate opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Attachment Protocol Development | Component-level refresh demand from German butcher shops displaces full-unit replacement economics. |
| Multi-Jurisdictional Certification Investment | NSF/ANSI and CE marking compliance locks out uncertified imports from Asian manufacturing hubs. |
| Clean-in-Place Compatibility Engineering | FDA food-contact surface regulations mandate stainless steel configurations in hospital catering procurement. |
| Compact Footprint Design Specialization | Sirman SpA demonstrates attach-rate potential in Mediterranean retail counter space-constrained environments. |
| Backward Integration into Cutting Components | Paul KOLBE GmbH's captive worm gear production insulates margins from ECHA REACH alloy volatility. |
Research Methodology
Bottom-up butcher shop and supermarket meat department modeling reconciled against top-down commercial kitchen equipment manufacturer production tracking forms the analytical core of this study. Primary interviews with equipment procurement managers at restaurant chains, maintenance directors at institutional foodservice operators, and aftermarket service heads at commercial kitchen distributors combined with secondary validation from NSF International certification databases, FDA food-contact surface regulation filings, and EU Machinery Directive conformity assessment records. Trade data from German and Italian metalworking export statistics and US commercial foodservice equipment import records anchored supply-side triangulation.
Historical trendline analysis of equipment refresh cycles across restaurant chain capital expenditure disclosures and supermarket meat department modernization program announcements established baseline growth patterns. Segmentation modeling incorporated product type, end user facility category, material specification grade, and physical size dimensions alongside regional regulatory cluster differentiation. CAGRs derived from fitted trend extrapolation adjusted for alloy cost volatility and certification timeline compression effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA REACH regulatory expansion, stainless steel commodity price swings, and modular attachment ecosystem standardization trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
North America Bacon Market
Meat Products
Global Edible Meat Market
Meat Products
Organic Pork Market
Meat Products
Organic Chicken Market
Meat Products
Meat Ingredients Market
Meat Products
Mexico Meat Products Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Antibiotic Free Meat Market
Meat Products
Meat Flavors Market
Meat Products
Pork Flavors Market
Meat Products
United States Frozen Meat Market
Meat Products
France Meat Products Market
Meat Products
Canned Chicken Market
Meat Products
US Meat Market
Meat Products
Ham Slicers Market