
 United States Frozen Meat Market | 2026-2036
United States Frozen Meat Market Size, Share, and Industry Trends Forecast 2026-2036
United States Frozen Meat Market Intelligence
Plant-based protein formulations are shifting partial share in processed frozen meat alternatives, though animal protein retains cost advantages in bulk food service. Tyson Foods sustains vertical integration across feedlot-to-retail operations, controlling upstream supply security. Cargill Meat Solutions Corporation leverages advanced blast-freezing and portion-control technology to anchor margins in institutional channels. JBS USA Holdings, Inc. competes through scale concentration in beef and pork processing complexes.
Frozen meat comprises animal protein preserved at sub-zero temperatures to halt microbial activity and enzymatic degradation, typically held at minus eighteen degrees Celsius or below through controlled blast or cryogenic freezing processes. The category serves commercial food preparation, retail grocery, and institutional feeding operations requiring extended shelf stability without continuous refrigeration infrastructure. Beef commands the largest product type position due to sustained quick-service restaurant demand and centralized patty production. Online retail distribution is expanding fastest among channels as direct-to-consumer fulfillment infrastructure matures. Vacuum seal packaging dominates margin pools through extended shelf-life premiums and reduced spoilage rates in food service procurement.
USDA-FSIS inspection protocols and HACCP mandates govern slaughter, processing, and labeling standards across interstate commerce, raising compliance costs for smaller processors while consolidating volume at federally inspected facilities. FDA oversight of refrigerated warehouse sanitation under the Food Safety Modernization Act shapes cold-chain infrastructure investment requirements. Stakeholders must monitor evolving FSIS pathogen reduction performance standards and state-level cage-free sourcing mandates as these regulations reshape procurement specifications and supplier qualification thresholds.
Market Dynamics
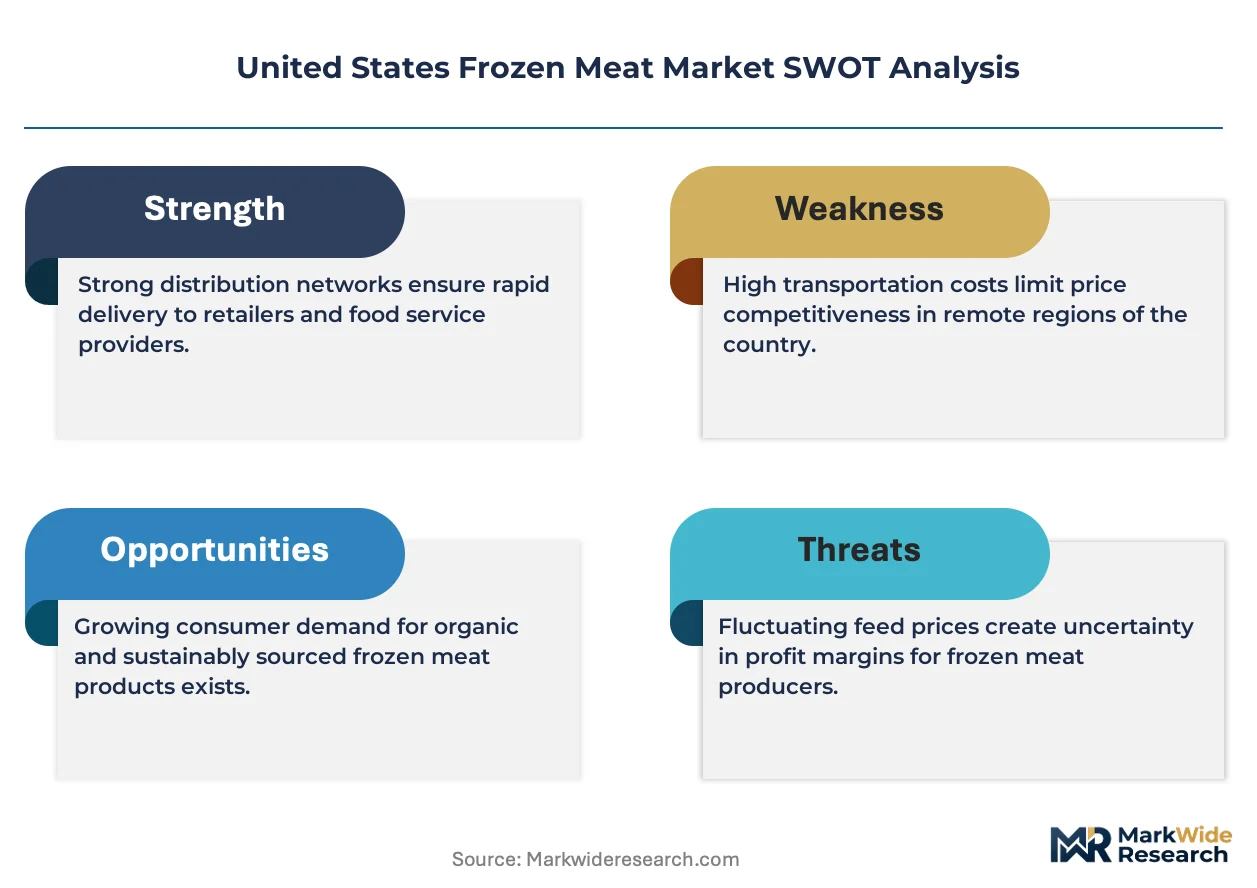
Blast-freezing technology upgrades and USDA-FSIS inspection modernization are compressing margins for smaller processors while concentrating volume at federally inspected facilities across Texas and the Great Plains.
Growth Catalysts
- Quick-service restaurant procurement:Chains are expanding frozen protein orders as labor costs rise and centralized patty production reduces kitchen preparation time.
- USDA-FSIS inspection modernization:Updated protocols streamline interstate commerce approval, accelerating throughput at high-volume beef processing complexes.
- Cryogenic freezing adoption:Advanced rapid-freeze systems preserve cellular structure in premium cuts, opening institutional channel penetration for portion-controlled proteins.
Market Restraints
- Feedlot input cost volatility:Corn and soybean meal price swings compress processor margins during contract renegotiation cycles with institutional buyers.
- Texas supply concentration risk:Beef processing capacity clustering around Dallas-Fort Worth creates single-point-of-failure exposure during extreme weather events.
- Plant-based protein substitution:Formulated alternatives capture share in processed frozen meat segments where taste differentiation narrows.
Strategic Opportunities
- Online retail channel expansion:Direct-to-consumer fulfillment infrastructure maturation enables regional processors to bypass traditional distributor markups.
- Food Safety Modernization Act compliance services:Cold-chain infrastructure investment requirements create ancillary revenue streams for warehouse sanitation technology providers.
- Vacuum seal packaging premiumization:Extended shelf-life technology captures margin pools in food service procurement through reduced spoilage rates.
Industry Challenges
- HACCP certification timeline compression:Smaller processors face extended qualification periods for federal inspection compliance, delaying market entry.
- Blast-freezing capex intensity:Equipment upgrades for pathogen reduction performance standards require capital deployment that strains mid-tier operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Frozen Meat Market |
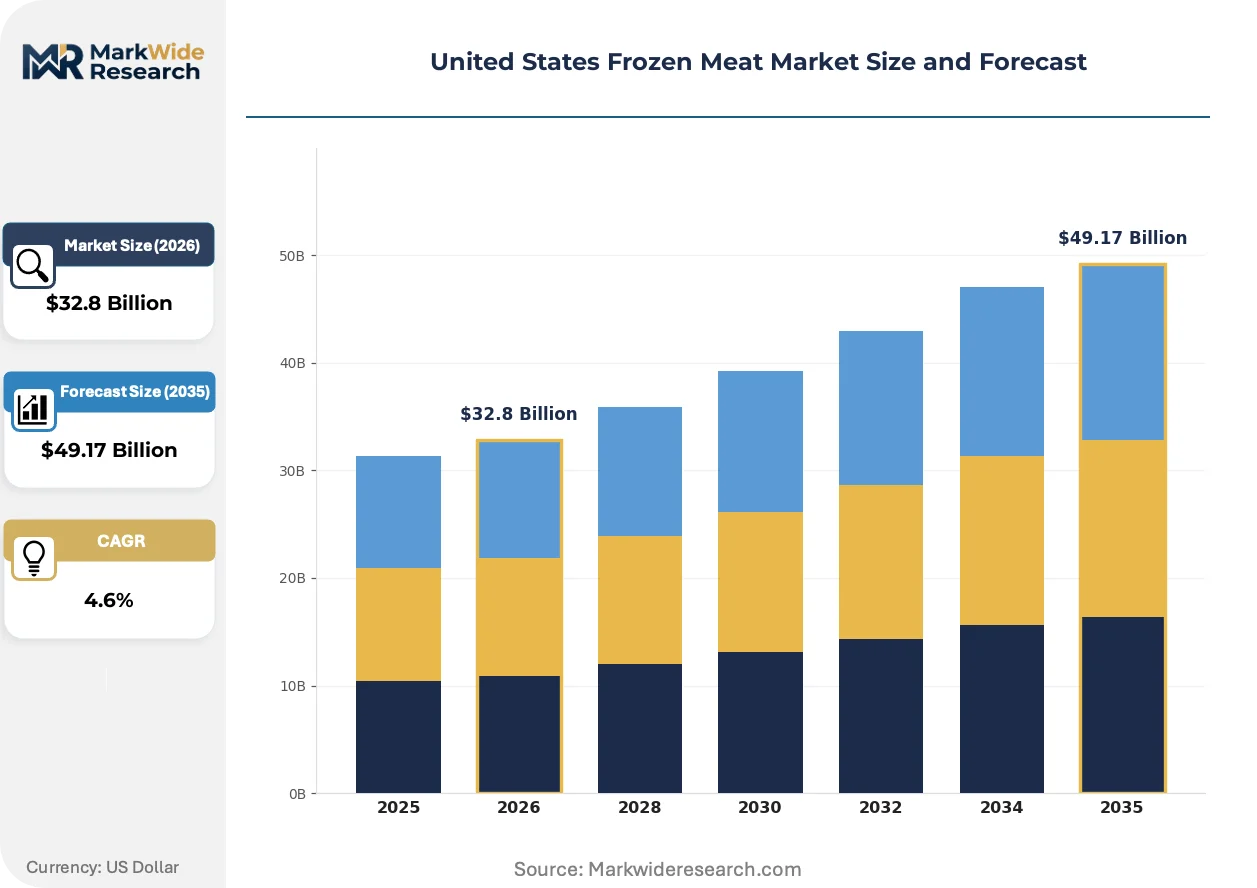
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Chicken, Pork, Seafood Distribution Channel: Online Retail, Supermarket, Convenience Store, Wholesale End User: Restaurants, Households, Food Service, Catering Packaging Type: Vacuum Seal, Tray Pack, Bulk Pack, Retail Pack |
| Companies Covered | Hormel Foods Corporation, Smithfield Foods Inc., Tyson Foods, Inc., Perdue Farms Inc., Pilgrim's Pride Corporation, Conagra Brands, Inc., Cargill Meat Solutions Corporation, Foster Farms Inc., JBS USA Holdings, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Frozen Meat Market Strategic Shifts & Innovations
Technology convergence, regulatory tightening, and procurement model evolution are restructuring competitive positioning across frozen meat supply chains.
Blast-freezing with integrated portion-control automation is decentralizing production location decisions for institutional buyers. Hospital and school district food service directors are adopting cryogenic systems that enable on-site finishing from bulk-frozen primal cuts. This technology is decentralizing the historical advantage of centralized patty production facilities, allowing regional processors to compete for contracts previously captured by national suppliers.
USDA-FSIS pathogen reduction performance standards are tightening microbial testing protocols for ground beef and poultry processing. The industrial consequence is forced consolidation of slaughter operations at facilities with in-house laboratory capacity. Beef grinding operations in Nebraska and Kansas are most affected, responding by integrating testing infrastructure or exiting interstate commerce for state-inspected local markets.
Food service procurement through cooperative purchasing organizations is compressing vendor qualification cycles for frozen protein suppliers. K-12 districts and correctional facilities are aggregating demand through shared services alliances, displacing individual district RFP processes. This concentration is most visible in the Southwest, where Texas Education Agency-affiliated cooperatives now handle protein sourcing for hundreds of independent school districts.
United States Frozen Meat Market Segmentation
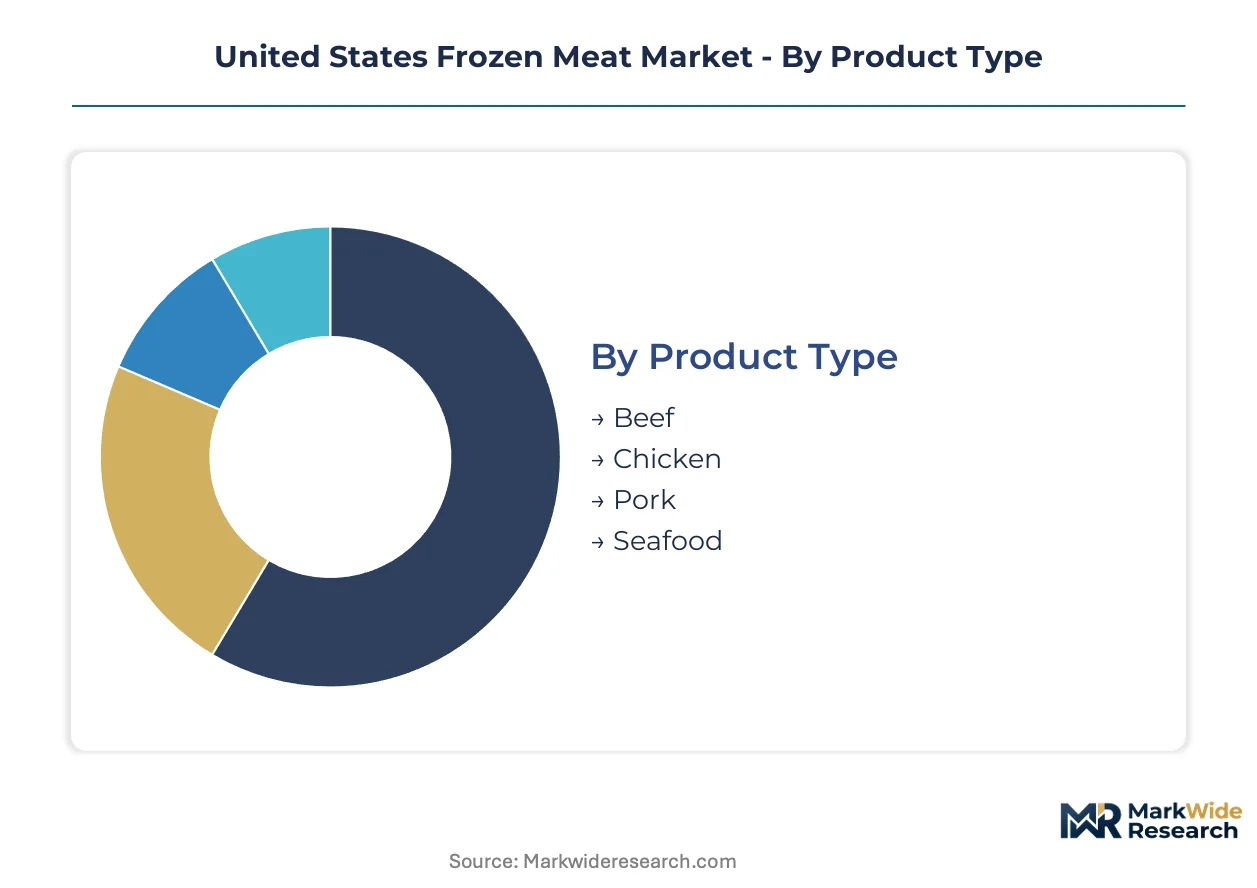
Frozen meat procurement patterns diverge sharply across customer types, with institutional buyers prioritizing portion control and shelf stability while household consumers weigh convenience against per-unit cost. Understanding these segment boundaries clarifies where technology investments and compliance resources generate differentiated returns.
Product Type:
Protein selection tracks directly to end-use cooking method and price elasticity, with quick-service operators driving volume in ground formats and premium cuts serving white-tablecloth channels.
- Beef:Ground beef and patty formats dominate institutional procurement, with USDA-FSIS-inspected grinding operations in Nebraska and Texas supplying quick-service restaurant chains. Demand concentrates in the Dallas-Fort Worth corridor, where interstate distribution infrastructure reduces freight costs to Southwest markets.
- Chicken:Portion-controlled breast and thigh cuts serve K-12 districts through cooperative purchasing organizations, with cryogenic freezing preserving cellular structure for on-site finishing. Blast-freezing technology upgrades at Georgia and Arkansas processing complexes tighten pathogen compliance.
- Pork:Processed bacon and sausage formats anchor breakfast daypart menus across correctional and hospital food service.
- Seafood:IQF shrimp and whitefish fillets supply regional distributors serving landlocked states with limited fresh catch access.
Volume sits with Beef; growth tilts toward Chicken as white-meat preference expands in institutional feeding.
Distribution Channel:
Channel selection determines margin capture, with direct fulfillment bypassing distributor markups while traditional retail maintains reach in cost-sensitive geographies.
- Online Retail:Direct-to-consumer fulfillment infrastructure enables regional processors to ship portion-controlled proteins outside traditional wholesale networks, with vacuum-sealed packaging extending transit viability.
- Supermarket:Retail pack formats dominate household procurement in suburban and rural markets where cold-chain continuity varies.
- Convenience Store:Single-serve and small-format packs serve travel corridor demand and food desert access points.
- Wholesale:Bulk pack configurations supply independent restaurants and catering operations through broadline distributors.
Supermarket channels retain volume dominance; Online Retail climbs fastest as fulfillment density matures in metropolitan corridors.
End User:
End-user category dictates specification stringency, with federal feeding programs enforcing pathogen standards that exceed typical commercial requirements.
- Restaurants:Quick-service chains centralize patty production to reduce kitchen labor, sourcing blast-frozen ground beef from federally inspected Texas and Great Plains facilities.
- Households:Retail pack and tray pack formats serve home preparation, with vacuum seal premiums capturing margin in suburban markets.
- Food Service:Hospital and school district directors adopt cryogenic systems for on-site finishing from primal cuts, displacing historical reliance on centralized patty facilities.
- Catering:Bulk pack procurement supports event-volume preparation with flexible portioning requirements.
Restaurants generate the largest throughput; Food Service shows steepest expansion trajectory as institutional procurement consolidates through cooperative purchasing.
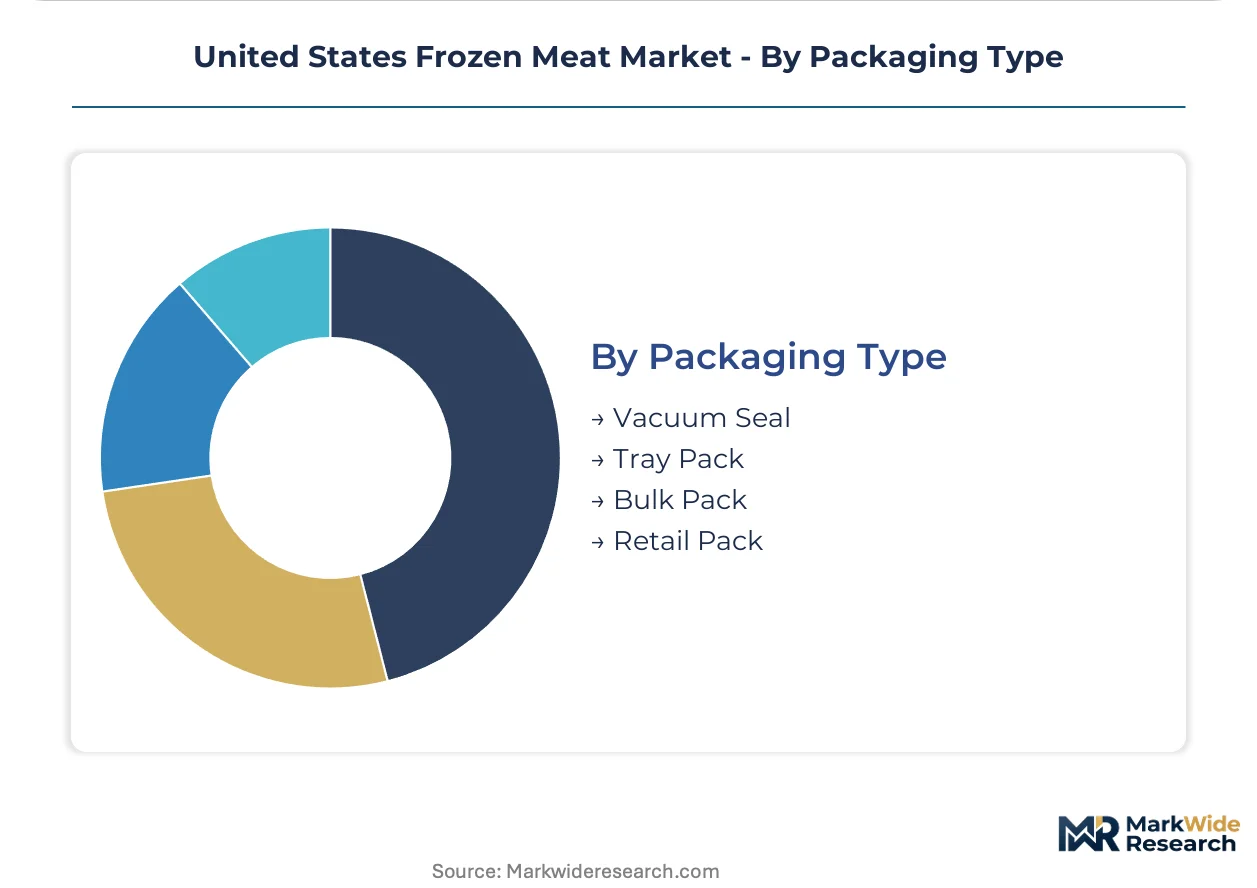
Packaging Type:
Packaging technology governs shelf-life extension and spoilage reduction, with premium formats capturing margin pools in food service channels where waste carries contract penalties.
- Vacuum Seal:Oxygen-barrier films extend frozen shelf life while reducing freezer burn incidence, commanding price premiums in institutional procurement where inventory turns are slower.
- Tray Pack:Modified atmosphere packaging serves retail display requirements with consumer-facing presentation.
- Bulk Pack:Poly-lined corrugated configurations minimize per-pound packaging cost for high-volume food service and catering accounts.
- Retail Pack:Branded consumer formats with cooking instructions and nutritional labeling serve household decision-making.
Vacuum Seal captures the highest margin per pound; Retail Pack maintains widest household penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and institutional food service operators concentrate procurement in Texas and the Great Plains, where interstate distribution infrastructure and federally inspected processing capacity cluster around logistics corridors.
Texas
Beef processing capacity concentrates in the Dallas-Fort Worth logistics corridor, serving quick-service restaurant chains with blast-frozen ground beef and portion-controlled proteins. USDA-FSIS inspection modernization accelerates throughput at high-volume facilities while tightening compliance requirements for smaller operators. Interstate distribution infrastructure reduces freight costs to Southwest markets, anchoring procurement decisions for national chains.
Nebraska
Beef grinding operations supply ground beef formats to institutional channels under updated pathogen reduction performance standards. USDA-FSIS mandates force consolidation at facilities with in-house laboratory capacity, displacing state-inspected operations toward local markets. Processing complexes in the eastern half of the state integrate testing infrastructure to maintain interstate commerce eligibility.
Kansas
Cattle feeding and processing operations face margin compression from feedlot input cost volatility during contract renegotiation cycles. USDA-FSIS protocols govern slaughter and labeling standards, raising qualification thresholds for supplier status. Western Kansas facilities cluster around rail and highway corridors connecting to Texas distribution networks.
Georgia
Poultry processing complexes supply portion-controlled chicken cuts to K-12 districts through cooperative purchasing organizations. Blast-freezing technology upgrades tighten pathogen compliance for institutional contracts. The state's processing infrastructure serves Southeastern food service demand with cryogenic freezing preserving cellular structure for on-site finishing.
Arkansas
Chicken processing operations support regional distribution to school districts and hospital food service directors adopting decentralized procurement models. USDA-FSIS inspection governs interstate shipment eligibility for frozen poultry products. Processing facilities align with cooperative purchasing organization specifications to capture institutional volume.
United States Frozen Meat Market Key Industry Players
Capacity expansion dominates the current landscape as federally inspected facilities absorb volume displaced by compliance-driven consolidation. The market structure concentrates around vertically integrated protein processors and specialized poultry operators, with mid-tier regional processors occupying niche positions in state-inspected local channels. Two strategic archetypes prevail: scale-driven national suppliers controlling upstream feedlot-to-retail operations, and technology-focused operators leveraging advanced blast-freezing and portion-control systems. Competitive moves center on M&A activity to secure processing capacity and strategic partnerships with cooperative purchasing organizations to anchor institutional volume.
Among US-based protein processors, Tyson Foods, Inc. and Cargill Meat Solutions Corporation exemplify scale-driven national archetypes, while JBS USA Holdings, Inc. represents foreign-owned consolidation within domestic beef and pork processing. These entities occupy positions defined by upstream supply security and technology deployment in institutional channels.
| Leading Market Players |
|---|
| Hormel Foods Corporation |
| Smithfield Foods Inc. |
| Tyson Foods, Inc. |
| Perdue Farms Inc. |
| Pilgrim's Pride Corporation |
| Conagra Brands, Inc. |
| Cargill Meat Solutions Corporation |
| Foster Farms Inc. |
| JBS USA Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
Cryogenic freezing adoption across institutional channels is compressing per-unit processing economics while redistributing margin capture toward technology-equipped facilities in Texas and the Great Plains. This equipment transition simultaneously raises capital barriers for smaller operators and concentrates pricing power among federally inspected complexes with integrated portion-control automation.
Pricing Analysis
Volume throughput in ground beef and patty formats operates on thin margins anchored to commodity input costs, while premium cryogenic-processed cuts command substantial markups through cellular-structure preservation. Price differentiation separates vacuum-sealed institutional packs from standard tray-pack retail formats, with certification tier and geographic freight advantage driving variance. Pricing pressure stems from feedlot input cost volatility during corn and soybean meal contract cycles. Quick-service restaurant chains exhibit highest price sensitivity due to centralized procurement scale, while hospital food service directors accept premiums for extended shelf-life specifications.
Supply Chain Analysis
Corn and soybean meal supply rests on Midwest grain belt production, with protein processing equipment sourcing concentrated in Germany, Japan, and domestic fabrication facilities. Live cattle supply draws from Texas Panhandle and Nebraska feedlot operations, while cryogenic freezing systems import specialty gases and precision engineering components. Single-source vulnerability concentrates in Dallas-Fort Worth logistics corridor exposure to extreme weather disruption. Distribution runs through interstate cold-chain networks anchored at federally inspected facilities, with cooperative purchasing organizations consolidating downstream demand aggregation for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States frozen meat market is transitioning from centralized patty production toward decentralized cryogenic finishing systems, with blast-freezing technology replacing legacy blast-cell infrastructure across institutional procurement channels.
For Market Incumbents: To counter plant-based protein substitution in processed segments, Tyson Foods and JBS USA Holdings should deepen backward integration into feedlot operations securing upstream supply stability, while accelerating USDA-FSIS laboratory certification investments to maintain interstate commerce eligibility against tightening pathogen standards.
For New Entrants and Emerging Players: Capture online retail channel expansion through direct-to-consumer fulfillment infrastructure bypassing traditional distributor markups, targeting metropolitan corridors with vacuum-sealed portion-controlled products. White-space opportunity concentrates in regional cooperative purchasing organization contracts for K-12 districts seeking alternative suppliers to national incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier processors possessing USDA-FSIS inspection certification and cryogenic equipment capacity given regulatory-driven consolidation tailwinds. Long-term viability favors facilities with integrated laboratory testing and portion-control automation. Watch state-level cage-free sourcing mandate adoption as procurement specification inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Freezing Capacity Expansion | Advanced rapid-freeze systems preserve cellular structure, opening institutional penetration for premium portion-controlled proteins. |
| USDA-FSIS Laboratory Certification Investment | In-house testing infrastructure maintains interstate commerce eligibility under tightening pathogen reduction performance standards. |
| Cooperative Purchasing Organization Partnership | Shared services alliances aggregate K-12 and correctional demand, displacing individual district RFP processes. |
| Direct-to-Consumer Fulfillment Infrastructure | Online retail channel maturation enables regional processors to bypass traditional broadline distributor markups. |
| Upstream Feedlot Integration | Captive supply of live cattle hedges against corn and soybean meal input cost volatility during contract cycles. |
Research Approach
Multi-period observation of USDA-FSIS inspection modernization timelines, cryogenic freezing equipment deployment rates, and cooperative purchasing organization contract awards anchored the trend analysis, supplemented by interviews with quick-service restaurant procurement directors, hospital food service administrators, K-12 district nutrition coordinators, beef processing plant managers, and cold-chain logistics operators. Secondary validation drew from USDA Agricultural Marketing Service data, FDA Food Safety Modernization Act implementation records, state agriculture department inspection reports, and interstate commerce freight flow databases. Bottom-up facility capacity modeling triangulated against top-down protein consumption projections.
Segment-weighting across product type, distribution channel, end user, and packaging technology dimensions structured the analytical framework across the analysis window. CAGRs were derived from trend extrapolation calibrated to historical procurement pattern shifts and technology adoption S-curves. Forecast inputs incorporated feedlot capacity utilization rates, blast-freezing equipment replacement cycles, and cooperative purchasing organization membership growth trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to feedlot input cost volatility, extreme weather disruption of Texas logistics corridors, and plant-based protein formulation advances narrowing taste differentiation. A small set of triggers—USDA-FSIS pathogen standard revisions, state cage-free mandate adoption, and cryogenic equipment cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Animal Protein Market
Meat Products
United States Processed Pork Meat Market
Meat Products
GCC Edible Meat Market
Meat Products
Beef Bouillon Market
Meat Products
Meat Flavors Market
Meat Products
Poultry Processing Meat Market
Meat Products
Rendered Poultry Products Market
Meat Products
Meat Market
Meat Products
Organic Pork Market
Meat Products
Meat Paste Market
Meat Products
Organic Beef Meat Market
Meat Products
Reduced Fat Meat Market
Meat Products
Low Fat Sausage Market
Meat Products
South Africa Processed Meat Market
Meat Products
North America Canned Meat Market
Meat Products
Beef Extract Market