
 Global Edible Meat Market | 2026-2036
Global Edible Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Edible Meat Market Foresight
Precision fermentation and cell-culture scaffolding is narrowing the cost gap between conventional slaughter and alternative protein production methods. Tyson Foods Inc leverages its integrated feedlot-to-retail infrastructure to control input costs across North American operations. JBS S.A. anchors its global position through dominant beef processing capacity in Brazil and Australian export corridors. Cargill Incorporated sustains margins via captive grain supply chains that buffer against feed price volatility.
Edible meat comprises skeletal muscle tissue and associated fat from domesticated livestock and game species, typically processed to achieve specific pH levels, moisture retention, and microbial safety thresholds for human consumption. Fresh and frozen processing methods retain the largest volume share, though cured and smoked segments command premium pricing through extended shelf-life protocols. Poultry leads product type volumes due to favorable feed conversion ratios, while beef and pork concentrate margin pools in premium grading tiers. Foodservice outlets and supermarkets represent the dominant distribution channels, with online retailers gaining traction in urban fulfillment networks.
FDA oversight of slaughter and processing facilities, USDA grading standards for quality and yield, and EU REACH chemical safety protocols collectively shape product specifications and market access conditions across major trade corridors. The EU Green Deal's methane reduction targets are forcing processors to document supply chain emissions or risk exclusion from European import quotas. Stakeholders must monitor evolving carbon border adjustment mechanisms and alternative protein parity points to time capital allocation between conventional capacity and biotech-enabled production platforms.
Market Dynamics
The EU Green Deal's methane reduction mandates are compressing operating margins for conventional processors while accelerating capital flows toward biotech-enabled production platforms. This regulatory pressure is restructuring procurement relationships across the value chain.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:The EU Green Deal's binding emissions documentation requirements are redirecting import volumes toward certified low-carbon suppliers, creating preferential market access for compliant processors.
- Precision fermentation cost curves:Cell-culture scaffolding technologies are narrowing unit economics against conventional slaughter methods, pulling institutional investment into alternative protein capacity expansion.
- Brazilian export corridor concentration:JBS S.A. and integrated processors in Brazil command refrigerated logistics networks that lock in Asian and Middle Eastern offtake agreements.
Market Restraints
- Feed grain price volatility:Cargill Incorporated's captive grain supply chains buffer margin erosion, but independent processors face soybean and corn input swings that compress quarterly earnings.
- Single-origin supply concentration:Australian beef export capacity bottlenecks through limited port refrigeration infrastructure, exposing buyers to shipment delays during climate disruptions.
- Cell-culture technical limitations:Scaffolding material costs and serum-free media formulations remain unresolved at commercial scale, delaying price parity timelines for lab-grown alternatives.
Strategic Opportunities
- Underpenetrated Indian foodservice:Quick-service restaurant chains in India are expanding protein procurement volumes faster than domestic supply can match, creating import substitution openings for frozen poultry exporters.
- Carbon border adjustment mechanisms:The EU's CBAM framework rewards documented low-emission supply chains, advantaging early movers who invest in lifecycle tracking infrastructure.
- Direct-to-retailer channel innovation:E-commerce fulfillment networks in urban China are bypassing traditional wholesale layers, allowing processors to capture margin previously allocated to distributors.
Industry Challenges
- Microbiological safety certification timelines:HACCP protocol validation and third-party audit backlogs delay facility approvals, freezing capital in pre-revenue assets for 12-18 month cycles.
- Legacy ERP integration friction:Blockchain traceability systems for EU compliance require retrofitting into decades-old slaughterhouse inventory platforms, multiplying implementation costs.
- Bioprocess engineering talent scarcity:Cell-culture meat facilities compete with pharmaceutical manufacturers for the same fermentation specialist labor pools, inflating compensation benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Edible Meat Market |
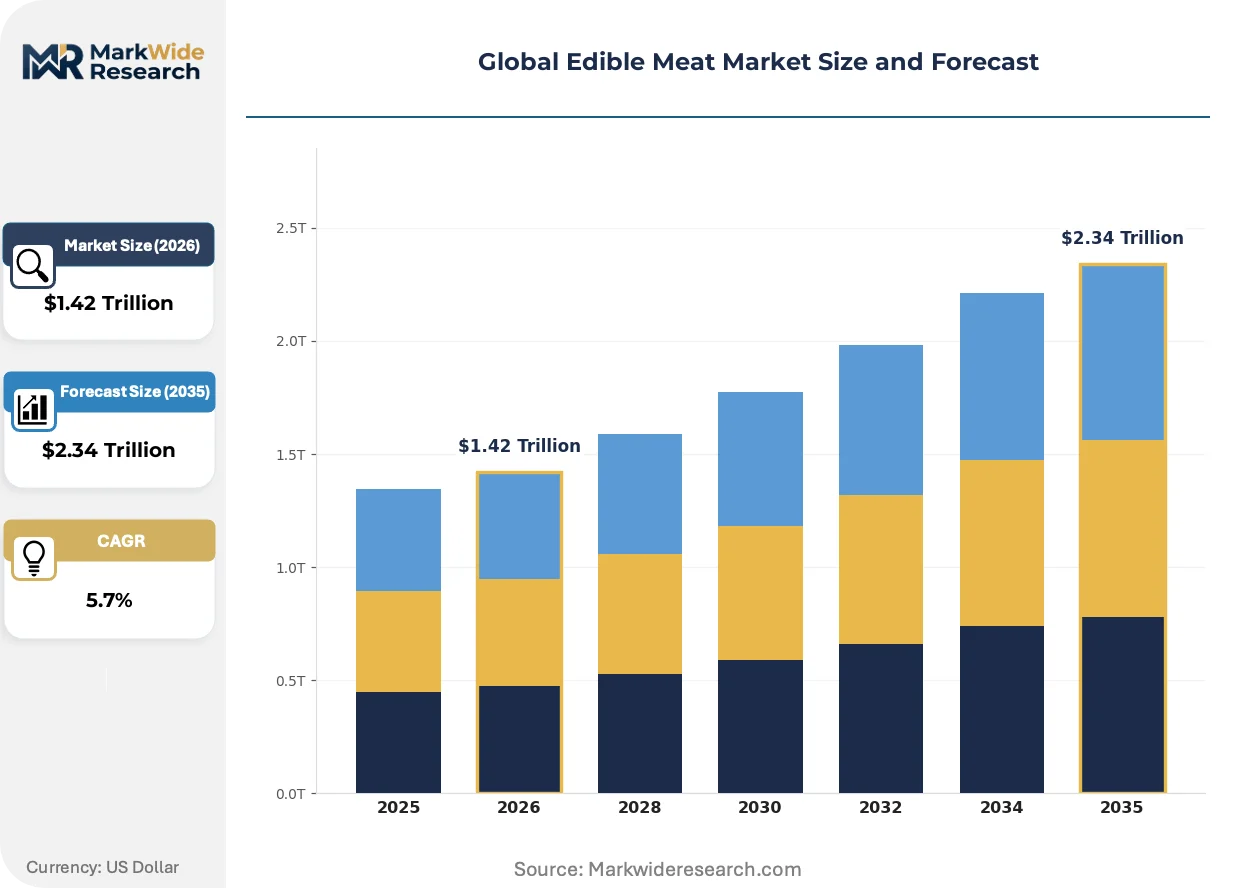
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.34 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb, Goat, Game Meat Processing Method: Fresh, Frozen, Cured, Smoked, Cooked, Dried Distribution Channel: Supermarkets, Butcher Shops, Convenience Stores, Online Retailers, Foodservice Outlets End User: Households, Hotels & Restaurants, Catering Services, Institutional Buyers |
| Companies Covered | WH Group Limited, Smithfield Foods Inc., Tyson Foods Inc, Conagra Brands Inc., Hormel Foods Corporation, JBS S.A., Pilgrim's Pride Corporation, Danish Crown A/S, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Edible Meat Market Shifts & Advancements
Alternative protein production platforms are migrating from pilot-scale demonstration to industrial-grade deployment, forcing incumbent processors to defend margin pools through supply chain restructuring rather than volume expansion alone.
Precision fermentation scaffolding is migrating from pharmaceutical-grade bioreactor configurations to commodity-scale meat analog production. Quick-service restaurant chains in Western Europe are piloting hybrid menu formulations that blend cultivated fat with plant protein bases. This technology migration is compressing the cost gap against conventional beef trimmings in ground meat applications.
REACH chemical safety protocols are tightening residue limits for antimicrobial compounds used in poultry processing. The European Chemicals Agency's updated hazard classifications are forcing Brazilian and Thai exporters to reformulate sanitation protocols or risk quota suspensions. Premium grading tiers face the steepest compliance cost escalation as traceability documentation requirements multiply.
Foodservice procurement patterns are consolidating around long-term offtake contracts with embedded carbon accounting clauses. Hotel and restaurant groups in Singapore and the UAE are replacing spot-market purchasing with three-year supply agreements that specify emissions thresholds per kilogram. This contractual shift is displacing traditional commodity traders from high-value protein sourcing relationships.
Global Edible Meat Market Segmentation
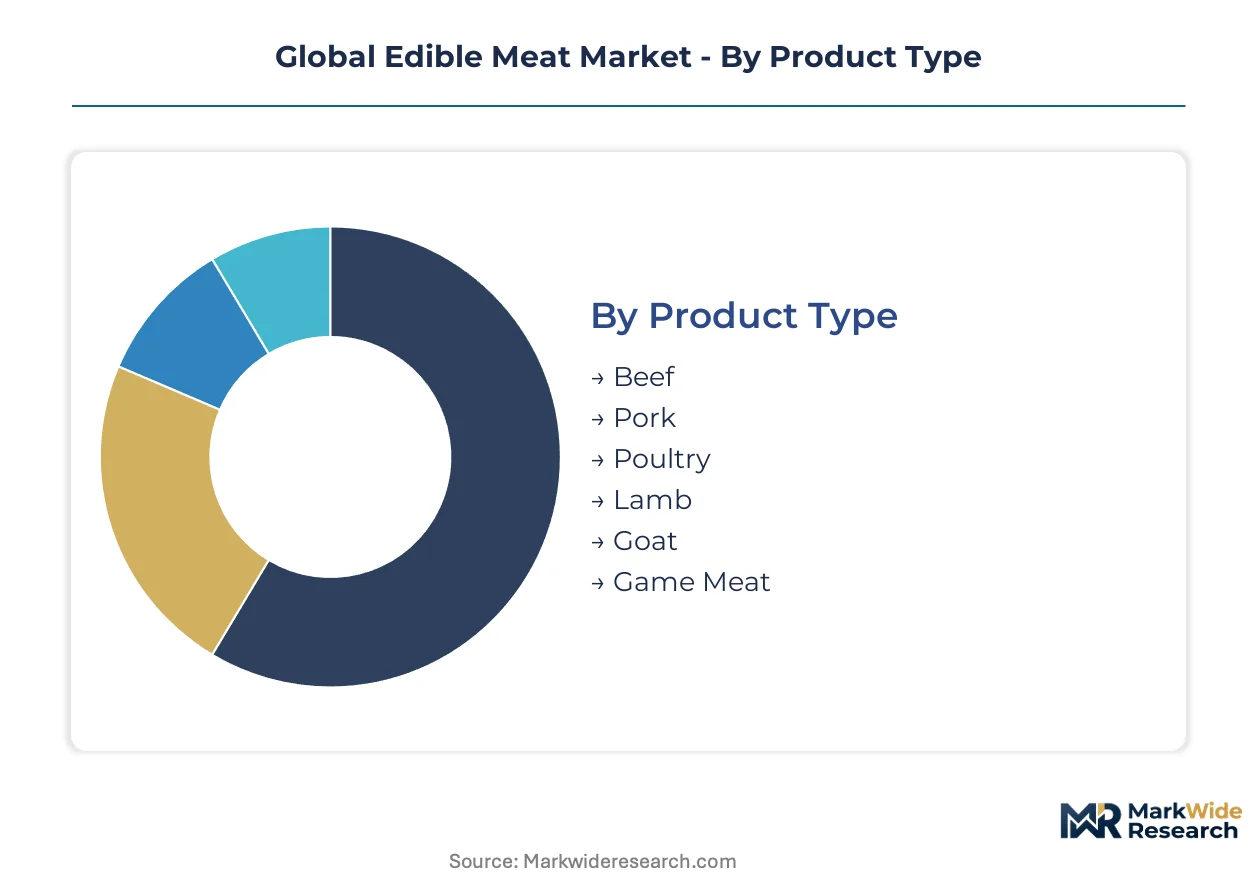
Protein procurement patterns diverge sharply across species and processing tiers, with feed conversion economics and shelf-life protocols determining margin capture. Distribution channel selection locks processors into distinct working capital cycles and traceability compliance burdens.
Product Type:
Mature segments dominate volume throughput while emerging categories reshape premium positioning through niche export channels.
- Poultry:Superior feed conversion ratios and shorter production cycles compress unit costs below ruminant alternatives. Quick-service restaurant chains in India and Southeast Asia concentrate procurement here, though avian influenza surveillance protocols in the EU and China periodically disrupt supply continuity.
- Beef:Extended finishing periods and grain-intensive feeding elevate input costs, yet marbling-graded cuts command substantial premiums in Japanese and Middle Eastern import markets. JBS S.A. and Tyson Foods Inc anchor global supply through Brazilian and North American feedlot networks.
- Pork:High litter sizes and efficient protein accretion sustain cost competitiveness across East Asian consumption clusters.
- Lamb:Seasonal breeding constraints and pasture dependency limit scale, concentrating output in Australian and New Zealand export corridors.
- Goat:Low-input foraging requirements suit smallholder production in South Asia and Sub-Saharan Africa, with limited formal trade infrastructure.
- Game Meat:Wild-harvest and farmed venison segments serve specialty retail and hospitality channels in Germany, France, and Nordic markets.
Poultry handles the majority of throughput; beef is the fastest mover on share in premium grading tiers.
Processing Method:
Cost tier stratification separates commodity-scale operations from value-added facilities requiring specialized equipment and extended holding inventory.
- Fresh:Minimal processing preserves native protein structures and flavor profiles, demanding refrigerated logistics with 3-7 day shelf windows. Supermarkets in Germany and France prioritize this format for consumer perception of quality, though spoilage rates compress margins.
- Frozen:Blast-freezing at -18°C halts microbial proliferation and extends distribution radius to intercontinental trade lanes. Brazilian and Australian exporters rely on this method for Asian and Middle Eastern offtake, with containerized reefers locking in temperature integrity.
- Cured:Salt and nitrite applications inhibit pathogen growth while developing characteristic texture and flavor compounds.
- Smoked:Thermal processing with hardwood combustion products creates preservative and organoleptic differentiation for deli and hospitality segments.
- Cooked:Ready-to-eat formats reduce foodservice labor requirements and HACCP liability at point of service.
- Dried:Moisture reduction to water activity thresholds below 0.85 enables ambient storage for military, expedition, and snack applications.
Frozen handles the majority of throughput; cured is expanding most quickly in European premium retail.
Distribution Channel:
Customer type and purchase occasion dictate channel selection, with institutional buyers prioritizing contract reliability over assortment breadth.
- Supermarkets:Multi-temperature display cases and private-label programs concentrate consumer purchasing in urban Brazil, China, and EU member states. Carrefour and Tesco procurement teams negotiate annual volume commitments with specified origin documentation.
- Foodservice Outlets:Hotels and restaurants in Singapore, UAE, and Qatar are replacing spot-market purchasing with multi-year offtake agreements embedding carbon accounting clauses.
- Butcher Shops:Skilled cutting and custom fabrication retain relevance in traditional consumption clusters across Italy, Spain, and Argentina.
- Convenience Stores:Limited assortment and grab-and-go packaging target time-constrained urban consumers in Japan and South Korea.
- Online Retailers:E-commerce fulfillment networks in urban China bypass wholesale layers, with Alibaba and JD.com cold-chain infrastructure enabling direct processor-to-consumer delivery.
Supermarkets handle the majority of throughput; online retailers are gaining share fastest in East Asian metropolitan corridors.
End User:
Volume scale and specification stringency separate household procurement from institutional buyers with embedded compliance requirements.
- Hotels & Restaurants:Protein procurement volumes are expanding in this channel, with quick-service chains in India and quick-casual formats in Western Europe driving specification standardization. Marriott and Hilton sustainability mandates now require documented supply chain emissions per kilogram.
- Households:Retail purchasing decisions in the US, Brazil, and China respond to price promotions and origin labeling, with organic and antibiotic-free claims commanding 15-30% shelf price premiums.
- Catering Services:Event-driven demand concentrates in wedding and corporate hospitality segments across Gulf Cooperation Council states.
- Institutional Buyers:Military, prison, and school feeding programs in the US, UK, and Australia prioritize lowest-compliant-cost procurement through centralized tender processes.
Households handle the majority of throughput; hotels and restaurants are climbing the fastest on procurement volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across major trade corridors, with surplus production regions competing for access to deficit markets tightening carbon documentation requirements. Brazil and Australia maintain structural export surpluses in beef and lamb, while China and the Middle East absorb the majority of seaborne volumes.
Brazil
JBS S.A. and integrated processors command refrigerated logistics networks locking in Asian and Middle Eastern offtake agreements. ANVISA sanitation protocols and EU equivalence agreements shape facility certification timelines for export-authorized plants. The São Paulo-Paraná axis concentrates slaughter capacity, with Mato Grosso feedlots expanding to capture China quota allocations.
United States
Tyson Foods Inc leverages integrated feedlot-to-retail infrastructure controlling input costs across North American operations. USDA grading standards for quality and yield, plus FDA oversight of slaughter facilities, collectively shape product specifications. The Texas Panhandle and Kansas beef corridor anchors fed cattle processing, with Iowa and Arkansas poultry complexes supplying quick-service restaurant chains.
China
Protein procurement volumes concentrate in urban foodservice and e-commerce fulfillment networks bypassing traditional wholesale layers. SAMR food safety regulations and GB standards for refrigerated logistics constrain import facility approvals. Yangtze River Delta cold-chain infrastructure enables direct processor-to-consumer delivery through Alibaba and JD.com platforms.
Germany
EU Green Deal farm-to-fork mandates redirect import volumes toward certified low-carbon suppliers, creating preferential market access for compliant processors. ECHA REACH chemical safety protocols and EFSA residue limits force sanitation protocol reformulation. The North Rhine-Westphalia slaughterhouse cluster faces margin compression from methane reduction documentation requirements.
Australia
Marbling-graded cuts command substantial premiums in Japanese and Middle Eastern import markets, though port refrigeration infrastructure bottlenecks expose buyers to shipment delays. DAWR export certification and EU hormone-free protocols constrain supply eligibility. Queensland and New South Wales feedlot networks anchor beef export capacity, with Victoria lamb processing serving GCC states.
Global Edible Meat Market Competitive Landscape
On the supply side, the industry is consolidating around integrated processors with captive grain supply chains and refrigerated logistics networks spanning multiple continents. Three strategic archetypes dominate: diversified protein conglomerates with feedlot-to-retail integration, regional specialists leveraging geographic origin premiums, and commodity traders with backward integration into grain origination. Competitive moves concentrate on M&A for capacity consolidation and strategic partnerships for carbon accounting infrastructure.
Within the diversified protein tier, JBS S.A., Tyson Foods Inc, and Cargill Incorporated exemplify scale-driven positioning across species and geographies. JBS S.A. anchors its global position through dominant beef processing capacity in Brazil and Australian export corridors. Tyson Foods Inc occupies a position leveraging integrated infrastructure across North American operations. Cargill Incorporated sits within the commodity-trader archetype, sustaining margins via captive grain supply chains that buffer against feed price volatility.
| Leading Market Players |
|---|
| WH Group Limited |
| Smithfield Foods Inc. |
| Tyson Foods Inc |
| Conagra Brands Inc. |
| Hormel Foods Corporation |
| JBS S.A. |
| Pilgrim's Pride Corporation |
| Danish Crown A/S |
| Cargill Incorporated |
| Others |
Supply & Pricing Matrix
Brazilian feedlot concentration and JBS S.A.'s captive cattle supply determine where margin pools accumulate across global beef value chains. Tyson Foods Inc's integrated feedlot-to-retail infrastructure captures pricing power in North American poultry and pork segments, while grain price volatility transmitted through Cargill Incorporated's origination networks reshapes processor cost structures quarterly.
Pricing Analysis
Foodservice procurement teams anchor contract-based long-term offtake pricing with embedded carbon accounting clauses. Price differentiation separates EU Green Deal-certified low-carbon supply from conventional commodity tiers, with marbling-graded beef commanding substantial premiums in Japanese and Middle Eastern import markets. Pricing pressure stems from feed grain volatility compressing processor margins, particularly for independent operators lacking captive grain supply chains. Quick-service restaurant chains in India exhibit highest price sensitivity due to domestic supply shortages, while hotel groups in Singapore and the UAE prioritize contract reliability over unit cost.
Supply Chain Analysis
Integrated processors in Brazil, the United States, and Australia hold dominant slaughter and refrigerated logistics capacity. Raw material flows draw from corn and soybean feed inputs in the Midwest US and Mato Grosso, plus pasture-based cattle finishing in Queensland and New South Wales. Supply chain risk centers on Australian port refrigeration infrastructure bottlenecks exposing buyers to climate-driven shipment delays. Distribution runs through multi-temperature containerized reefers serving Asian and Middle Eastern offtake agreements, with urban China e-commerce fulfillment networks increasingly bypassing wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting and lifecycle traceability services attach to protein procurement contracts faster than conventional slaughter capacity expands, creating recurring revenue layers for compliance infrastructure providers.
For Market Incumbents: Build regulatory compliance moats through early investment in blockchain traceability systems for EU Green Deal methane documentation requirements. Tyson Foods Inc and JBS S.A. should consolidate backward integration into feed grain origination to buffer against input price volatility threatening quarterly margins. Certification investment in hormone-free and antibiotic-free protocols secures preferential access to European and Japanese import quotas. For New Entrants and Emerging Players: Pursue underpenetrated Indian foodservice procurement channels where quick-service restaurant expansion outpaces domestic poultry supply growth. Precision fermentation specialists should target hybrid menu formulation partnerships with Western European quick-service chains blending cultivated fat with plant protein bases. Direct-to-retailer channel innovation in urban China e-commerce fulfillment offers margin capture previously allocated to distributor layers. For Investors and Strategic Acquirers: Capital is best deployed toward integrated processors with captive grain supply chains and refrigerated logistics networks spanning multiple continents. Long-term viability over the coming decade hinges on positioning for carbon border adjustment mechanism compliance rather than volume expansion alone. Monitor EU Green Deal methane reduction target enforcement timelines as inflection indicator for alternative protein parity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Accounting Infrastructure Investment | EU Green Deal compliance documentation creates preferential market access for early movers. |
| Backward Integration into Feed Grain Origination | Cargill Incorporated's captive supply chains buffer margin erosion from input price volatility. |
| Precision Fermentation Scale-Up | Cell-culture scaffolding technologies narrow unit economics against conventional slaughter methods. |
| Direct-to-Retailer Channel Development | Alibaba and JD.com cold-chain infrastructure enables margin capture bypassing wholesale layers. |
| Blockchain Traceability System Deployment | EU REACH and farm-to-fork mandates require retrofitting legacy slaughterhouse inventory platforms. |
Research Methodology
Cross-validation between processor procurement executives and foodservice chain sustainability officers anchors the qualitative findings in operational reality. Primary interviews engaged feedlot operations managers, refrigerated logistics coordinators, EU regulatory affairs specialists, and quick-service restaurant procurement directors across Brazil, the United States, Germany, China, and Australia. Secondary validation drew from ANVISA sanitation protocols, USDA grading standards documentation, EU Green Deal regulatory filings, SAMR food safety regulations, and customs trade data for beef and poultry export volumes. Bottom-up facility capacity assessments triangulate against top-down trade flow analysis.
Calibration against historical trade volumes and processing capacity utilization rates shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include protein species, processing method tier, distribution channel type, and end-user procurement pattern, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from trend extrapolation adjusted for policy intervention timelines and technology cost curve trajectories. Forecast inputs incorporate feed conversion ratio improvements and alternative protein production cost parity milestones.
Sensitivities concentrate around EU methane reduction enforcement intensity, precision fermentation scaffolding material cost breakthroughs, and Australian port infrastructure expansion timelines. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology adoption curves. Quarterly review of EU carbon border adjustment mechanism implementation phases and cell-culture meat commercial scale-up announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Meat-Based FPP Market
Meat Products
Pork Flavors Market
Meat Products
India Poultry Meat Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Hot Dog and Sausages Market
Meat Products
Grass-Fed Meat Market
Meat Products
Oman Poultry Meat Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Meat Flavors Market
Meat Products
Global Lab-Based Meat Market
Meat Products
3D Printed Meat Market
Meat Products
Antibiotic Free Meat Market
Meat Products
Rendered Poultry Products Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Brisket Market
Meat Products
Asia-Pacific Processed Meat Market