
 Ham Slicers Market | 2026-2036
Ham Slicers Market Size, Share, and Industry Trends Forecast 2026-2036
Ham Slicers Market Insights
The capital-intensity divergence between automated and manual equipment specialists is reorganizing competitive dynamics across the ham slicers landscape. Bizerba SE & Co. KG leverages its integrated weighing and slicing platforms to dominate high-throughput supermarket installations. Hobart sustains broad commercial kitchen penetration through extensive service networks and durable build specifications. Sirman competes on compact footprint designs tailored to space-constrained European delis and small restaurants.
Ham slicers are precision cutting machines engineered to deliver uniform slice thickness across variable meat textures, typically employing gravity-fed or horizontal carriage systems with blade diameters ranging from 250 mm to 370 mm and rotational speeds calibrated to prevent protein degradation. Their primary commercial purpose centers on portion control, labor reduction, and presentation standardization in foodservice and retail environments. Electric and automatic units now capture the fastest expansion as labor shortages intensify across restaurants and catering services, while manual slicers retain stubborn share in traditional delis where operator skill constitutes brand identity. Stainless steel dominates material selection for commercial-grade equipment due to sanitation mandates, though composite components gain traction in price-sensitive small-format installations.
The FDA's Food Code provisions on equipment design and cleanability directly shape blade housing geometries and seam minimization in US-bound products, while EU Regulation 1935/2004 on food contact materials governs stainless steel grade certifications and surface roughness parameters for European market access. NSF International standards further segment the market by certifying equipment for specific commercial use categories, creating compliance tiers that manufacturers must navigate. Stakeholders must monitor evolving energy efficiency benchmarks and emerging right-to-repair legislation that could alter blade motor specifications and service access design decisions.
Market Dynamics
Automated slicing capacity expansion in commercial kitchens is compressing manual equipment margins while stainless steel alloy certification requirements under EU and US food safety codes are elevating compliance costs for cross-border suppliers.
Growth Catalysts
- Labor Cost Pressures:Full-service restaurant chains are replacing manual slicing stations with gravity-fed automatic units to reduce kitchen headcount and standardize portion weights across locations.
- EU Regulation 1935/2004:Mandatory food contact material certifications for stainless steel grades are filtering out uncertified suppliers and consolidating demand around verified European manufacturers.
- Blade Motor Efficiency Standards:Energy consumption benchmarks in commercial food equipment are accelerating replacement cycles in high-throughput supermarket deli operations.
Market Restraints
- Nickel Alloy Price Volatility:Surgical-grade 316L stainless steel input costs fluctuate with mining output from Indonesian and Philippine suppliers, squeezing margin predictability for mid-tier equipment builders.
- German Production Cluster Concentration:Precision engineering capabilities for high-tolerance blade assemblies concentrate in Baden-Württemberg and Bavaria, creating geographic supply vulnerability.
- Manual Slicer Substitution Resistance:Traditional European delis and artisanal charcuterie operations treat operator slicing skill as brand differentiation, slowing automatic unit penetration in heritage foodservice segments.
Strategic Opportunities
- Compact Footprint Designs:Space-constrained urban restaurants in Paris, Milan, and Barcelona present unmet demand for vertical carriage systems under 400 mm width.
- Right-to-Repair Legislation:Emerging EU directives on equipment serviceability are creating first-mover advantage for modular blade motor designs with field-replaceable components.
- Cloud-Connected Portion Tracking:Integration of IoT sensors with slicing platforms enables real-time yield analytics for supermarket chains managing shrinkage across multiple deli counters.
Industry Challenges
- Certification Timeline Compression:NSF International category-specific approvals for modified blade housing geometries now require 14-18 month validation cycles, delaying product launches.
- Legacy System Integration:Existing weighing and labeling infrastructure in established supermarket deli departments resists retrofit with new slicing platform data protocols.
- Precision Grinding Skill Scarcity:Blade edge geometry specialists capable of maintaining 0.3 mm thickness tolerance across variable meat textures command premium wages in manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ham Slicers Market |
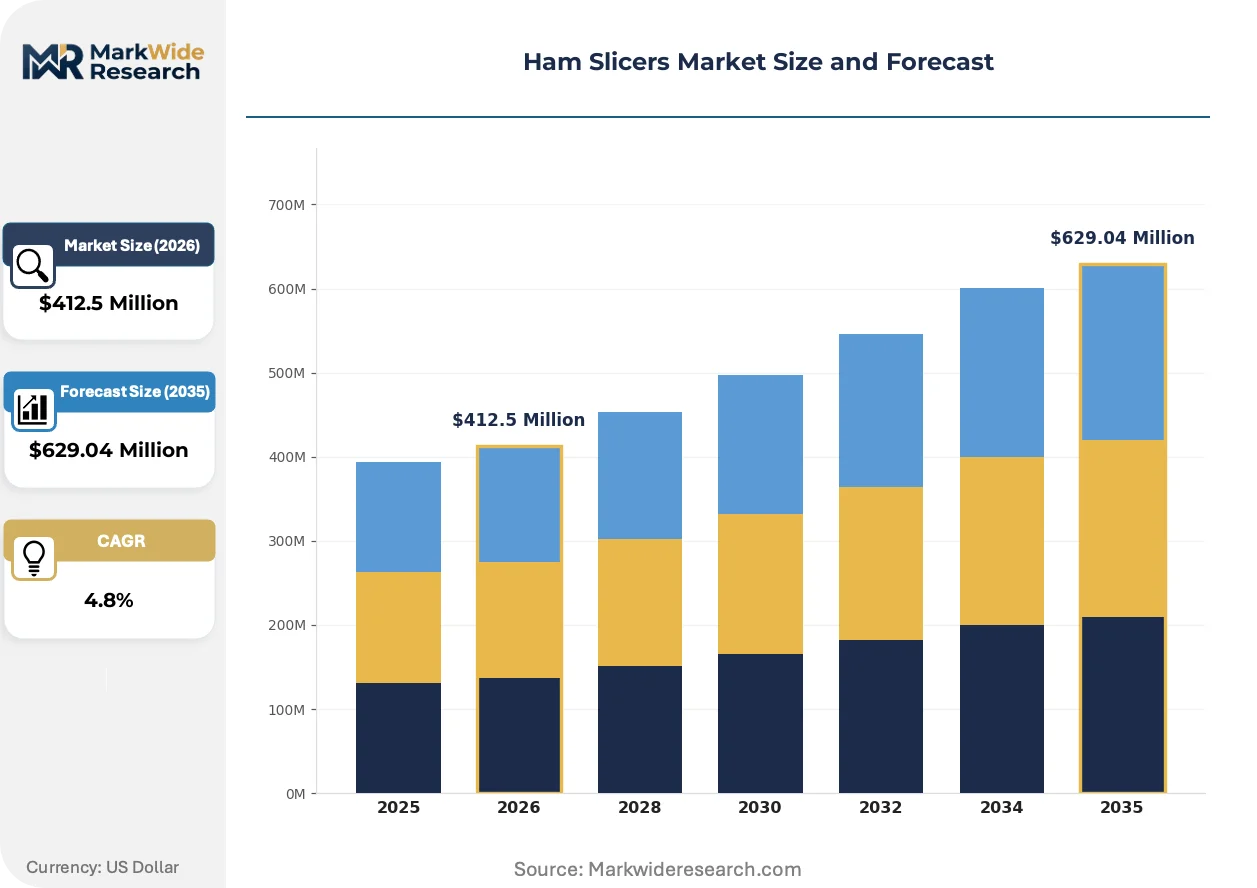
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Automatic, Commercial End User: Restaurants, Delis, Supermarkets, Catering Services Size: Small, Medium, Large, Industrial Material: Stainless Steel, Plastic, Aluminum, Composite |
| Companies Covered | Bizerba SE & Co. KG, Swedinghaus, Magurit Gefrierschneider GmbH, Foodmate, Hallde, Berkel, Hobart, Sirman, Chef'sChoice, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ham Slicers Market Trends and Innovations
Precision cutting technology is converging with connected foodservice infrastructure, while regulatory pressure on material traceability and energy performance is reshaping equipment design priorities across manufacturing bases.
Brushless DC blade motors with integrated variable speed control are replacing universal AC motors in mid-tier commercial units. Deli operators in high-volume supermarket chains are specifying these systems for reduced heat generation during continuous operation. The technology is miniaturizing motor housing dimensions, enabling slimmer carriage profiles that reclaim counter space in compact kitchen layouts.
REACH restrictions on chromium VI compounds in surface treatment processes are forcing blade manufacturers to adopt electrolytic polishing and passivation alternatives. Equipment builders serving the European market must now document stainless steel surface roughness parameters below Ra 0.8 micrometers. German export-oriented manufacturers are absorbing these compliance costs into premium product tiers, widening price spreads against non-certified competitors.
After-sales service unbundling is disrupting traditional equipment procurement in North American foodservice. Restaurant groups are separating slicer acquisition from maintenance contracts, sourcing blade sharpening and motor calibration through third-party specialists. This pattern concentrates in multi-unit casual dining chains operating across Texas, Florida, and California, where centralized procurement teams negotiate hardware and service as distinct spend categories.
Ham Slicers Market Segmentation
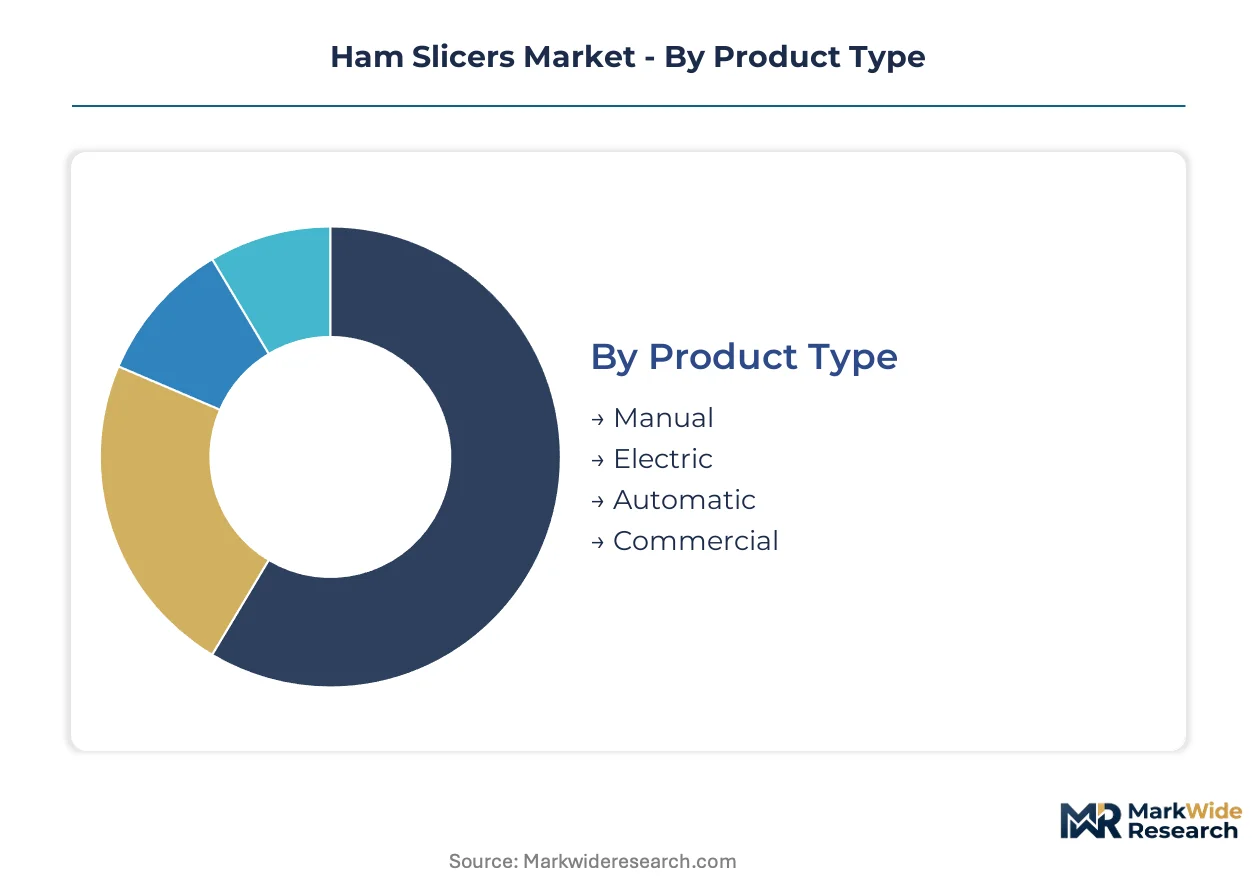
Segmentation in the ham slicers market reveals how regulatory compliance costs, labor economics, and facility constraints reshape equipment procurement across distinct operational environments. Understanding these divides enables manufacturers to align certification investments with addressable demand pools.
Product Type:
FDA Food Code cleanability mandates and EU 1935/2004 material certifications create divergent compliance burdens across automation tiers, filtering supplier participation by certification depth.
- Automatic:Gravity-fed carriage systems with integrated portion control dominate high-throughput supermarket deli installations. Full-service restaurant chains in Germany and the United States are expanding automated capacity to compress kitchen labor headcount while standardizing slice weights across multi-location operations.
- Electric:Variable-speed blade motors with brushless DC architecture are displacing universal AC systems in mid-tier commercial kitchens. Energy efficiency benchmarks in European foodservice equipment are accelerating replacement cycles in deli departments managing continuous operation schedules.
- Manual:Precision hand-cranked mechanisms retain stubborn share in traditional European delis where operator slicing skill constitutes brand identity. Artisanal charcuterie operations in Paris and Milan treat manual technique as customer-facing differentiation.
- Commercial:Heavy-duty frame construction with 370 mm blade diameter capacity serves institutional catering and central kitchen facilities. NSF International category-specific approvals for modified blade housing geometries extend validation timelines for this tier.
Automatic units handle the majority of throughput in volume-driven installations; electric models are gaining share fastest as mid-market operators balance capital constraints with labor reduction targets.
End User:
Procurement authority concentration varies sharply across customer types, with supermarket chains leveraging centralized purchasing against fragmented independent restaurant decision-making.
- Supermarkets:High-volume deli departments specify integrated weighing and slicing platforms with cloud-connected yield analytics. Shrinkage management requirements across multiple counter locations are driving IoT sensor adoption in German and US retail chains.
- Restaurants:Full-service chains prioritize portion standardization equipment to reduce per-location kitchen labor. Space-constrained urban operators in Barcelona and Milan are demanding vertical carriage systems under 400 mm width.
- Delis:Traditional European operators resist automatic substitution, preserving manual slicing as heritage craft. Baden-Württemberg and Bavaria production clusters supply precision blade assemblies calibrated for operator-controlled thickness variation.
- Catering Services:Mobile and event-focused operations require compact, rapid-deployment units with simplified cleaning protocols. Stainless steel construction dominates for sanitation compliance in multi-site service environments.
Supermarket chains command the largest equipment volumes; catering services are expanding most quickly as event-driven foodservice recovers and scales.
Size:
Counter space economics and throughput requirements create distinct specification bands that align with facility real estate constraints.
- Industrial:Continuous-duty blade motors and reinforced carriage frames serve central kitchen and food manufacturing applications. German precision engineering capabilities concentrate high-tolerance blade assembly production for this tier.
- Large:370 mm blade diameter capacity supports peak-hour deli counter throughput in high-traffic supermarket locations. Energy consumption benchmarks are elevating motor efficiency specifications in European retail installations.
- Medium:Balanced footprint-to-capacity ratios address full-service restaurant back-of-house requirements. REACH-compliant surface treatment processes are filtering supplier participation in EU-bound equipment.
- Small:Compact dimensions under 400 mm width target space-constrained urban foodservice operators. Composite material components gain traction in price-sensitive small-format installations where stainless steel certification costs weigh heavily.
Large-format equipment moves the greatest unit value; small-format designs are climbing the fastest as urban restaurant density intensifies.
Material:
Surface roughness certification requirements and alloy traceability mandates are restructuring material selection economics across price tiers.
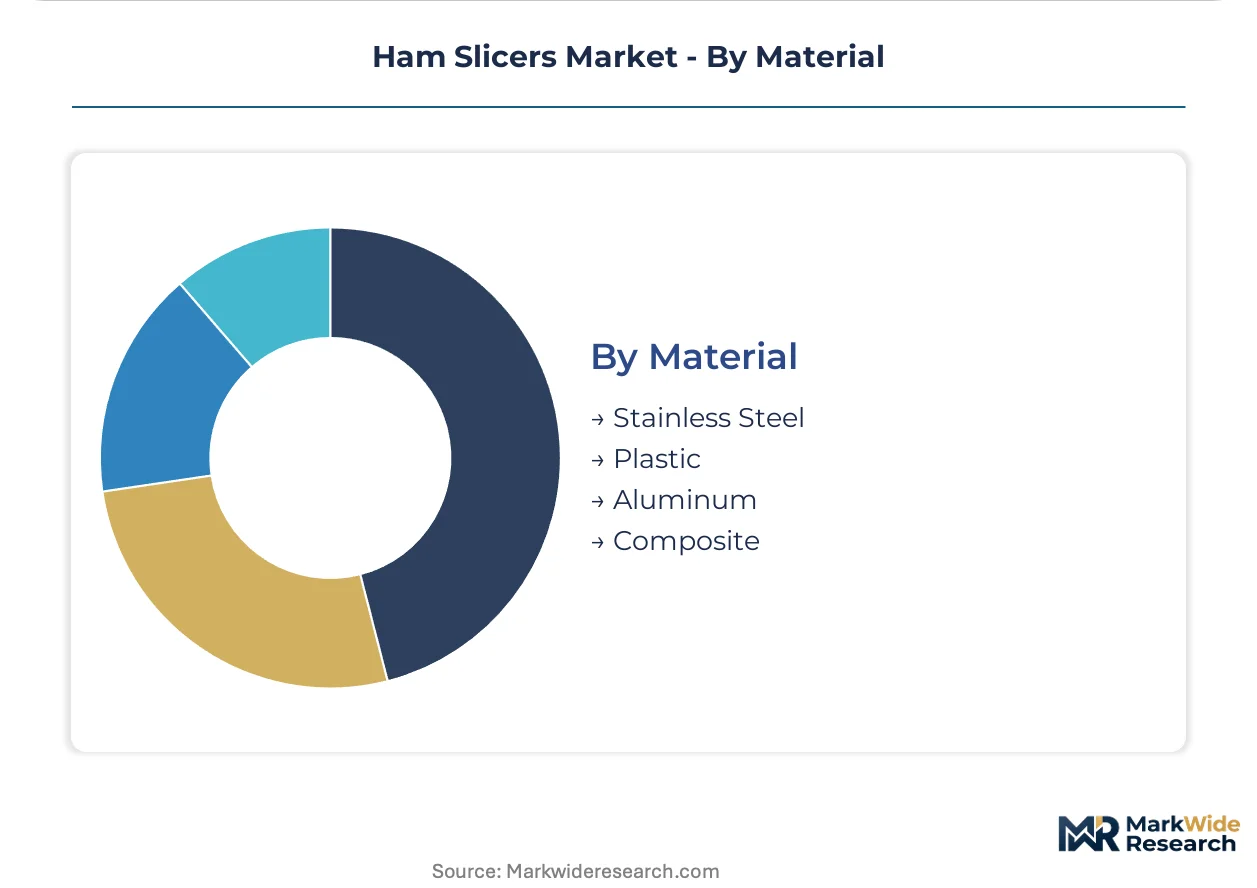
- Stainless Steel:Surgical-grade 316L construction with Ra 0.8 micrometer surface finish satisfies EU 1935/2004 food contact material mandates. Nickel alloy price volatility from Indonesian and Philippine mining output squeezes margin predictability for mid-tier equipment builders.
- Composite:Reinforced polymer components reduce unit weight and material cost in price-sensitive small-format installations. NSF International cleanability standards limit composite application to non-contact structural elements in US-bound products.
- Aluminum:Lightweight frame construction serves mobile catering and temporary foodservice installations. Surface treatment alternatives to chromium VI compounds are required under REACH restrictions for European market access.
- Plastic:Cost-driven component selection concentrates in disposable or short-lifecycle equipment segments. FDA Food Code seam minimization requirements restrict plastic application to non-structural, non-contact parts in commercial-grade units.
Stainless steel commands the dominant share of commercial-grade value; composite materials are expanding most quickly in entry-level compact equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between German precision-engineering clusters serving export markets and US supermarket chains prioritizing labor automation, while traditional European delis preserve manual equipment heritage against standardization pressures.
Germany
Baden-Württemberg and Bavaria host concentrated blade assembly manufacturing for high-tolerance equipment serving global export demand. EU Regulation 1935/2004 mandates surgical-grade 316L stainless steel certifications with Ra 0.8 micrometer surface finishes, filtering supplier participation. Precision engineering capabilities in Stuttgart and Munich sustain premium equipment manufacturing clusters supplying automated slicing platforms to international retail chains.
United States
Full-service restaurant chains across Texas, Florida, and California are expanding automated slicing capacity to compress kitchen labor headcount. FDA Food Code provisions on equipment cleanability and seam minimization directly shape blade housing geometries for US-bound products. Hobart maintains broad commercial kitchen penetration through extensive service networks covering high-volume foodservice operations.
France
Traditional Parisian delis and artisanal charcuterie operations resist automatic substitution, treating operator slicing skill as brand differentiation. REACH restrictions on chromium VI compounds in surface treatment processes force adoption of electrolytic polishing alternatives for European market access. Île-de-France and Provence-Alpes-Côte d'Azur concentrate heritage foodservice segments preserving manual equipment demand.
Italy
Milan and Barcelona operators are demanding compact vertical carriage systems under 400 mm width for space-constrained urban restaurants. NSF International category-specific approvals for modified blade housing geometries extend validation timelines for equipment serving North American export channels. Lombardy and Veneto production clusters supply precision blade assemblies calibrated for operator-controlled thickness variation.
Spain
Catering services in Madrid and Barcelona are expanding mobile and event-focused operations requiring rapid-deployment units with simplified cleaning protocols. Energy efficiency benchmarks in commercial food equipment are accelerating replacement cycles in high-throughput deli departments. Catalonia concentrates compact equipment demand from urban foodservice operators managing premium real estate constraints.
Ham Slicers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in ham slicers manufacturing. The upper tier combines slicing platforms with weighing systems and cloud connectivity, while mid-tier players compete on compact footprint designs and regional service density. Three archetypes dominate: integrated platform builders, precision blade specialists, and compact equipment fabricators. Competitive moves concentrate on modular blade motor designs anticipating right-to-repair legislation and geographic expansion through distributor partnerships rather than direct sales infrastructure.
Among German precision engineering groups, Bizerba SE & Co. KG and Magurit Gefrierschneider GmbH exemplify the integrated platform archetype, occupying positions that combine slicing with adjacent food processing functions. Hobart represents the service-network-driven model among North American commercial kitchen suppliers. Sirman sits within the compact-specialist tier, anchoring space-constrained European deli and small restaurant demand through footprint-optimized designs.
| Leading Market Players |
|---|
| Bizerba SE & Co. KG |
| Swedinghaus |
| Magurit Gefrierschneider GmbH |
| Foodmate |
| Hallde |
| Berkel |
| Hobart |
| Sirman |
| Chef'sChoice |
| Others |
Pricing and Supply Chain Analysis
EU Regulation 1935/2004 on food contact materials gates both supplier qualification and price differentiation simultaneously, filtering uncertified manufacturers from premium tiers while elevating compliance costs into product positioning. Surgical-grade 316L stainless steel certification with Ra 0.8 micrometer surface finish separates European export-capable builders from price-pressured competitors serving non-regulated markets.
Pricing Analysis
Long-term equipment procurement contracts dominate high-volume supermarket deli installations, while spot-market transactions concentrate in small-format restaurant replacements and catering fleet expansions. Three-tier pricing structure across premium certified, standard commercial, and economy non-certified levels tracks directly to stainless steel grade verification and NSF International approval depth. Pricing pressure stems from nickel alloy input volatility from Indonesian and Philippine mining output squeezing margin predictability for mid-tier equipment builders. Independent delis and small urban restaurants exhibit highest price sensitivity, whereas centralized supermarket procurement teams prioritize total cost of ownership over unit acquisition price.
Supply Chain Analysis
Baden-Württemberg and Bavaria blade assembly manufacturing creates a geographic chokepoint for high-tolerance equipment serving global export demand. German precision engineering clusters, Chinese component fabrication for motors and electronics, and Italian compact-system assembly feed finished equipment distribution. Supply chain risk centers on single-source vulnerability for 0.3 mm thickness tolerance grinding specialists commanding premium wages in Stuttgart and Munich manufacturing hubs. Distribution runs through authorized dealer networks for commercial kitchen equipment, with direct OEM relationships dominating supermarket chain procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ham slicers market rewards manufacturers who control precision blade grinding capabilities, as qualified specialists capable of maintaining sub-millimeter tolerances across variable meat textures remain scarce relative to automated assembly capacity expansion.
For Market Incumbents: Fortify blade motor service infrastructure ahead of emerging EU right-to-repair legislation by modularizing field-replaceable components and certifying third-party calibration networks. Deepen backward integration into surgical-grade 316L stainless steel sourcing relationships to buffer nickel alloy price volatility from Southeast Asian mining output. Incumbent platforms must also defend against compact-specialist entrants by reclaiming counter space in vertical carriage designs under 400 mm width. For New Entrants and Emerging Players: After-sales service unbundling in North American foodservice creates entry space for blade sharpening and motor calibration specialists operating independently of OEM maintenance contracts. Target multi-unit casual dining chains across Texas, Florida, and California where centralized procurement teams negotiate hardware and service as distinct spend categories. Go-to-market positioning should emphasize rapid-response field service density against incumbent network coverage gaps. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automatic slicing platforms with integrated IoT yield analytics, as cloud-connected portion tracking capabilities separate premium equipment tiers. Long-term viability favors manufacturers with demonstrated EU 1935/2004 certification depth and established export relationships with German supermarket retail chains. Acquisition screening should prioritize precision grinding skill retention and modular motor design IP; the signal to watch is NSF International validation timeline compression for modified blade housing geometries.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Blade Motor Design | Anticipates EU right-to-repair directives with field-replaceable components reducing service dependency. |
| Cloud-Connected Yield Analytics | Integrates IoT sensors with Bizerba-style weighing platforms for real-time supermarket shrinkage management. |
| Compact Vertical Carriage Systems | Reclaims counter space under 400 mm width for Paris, Milan, and Barcelona urban restaurant constraints. |
| Electrolytic Polishing Certification | Substitutes REACH-compliant surface treatment for chromium VI compounds in European market access. |
| Third-Party Service Network Authorization | Captures after-sales unbundling trend in North American multi-unit restaurant procurement patterns. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with equipment manufacturing executives, commercial kitchen procurement directors, supermarket deli operations managers, and aftermarket service specialists; and secondary validation through EU food contact material certification databases, NSF International approval registries, FDA Food Code equipment provisions, and stainless steel trade flow customs records. Bottom-up unit shipment estimates by product tier and end-use segment were triangulated against top-down market value reconstructions.
Across the projection horizon, the analytical framework modeled demand drivers across automation level, blade diameter specification, and regional regulatory cluster, with CAGRs derived from equipment replacement cycle analysis and labor cost elasticity estimates in full-service restaurant operations. Forecast inputs incorporated energy efficiency benchmark adoption rates in European retail installations and REACH restriction implementation timelines affecting surface treatment process transitions.
Forecasts assume regulatory continuity in EU 1935/2004 food contact material mandates and FDA Food Code cleanability provisions; material policy shifts in stainless steel grade certification or right-to-repair directive scope would require re-modeling. Nickel alloy price volatility from Indonesian and Philippine mining output, precision grinding labor scarcity in German manufacturing clusters, and NSF International validation timeline extensions represent specific risk factors that could revise equipment replacement cycle assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
GCC Red Meat Market
Meat Products
Global Beef Market
Meat Products
3D Printed Meat Market
Meat Products
Meat Packaging Market
Meat Products
United States Poultry Meat Market
Meat Products
Grass Fed Beef Market
Meat Products
Sausage Premixes Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Middle East Red Meat Market
Meat Products
Bacon Market
Meat Products
Smokehouse Market
Meat Products
India Edible Meat Market
Meat Products
Global Duck Meats Market
Meat Products
Low Fat Sausage Market
Meat Products
Emulsified Meat Market
Meat Products
Oman Poultry Meat Market