
 France Meat Products Market | 2026-2036
France Meat Products Market Size, Share, and Industry Trends Forecast 2026-2036
France Meat Products Market Insights
Food service procurement of premium charcuterie and prepared meats is expanding as Parisian restaurants and regional brasseries rebuild post-pandemic volume commitments. Société LDC leverages its integrated poultry and processed meat platform to secure shelf space across hypermarket banners. Groupe Bigard anchors beef and veal supply through its western France slaughtering and boning network. Terrena competes via cooperative farmer ownership, giving it backward control over raw material traceability.
France meat products encompass muscle tissue and edible offal from cattle, swine, poultry, and ovine species, processed through slaughtering, cutting, curing, smoking, or chilling to yield fresh, frozen, or shelf-stable proteins for human consumption. Poultry leads volume throughput due to lower feed conversion ratios and shorter production cycles that compress working capital needs. Cured and smoked processing methods command margin premiums as aging requirements and regional appellation rules create scarcity value. Supermarkets and hypermarkets dominate distribution, though online retail is gaining traction among urban households seeking subscription-based fresh delivery.
ANSES sets maximum residue limits and microbiological criteria that all French meat processors must meet for domestic sale and export eligibility. EU Green Deal farm-to-fork targets and national EGAlim laws mandate reduced antibiotic use and improved animal welfare standards, raising compliance costs for smaller abattoirs. BSI and DGCCRF market surveillance enforce labeling accuracy and origin claims at retail. Stakeholders must monitor how CAP subsidy reallocations and carbon border adjustment mechanisms reshape feed grain costs and export competitiveness in neighboring European markets.
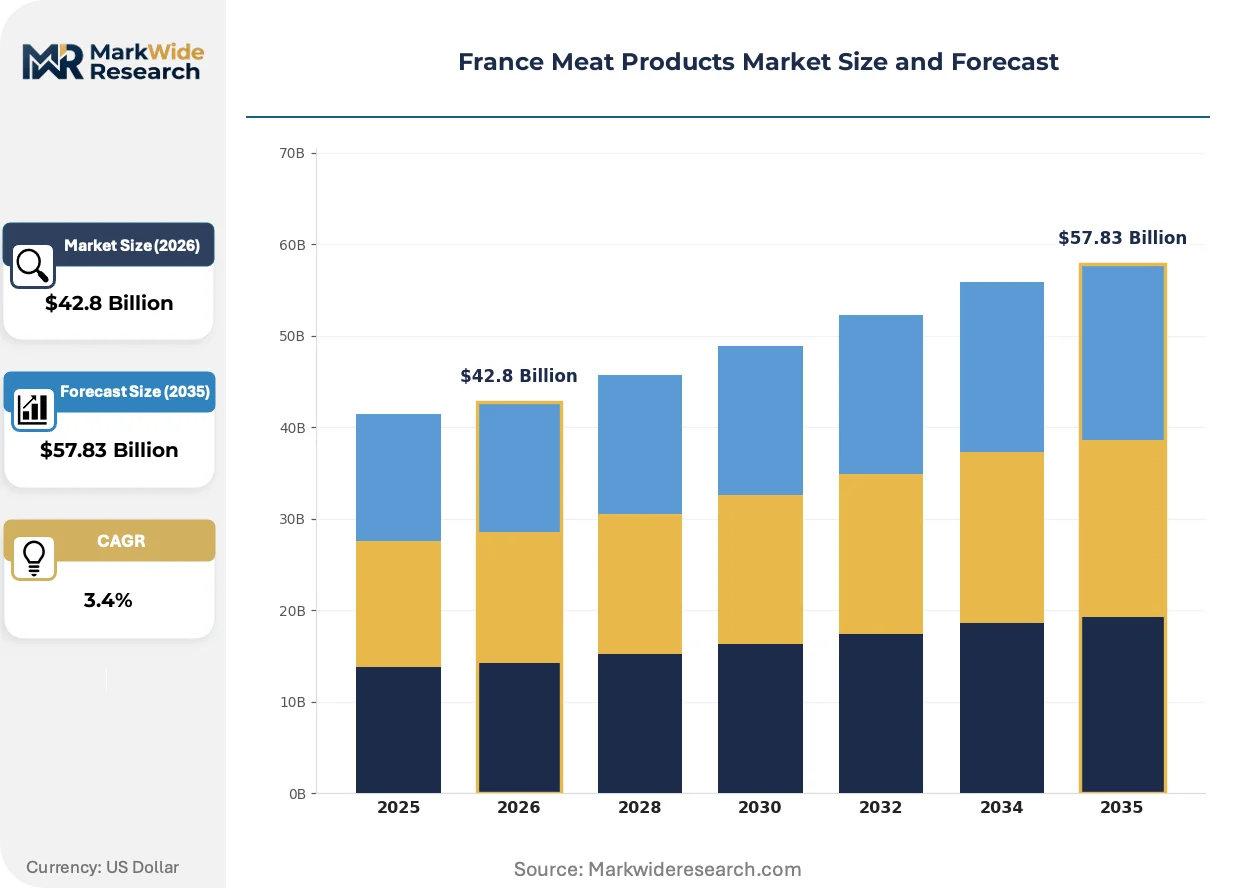
Market Dynamics
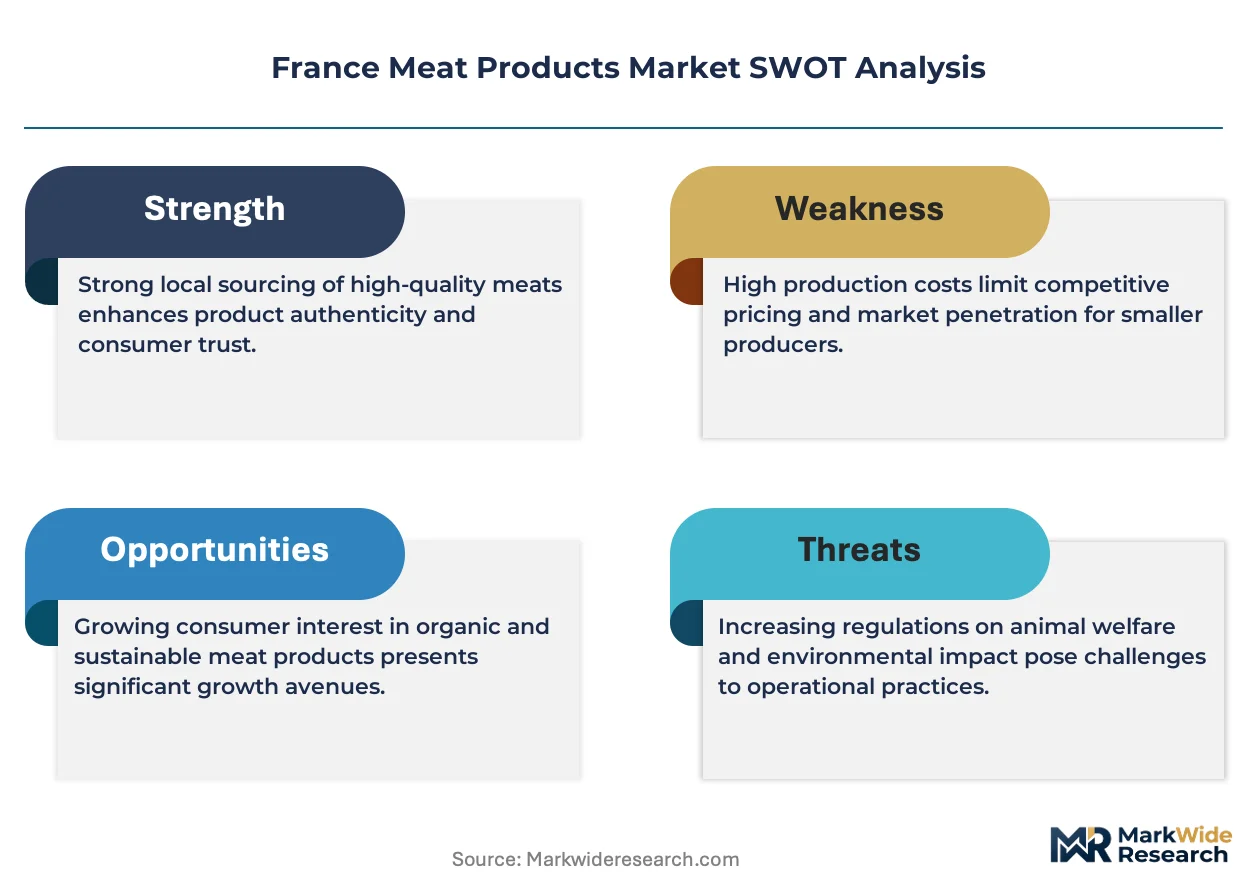
EGAlim laws and EU Green Deal farm-to-fork mandates are compressing antibiotic use timelines while raising animal welfare compliance costs, forcing smaller French abattoirs to consolidate or exit as larger processors absorb regulatory overhead.
Growth Catalysts
- ANSES nutritional labeling:Mandatory front-of-pack nutrient scoring drives reformulation investment, creating premium positioning for clean-label charcuterie lines that exceed baseline requirements.
- Parisian food service recovery:Brasserie and fine-dining procurement of aged cured cuts has rebounded to pre-pandemic throughput levels, absorbing excess aging inventory from regional processors.
- Île-de-France retail density:Hypermarket and specialty butcher concentration in the Paris basin enables just-in-time fresh distribution that reduces cold-chain spoilage and working capital lockup.
Market Restraints
- Feed grain cost volatility:Ukrainian sunflower meal and Brazilian soybean price swings transmit directly into poultry and swine production economics, compressing processor margins during input spikes.
- Western France slaughtering concentration:Beef and veal processing clusters around Brittany and Pays de la Loire create geographic supply risk during livestock disease outbreaks or transport disruptions.
- Plant protein substitution:Pea and fava bean extruded alternatives are capturing flexitarian households in urban centers, eroding volume growth for conventional processed meats.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur tourism channel:Seasonal hospitality demand along the Côte d'Azur remains underpenetrated by premium cured meat suppliers relative to Parisian saturation.
- EU carbon border adjustment mechanism:Import levies on high-carbon-intensity meat products will advantage French producers with verified low-emission supply chains and renewable energy integration.
- Direct-to-consumer subscription platforms:Urban households in Lyon and Bordeaux are migrating from supermarket bulk purchases to curated monthly charcuterie boxes with provenance storytelling.
Industry Challenges
- Master butcher apprenticeship gaps:Traditional saucisson and jambon de Paris curing expertise is aging out faster than vocational training programs replenish qualified labor pools.
- CAP subsidy reallocation complexity:Shifting Common Agricultural Program payments from production volume to environmental outcomes requires processors to renegotiate long-term livestock supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Meat Products Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $57.83 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb Processing Method: Fresh, Frozen, Cured, Smoked Distribution Channel: Supermarkets, Butcher Shops, Online Retail, Food Service Packaging Type: Tray, Vacuum Pack, Can, Fresh Pack |
| Companies Covered | Société LDC, Groupe Bigard, Terrena, Doux, Gastronome, Arrivé, Le Gaulois, Plukon Food Group, Vion Food Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Meat Products Market Trends and Innovations
Automation and precision fermentation are converging with tightening welfare standards to redefine how French meat products achieve shelf stability and flavor differentiation without legacy additive portfolios.
High-pressure processing is overtaking traditional nitrite curing for ready-to-eat charcuterie preservation. Industrial processors in the Rhône corridor are adopting HPP lines to eliminate Listeria risk without residual nitrosamine concerns. This technology is overtaking thermal pasteurization as the default pathogen control method for premium sliced meats.
EU Green Deal farm-to-fork targets are mandating 50% reduction in antimicrobial use across livestock supply chains by 2030. French processors must redesign veterinary protocols and housing specifications to maintain health status without prophylactic antibiotics. Poultry integrators face the steepest compliance curve given their reliance on rapid growth promotion.
Subscription-based fresh delivery is displacing supermarket bulk purchasing among dual-income Parisian households. Digital-native entrants are capturing urban consumers with traceability apps and flexible portion sizing that traditional hypermarket counters cannot replicate. This channel rotation is most pronounced in the Île-de-France and Occitanie regions where delivery density supports unit economics.
France Meat Products Market Segmentation
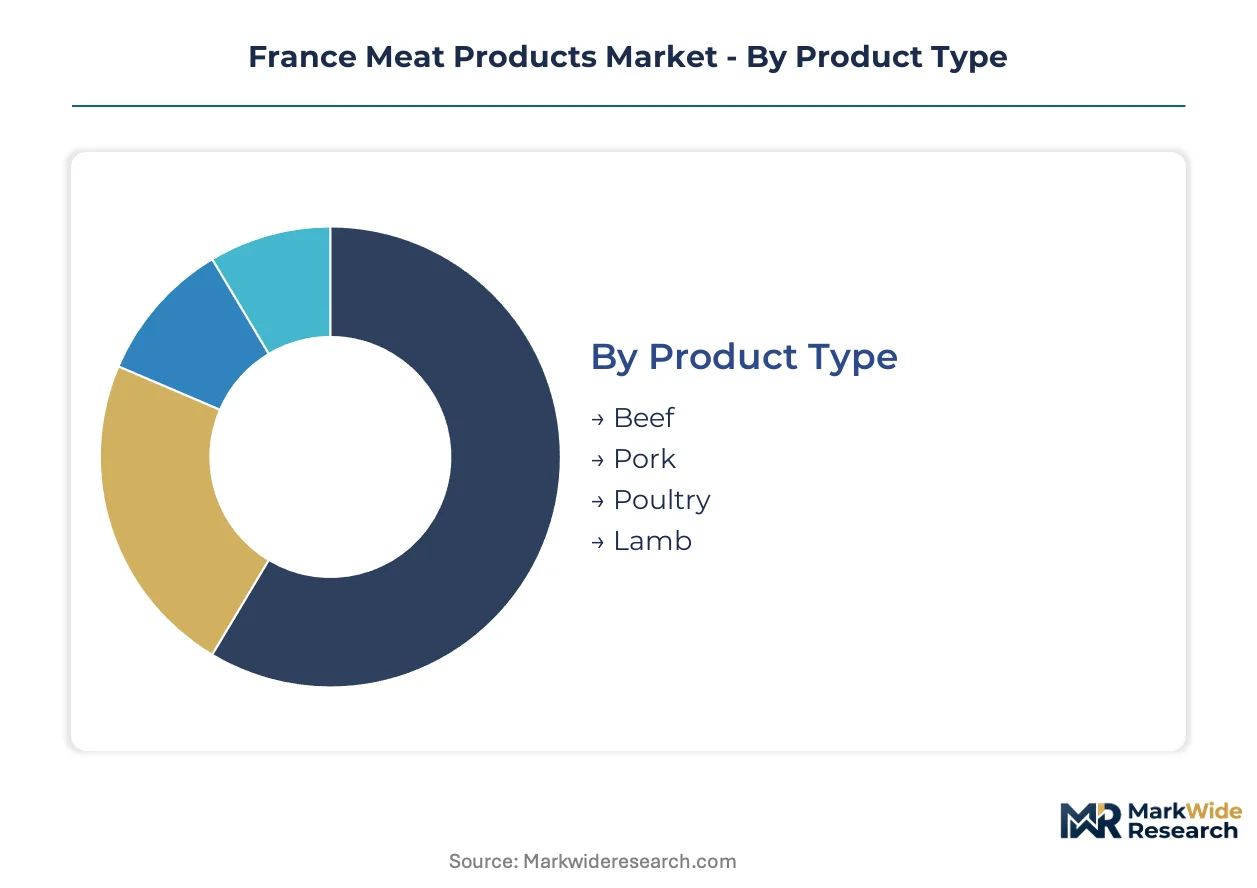
Segmentation reveals how French meat processors allocate capital across species, preservation technologies, and channel configurations. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Poultry supply chains concentrate around western France integrators who compress working capital through shorter grow-out cycles.
- Beef:Grass-fed and grain-finished cattle from Limousin and Charolais herds supply premium bistecca and ground meat lines. Brasserie demand in Paris absorbs disproportionate volumes of aged primal cuts, though CAP subsidy reallocation is pressuring farm-gate economics in Massif Central cooperatives.
- Pork:Breton and Pays de la Loire slaughtering clusters dominate fresh and cured output, with jambon de Paris and saucisson sec commanding appellation premiums. ANSES residue monitoring has tightened veterinary protocols across the Brittany integration belt.
- Poultry:Vertical integration from hatchery to retail pack characterizes the Landes and Vendée production bases. Shorter production cycles compress working capital needs relative to ruminant species.
- Lamb:Seasonal supply from Pyrenean and Provence-Alpes-Côte d'Azur flocks serves Easter and Ramadan demand peaks. Import dependency from New Zealand fills winter supply gaps.
Today's leader: Poultry. Tomorrow's challenger: Beef.
Processing Method:
Margin stratification across preservation technologies reflects capital intensity and aging infrastructure requirements.
- Fresh:Chilled primal and retail-ready cuts dominate hypermarket volume, with just-in-time distribution from Rungis and regional wholesale markets minimizing cold-chain spoilage.
- Frozen:Industrial food service and export channels absorb blast-frozen primals, though energy costs for cold storage have compressed processor margins.
- Cured:Dry-aging cellars in Auvergne-Rhône-Alpes and Provence generate scarcity value through controlled mold development and regional appellation rules. Parisian charcuterie retailers pay premiums for certified origin hams.
- Smoked:Alsatian and Franche-Comté smokehouses maintain traditional beechwood protocols for saucisse de Montbéliard and jambon fumé, though HPP adoption is displacing thermal pasteurization in industrial lines.
Fresh commands volume leadership. Cured delivers margin expansion.
Distribution Channel:
Channel mix determines working capital velocity and traceability investment requirements.
- Supermarkets:Hypermarket banners in Île-de-France and Rhône-Alpes concentrate procurement power, squeezing processor margins through private-label substitution and just-in-time delivery mandates.
- Butcher Shops:Independent bouchers and artisan charcutiers in Paris and Lyon maintain premium positioning through whole-carcass breakdown and custom cutting services that supermarkets cannot replicate.
- Online Retail:Subscription platforms and quick-commerce apps are capturing urban households in Bordeaux and Lille with portion-flexible delivery and blockchain traceability storytelling.
- Food Service:Brasserie and fine-dining procurement has rebounded to pre-pandemic throughput, absorbing excess aging inventory from regional processors in Auvergne and Savoie.
Supermarkets anchor volume. Online retail is climbing the fastest.
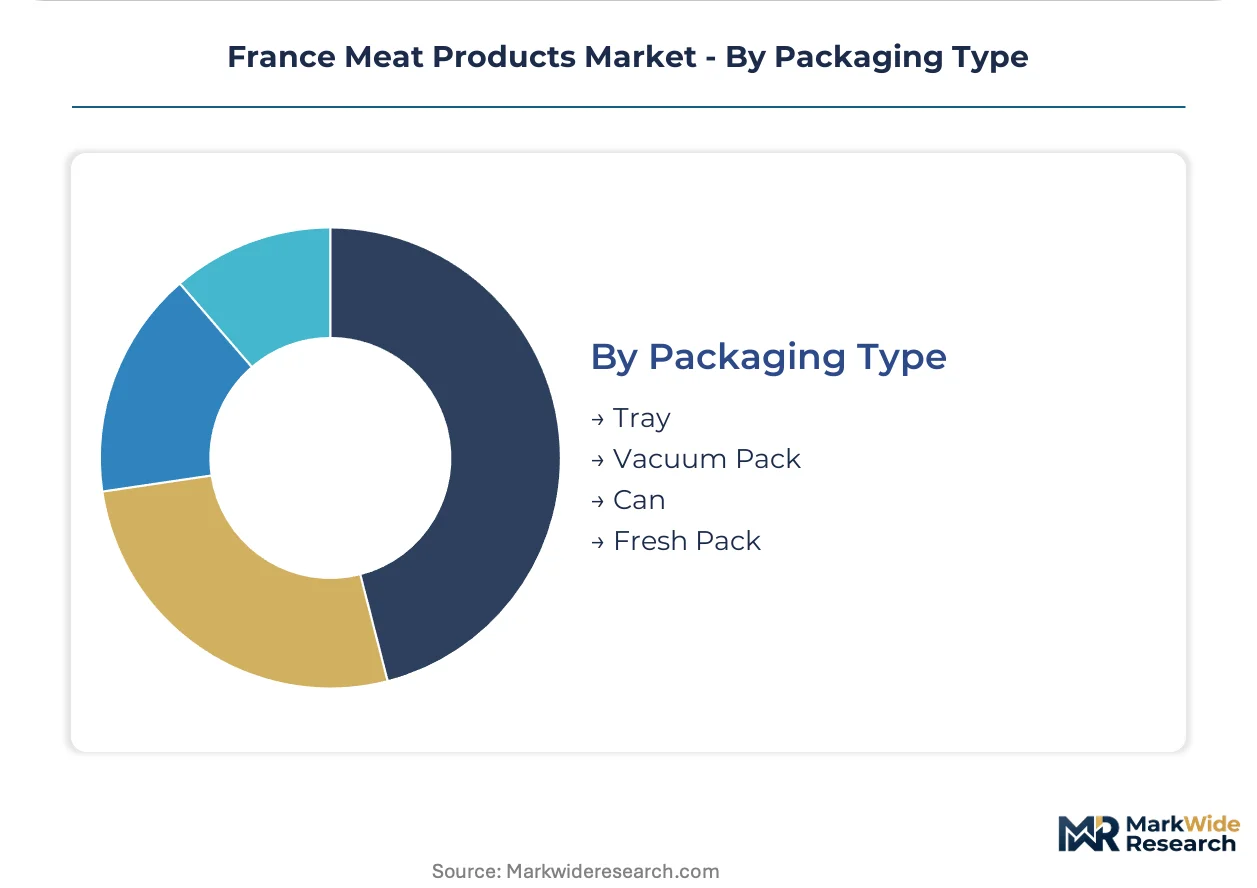
Packaging Type:
Packaging configuration directly influences shelf-life extension and retail presentation economics.
- Tray:Modified-atmosphere retail packs dominate fresh poultry and pork counter displays, with oxygen-scavenging films extending color stability.
- Vacuum Pack:Sub-primal and cured meat preservation for food service and export, with barrier films preventing oxidative rancidity in aged charcuterie.
- Can:Shelf-stable pâtés and confits for rural retail and emergency stockpiling, though volume is eroding as fresh alternatives penetrate deeper distribution.
- Fresh Pack:Overwrapped foam trays with absorbent pads remain the default for traditional butcher counter presentation, despite sustainability pressure to eliminate single-use plastics.
Vacuum pack leads premium positioning. Tray formats face regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France anchors French meat products demand through Parisian retail density and hospitality procurement volume. Hypermarket banners and brasserie networks in the capital basin absorb disproportionate throughput of fresh and cured lines. ANSES nutritional labeling requirements and EGAlim welfare mandates apply uniformly across all regions.
Île-de-France
Parisian food service operators drive premium charcuterie absorption as post-pandemic dining rebounds. ANSES front-of-pack nutrient scoring compels reformulation investment among processors supplying Rungis wholesale markets. The Paris basin concentration enables just-in-time fresh distribution that minimizes cold-chain spoilage for poultry and pork integrators.
Auvergne-Rhône-Alpes
Dry-aging cellars in the Rhône corridor generate scarcity value for certified origin hams and saucisson sec. EU Green Deal farm-to-fork targets pressure livestock producers around Lyon to reduce antimicrobial use by 2030. Industrial processors in Saint-Étienne adopt high-pressure processing lines to eliminate Listeria risk without nitrite curing.
Provence-Alpes-Côte d'Azur
Seasonal tourism demand along the Côte d'Azur creates underpenetrated opportunity for premium cured meat suppliers. BSI and DGCCRF market surveillance enforces labeling accuracy at retail counters in Nice and Marseille. Pyrenean lamb flocks supply Easter and Ramadan peaks while winter gaps fill through New Zealand imports.
Brittany and Pays de la Loire
Breton slaughtering clusters dominate fresh and cured pork output with jambon de Paris commanding appellation premiums. CAP subsidy reallocation from production volume to environmental outcomes pressures farm-gate contract renegotiation. Western concentration creates geographic supply risk during livestock disease outbreaks or transport disruptions.
Occitanie
Landes poultry integrators compress working capital through vertical hatchery-to-retail control. Shorter production cycles relative to ruminant species enable faster inventory turns for processors serving Toulouse and Montpellier markets. Subscription-based fresh delivery platforms capture urban households migrating from supermarket bulk purchasing.
France Meat Products Market Competitive Landscape
Capacity expansion dominates the current landscape as processors retrofit aging cellars and adopt high-pressure processing lines. The vendor base stratifies across three tiers: integrated poultry specialists, cooperative-backed livestock networks, and regional charcuterie artisans. Consolidation pressure intensifies as EGAlim compliance costs force smaller abattoirs to exit. Strategic archetypes include backward-integrated integrators controlling hatchery-to-retail supply chains, cooperative structures leveraging farmer ownership for traceability claims, and premium-positioned cured meat houses with appellation-protected aging protocols.
Among France-based processors, Société LDC anchors the integrated poultry and processed meat platform, exemplifying scale-driven supply chain control through captive hatchery and retail pack operations. Groupe Bigard occupies a position within beef and veal processing, representing western France slaughtering concentration through its Brittany and Pays de la Loire network. Terrena sits within the cooperative archetype, leveraging farmer ownership to secure backward material traceability for clean-label positioning. These three entities collectively illustrate how capital intensity and regulatory compliance are reshaping competitive structure across fresh, frozen, and cured segments.
| Leading Market Players |
|---|
| Société LDC |
| Groupe Bigard |
| Terrena |
| Doux |
| Gastronome |
| Arrivé |
| Le Gaulois |
| Plukon Food Group |
| Vion Food Group |
| Others |
Pricing and Supply Chain Analysis
Ukrainian sunflower meal and Brazilian soybean price indices cascade through French poultry and swine supply chains, compressing processor margins during input spikes while forcing tiered pricing adjustments across premium charcuterie, standard fresh cuts, and economy frozen lines. Feed grain volatility transmits directly into farm-gate contract renegotiations, with larger integrators absorbing cost shocks through backward integration while smaller abattoirs pass through increases or exit.
Pricing Analysis
Input-cost pass-through dominates French meat pricing, with feed grain spikes compressing margins faster than processors can renegotiate retail and food service contracts. Three-tier pricing structure across premium appellation-cured, standard fresh-cut, and economy frozen segments reflects quality grade differentiation and ANSES compliance certification levels. Pricing pressure stems from CAP subsidy reallocation raising livestock procurement costs, with supermarket banners squeezing processor margins through private-label substitution. Food service operators show least price sensitivity for aged cured cuts, while urban subscription households demonstrate highest elasticity to delivery premiums.
Supply Chain Analysis
Single-source vulnerability sits with Ukrainian sunflower meal and Brazilian soybean suppliers for feed protein, exposing French poultry integrators to commodity price volatility and currency fluctuation risks. Raw material dependencies extend to Breton slaughtering clusters for pork, Massif Central cooperatives for beef, and Landes hatcheries for poultry genetics. Supply chain risk centers on geographic concentration in western France slaughtering infrastructure during livestock disease outbreaks. Distribution runs through Rungis wholesale markets for just-in-time fresh delivery to Parisian retail and hospitality channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France meat products function as a regulatory compounder where EU Green Deal farm-to-fork mandates and EGAlim welfare standards continuously raise compliance thresholds, advantaging scaled processors with capital to absorb veterinary protocol redesign and aging infrastructure investment.
For Market Incumbents: To counter plant protein substitution erosion in urban flexitarian households, prioritize HPP line adoption for nitrite-free charcuterie preservation and secure backward integration into certified low-emission livestock supply chains. Expand aging cellar capacity in Auvergne-Rhône-Alpes to capture Parisian premium demand while defending shelf space against cooperative traceability claims. For New Entrants and Emerging Players: EU carbon border adjustment mechanism implementation opens a window for verified low-emission supply chain positioning against import competition. Target Provence-Alpes-Côte d'Azur seasonal hospitality channels with curated provenance storytelling and direct-to-consumer subscription platforms in Lyon and Bordeaux where supermarket bulk purchasing is displacing fastest. For Investors and Strategic Acquirers: Asymmetric upside sits with cooperative-structured processors possessing farmer-owned traceability networks that command clean-label premiums. Long-term viability hinges on EGAlim compliance scalability across the projection horizon. Monitor CAP subsidy reallocation negotiations as inflection signal for farm-gate contract restructuring and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Line Adoption | Eliminates Listeria risk in ready-to-eat charcuterie without residual nitrosamine concerns from traditional curing. |
| Backward Integration into Certified Livestock Supply | Secures ANSES-compliant raw material traceability for clean-label positioning against cooperative competitors. |
| Direct-to-Consumer Subscription Platform Launch | Captures urban households in Bordeaux and Lille migrating from hypermarket bulk purchasing with blockchain provenance apps. |
| Aging Cellar Capacity Expansion | Generates scarcity value through controlled mold development for jambon de Paris and saucisson sec appellation premiums. |
| Cooperative Acquisition or Partnership | Leverages farmer ownership structures for backward material control and EGAlim welfare compliance cost sharing. |
Research Methodology
Coverage spans Île-de-France, Auvergne-Rhône-Alpes, Brittany, Pays de la Loire, and Provence-Alpes-Côte d'Azur, with primary inputs from each region combining processor procurement directors, Rungis wholesale market operators, cooperative livestock managers, ANSES regulatory affairs specialists, and brasserie chain purchasing executives. Secondary validation draws from EU Green Deal implementation tracking, CAP subsidy reallocation documentation, DGCCRF enforcement records, and customs trade data for feed grain imports. Bottom-up volume modeling triangulates against top-down value estimates across species and processing method segments.
Rate-of-change decomposition separates volume growth drivers from price evolution across the analysis window, with CAGRs derived from segment-level elasticity modeling and cross-species substitution dynamics. Segmentation dimensions include product type, processing method, distribution channel, and packaging configuration, with additional industry-specific modeling of appellation certification tiers and antimicrobial compliance trajectories. Forecast inputs incorporate feed grain price scenario analysis and carbon border adjustment mechanism implementation timelines.
Revisions become necessary when Ukrainian grain export disruptions, Brazilian soybean harvest failures, or accelerated EU farm-to-fork antimicrobial reduction mandates materialize beyond baseline assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Reduced Fat Meat Market
Meat Products
North America Processed Meat Market
Meat Products
Bacon Slicers Market
Meat Products
Bacon Flavors Market
Meat Products
Meat Ingredients Market
Meat Products
Organic Meat Products Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Global Duck Meats Market
Meat Products
Oman Poultry Meat Market
Meat Products
Organic Chicken Market
Meat Products
Animal Protein Market
Meat Products
Global Canned Meat Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Emulsified Meat Market
Meat Products
Germany Poultry Meat Market
Meat Products
Europe Processed Meat Market