
 Pork Flavors Market | 2026-2036
Pork Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Pork Flavors Market Analytics
China is reshaping supply dynamics through expanded savory flavor production complexes in Jiangsu and Shandong provinces. Kerry Group leverages vertical integration from raw material sourcing through finished flavor compounding to sustain cost advantages across Asian markets. Givaudan anchors its position through specialized smoke and roast reaction flavor technology developed for processed meat applications. International Flavors & Fragrances competes via broad patent coverage in thermal process flavor generation.
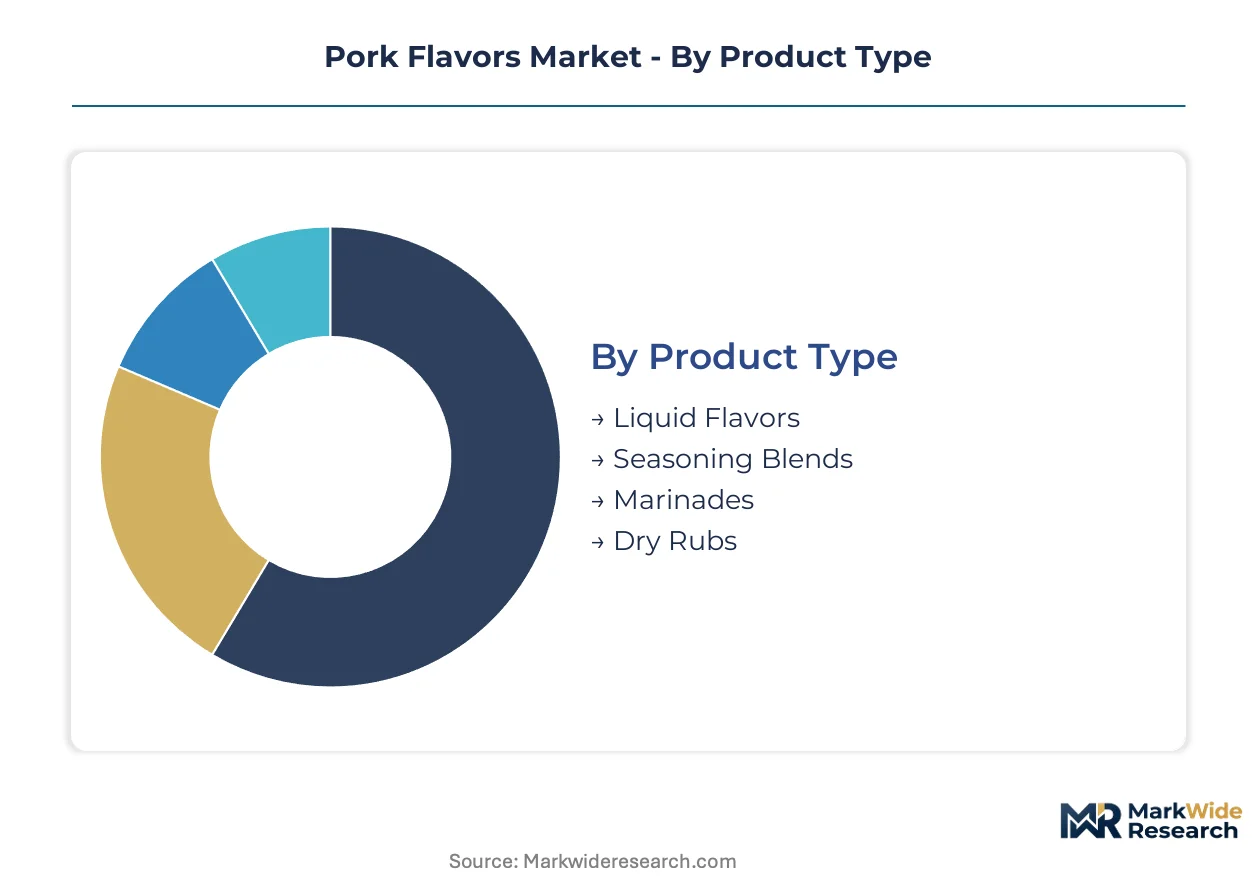
Pork flavors comprise thermally processed reaction flavors, enzyme-modified extracts, and compounded top-note systems designed to replicate species-specific aroma chemistry in food matrices. Manufacturers employ Maillard reaction control, lipid oxidation management, and selective pyrolysis to achieve authentic cured, roasted, or smoked sensory profiles for industrial food production. Liquid flavors dominate volume throughput in food manufacturing channels where pumpable dosing and batch consistency matter most. Seasoning blends capture expanding margin pools as restaurants and catering operators outsource spice procurement complexity. Marinades represent the fastest-growing product type, reflecting ready-to-cook protein retail trends and home meal replacement demand.
USDA and FDA standards govern species authenticity and allergen labeling for pork-derived flavor ingredients in American commerce, while China's SAMR enforces GB standards for compound seasoning safety and additive limits. REACH and EFSA frameworks in Europe restrict certain pyrazine and sulfur-containing flavor precursors, compelling reformulation toward cleaner thermal processing methods. Stakeholders must monitor evolving natural claim definitions across FDA, EFSA, and SAMR jurisdictions to anticipate compliance-driven product redevelopment cycles.
Market Dynamics
China's SAMR labeling enforcement is forcing pork flavor manufacturers to rebuild formulation architectures around natural claim substantiation, triggering cascading investments in reaction flavor technology and clean-label extraction methods.
Growth Catalysts
- Instant noodle sector expansion:Asia-Pacific food manufacturers are scaling pork flavor procurement to serve Southeast Asian and African export markets, with Indonesia and Vietnam emerging as high-volume absorption points.
- GB standards compliance:China's tightened additive limits under SAMR oversight are accelerating domestic producer consolidation, advantaging technical specialists with captive analytical laboratories.
- Maillard reaction optimization:Thermal process control technologies are enabling precise aroma replication without synthetic precursors, satisfying clean-label requirements while maintaining sensory fidelity.
Market Restraints
- Raw material concentration:Porcine tissue sourcing clusters in Jiangsu and Shandong provinces, creating geographic vulnerability to African swine fever recurrence and provincial biosecurity disruptions.
- REACH precursor restrictions:EFSA frameworks limit pyrazine and sulfur compound deployment in European formulations, forcing reformulation cycles that extend product development timelines.
- Plant protein substitution:Pea and soy protein hydrolysates are capturing flavor carrier applications in meat-analog production, displacing traditional pork-derived substrates in select segments.
Strategic Opportunities
- Ready-to-cook marinades:Retail protein preparation trends in South Korea and Japan are opening formulation partnerships with supermarket private-label programs.
- Smoke flavor technology convergence:Integration of controlled pyrolysis with enzyme modification is creating differentiated roast profiles for premium processed meat lines.
- SAMR natural claim pathways:Regulatory clarity on fermentation-derived flavor classification is enabling investment in bioprocess capacity with defined compliance boundaries.
Industry Challenges
- Flavor chemist scarcity:Specialized expertise in species-specific Maillard pathway control remains concentrated among senior practitioners in European and Japanese technical centers.
- Legacy equipment retrofit costs:Continuous thermal processing systems require substantial capital deployment to achieve batch-to-batch consistency demanded by branded food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pork Flavors Market |
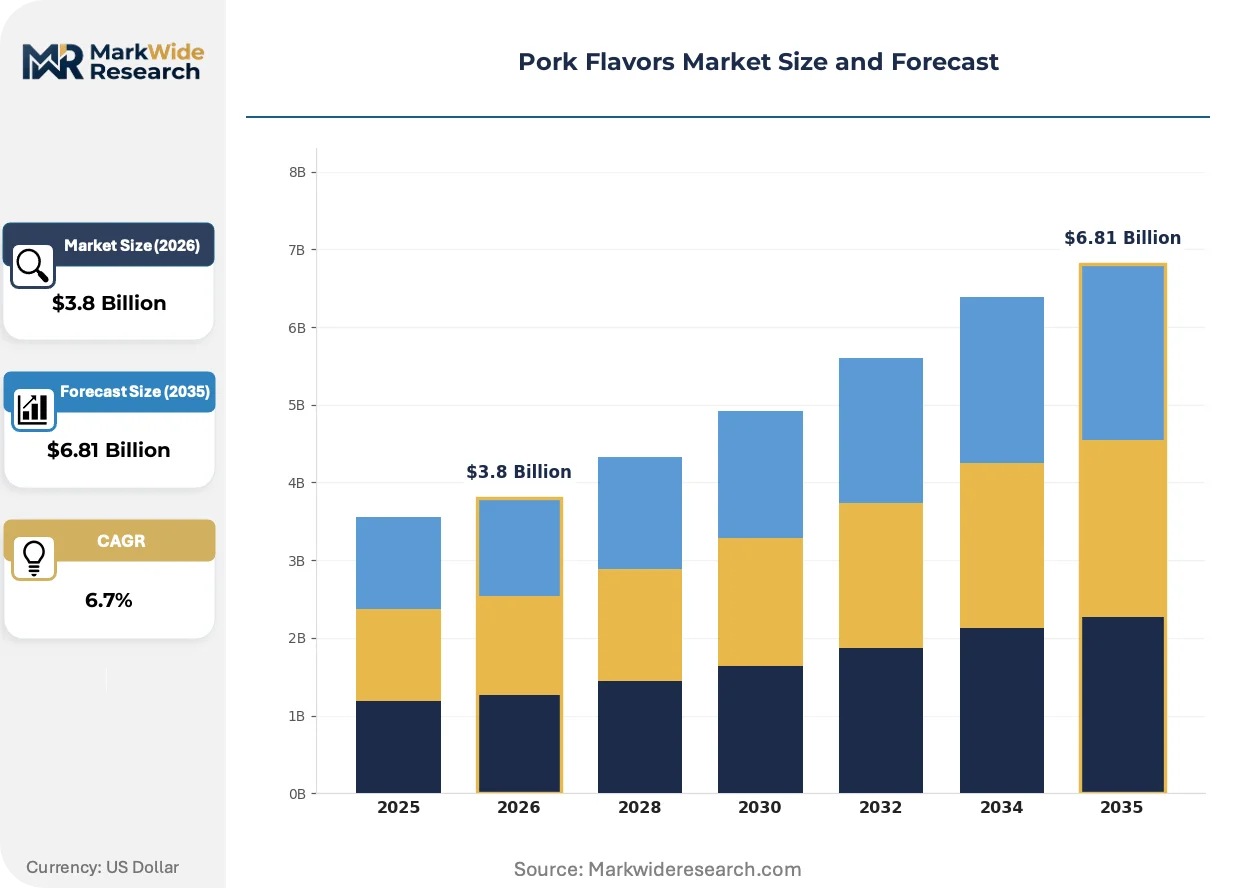
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Flavors, Seasoning Blends, Marinades, Dry Rubs End User: Restaurants, Food Manufacturers, Catering Services, Retailers Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales Flavor Profile: Smoky, Sweet, Spicy, Savory |
| Companies Covered | Kerry Group, International Flavors & Fragrances, Givaudan, Archer Daniels Midland, Cargill, BASF, DuPont Danisco, Williamson & Co Inc, Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pork Flavors Market Evolving Landscape
Digital formulation tools and biosynthetic production methods are converging to compress development cycles while expanding the definitional boundaries of "natural" in regulatory contexts across major markets.
Computational flavor chemistry is virtualizing traditional bench-scale development workflows. Major seasoning blend manufacturers are adopting molecular modeling platforms to predict Maillard pathway outcomes before pilot production. This capability is virtualizing the role of experienced flavor chemists in early-stage formulation, compressing timeline risk and enabling rapid iteration across multiple sensory targets.
REACH authorization processes are tightening scrutiny on thermal process flavor precursors. ECHA's evolving substance evaluation criteria are restricting certain pyrazine derivatives previously standard in smoked pork profiles. European compounders are responding with investment in alternative pyrolysis feedstocks and accelerated natural claim substantiation documentation.
Restaurant procurement consolidation is restructuring seasoning supply relationships. Multi-unit chain operators in China are centralizing spice specification authority, displacing fragmented distributor relationships with direct manufacturer contracts. This concentration is most visible in Shanghai and Beijing metropolitan clusters, where centralized kitchen models demand pumpable liquid flavor systems with documented lot traceability.
Pork Flavors Market Segmentation
Pork flavor procurement varies sharply by operational intensity. Food manufacturers demand pumpable liquid systems with batch-to-batch consistency, while restaurants prioritize customizable seasoning blends. Understanding segment-specific technical requirements enables targeted formulation investments and distribution alignment.
Product Type:
After-sales service intensity peaks with marinades and liquid flavors, where manufacturers provide technical dosing support, equipment calibration, and sensory troubleshooting to industrial buyers.
- Liquid Flavors:Pumpable emulsions and concentrated extracts designed for automated dosing systems in high-volume food manufacturing. Demand concentrates in Jiangsu and Shandong province processing clusters, where instant noodle and processed meat producers require precise viscosity control and microbial stability under GB standards.
- Marinades:Ready-to-apply liquid systems combining flavor compounds with functional ingredients for protein tenderization and moisture retention. South Korean and Japanese supermarket private-label programs are absorbing expanding volumes as home meal replacement trends accelerate.
- Seasoning Blends:Dry mix formulations integrating pork-derived flavor carriers with salt, sugar, and spice components for flexible kitchen application.
- Dry Rubs:Coarse-grind powder systems optimized for surface adhesion during roasting or grilling operations.
By volume, liquid flavors lead. By growth pace, marinades are ahead.
End User:
Cost tier stratification separates specification authority: multinational food manufacturers negotiate direct contracts with captive technical service, while fragmented restaurant operators purchase through consolidated distributor networks.
- Food Manufacturers:Industrial buyers of bulk flavor compounds for processed meat, instant noodles, and savory snack production. China-based producers dominate procurement volumes, with SAMR-compliant documentation requirements driving supplier consolidation toward technical specialists with in-house analytical laboratories.
- Restaurants:Foodservice operators sourcing seasoning blends and liquid concentrates for menu execution. Centralized kitchen models in Shanghai and Beijing metropolitan clusters are displacing fragmented distributor relationships with direct manufacturer contracts demanding pumpable systems with documented lot traceability.
- Catering Services:Institutional volume buyers requiring shelf-stable flavor formats for large-batch preparation.
- Retailers:Supermarket and e-commerce operators procuring private-label marinades and seasoning blends for consumer-facing protein preparation kits.
Food manufacturers command the largest volume share. Restaurants are expanding most quickly as procurement centralization accelerates.
Distribution Channel:
Application-specific logistics requirements segment channel selection: temperature-sensitive liquid flavors favor direct sales with dedicated tanker delivery, while ambient-stable dry products tolerate multi-hop distribution.
- Direct Sales:Manufacturer-to-buyer relationships for high-volume liquid flavor contracts with technical service obligations. Dominates food manufacturer procurement in China, where SAMR documentation requirements and just-in-time delivery schedules reward supplier proximity to Jiangsu and Shandong production complexes.
- Supermarkets:Mass retail channels for consumer-facing seasoning blends and marinade bottles. Indonesian and Vietnamese retail expansion is absorbing increasing volumes as Southeast Asian middle-class protein consumption rises.
- Online:E-commerce platforms serving specialty and small-batch buyers with extended SKU variety.
- Specialty Stores:Premium retail channels targeting artisanal meat processors and high-end restaurant suppliers.
Direct sales capture the highest volume throughput. Online channels are climbing the fastest as digital procurement penetrates mid-tier food manufacturers.
Flavor Profile:
Customer type differentiation separates industrial specification from consumer preference: food manufacturers demand precise sensory targets with analytical substantiation, while retail buyers respond to trend-driven positioning.
- Savory:Umami-forward profiles emphasizing glutamate and nucleotide synergy for depth and mouthfeel. Chinese instant noodle producers specify these formats most heavily, with Maillard reaction optimization enabling clean-label claims under tightened SAMR natural flavor definitions.
- Smoky:Pyrolysis-derived or liquid smoke-based systems replicating wood-fired sensory characteristics. European REACH restrictions on pyrazine precursors are forcing reformulation toward controlled thermal processing methods with accelerated natural claim documentation.
- Spicy:Heat-integrated profiles combining capsaicin delivery with pork-specific aroma chemistry.
- Sweet:Caramelized and honey-noted variants targeting glaze and barbecue sauce applications.
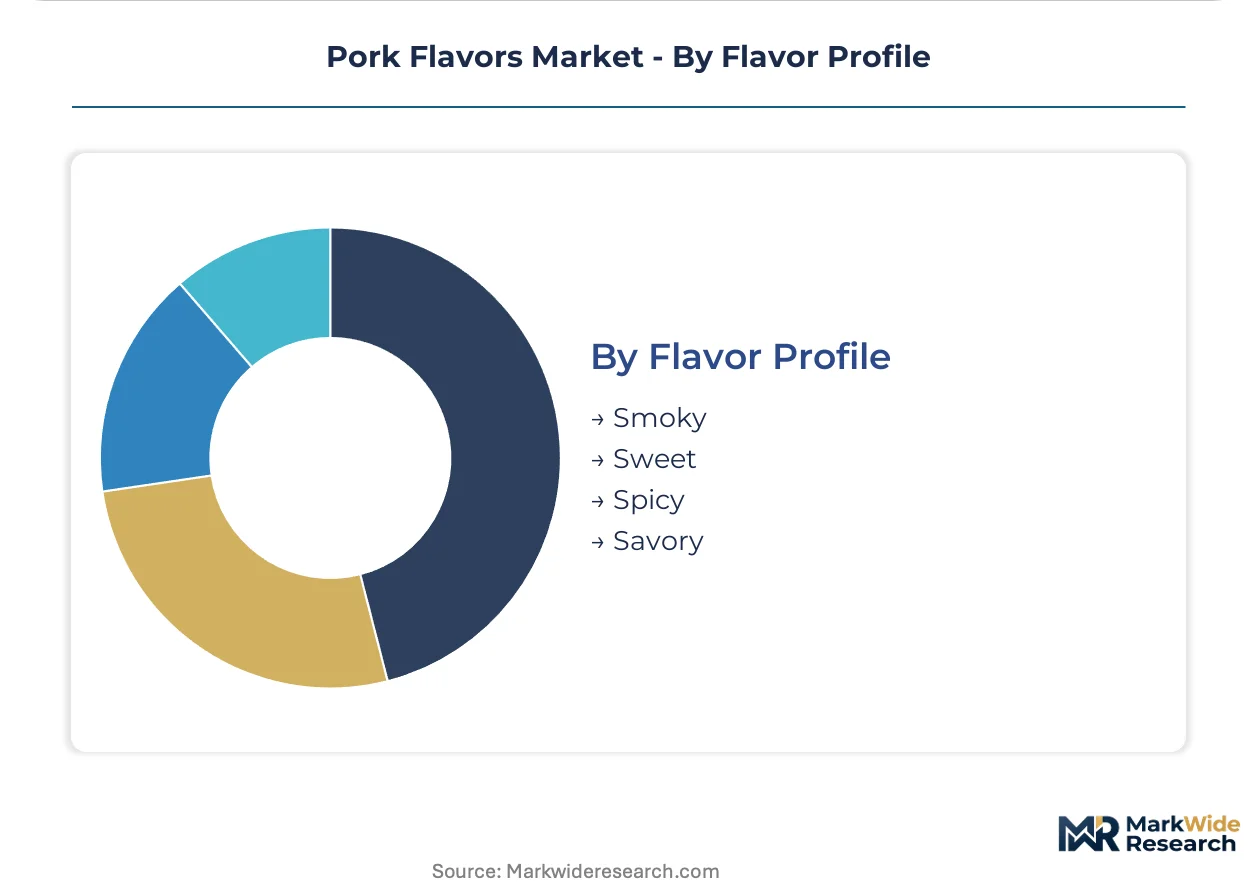
Savory profiles dominate volume absorption. Smoky formulations are gaining share fastest as premium processed meat lines expand in South Korea and Japan.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Food manufacturers in China absorb pork flavors through direct industrial procurement for instant noodle and processed meat lines. Restaurant operators in South Korea and Japan drive marinade demand through centralized kitchen models. European compounders navigate REACH precursor restrictions while North American buyers prioritize USDA species-authenticity documentation.
China
Instant noodle producers in Jiangsu and Shandong provinces specify pumpable liquid systems with GB standards compliance. SAMR tightened natural versus artificial flavor labeling requirements, forcing reformulation investments toward Maillard reaction optimization. Qingdao and Nanjing processing clusters concentrate domestic pork flavor production capacity serving both local food manufacturers and Southeast Asian export markets.
United States
Processed meat and savory snack manufacturers dominate procurement volumes with emphasis on thermal process flavor consistency. USDA and FDA enforce species authenticity and allergen labeling standards for pork-derived ingredients. Chicago and Omaha metropolitan areas anchor Midwest flavor compounding operations supplying national meat processing conglomerates.
South Korea
Supermarket private-label programs absorb expanding marinade volumes for ready-to-cook protein retail. MFDS regulates compound seasoning safety and additive limits for domestic distribution. Seoul metropolitan cluster centralizes procurement authority for multi-unit restaurant chains demanding pumpable liquid systems with documented lot traceability.
Japan
Premium processed meat lines drive demand for smoke and roast reaction flavor technology. METI oversees food additive standards while industry adheres to JIS quality frameworks. Osaka-Kobe industrial corridor hosts specialized flavor houses developing species-specific aroma chemistry for export-oriented meat processors.
Germany
European REACH restrictions on pyrazine and sulfur-containing precursors compel reformulation toward cleaner thermal processing methods. EFSA frameworks govern natural claim substantiation documentation. Cologne-Düsseldorf chemical cluster concentrates savory flavor R&D investment serving continental meat-analog and traditional processed meat producers.
Pork Flavors Market Competitive Landscape
Capability concentration sits with technical specialists mastering Maillard pathway control; scale advantage sits with diversified ingredient conglomerates. The vendor base stratifies across three tiers: integrated flavor houses with captive reaction technology, mid-scale compounders serving regional food manufacturers, and commodity processors supplying standardized extracts. Dominant competitive moves include backward integration into raw material sourcing and geographic expansion through technical service partnerships.
Among diversified ingredient conglomerates, Kerry Group, International Flavors & Fragrances, and Givaudan occupy positions spanning multiple savory flavor categories. Kerry Group exemplifies the vertically integrated archetype with control from porcine tissue sourcing through finished compounding. International Flavors & Fragrances represents the patent-anchored technology licensor model. Givaudan sits within the specialized reaction flavor tier with emphasis on smoke and roast profile development.
| Leading Market Players |
|---|
| Kerry Group |
| International Flavors & Fragrances |
| Givaudan |
| Archer Daniels Midland |
| Cargill |
| BASF |
| DuPont Danisco |
| Williamson & Co Inc |
| Firmenich |
| Others |
Value Network & Pricing Analysis
Jiangsu and Shandong province raw material concentration anchors cost structures for downstream liquid flavor and marinade producers. SAMR compliance documentation requirements concentrate procurement authority with technical specialists possessing captive analytical laboratories, shifting margin pools toward specification-grade suppliers.
Pricing Analysis
Long-term offtake contracts dominate food manufacturer procurement, locking in volume commitments against technical service obligations. Three-tier pricing structure across premium, standard, and economy levels separates SAMR-certified natural claim products from conventional formulations and commodity extracts. Pricing pressure stems from REACH-driven reformulation costs in European export channels. Food manufacturers exhibit lowest price sensitivity due to specification rigidity, while fragmented restaurant operators negotiate hardest on per-unit seasoning blend costs.
Supply Chain Analysis
African swine fever recurrence risk in Chinese provincial clusters threatens porcine tissue availability for thermal process flavor production. Raw material sourcing draws from Jiangsu and Shandong provinces, with enzyme modification feedstocks and pyrolysis substrates imported from Germany and Japan. Single-source vulnerability concentrates in domestic tissue processing infrastructure. Distribution runs through direct sales channels for liquid flavors and consolidated distributor networks for dry seasoning blends.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in species-specific Maillard pathway control remains concentrated among senior practitioners in European and Japanese technical centers, constraining capacity expansion for clean-label reaction flavor production.
For Market Incumbents: Entrench position through backward integration into porcine tissue sourcing in Jiangsu province and investment in continuous thermal processing systems achieving batch-to-batch consistency. Plant protein hydrolysate substitution in meat-analog applications threatens traditional substrate demand. SAMR natural claim substantiation capability is the critical defensive lever. For New Entrants and Emerging Players: Southeast Asian export markets, particularly Indonesian and Vietnamese instant noodle producers, absorb expanding pork flavor volumes with less stringent documentation requirements than Chinese domestic buyers. Technical partnerships with regional compounders lacking Maillard optimization capability offer the most penetrable entry path. Licensing smoke and roast reaction technology from specialized Japanese houses accelerates product credibility. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mid-scale compounders in the Cologne-Düsseldorf chemical cluster possessing EFSA-compliant documentation libraries. Long-term viability hinges on bioprocess capacity for fermentation-derived natural claims. Watch for SAMR clarification on enzyme-modified extract classification as the inflection signal for compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Maillard Reaction Technology Licensing | Japanese specialized houses control species-specific aroma chemistry patents for premium processed meat applications. |
| Backward Integration into Tissue Sourcing | Kerry Group's captive porcine supply in Jiangsu province sustains cost advantages across Asian markets. |
| GB Standards Compliance Certification | SAMR analytical laboratory requirements are accelerating domestic producer consolidation toward technical specialists. |
| Bioprocess Capacity Investment | Fermentation-derived flavor classification clarity enables defined compliance boundaries for natural claim substantiation. |
| Direct Sales Channel Expansion | Centralized kitchen models in Shanghai and Beijing displace fragmented distributor relationships with manufacturer contracts. |
Research Methodology
Initial hypotheses were tested against primary input from flavor chemists, food manufacturer procurement directors, SAMR regulatory consultants, and restaurant chain supply chain managers and refined through secondary validation. Trade data from Chinese customs authorities, EFSA substance evaluation registers, GB standards documentation, and savory flavor patent filings anchored quantitative estimates. Bottom-up volume modeling across product types and end-use segments triangulated against top-down value projections from ingredient conglomerate segment disclosures.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation by product type, end user, distribution channel, and flavor profile modeled independently. CAGRs were derived from fitted growth curves applied to base-year estimates, cross-checked against capacity expansion announcements and procurement contract visibility. Maillard reaction technology deployment timelines and SAMR enforcement intensity served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plant protein analog producers or sudden SAMR classification shifts would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Beef Extract Market
Meat Products
Low-Fat Chorizo Market
Meat Products
United Arab Emirates Red Meat Market
Meat Products
India Animal Protein Market
Meat Products
Global Poultry Meat Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Vegan Meatball Market
Meat Products
North America Bacon Market
Meat Products
Global Processed Pork Meat Market
Meat Products
Bacon Flavors Market
Meat Products
US Meat Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
Europe Meat Products Market
Meat Products
Blended Meat Market
Meat Products
Europe Bacon Market
Meat Products
Non-Veg Rte and Rtc Market