
 United States Paper Packaging Market | 2026-2036
United States Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Paper Packaging Market Intelligence
Multi-source procurement is recalibrating how American consumer brands secure fiber-based containment systems. Packaging Corporation of America leverages its integrated mill-to-box model to control cost volatility across the Midwest. Smurfit WestRock anchors national supply through its corrugated network spanning 30-plus states. Pratt Industries competes aggressively on 100% recycled-content positioning, differentiating its sustainability credentials in retail and food service channels.
United States paper packaging comprises engineered fiber structures—typically 90–350 gsm kraft or recycled linerboard, fluted into corrugated medium or flat-die-cut into folding cartons—designed to protect, contain, and display goods through distribution and retail environments. Kraft paper dominates the material tier for its tensile strength in heavy-duty shipping applications, while coated paper commands premium shelf-facing segments in food and beverage end-use where grease resistance and print fidelity matter. Boxes lead product-type volume due to e-commerce fulfillment scale, yet wraps and sheets represent the fastest-expanding category as brands reduce plastic film substitution in produce and protein packaging.
FDA food-contact substance regulations and EPA recycled fiber standards shape material compliance thresholds for domestic producers, while OSHA workplace safety rules govern converting-plant operational permits. State-level extended producer responsibility frameworks in California, Oregon, and Maine are tightening post-consumer recovery targets, forcing converters to certify chain-of-custody documentation. Stakeholders must monitor how fragmented state legislation interacts with federal procurement guidelines to avoid supply chain disqualification.
Market Dynamics
E-commerce fulfillment networks are recalibrating corrugated demand patterns across the United States, while EPA recycled content mandates and state-level extended producer responsibility laws compress virgin fiber sourcing options for domestic converters.
Growth Catalysts
- State-level EPR frameworks:California, Oregon, and Maine extended producer responsibility laws mandate post-consumer recovery targets that force brands toward certified recycled-content packaging, pulling demand through certified supply chains.
- E-commerce fulfillment density:Corrugated shipping container consumption concentrates in the Great Lakes manufacturing corridor and Southeastern pulp-and-paper belt, anchoring regional capacity expansion.
- Food service substitution:Quick-service restaurants and grocery retailers are displacing plastic film with kraft paper wraps and sheets for produce and protein containment, opening new volume channels.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container pricing fluctuates with municipal collection system efficiency, squeezing converter margins when collection rates dip below supply thresholds.
- Southeastern pulp concentration:Integrated virgin linerboard production clusters along the Georgia-Alabama corridor, creating geographic supply risk during hurricane season disruptions.
- Barrier coating limitations:Water-based and bio-based grease-resistant coatings fail to match polyethylene performance in high-moisture frozen food applications, restricting material substitution depth.
Strategic Opportunities
- Midwest agricultural packaging:Underpenetrated grain and protein processing facilities in Iowa, Nebraska, and Kansas present white space for automated case-packing systems paired with domestic corrugated supply.
- FDA food-contact certification acceleration:Streamlined notification pathways for recycled fiber food-contact substances enable faster time-to-market for sustainable primary packaging in dairy and dry goods.
- Digital printing convergence:Single-pass inkjet integration with die-cutting lines enables lot-size-one customization for direct-to-consumer brands, compressing minimum order quantities.
Industry Challenges
- Converting technician scarcity:Skilled folder-gluer and rotary die-cutter operators are retiring faster than vocational programs replenish the workforce, constraining plant utilization rates.
- Chain-of-custody audit burden:FSC and SFI certification documentation requirements multiply with multi-source recycled fiber procurement, extending compliance timelines by 30-60 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Paper Packaging Market |
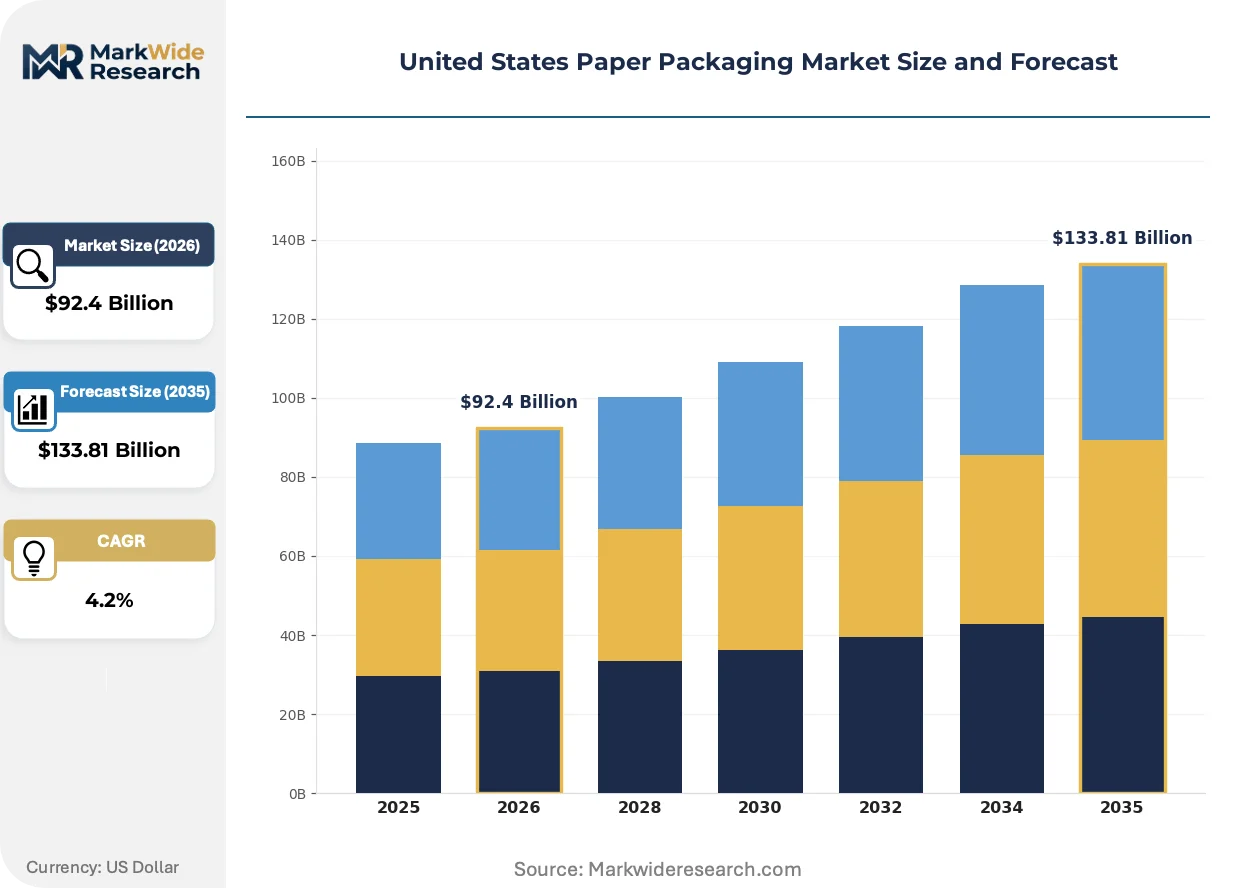
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $133.81 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wraps, Sheets Material: Kraft Paper, Recycled Paper, Coated Paper, Duplex Board End User: Food & Beverage, Healthcare, Retail, Consumer Goods Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Packaging Corporation of America, Cascades Inc., International Paper Company, Pratt Industries, Crown Holdings Inc., Smurfit WestRock, Graphic Packaging Holding Company, Pactiv Evergreen, Berry Global Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Paper Packaging Market Strategic Shifts & Innovations
Material science advances and regulatory pressure are compressing the viable design space for fiber-based containment, forcing simultaneous performance upgrades and sustainability credentialing across the value chain.
Molded fiber technology is expanding into protective packaging applications previously dominated by expanded polystyrene. Electronics and appliance manufacturers are adopting pulp-molded corner protectors and cushion sets at accelerating pace. This displacement is compressing foam converter margins while creating captive demand for specific pulp grades in the Southeastern United States.
EPA recycled fiber standards are tightening post-consumer content thresholds for federal procurement eligibility. Domestic converters must now certify minimum 35% recycled content to qualify for General Services Administration supply contracts. Food and beverage end-use segments are responding by dual-sourcing virgin and recycled linerboard to maintain compliance optionality.
Direct procurement relationships between consumer brands and integrated mill-to-box producers are displacing traditional distributor intermediaries in corrugated supply. Large retail and e-commerce operators are negotiating multi-year volume commitments with Packaging Corporation of America and Smurfit WestRock directly. This channel compression is most visible in the Midwest and Southeast, where fulfillment center density supports dedicated mill supply arrangements.
United States Paper Packaging Market Segmentation
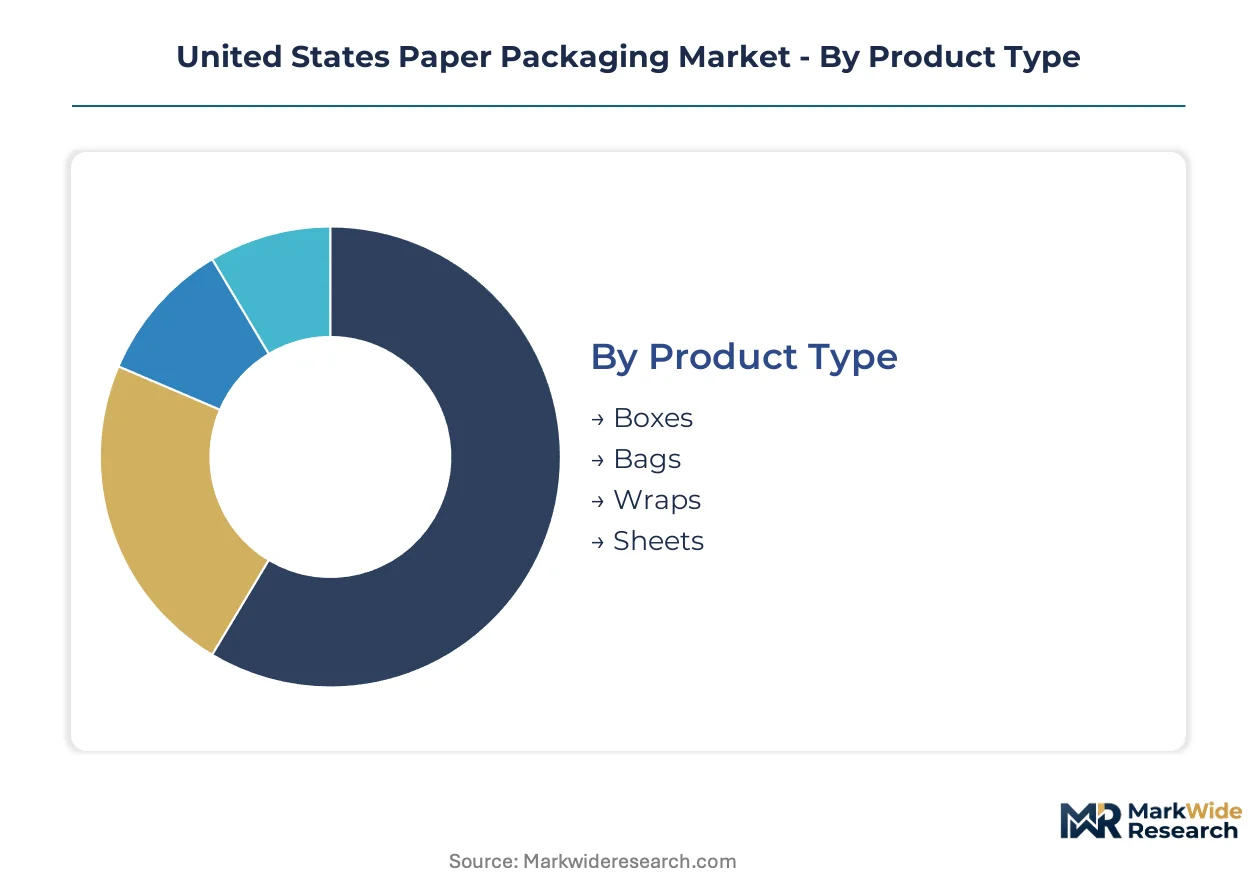
Segmentation in the United States paper packaging market reveals how procurement decisions fragment across performance requirements, regulatory compliance, and supply chain proximity. Understanding these divides enables converters to align capacity investments with where volume concentrates and where specifications are tightening fastest.
Product Type:
Shipper economics and fulfillment velocity determine which containment formats brands specify for their distribution networks.
- Boxes:Corrugated shipping containers built from 90–350 gsm linerboard and fluted medium dominate e-commerce fulfillment and industrial distribution. Demand concentrates in the Great Lakes manufacturing corridor and Southeastern pulp-and-paper belt, where integrated mill networks anchor supply reliability for Amazon, Walmart, and Target fulfillment centers.
- Wraps:Flat kraft paper sheets and roll stock serve quick-service restaurants and grocery retailers displacing plastic film for produce and protein containment. Food service substitution is accelerating fastest in California and Oregon, where state-level extended producer responsibility laws mandate certified recycled content.
- Bags:Multiwall and pinch-bottom sacks carry bulk dry goods, chemicals, and agricultural inputs. Cement and grain processors in Iowa and Nebraska drive specification for high-burst-strength constructions.
- Sheets:Interleaving and pallet slip sheets protect unitized loads during transit. Automated warehouse investments in Texas and Georgia are expanding demand for precision-die-cut formats.
Volume sits with boxes; growth tilts toward wraps.
Material:
Performance specifications and FDA food-contact compliance thresholds sort fiber grades into distinct procurement tiers.
- Kraft Paper:Virgin unbleached sulfate pulp delivers tensile strength for heavy-duty shipping and industrial containment. Georgia-Pacific and International Paper anchor virgin linerboard supply along the Georgia-Alabama corridor, though hurricane season disruptions create geographic risk concentration.
- Recycled Paper:Post-consumer old corrugated container fiber feeds EPA-mandated minimum 35% content thresholds for federal procurement eligibility. California, Oregon, and Maine extended producer responsibility frameworks are tightening certified chain-of-custody documentation requirements.
- Coated Paper:Clay or polymer surface treatments enable high-fidelity printing and grease resistance for premium retail-facing applications. Dairy and dry goods brands specify coated grades where shelf presence drives purchase decisions.
- Duplex Board:Grey-back or white-back laminated constructions balance stiffness and cost for folding cartons and display packaging. Cosmetic and electronics brands in New Jersey and Illinois specify duplex for point-of-sale differentiation.
Procurement weight rests with kraft paper; specification momentum favors recycled grades.
End User:
Regulatory exposure and contamination sensitivity determine fiber grade selection and barrier coating requirements.
- Food & Beverage:Primary and secondary packaging for perishables, dry goods, and beverages demands FDA food-contact substance compliance. Water-based grease-resistant coatings are displacing polyethylene in frozen food applications, though performance gaps persist in high-moisture environments.
- Retail:Corrugated displays and shelf-ready packaging serve big-box and grocery channels. Direct procurement relationships between retailers and integrated mill-to-box producers are compressing distributor intermediaries in the Midwest and Southeast.
- Healthcare:Sterile barrier systems and pharmaceutical secondary packaging require particulate control and lot-traceability. FDA 21 CFR compliance and USP <661> testing constrain supplier qualification.
- Consumer Goods:Electronics, appliances, and personal care products specify molded fiber protective packaging. Pulp-molded corner protectors are displacing expanded polystyrene in the Southeastern United States where captive pulp supply supports conversion.
Food and beverage commands the largest procurement volume; healthcare imposes the tightest compliance burden.
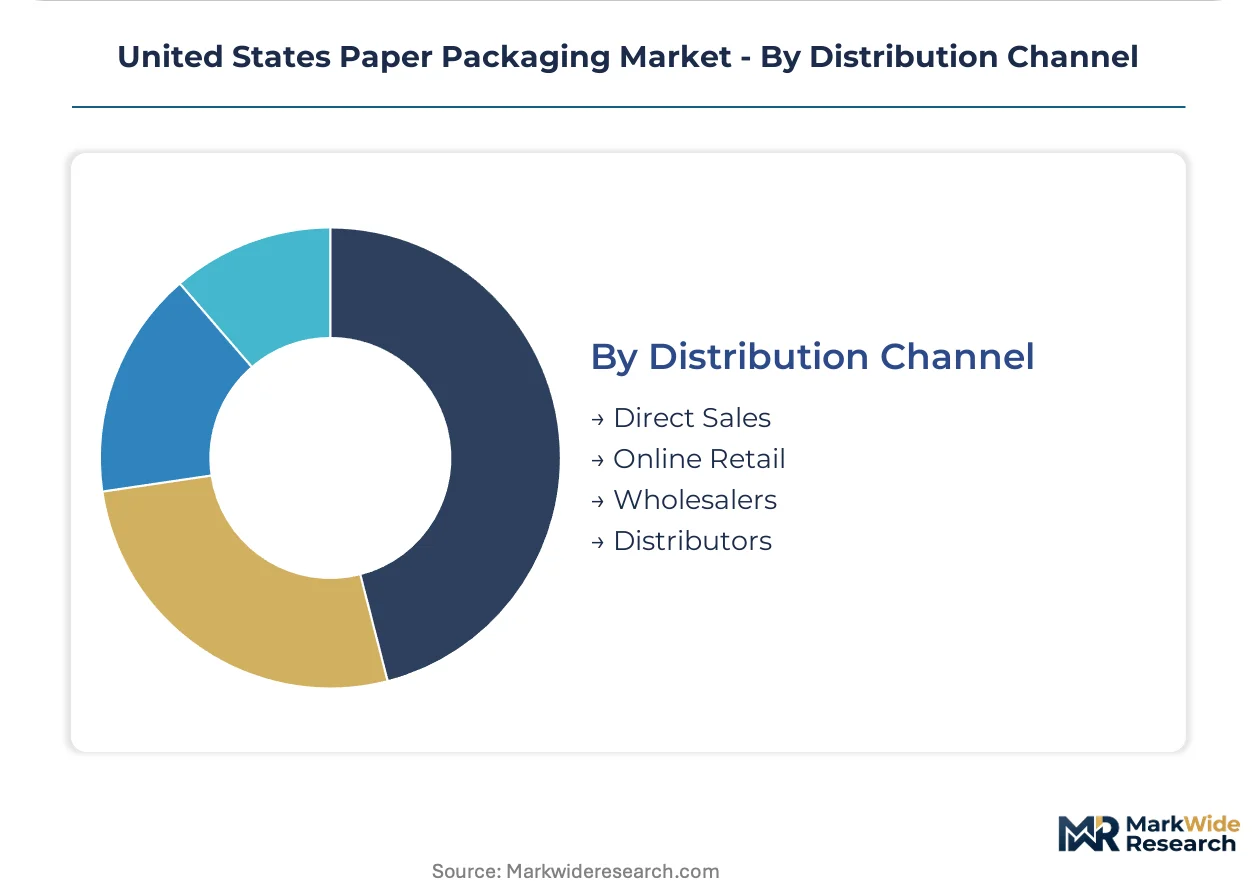
Distribution Channel:
Order scale and customization depth determine whether brands source through intermediaries or direct mill relationships.
- Direct Sales:Multi-year volume commitments between large retail and e-commerce operators and integrated producers Packaging Corporation of America and Smurfit WestRock. Channel compression is most visible where fulfillment center density supports dedicated mill supply arrangements.
- Distributors:Regional converters and independent box plants serve mid-tier brands requiring smaller lot sizes and faster turnaround. Inventory pooling and logistics coordination justify margin capture for fragmented demand.
- Online Retail:Digital platforms aggregate specification templates and quote comparison for small-to-mid shippers. Minimum order quantity compression from digital printing convergence is enabling lot-size-one procurement for direct-to-consumer brands.
- Wholesalers:Stock-and-defer models for standardized box sizes and commodity grades. Price transparency and working capital efficiency appeal to seasonal agricultural shippers in the Midwest.
Direct sales anchor volume concentration; online retail is expanding fastest at the small-lot frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virgin linerboard production clusters along the Georgia-Alabama corridor anchor national supply, while recycled fiber processing concentrates in the Great Lakes and Pacific Northwest. State-level extended producer responsibility laws in California, Oregon, and Maine are reshaping regional procurement patterns.
California
E-commerce fulfillment centers in the Inland Empire and Central Valley drive corrugated consumption for Amazon and Walmart distribution networks. The state's extended producer responsibility law mandates certified recycled content thresholds, pushing converters toward chain-of-custody documentation. Los Angeles Basin converters are expanding water-based coating capacity to meet food-contact compliance for quick-service restaurant packaging.
Texas
Petrochemical corridor proximity supports polyethylene-coated paperboard for frozen food applications, though bio-based barrier development is accelerating in Houston research clusters. Automated warehouse investments in Dallas-Fort Worth are expanding demand for precision-die-cut pallet slip sheets. San Antonio food processors are sourcing multiwall sacks for bulk dry goods distribution.
Illinois
Chicago's rail and intermodal hub status positions the state as a corrugated distribution nexus for Midwest manufacturing. FDA food-contact substance regulations govern dairy and dry goods packaging specifications for processors in the Rockford-Beloit corridor. Graphic Packaging and Crown Holdings maintain folding carton capacity in the greater Chicago area for retail-facing applications.
Georgia
Integrated virgin linerboard mills along the Savannah River corridor supply heavy-duty shipping containers for Southeastern fulfillment networks. Hurricane season disruptions create periodic supply risk concentration that converters mitigate through inventory pre-positioning. Atlanta's logistics infrastructure anchors regional distribution for Smurfit WestRock and International Paper mill networks.
Ohio
Packaging Corporation of America's integrated mill-to-box model concentrates converting capacity in the Toledo-Cleveland corridor for Midwest automotive and appliance manufacturers. OSHA workplace safety rules govern rotary die-cutter and folder-gluer operations across the state's converting plants. Columbus-area food processors are specifying molded fiber protective packaging for electronics shipments.
United States Paper Packaging Market Key Industry Players
Global majors compete with regional champions across mill-to-box integration and recycled-content positioning. The vendor base stratifies into three tiers: integrated producers with captive pulp supply, independent converters sourcing open-market linerboard, and specialty players focused on certified sustainable grades. Strategic archetypes include scale-driven volume suppliers, sustainability-differentiated niche operators, and logistics-integrated regional champions. Dominant competitive moves center on backward integration into recycled fiber collection networks and direct procurement relationships with large retail operators.
Within the integrated producer tier, Packaging Corporation of America exemplifies the mill-to-box model controlling cost volatility across Midwest manufacturing corridors. Smurfit WestRock occupies a position anchoring national corrugated supply through extensive converting networks. Pratt Industries represents the 100% recycled-content archetype, differentiating on sustainability credentials in retail and food service channels.
| Leading Market Players |
|---|
| Packaging Corporation of America |
| Cascades Inc. |
| International Paper Company |
| Pratt Industries |
| Crown Holdings Inc. |
| Smurfit WestRock |
| Graphic Packaging Holding Company |
| Pactiv Evergreen |
| Berry Global Group Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap converters in the Midwest and Southeast maintain pricing discipline through captive recycled fiber collection networks, insulating their corrugated operations from Old Corrugated Container spot-market volatility while passing through EPA compliance premiums to federal procurement accounts.
Pricing Analysis
Freight and die-cut tooling warranties bundle into multi-year corrugated supply contracts, while unbundled spot purchases expose buyers to fuel surcharge volatility. Three-tier pricing structure across virgin kraft, certified recycled, and coated food-contact grades sorts buyers by FDA compliance tier and volume commitment scale. Pricing pressure stems from integrated mill-to-box producers absorbing logistics costs to capture direct retail relationships. Small-to-mid shippers through online retail platforms exhibit highest price sensitivity; federal GSA contractors demonstrate lowest due to compliance-driven specification rigidity.
Supply Chain Analysis
Virgin linerboard supply rests on integrated pulp mills concentrated in Georgia, Alabama, and South Carolina, where hurricane exposure creates seasonal supply vulnerability. Recycled fiber feeds from municipal collection systems across the Great Lakes and Pacific Northwest; water-based barrier coatings and starch adhesives constitute critical chemical inputs. Single-source vulnerability concentrates in the Savannah River corridor during storm season. Distribution runs through dedicated mill-direct arrangements for large e-commerce operators and regional distributor networks for fragmented agricultural and food service demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
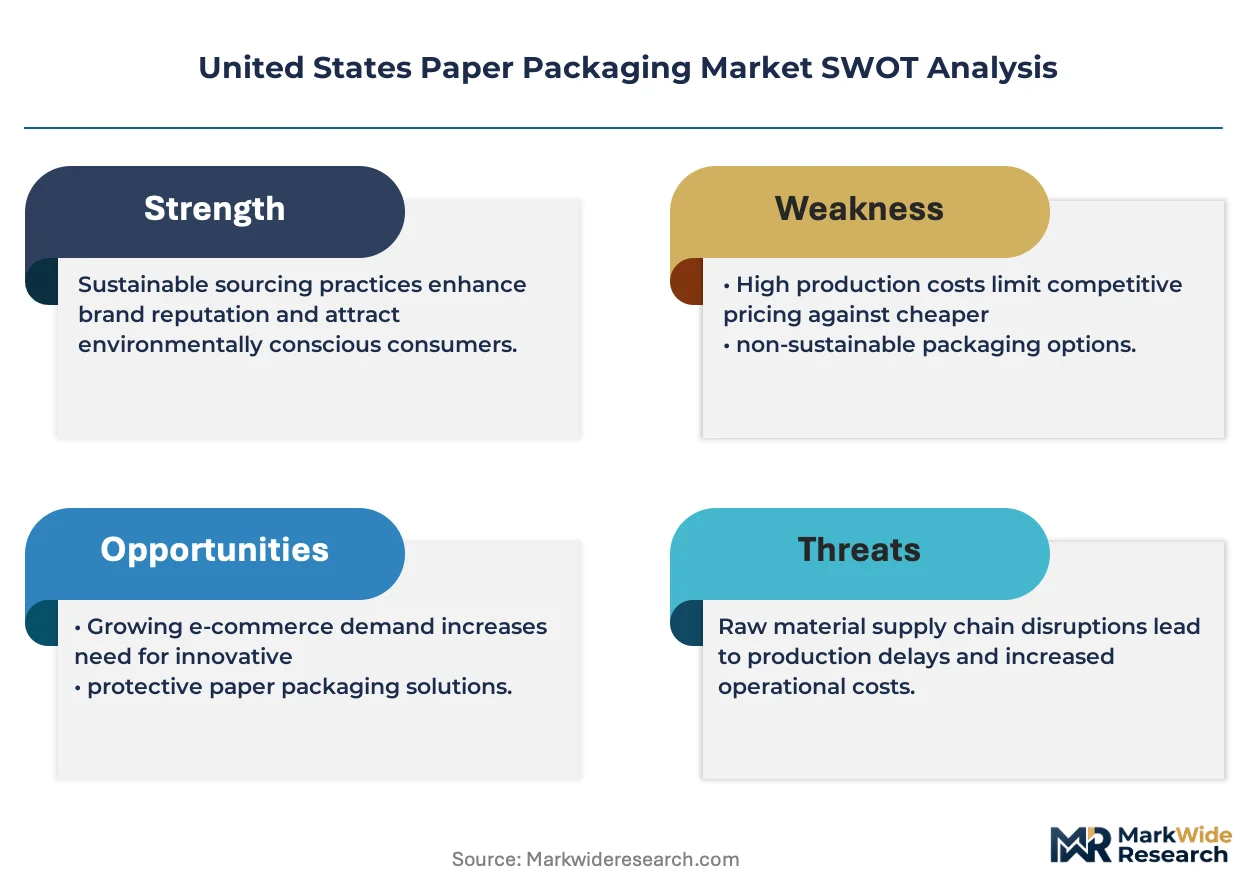
EPA recycled content mandates and state-level extended producer responsibility laws in California, Oregon, and Maine erect compliance moats that favor incumbents with certified chain-of-custody infrastructure, raising capital barriers for speculative entrants.
For Market Incumbents: Deepen backward integration into OCC collection networks across the Great Lakes to secure fiber supply during municipal collection shortfalls. Expand water-based coating capacity in Los Angeles Basin to capture quick-service restaurant substitution demand from plastic film. Defend against Pratt Industries' 100% recycled-content positioning by dual-sourcing virgin and recycled linerboard to maintain federal procurement optionality. For New Entrants and Emerging Players: Digital printing-enabled lot-size-one customization offers a technology-first wedge into direct-to-consumer brand packaging in underpenetrated Iowa and Nebraska grain processing corridors. Target automated case-packing system integration for Midwest agricultural facilities lacking dedicated corrugated supply relationships. Pursue FDA food-contact substance notification acceleration as a go-to-market differentiator for dairy and dry goods primary packaging. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional converters with FSC-certified capacity in Pacific Northwest and New England markets where EPR laws tighten fastest. Long-term viability hinges on positioning for post-consumer recovery target escalation across multiple state jurisdictions. Monitor Old Corrugated Container pricing spreads as an inflection signal for integrated versus independent converter margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Collection | Captive fiber supply insulates Packaging Corporation of America from municipal collection volatility. |
| Water-Based Coating Capacity Expansion | Los Angeles Basin investments capture California quick-service restaurant substitution mandates. |
| Digital Printing Line Integration | Single-pass inkjet convergence enables lot-size-one procurement for direct-to-consumer brands. |
| FDA Food-Contact Certification Acceleration | Streamlined notification pathways compress time-to-market for sustainable dairy packaging. |
| Direct Mill-to-Retail Procurement Relationships | Multi-year volume commitments with Amazon displace distributor intermediaries in Midwest. |
Research Approach
Independent corroboration across mill operations executives, corrugated procurement managers at e-commerce fulfillment networks, and FDA regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from EPA recycled fiber standard filings, state EPR regulatory dockets in California and Oregon, and SEC disclosures from integrated producers. Bottom-up capacity assessments triangulate against top-down consumption estimates from retail distribution data.
Comparable historical periods anchor volume and value projections across the analysis window, with segmentation modeled by product type, material grade, end-use industry, and distribution channel. CAGRs derive from trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporate e-commerce fulfillment center buildout schedules and state-level EPR implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under hurricane disruption scenarios or sudden OCC collection rate declines. A small set of named triggers warrants ongoing watch: EPA threshold revisions, Maine EPR enforcement intensity, and Georgia-Alabama corridor weather patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
India Paper Packaging Market
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
Compostable Paper Tray Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Carrier Bags Market