
 Maritime Drone Market | 2026-2036
Maritime Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Maritime Drone Market Insights
Buyer concentration among oil and gas operators is pivoting as national oil companies diversify supplier rosters while independent offshore contractors multiply fleet orders. L3Harris Technologies leverages its sonar integration heritage to dominate government maritime programs. Kongsberg Gruppen anchors Nordic demand through its in-house production of autonomous underwater vehicle propulsion systems. Elbit Systems competes aggressively in Mediterranean and Asia-Pacific naval tenders with combat-proven surface drone architectures.
Maritime drones encompass unmanned platforms operating on or below the waterline, typically incorporating pressure-rated hull composites, lithium-sulfur battery packs, and multi-beam echo sounders for bathymetric mapping. These systems execute missions in environments where crewed vessel operations prove hazardous or economically unworkable. Unmanned Surface Vehicles currently occupy the largest revenue pool due to port security patrol contracts and offshore logistics support. Unmanned Underwater Vehicles represent the fastest-expanding segment as seabed mining exploration licenses activate in the Pacific Clarion-Clipperton Zone. Artificial Intelligence integration across both categories now determines bid competitiveness in NATO naval procurement cycles.
The International Maritime Organization has advanced its regulatory scoping exercise for Maritime Autonomous Surface Ships, while the United States Coast Guard enforces specific unmanned vessel reporting protocols under its Ports and Waterways Safety Act authority. Classification societies including DNV and Lloyd's Register have published separate guidelines for autonomous navigation system certification, creating divergent compliance pathways across flag states. Stakeholders must monitor which certification framework achieves dominant reference status among major port authorities and underwriters.
Market Dynamics
The maritime drone sector is restructuring around collision-avoidance AI mandates from classification societies, which now require autonomous navigation certification before hull insurance coverage activates. This regulatory pressure is compressing development timelines for platform developers while elevating systems integrators with proven sensor fusion track records.
Growth Catalysts
- IMO Regulatory Scoping Exercise:The International Maritime Organization's advancing framework for Maritime Autonomous Surface Ships creates compliance-driven replacement cycles for legacy inspection fleets across flag states.
- Seabed Mining Exploration:Pacific Clarion-Clipperton Zone license activations generate demand for deep-rated Unmanned Underwater Vehicles capable of polymetallic nodule survey operations.
- Lithium-Sulfur Battery Maturation:Energy density improvements in pressure-rated power systems extend mission endurance for subsea pipeline surveys beyond current lithium-ion limitations.
Market Restraints
- Classification Divergence:DNV and Lloyd's Register maintain separate autonomous navigation certification pathways, forcing dual-track compliance expenditure for multi-flag operators.
- Rare Earth Magnet Supply:Permanent magnet propulsion motor production concentrates in Chinese processing facilities, exposing AUV manufacturers to export restriction volatility.
- Acoustic Communication Bandwidth:Underwater data transmission rates constrain real-time command-and-control for deep-rated platforms operating below 3,000 meters.
Strategic Opportunities
- Port Security Modernization:United States Coast Guard unmanned vessel reporting protocols under Ports and Waterways Safety Act authority accelerate harbor patrol fleet conversions.
- AI-Sonar Convergence:Machine learning integration with multi-beam echo sounders enables autonomous target recognition for mine countermeasures without human-in-the-loop verification.
- Norwegian Subsea Infrastructure:Aging North Sea pipeline networks require continuous survey coverage that crewed vessels cannot economically provide.
Industry Challenges
- Maritime AI Certification Timelines:NATO naval procurement cycles now embed algorithmic validation requirements that extend bid-to-contract intervals by 18-24 months.
- Pressure Hull Composite Fabrication:Qualified manufacturing capacity for depth-rated carbon fiber cylinders concentrates in Nordic and Japanese specialist facilities.
- Cross-Domain Integration Complexity:Surface drone fleets must interoperate with existing satellite communication constellations and shore-based command centers built for crewed vessel traffic management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maritime Drone Market |
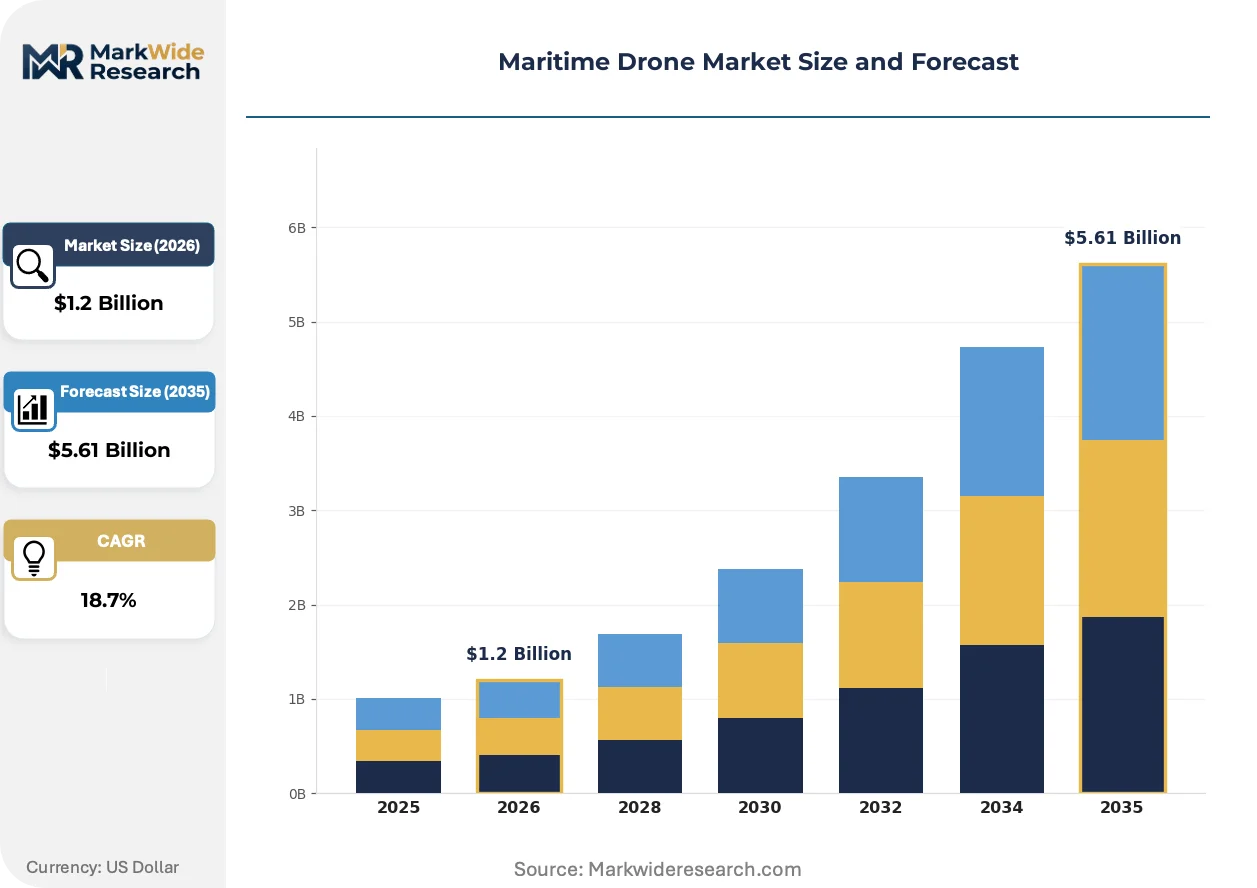
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $5.61 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unmanned Surface Vehicles, Unmanned Underwater Vehicles, Remotely Operated Vehicles, Hybrid Drones Application: Surveillance, Environmental Monitoring, Search & Rescue, Offshore Inspection, Marine Research Technology: Autonomous Navigation, Remote Control, Artificial Intelligence, Sonar Imaging, Radio Frequency Identification End User: Coast Guard, Research Institutions, Commercial Shipping, Oil & Gas Operators, Port Authorities |
| Companies Covered | L3Harris Technologies, Textron Systems, Elbit Systems, Kongsberg Gruppen, Saab AB, Teledyne Technologies, Northrop Grumman Corporation, Lockheed Martin Corporation, Ocean Infinity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maritime Drone Market Trends and Innovations
Autonomous platform development is converging on edge-computing architectures that process sensor data locally rather than transmitting raw feeds to shore stations. This shift reduces bandwidth requirements while enabling faster decision loops for collision avoidance and target identification.
Sensor fusion middleware is unifying previously separate sonar, optical, and radar processing streams into single computational pipelines. Offshore inspection contractors at oil and gas operators are deploying these integrated systems for simultaneous bathymetric mapping and subsea asset condition assessment. The compression of hardware integration timelines is forcing traditional sonar specialists to partner with AI software houses or cede platform-level contracts.
The United States Coast Guard has formalized unmanned vessel reporting protocols under its Ports and Waterways Safety Act authority, creating the first federal enforcement mechanism for autonomous surface operations in US waters. Commercial harbor operators must now integrate drone traffic into existing vessel traffic service systems. Port authorities in Houston and Long Beach are responding by funding dedicated autonomous vessel monitoring centers separate from legacy radar installations.
Buyer contracting patterns are fragmenting from multi-year platform purchases toward mission-service agreements where operators pay per kilometer of pipeline surveyed. Independent offshore contractors in the North Sea corridor are displacing integrated energy majors as the primary fleet purchasers. Norwegian classification society DNV has responded by developing outcome-based certification modules that validate operational capability rather than design specifications alone.
Maritime Drone Market Segmentation
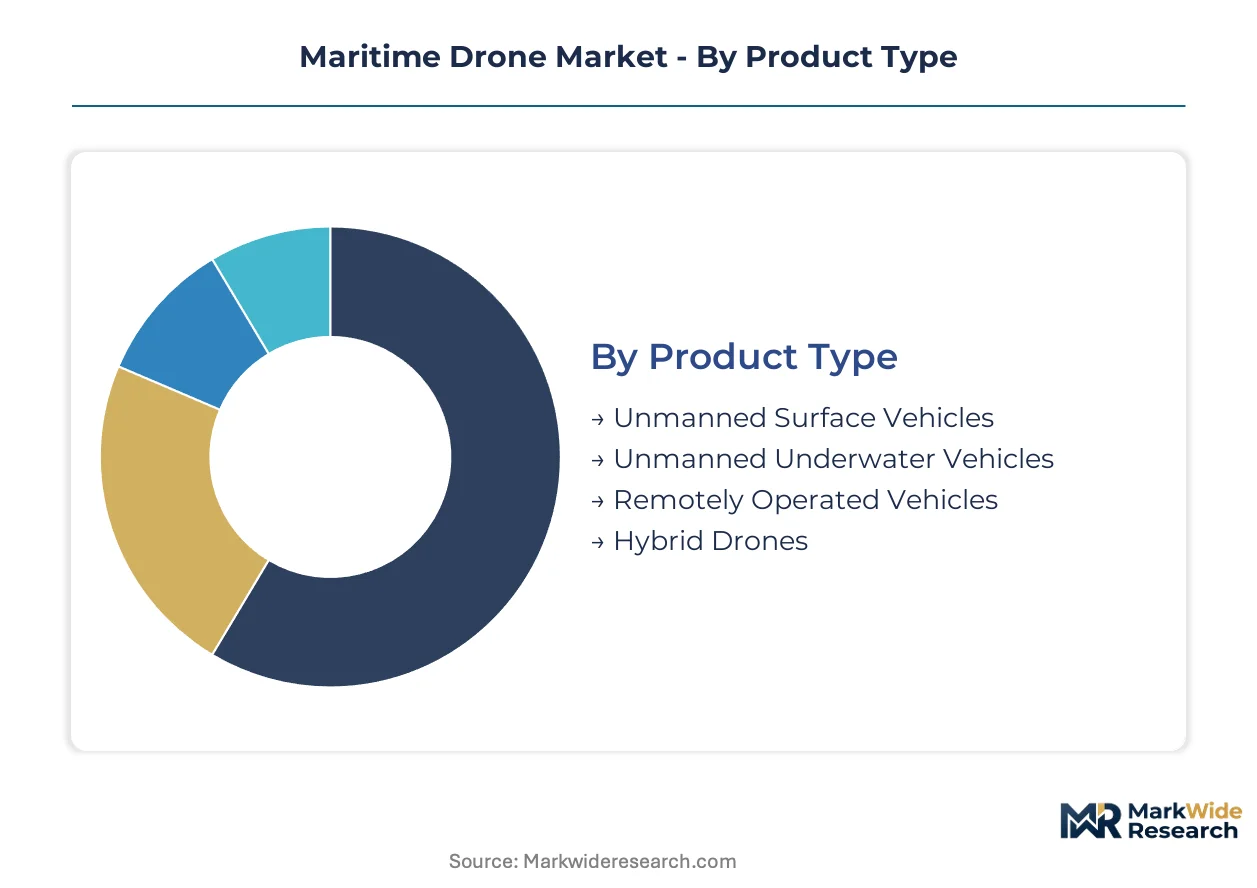
Segmentation reveals how maritime drone procurement diverges across operational environments and buyer risk tolerances. Platform specifications, autonomy levels, and sensor payloads vary sharply between harbor security contracts and deep-seabed exploration missions.
Product Type:
Buyers differentiate primarily by depth rating requirements and surface endurance needs, with offshore energy operators demanding pressure-hardened hulls while port authorities prioritize collision-avoidance AI.
- Unmanned Surface Vehicles:These platforms operate at the air-sea interface with composite hulls and lithium-sulfur battery packs for extended patrol cycles. Coast Guard harbor security contracts in the United States and Singapore concentrate demand here, driven by federal unmanned vessel reporting mandates under Ports and Waterways Safety Act authority.
- Unmanned Underwater Vehicles:Pressure-rated carbon fiber cylinders and multi-beam echo sounders enable bathymetric mapping below 3,000 meters. Pacific Clarion-Clipperton Zone seabed mining licenses activate demand from research consortia and mineral exploration firms seeking polymetallic nodule survey capability.
- Remotely Operated Vehicles:Tethered power and data links support heavy intervention tasks on subsea pipelines and wellheads. Norwegian North Sea operators deploy these for aging infrastructure inspection where real-time human control remains mandatory.
- Hybrid Drones:Dual-mode architectures transition between surface transit and submerged operation. Experimental programs at NATO naval research centers evaluate these for mine countermeasures requiring rapid area coverage followed by covert inspection.
Unmanned Surface Vehicles lead volumes today; Unmanned Underwater Vehicles is gaining share fastest.
Application:
Mission type determines sensor payload configuration and autonomy certification tier, with regulatory frameworks from classification societies creating divergent compliance costs across use cases.
- Surveillance:Continuous perimeter monitoring for port facilities and offshore installations demands radar and optical sensor fusion with edge-computing collision avoidance. United States Coast Guard unmanned vessel protocols accelerate harbor patrol fleet conversions at Houston and Long Beach.
- Environmental Monitoring:Water quality sampling and marine ecosystem tracking require biofouling-resistant sensor housings and extended loiter capability. Research institutions in Norway and Singapore fund these deployments for climate impact assessment in the North Sea and Pacific reef systems.
- Search & Rescue:Thermal imaging and acoustic locating systems support emergency response in hazardous sea states. Coast Guard organizations prioritize these platforms for crew recovery operations where manned helicopter deployment carries excessive risk.
- Offshore Inspection:Subsea pipeline and riser assessment combines multi-beam sonar with magnetic flux leakage sensors. Oil and gas operators in the North Sea corridor are shifting from crewed vessel contracts to autonomous fleet service agreements for aging infrastructure.
- Marine Research:Deep-ocean sampling and benthic habitat mapping require pressure-rated instrument payloads and precision navigation. Academic institutions and government oceanographic agencies in the United States, Japan, and Norway drive specialized procurement cycles.
Offshore Inspection commands the largest contract values; Environmental Monitoring shows the steepest expansion trajectory as regulatory disclosure requirements multiply.
Technology:
Technology selection separates premium platform tiers from commodity alternatives, with AI integration and sensor fusion middleware now determining bid competitiveness in NATO and allied naval programs.
- Autonomous Navigation:Collision-avoidance algorithms and path-planning systems enable reduced-crew or crewless operations. Classification societies in Norway, the United States, and Singapore require certification before hull insurance coverage activates, compressing development timelines for platform developers.
- Remote Control:Tethered or radio-linked piloting maintains human-in-the-loop command for high-stakes intervention tasks. Remotely Operated Vehicle operators in the North Sea prefer this architecture for subsea pipeline repair where autonomous decision-making carries unacceptable liability.
- Artificial Intelligence:Machine learning integration with sonar data enables autonomous target recognition without human verification. NATO naval procurement cycles now embed algorithmic validation requirements that extend bid-to-contract intervals.
- Sonar Imaging:Multi-beam and synthetic aperture systems generate bathymetric maps and subsea asset condition assessments. Offshore inspection contractors deploy these for simultaneous pipeline survey and structural integrity evaluation.
- Radio Frequency Identification:Short-range tracking and asset tagging support inventory management in port logistics applications. Commercial shipping operators trial these systems for container yard automation and vessel traffic coordination.
Remote Control dominates current installed base; Artificial Intelligence is climbing the fastest as classification societies mandate autonomous navigation certification.
End User:
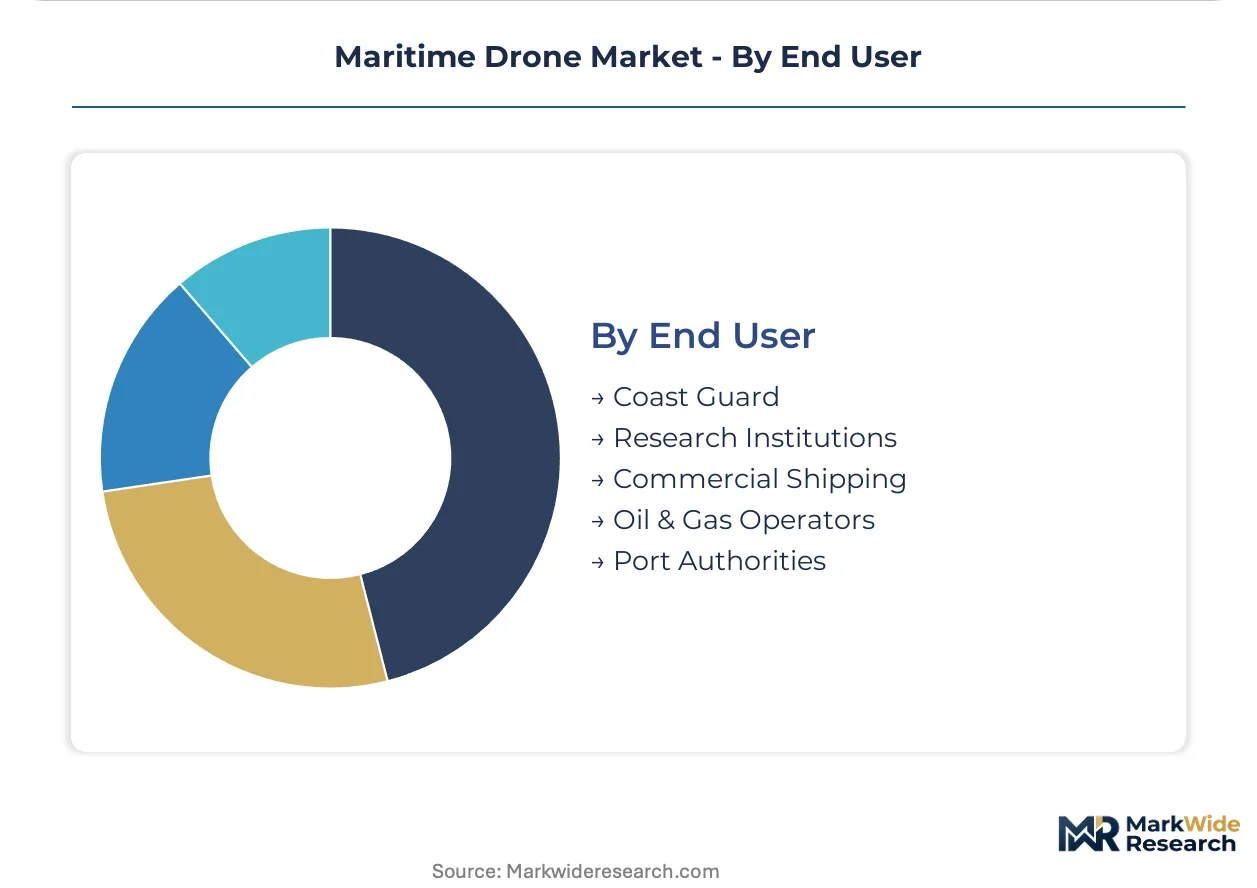
End user category dictates procurement scale, contract structure, and regulatory compliance pathway, with government programs favoring multi-year platform purchases while commercial operators shift toward mission-service agreements.
- Coast Guard:Harbor patrol and maritime border security programs require interoperable command-and-control with existing vessel traffic service systems. The United States Coast Guard enforces specific unmanned vessel reporting protocols, creating dedicated procurement channels.
- Research Institutions:Academic and government oceanographic programs prioritize sensor flexibility and data quality over operational tempo. Norwegian, Japanese, and American research fleets drive demand for deep-rated Unmanned Underwater Vehicles with customizable instrument payloads.
- Commercial Shipping:Container lines and bulk carriers evaluate autonomous platforms for hull inspection and anti-fouling monitoring between port calls. Classification society guidelines from DNV and Lloyd's Register create divergent compliance pathways across flag states.
- Oil & Gas Operators:Energy majors and independent offshore contractors deploy autonomous fleets for subsea pipeline surveys where crewed vessel economics fail. Buyer concentration is pivoting as national oil companies diversify supplier rosters and independents multiply fleet orders.
- Port Authorities:Harbor operators fund autonomous vessel monitoring centers separate from legacy radar installations. Houston and Long Beach authorities lead infrastructure investment in response to United States Coast Guard unmanned vessel protocols.
Oil & Gas Operators anchor procurement volumes today; Port Authorities are expanding most quickly as federal reporting mandates activate harbor modernization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway commands subsea infrastructure demand while Singapore drives port security procurement, creating divergent regulatory momentum across maritime corridors. National certification frameworks now determine fleet deployment economics in each jurisdiction.
United States
Coast Guard unmanned vessel protocols under Ports and Waterways Safety Act authority accelerate harbor patrol modernization at Houston and Long Beach. The Department of Homeland Security mandates interoperable command-and-control with legacy vessel traffic service systems. Gulf Coast energy operators deploy autonomous surface fleets for offshore logistics support.
Norway
Aging North Sea pipeline networks require continuous survey coverage beyond crewed vessel economics. DNV classification society develops outcome-based certification modules validating operational capability rather than design specifications alone. Stavanger and Bergen anchor subsea contractor clusters where independent fleet operators displace integrated energy majors.
Singapore
Port authority funding for dedicated autonomous vessel monitoring centers responds to federal maritime security directives. The Maritime and Port Authority of Singapore advances draft guidelines for unmanned vessel certification alongside harbor modernization budgets. Tuas mega-port development integrates drone traffic into automated container handling systems.
United Kingdom
Offshore wind farm expansion generates demand for subsea cable inspection platforms in North Sea lease zones. Lloyd's Register maintains separate autonomous navigation certification pathways from Nordic competitors, forcing dual-track compliance expenditure. Aberdeen retains subsea engineering concentration despite operator consolidation.
Japan
Deep-ocean research programs drive procurement of pressure-rated unmanned underwater vehicles for benthic habitat mapping. METI funding supports lithium-sulfur battery maturation for extended mission endurance below 3,000 meters. Yokosuka and Kobe harbor clusters develop specialized carbon fiber hull fabrication capacity.
Maritime Drone Market Competitive Landscape
Nordic producers anchor one tier; American defense contractors hold government maritime programs. The vendor base separates between systems integrators with sensor fusion track records and platform specialists with pressure-rated hull capabilities. Three archetypes dominate: sonar heritage players, in-house propulsion manufacturers, and combat-proven surface architects. Consolidation pressure elevates proven integrators while compressing development timelines for autonomous navigation certification.
Within the systems integration tier, L3Harris Technologies and Kongsberg Gruppen occupy positions shaped by distinct geographic and capability foundations. L3Harris represents American defense-industrial concentration in government maritime programs. Kongsberg Gruppen exemplifies Nordic vertical control through captive propulsion system production. Elbit Systems anchors a third vector as a Mediterranean-Asia-Pacific specialist in surface drone architectures.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Textron Systems |
| Elbit Systems |
| Kongsberg Gruppen |
| Saab AB |
| Teledyne Technologies |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Ocean Infinity |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber composite fabrication specialists in Norway and Japan command wage premiums that widen spreads between certified premium platforms and standard-grade alternatives. Labor-cost differentials in pressure-hull manufacturing cascade through tiered pricing structures as buyers weigh DNV certification premiums against Lloyd's Register pathway costs.
Pricing Analysis
Capacity additions in South Korean battery manufacturing are reshaping price floors for lithium-sulfur power systems that dominate endurance-rated platforms. Three-tier pricing structure across certified-premium, standard-compliant, and economy-grade levels separates DNV-validated autonomous navigation from Lloyd's Register alternatives. Pricing pressure stems from independent North Sea contractors consolidating fleet orders and demanding volume discounts. National oil companies exhibit lowest price sensitivity; port authorities face tightest budget constraints under federal reporting mandates.
Supply Chain Analysis
Workforce availability for deep-rated carbon fiber cylinder fabrication concentrates in Stavanger, Yokosuka, and Bergen manufacturing clusters. Rare earth magnet processing draws from Chinese facilities; pressure-rated battery cells rest on South Korean and Japanese production; multi-beam sonar arrays hinge on Norwegian and American sensor houses. Single-source vulnerability in permanent magnet supply exposes AUV manufacturers to export restriction volatility. Distribution runs through systems integrators with proven sensor fusion track records rather than direct platform sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in maritime drones rest on lithium-sulfur battery cost curves and the premium-tier shift toward AI-certified autonomous navigation. Buyers now pay for validated operational capability rather than hardware specifications alone.
For Market Incumbents: Lock in sensor fusion middleware partnerships before pure-play AI houses capture platform-level contracts. Secure captive supply of pressure-rated carbon fiber cylinders through long-term offtake agreements with Nordic fabricators. Classification society certification timelines compress development windows; early DNV outcome-based module validation creates switching costs for multi-flag operators. For New Entrants and Emerging Players: Offshore contractors in the North Sea corridor represent the most penetrable buyer segment as they displace integrated energy majors in fleet procurement. Target mission-service agreements rather than platform sales to bypass capital-intensive manufacturing scale requirements. Partner with established sonar heritage players for rapid sensor integration credibility. For Investors and Strategic Acquirers: Defense contractors with government maritime programs are the most active acquirer in this space, seeking proven autonomous navigation certification track records. Long-term viability centers on algorithmic validation capabilities that extend bid-to-contract intervals. Monitor NATO naval procurement cycle announcements for inflection signals in AI-sonar convergence demand.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Navigation Certification | DNV outcome-based modules validate operational capability ahead of Lloyd's Register alternatives. |
| Lithium-Sulfur Battery Supply Agreement | South Korean cell manufacturers anchor endurance extensions beyond current lithium-ion limits. |
| Sensor Fusion Middleware Acquisition | Machine learning integration with multi-beam echo sounders enables autonomous target recognition. |
| Port Authority Monitoring Center Partnership | Houston and Long Beach authorities fund dedicated autonomous vessel traffic infrastructure. |
| Pacific Clarion-Clipperton Zone License Alignment | Deep-rated UUV positioning captures polymetallic nodule survey demand from research consortia. |
Research Methodology
Multiple input streams — classification society technical committees, offshore contractor fleet managers, Coast Guard regulatory affairs officers, and lithium-sulfur battery R&D directors — were reconciled against secondary validation from IMO regulatory scoping documents, DNV certification guidelines, Lloyd's Register autonomous navigation protocols, and Pacific seabed mining license filings. Bottom-up platform deployment estimates and top-down maritime autonomy spending aggregates were triangulated to anchor volume figures.
Data-stream reconciliation across product type, application, technology tier, and end-user category generated segmentation outputs over the projection horizon. CAGRs were derived from deployment trajectory modeling against replacement cycle assumptions for aging North Sea infrastructure and harbor patrol fleet conversions. Battery energy density improvement curves and classification society certification adoption rates fed industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IMO regulatory finalization timelines and rare earth magnet export policy shifts. Practitioners should monitor DNV-Lloyd's Register certification framework convergence and Pacific mining license activation schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Sonobuoy Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
Asia-Pacific Aerospace Robotics Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Drone Parachute System Market