
 Autonomous Drone Platform Market | 2026-2036
Autonomous Drone Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Drone Platform Market Outlook
Military-grade autonomy standards are redrawing competitive boundaries in the autonomous drone platform sector. Skydio leverages its American manufacturing base to sustain defense contracts requiring domestic supply chain verification. General Atomics anchors its position through long-endurance platforms purpose-built for intelligence, surveillance, and reconnaissance missions. Anduril Industries differentiates via lattice AI architecture that integrates autonomous drones into networked defense systems.
An autonomous drone platform is a self-piloting aerial system operating without real-time human control, typically incorporating redundant IMUs, RTK-GPS positioning to within centimeter accuracy, and onboard edge computing for obstacle avoidance and mission replanning; its primary purpose is executing repetitive, hazardous, or geographically distributed tasks across commercial, civil, and defense domains. Agriculture applications lead volume shipments as vineyard and row-crop operators replace manual scouting with multispectral imaging drones. Defense end users command premium pricing tiers where payload capacity requirements drive procurement toward medium and heavyweight platforms with hardened communication links.
FAA Part 107 waivers and the EU AI Act create divergent compliance pathways that fragment certification costs for cross-border operators. EASA's specific category framework for unmanned aircraft systems mandates explicit risk assessments that favor established platform vendors with documented safety management systems. Stakeholders must monitor how emerging detect-and-avoid mandates reshape hardware requirements and whether national security screening of foreign-manufactured components restricts vendor eligibility for sensitive deployments.
Market Dynamics
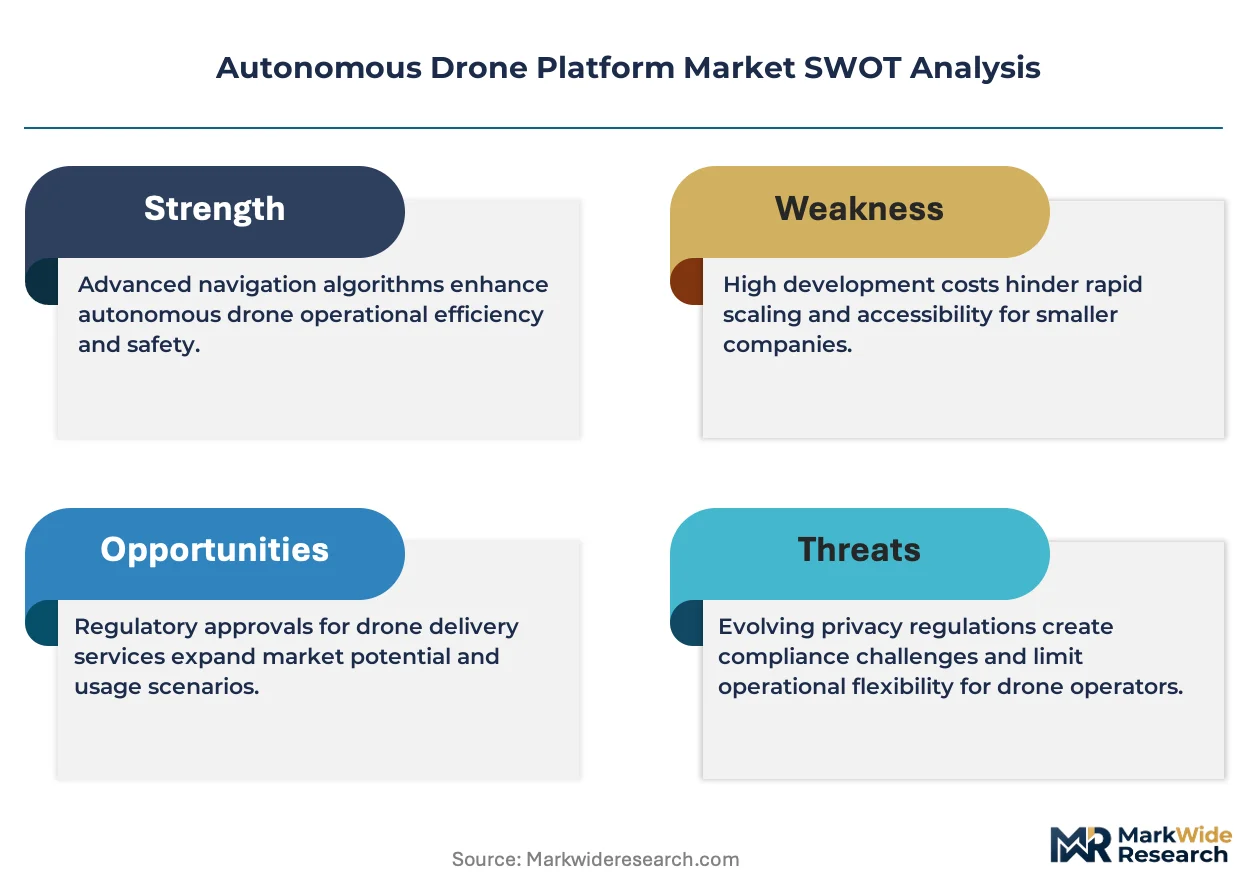
Autonomous drone platforms face a structural compression between defense-grade reliability requirements and commercial cost floors, as dual-use sensor packages and hardened communication links migrate from military procurement into civilian inspection and agriculture workflows.
Growth Catalysts
- Beyond-Visual-Line-of-Sight Waivers:FAA Part 107 expansions in the United States unlock commercial routes for infrastructure inspection and logistics, reducing operational friction for long-range missions.
- Energy Infrastructure Inspection:Utility operators in Germany accelerate platform procurement to automate pipeline and transmission tower monitoring, replacing manned helicopter surveys.
- Precision Agriculture Automation:Multispectral imaging integration enables vineyard and row-crop operators to replace manual scouting with autonomous crop-health mapping.
Market Restraints
- Detect-and-Avoid Hardware Mandates:Emerging regulatory requirements for onboard sense-and-avoid systems add sensor payload costs and power draw penalties to lightweight platforms.
- Foreign Component Screening:National security supply-chain verification restricts vendor eligibility for sensitive defense and critical infrastructure deployments.
- Centimeter-Grade Positioning Costs:RTK-GPS modules and redundant IMU configurations price entry-level platforms out of consumer-adjacent applications.
Strategic Opportunities
- Brazil Agriculture Expansion:Fleet deployments of autonomous spraying and crop-monitoring drones penetrate underserved soybean and sugarcane regions beyond established precision-farming zones.
- EU AI Act Compliance Services:Risk assessment documentation and safety management system tooling create aftermarket revenue streams for established platform vendors.
- Edge-Lattice Convergence:Integration of onboard edge computing with networked defense architectures enables real-time swarm coordination for perimeter security applications.
Industry Challenges
- Certification Timeline Compression:EASA specific-category risk assessments and FAA type certification processes create multi-year approval gaps between prototype readiness and commercial deployment.
- Autonomy Software Talent Scarcity:Competition for computer vision and flight-control engineers between defense contractors and commercial vendors inflates R&D payroll costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Drone Platform Market |
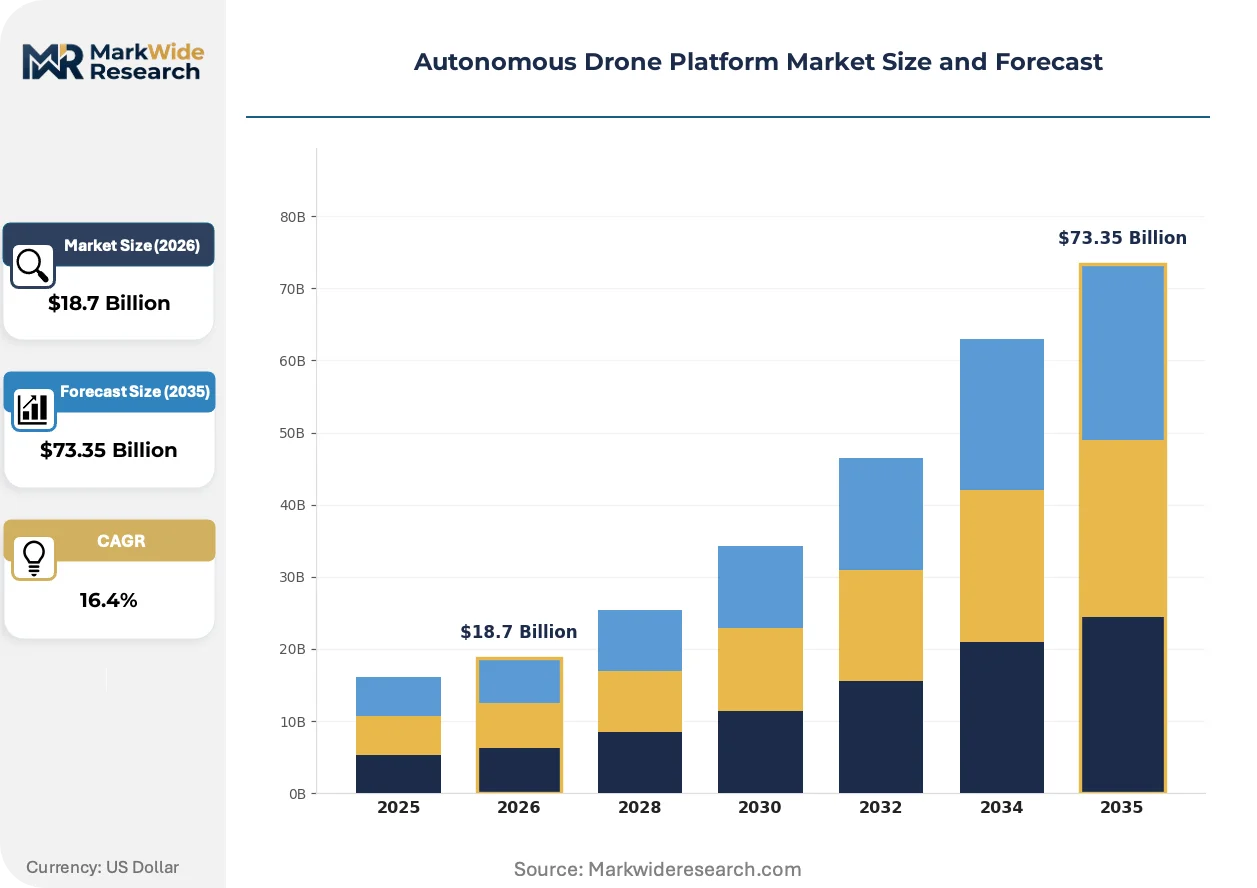
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Surveillance, Delivery, Infrastructure Inspection Technology: GPS Navigation, Computer Vision, Artificial Intelligence, LiDAR End User: Aerospace, Defense, Logistics, Construction Payload Capacity: Lightweight, Medium, Heavyweight, Ultra-Heavy |
| Companies Covered | DJI, Skydio, AeroVironment, Parrot, Northrop Grumman, General Atomics, Anduril Industries, Yuneec, Quantum Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Drone Platform Market Strategic Shifts
Hardware modularity and software-defined mission profiles are fragmenting traditional platform categories, as vendors repackage common airframes across defense, industrial, and agricultural end uses through payload and firmware differentiation.
Edge computing architectures are decomposing centralized ground-station dependency for real-time obstacle avoidance and mission replanning. Agriculture operators in Brazil deploy these systems for autonomous spraying in GPS-denied canopy environments. The shift compresses hardware margins on ground-control infrastructure while elevating software licensing value.
EASA's specific-category framework for unmanned aircraft systems mandates explicit risk assessments that favor established vendors with documented safety management systems. Industrial inspection contracts in Germany now require compliance pre-qualification, freezing out emerging entrants. Utility operators respond by consolidating procurement around proven platform lines.
Buyer concentration among defense primes and national utility operators is compressing vendor sales cycles into multi-year framework agreements. Channel relationships with systems integrators displace direct OEM sales in critical infrastructure verticals. This pattern concentrates most visibly in German energy markets and United States federal procurement.
Autonomous Drone Platform Market Segmentation
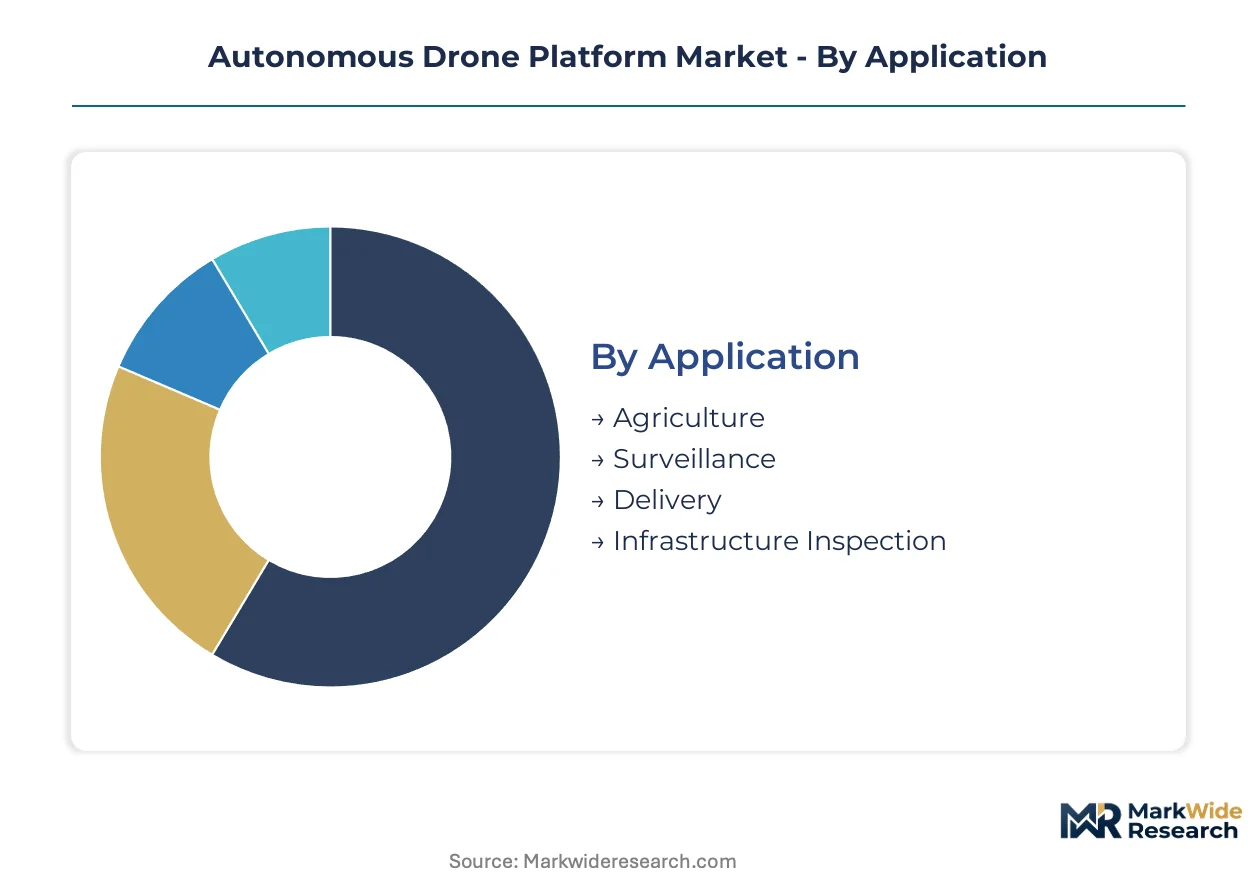
Segmentation in autonomous drone platforms reveals how defense-grade specifications cascade into commercial variants and where procurement budgets concentrate across mission profiles. Understanding these divisions exposes which technology combinations command premium positioning and which face commoditization pressure from volume agriculture deployments.
Application:
Margin pools concentrate in surveillance and infrastructure inspection where contract durations and regulatory barriers protect pricing.
- Agriculture:Multispectral imaging platforms with autonomous spraying capabilities dominate volume shipments. Vineyard and row-crop operators in Brazil replace manual scouting with crop-health mapping, driving fleet procurement at cost-optimized price points.
- Surveillance:Intelligence-gathering missions require hardened communication links and extended endurance. Defense primes anchor procurement here through multi-year framework agreements with domestic supply-chain verification requirements.
- Delivery:Last-mile logistics platforms face FAA Part 107 waiver dependencies for beyond-visual-line-of-sight operations. Urban air mobility corridors in the United States remain constrained by detect-and-avoid hardware mandates.
- Infrastructure Inspection:Pipeline and transmission tower monitoring contracts in Germany favor established vendors with EASA-specific category documentation.
The dominant share belongs to Agriculture, while Surveillance is closing the gap fastest.
Technology:
Cost tier stratification separates RTK-GPS precision systems from computer vision alternatives in price-sensitive deployments.
- GPS Navigation:Centimeter-grade RTK-GPS modules with redundant IMU configurations anchor high-value applications. Utility operators in Germany mandate this precision for energy infrastructure inspection where geolocation errors risk regulatory penalties.
- Computer Vision:Onboard edge computing enables real-time obstacle avoidance without ground-station dependency. Brazilian agriculture operators deploy these systems in GPS-denied canopy environments for autonomous spraying.
- Artificial Intelligence:Lattice architectures integrate autonomous drones into networked defense systems. The EU AI Act creates compliance documentation requirements that favor established platform vendors.
- LiDAR:3D mapping payloads command premium pricing in construction and surveying verticals. Power draw penalties limit deployment on lightweight platforms.
GPS Navigation holds the installed base lead, though Computer Vision is expanding most quickly into cost-constrained segments.
End User:
Customer type determines procurement channel structure, with defense and aerospace consolidating through systems integrators while logistics favors direct OEM relationships.
- Aerospace:Satellite coordination and high-altitude platform missions require specialized airframe certification. EASA risk assessments extend approval timelines for emerging entrants.
- Defense:Intelligence, surveillance, and reconnaissance missions drive procurement toward medium and heavyweight platforms. National security screening of foreign-manufactured components restricts vendor eligibility.
- Logistics:Warehouse inventory management and last-mile delivery operate under lighter regulatory burdens. Commercial cost floors compress margins compared to defense-grade alternatives.
- Construction:Site surveying and progress monitoring adopt modular payload configurations. Project-based procurement cycles create demand volatility.
Defense commands the premium tier, while Logistics is gaining share fastest as waiver expansions unlock commercial routes.
Payload Capacity:
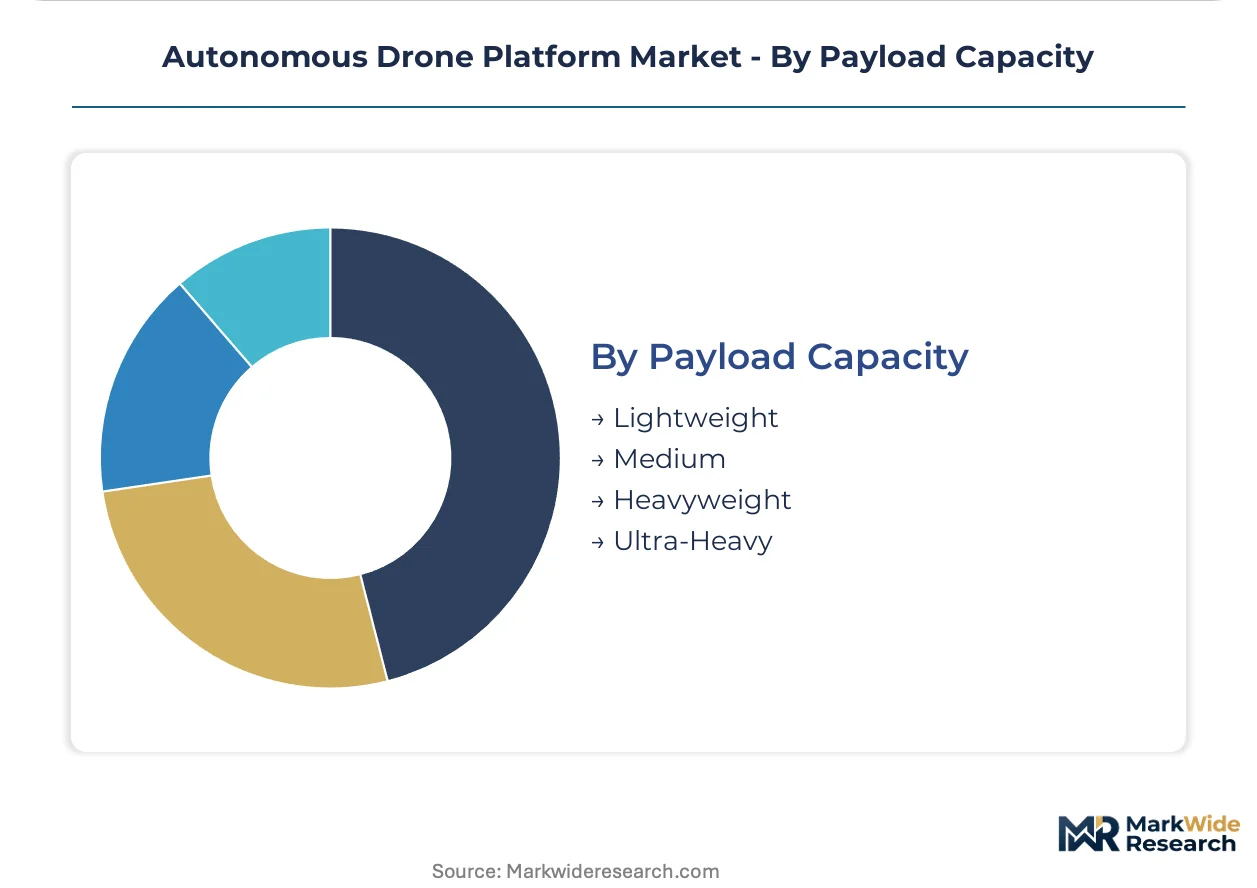
Volume concentration sits in lightweight platforms for agriculture, while revenue pools deepen in heavyweight categories serving defense and energy inspection.
- Lightweight:Sub-25kg platforms dominate precision agriculture with multispectral cameras and limited spraying payloads. Brazilian soybean operators drive fleet-scale procurement.
- Medium:Industrial inspection configurations balance sensor payload with endurance. German utility contracts standardize around this tier for transmission tower monitoring.
- Heavyweight:Extended-range missions carry dual-use sensor packages migrated from military procurement. Hardened communication links and redundant systems elevate unit economics.
- Ultra-Heavy:Cargo delivery and specialized defense applications require custom airframe engineering. Limited production runs sustain premium pricing.
Medium capacity leads commercial procurement, though Heavyweight is climbing the fastest as defense budgets modernize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli defense technology flows into European energy infrastructure markets, while Brazilian agriculture operators import precision navigation systems from German and American manufacturers. These trade corridors concentrate procurement decisions in regulatory environments with divergent certification timelines.
United States
FAA Part 107 waiver expansions unlock beyond-visual-line-of-sight routes for infrastructure inspection and logistics operators. The FAA mandates detect-and-avoid hardware for commercial autonomous flights above populated areas. Utility corridors in Texas and California host early deployments of long-range inspection platforms replacing manned helicopter surveys.
Germany
EASA's specific-category framework accelerates platform procurement by utility operators automating pipeline and transmission tower monitoring. The EU AI Act creates documentation requirements favoring established vendors with safety management systems. Industrial clusters in North Rhine-Westphalia concentrate drone-assembly operations serving energy infrastructure contracts.
Brazil
Soybean and sugarcane operators in Mato Grosso and São Paulo states expand fleet deployments of autonomous spraying and crop-monitoring drones. ANVISA regulates agricultural chemical application from unmanned platforms. Precision agriculture service providers cluster around Ribeirão Preto, deploying multispectral imaging for crop-health mapping in GPS-denied canopy environments.
China
Domestic manufacturers supply lightweight agricultural platforms to Southeast Asian and African markets. MIIT certification requirements for unmanned aerial systems restrict foreign vendor participation in critical infrastructure sectors. Manufacturing concentration in Shenzhen and Dongguan supports component integration for export-oriented drone producers.
Israel
Defense technology developers supply autonomous platforms to European and Asian military customers under government-to-government agreements. The Israeli Ministry of Defense screens foreign component sourcing for sensitive deployments. Tel Aviv-area engineering clusters specialize in lattice AI architectures for networked drone coordination.
Autonomous Drone Platform Market Competitive Environment
Listed leaders compete with private specialists across defense contracting channels, creating a tiered structure where public company disclosure requirements clash with classified program confidentiality. The vendor base stratifies around three archetypes: defense primes with multi-year framework agreements, commercial platform specialists with agriculture and inspection focus, and venture-backed autonomy software developers. Consolidation pressure intensifies through strategic partnerships between airframe manufacturers and AI software providers, plus vertical integration moves into sensor payload production.
Within the defense-prime tier, Northrop Grumman and General Atomics occupy positions anchored by long-endurance platform portfolios purpose-built for intelligence missions. Skydio represents the commercial-specialist archetype with American manufacturing credentials satisfying domestic supply-chain verification requirements. Anduril Industries exemplifies the venture-backed lattice-AI category, integrating autonomous drones into networked defense architectures without legacy airframe manufacturing overhead.
| Leading Market Players |
|---|
| DJI |
| Skydio |
| AeroVironment |
| Parrot |
| Northrop Grumman |
| General Atomics |
| Anduril Industries |
| Yuneec |
| Quantum Systems |
| Others |
Value Chain & Pricing Dynamics
Multi-year framework agreements with German utility operators and United States defense primes lock in supply access for RTK-GPS modules and hardened communication links while anchoring price visibility across volatile component markets. These contract structures insulate procurement teams from spot-market fluctuations in semiconductor and sensor payloads.
Pricing Analysis
Current-generation RTK-GPS precision platforms command substantial premiums over prior-generation computer-vision alternatives, while next-generation lattice-AI architectures promise further pricing stratification. The dominant pricing structure separates premium-tier defense contracts with domestic supply-chain verification from standard-tier industrial inspection bundles and economy-tier agriculture fleet deployments. Price differentiation hinges on certification grade under EASA specific-category frameworks and vertical integration depth in sensor manufacturing. Pricing pressure stems from detect-and-avoid hardware mandates elevating bill-of-materials costs for lightweight platforms. Agriculture operators in Brazil exhibit acute price sensitivity, while defense end users demonstrate inelastic demand for hardened communication links.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for flight-control processors and lithium-polymer battery cells sourced from Shenzhen and Dongguan manufacturing clusters. Supply concentrates in China for airframe components, the United States for defense-grade semiconductors, and Germany for precision navigation modules. Raw material dependencies center on rare-earth magnets for motor assemblies, gallium nitride substrates for RF components, and carbon-fiber prepregs for airframe structures. Single-source vulnerability in RTK-GPS chipset supply creates exposure to export control restrictions. Distribution runs through systems integrators for defense and energy verticals, with direct OEM relationships dominating agriculture procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous drone platforms sit in early-cycle expansion as FAA Part 107 waiver expansions unlock beyond-visual-line-of-sight commercial routes previously restricted to manned aviation. Penetration in precision agriculture and energy infrastructure inspection remains below saturation thresholds.
For Market Incumbents: Fortify positions through backward integration into sensor payload production and captive supply of RTK-GPS modules, reducing exposure to foreign component screening requirements. EASA specific-category documentation investments create regulatory moats against emerging entrants lacking safety management system tooling. Channel control through systems integrator partnerships in German energy markets protects pricing power. For New Entrants and Emerging Players: Lead with edge-computing software stacks targeting GPS-denied canopy environments in Brazilian agriculture, where established vendors underinvest in computer-vision autonomy. The most penetrable white space sits in aftermarket compliance services for EU AI Act risk assessment documentation. A direct-to-fleet-operator go-to-market model bypasses consolidated procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward venture-backed lattice-AI developers with defense contracting relationships and established platform vendors possessing EASA pre-qualification status. Long-term viability favors assets with dual-use technology migration paths from military to commercial workflows. The signal to watch is detect-and-avoid mandate finalization timing, which would accelerate hardware refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Supply Chain Certification | FAA and EASA sourcing requirements favor vendors with verified American or European manufacturing footprints for sensitive deployments. |
| Edge-Lattice AI Integration | Anduril's networked defense architecture demonstrates how software-defined coordination commands premium positioning in perimeter security applications. |
| EU AI Act Compliance Tooling | Risk assessment documentation services create recurring revenue streams from industrial operators requiring EASA specific-category pre-qualification. |
| Brazil Agriculture Fleet Expansion | ANVISA-regulated spraying operations in Mato Grosso offer volume scale for cost-optimized platforms with multispectral imaging payloads. |
| Detect-and-Avoid Hardware Mandate Preparation | Early sensor payload integration positions vendors for FAA commercial flight approvals above populated areas in United States corridors. |
Study Parameters
A standing panel of flight-control engineering leads, utility procurement directors, defense contracting officers, and precision agriculture fleet operators provided ongoing calibration across primary interview cycles. Secondary validation drew from FAA Part 107 waiver databases, EASA specific-category approval registries, SEC filings of listed drone manufacturers, and customs records of component trade flows. Bottom-up triangulation of platform shipment data against top-down procurement budget analysis anchored volume and value estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon. The analytical framework modeled segmentation dimensions including payload capacity tier, autonomy technology generation, end-use vertical, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle analysis. Forecast inputs incorporated FAA waiver expansion timelines and EASA risk assessment adoption curves without specifying year boundaries.
The analysis sits within stated boundaries; outcomes outside sustained regulatory waiver expansion or detect-and-avoid mandate implementation would require recalibration. Forecasts reflect assumptions regarding component supply continuity and defense budget authorization patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Integrated Range Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
High Altitude Long Endurance Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
Drone Jamming System Market
Unmanned Systems
High Altitude Platform Market