
 Global Spar Beacon Buoys Market | 2026-2036
Global Spar Beacon Buoys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spar Beacon Buoys Market Outlook
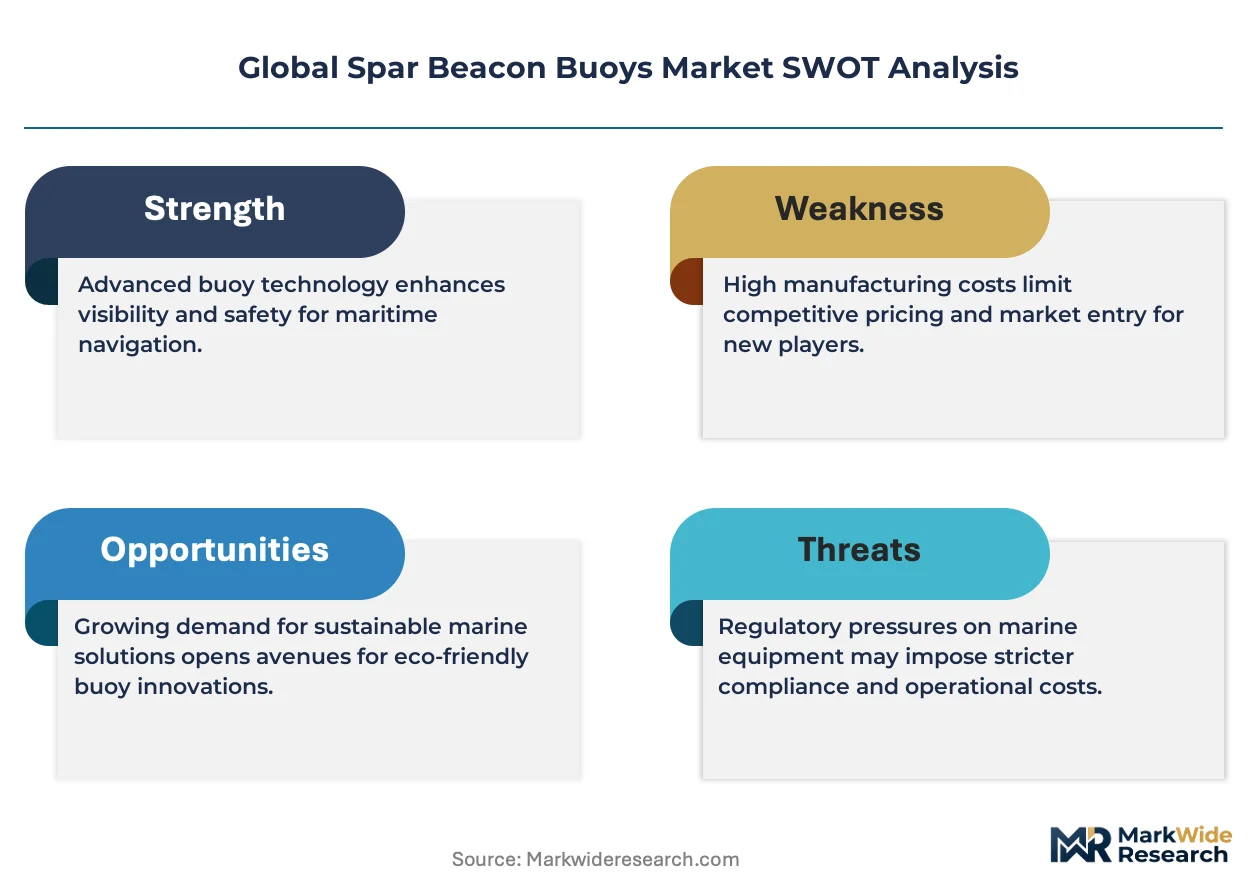
The capital-intensity divergence between large-scale manufacturers and regional assemblers is collapsing as modular LED and solar subsystems commoditize. Sealite leverages integrated photonics manufacturing to sustain margin on premium solar-powered buoys across Australasian harbor authorities. Mobilis anchors its position through polyethylene hull production in Brittany, competing on delivery speed for North Sea offshore wind installations.
Spar beacon buoys are long, slender floating structures with weighted keels that maintain upright stability in rough seas, typically constructed from rotationally molded polyethylene or welded aluminum hulls with internal foam filling for unsinkability; their primary purpose is to carry lights, radar reflectors, acoustic signals, or telemetry equipment for maritime channel marking and hazard warning. Solar-powered buoys dominate value contribution due to battery and photovoltaic integration complexity, while wireless communication buoys represent the fastest-expanding category as ports adopt real-time AIS and LoRaWAN monitoring. Aluminum hull variants retain entrenched demand in ice-prone latitudes where impact resistance governs procurement specifications.
IALA (International Association of Marine Aids to Navigation and Lighthouse Authorities) governs color-coding and light-character standards that determine product configurability, while the US Coast Guard and Maritime and Coastguard Agency in the United Kingdom enforce type-approval regimes that filter market access for non-certified suppliers. The EU Marine Equipment Directive and SOLAS convention jointly mandate minimum visibility ranges and backup power duration, forcing continuous R&D investment in energy density and optics. Stakeholders must monitor the divergence between national procurement budgets for legacy buoy replacement and emerging coastal state investments in autonomous vessel traffic management infrastructure.
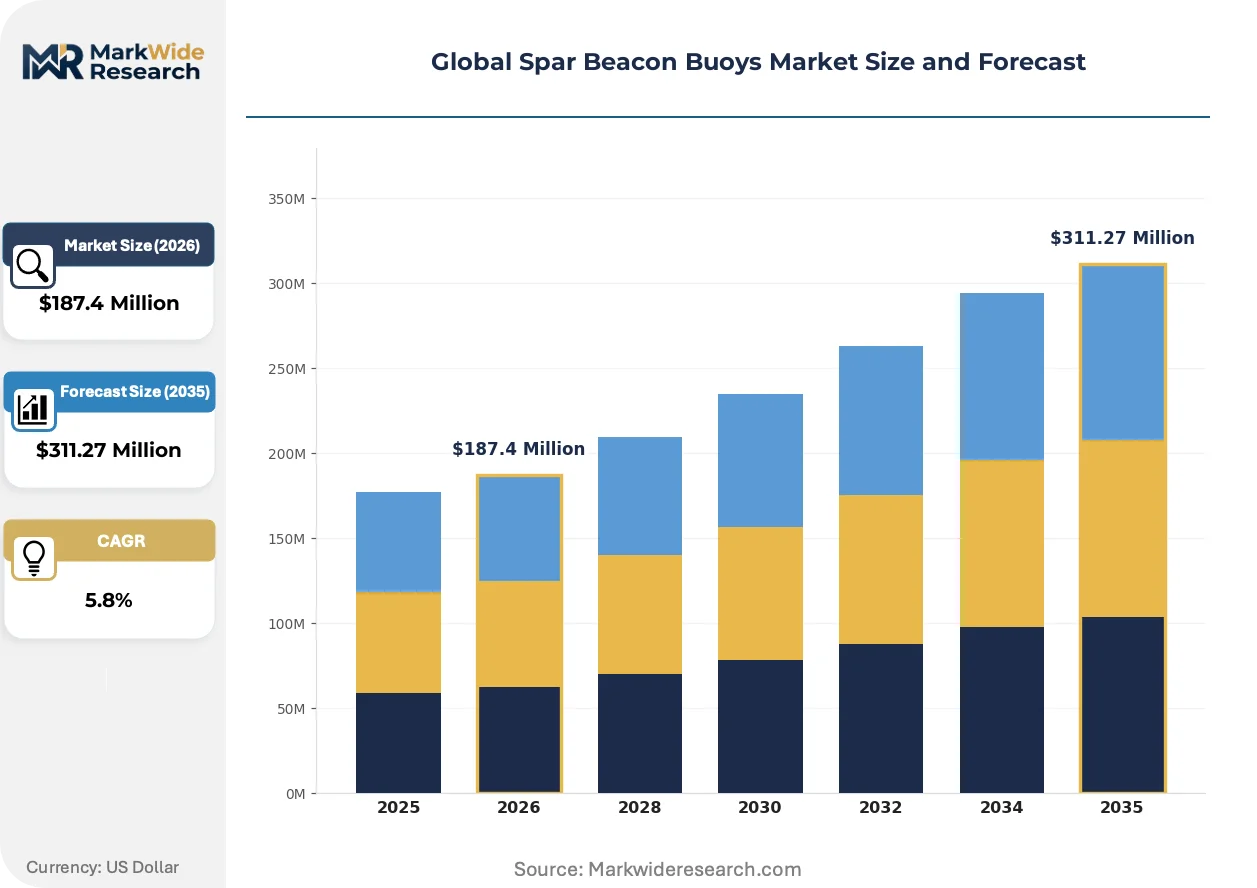
Market Dynamics
The IALA standard refresh on digital aids to navigation is compressing replacement cycles and forcing manufacturers to reconfigure product architectures around wireless telemetry integration.
Growth Catalysts
- Wireless Telemetry Mandates:The International Maritime Organization's updated IALA standards require real-time monitoring capabilities, compelling port authorities to upgrade legacy buoy fleets with LoRaWAN and AIS-integrated units.
- Offshore Wind Expansion:North Sea offshore wind developers are procuring marker buoys in volume for turbine field demarcation and cable protection zones.
- Solar-Battery Density Gains:Lithium iron phosphate cell chemistry improvements are extending autonomous operation windows, reducing maintenance vessel callouts for Norwegian and UK operators.
Market Restraints
- Aluminum Price Volatility:Ice-class hull procurement faces input cost pressure from London Metal Exchange aluminum fluctuations, squeezing margin on Arctic-rated buoy variants.
- Photovoltaic Supply Concentration:Solar panel sourcing depends heavily on Southeast Asian manufacturing clusters, exposing lead times to regional logistics disruptions.
- Certification Friction:US Coast Guard type-approval timelines for new optical configurations extend 18-24 months, delaying product launches in North American waters.
Strategic Opportunities
- Brazilian Pre-Salt Expansion:Petrobras field development off Rio de Janeiro state requires extensive channel marking for shuttle tanker corridors.
- Autonomous Vessel Infrastructure:Coastal states are piloting machine-readable navigation aids for unmanned surface vessel traffic management.
- Integrated Service Contracts:Port authorities in Australia are bundling buoy provision with telemetry data subscriptions, shifting revenue toward recurring models.
Industry Challenges
- Optical Engineer Scarcity:Specialized lens design talent for marine-grade LED collimation concentrates in German and Japanese industrial optics clusters.
- Legacy System Integration:Harbor authorities with 1980s-era radar infrastructure face compatibility gaps when deploying modern Racon-equipped buoys.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spar Beacon Buoys Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar-powered Buoys, LED Beacons, Acoustic Buoys, Wireless Communication Buoys Material: Polyethylene, Aluminum, Fiberglass, Steel Application: Marine Navigation, Offshore Oil & Gas, Search and Rescue, Environmental Monitoring End User: Government Agencies, Shipping Companies, Oil & Gas Operators, Research Institutions |
| Companies Covered | Sealite, Resinex, FenderCare, Mobilis, Almarin, Meritaito, Ryokuseisha, Carmanah Technologies Corporation, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spar Beacon Buoys Market Strategic Shifts
Digitalization of maritime navigation infrastructure is collapsing the distinction between passive markers and active sensor nodes, embedding spar buoys into real-time port operating systems.
Solid-state LED lantern technology is displacing traditional incandescent and xenon flash systems in new buoy deployments. Major North Sea operators including Equinor and Aker BP now specify LED-only configurations for platform safety zones. This shift is displacing legacy lamp maintenance business models while compressing energy consumption budgets by half.
The EU Marine Equipment Directive's 2024 amendments tightened backup power duration requirements for Category 1 aids to navigation. Manufacturers must now certify 30-day autonomous operation without solar input. German and Dutch certification bodies are processing backlog queues, delaying product launches for non-integrated suppliers.
Harbor authorities are unbundling hardware ownership from operational service, contracting telemetry and maintenance to specialist marine service firms. Danish and Swedish port clusters lead this transition, with Copenhagen Malmö Port and Gothenburg adopting full-service buoy provision. This reconfigures manufacturer relationships toward OEM supply rather than direct authority sales.
Global Spar Beacon Buoys Market Segmentation
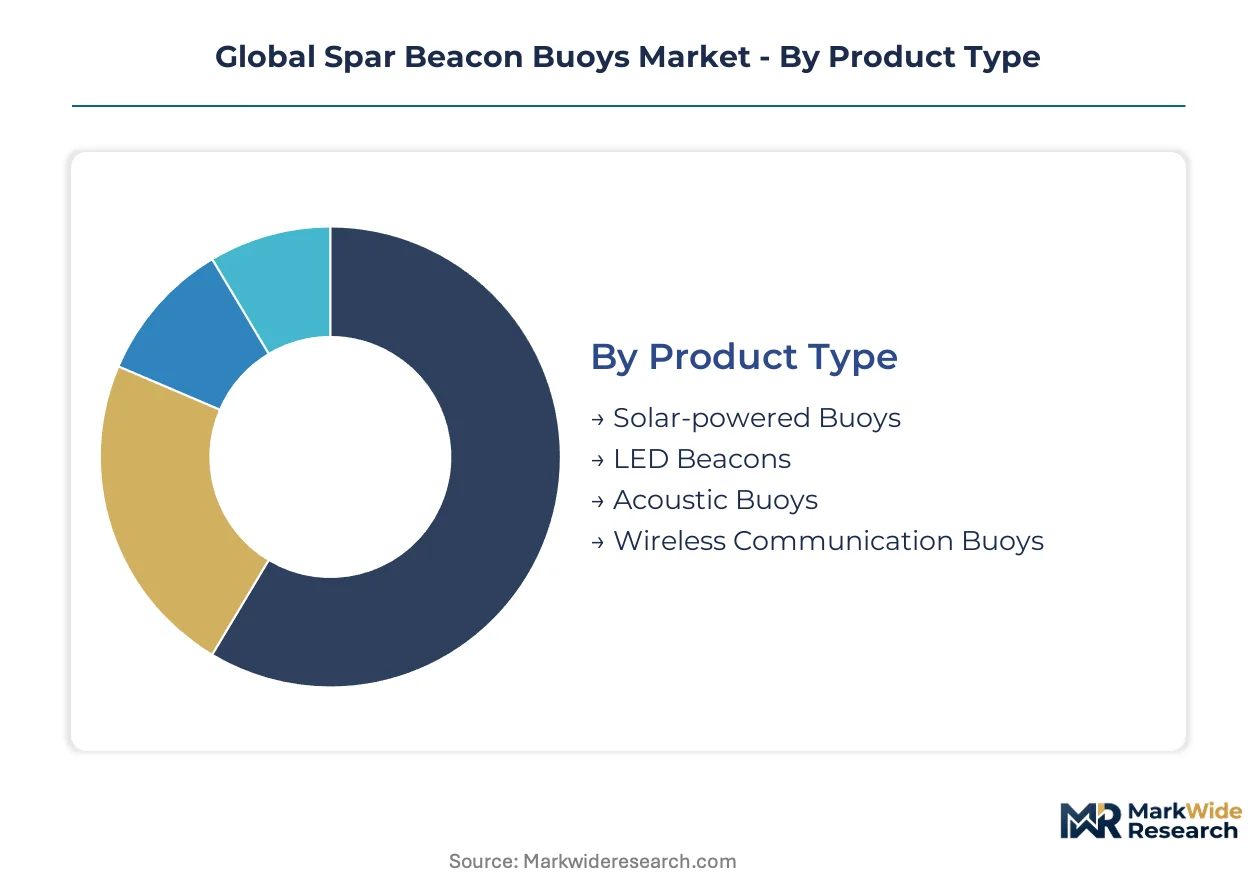
Spar beacon buoy procurement splits sharply between legacy passive markers and digitally integrated platforms, with substitution pressure intensifying as port authorities consolidate vendor relationships around telemetry-capable systems. Material selection and application scope further stratify the addressable base, creating distinct competitive arenas with diverging margin profiles.
Product Type:
Wireless communication buoys face the steepest substitution threat from integrated port operating systems that bundle hardware with data services, compressing standalone unit margins.
- Solar-powered Buoys:Photovoltaic panels married to lithium iron phosphate battery banks deliver autonomous operation exceeding regulatory backup mandates. Norwegian operators including Equinor specify these for North Sea platform marking where maintenance vessel access is costly and weather-dependent.
- Wireless Communication Buoys:LoRaWAN and AIS-integrated architectures transmit position, battery status, and collision alerts to shore-based traffic management centers. Copenhagen Malmö Port and Gothenburg have adopted these for real-time channel monitoring, displacing legacy radar-only infrastructure.
- LED Beacons:Solid-state optical engines with collimated beam patterns achieve IALA visibility standards at half the energy draw of xenon predecessors.
- Acoustic Buoys:Underwater pingers and DGPS correction transmitters serve hydrographic survey corridors and submarine cable routes.
Solar-powered buoys retain volume leadership across installed base; wireless communication buoys hold the steepest expansion curve.
Material:
Cost tier stratification separates premium aluminum hulls for ice-class deployment from commoditized polyethylene rotationally molded alternatives serving temperate harbors.
- Polyethylene:Rotationally molded hulls with closed-cell foam filling dominate volume production through lower tooling costs and corrosion immunity. Mobilis manufactures these in Brittany for rapid deployment across North Sea offshore wind installations.
- Aluminum:Welded marine-grade plate construction withstands ice impact and permits field repair, commanding procurement preference from Arctic operators in Norway and Russia where hull integrity governs specification.
- Fiberglass:Composite laminates offer intermediate weight and electromagnetic transparency for specialized radar reflector integration.
- Steel:Heavy-duty fabricated hulls persist in permanent mooring applications where mass stabilizes superstructure against tidal surge.
Polyethylene captures the widest deployment footprint; aluminum defends the highest unit economics.
Application:
Customer type concentration varies sharply across use cases, with government harbor authorities favoring standardized procurement against oil and gas operators demanding bespoke telemetry integration.
- Offshore Oil & Gas:Platform safety zones and subsea infrastructure corridors require redundant marking with satellite-linked monitoring. Petrobras pre-salt development off Rio de Janeiro state is driving tender volumes for shuttle tanker routing.
- Marine Navigation:Channel marking, hazard warning, and port entry sequences constitute the foundational installed base governed by IALA color-coding and light-character standards.
- Search and Rescue:Drift buoys with satellite distress relay support Coast Guard and maritime rescue coordination center operations.
- Environmental Monitoring:Sensor-integrated platforms measure sea surface temperature, salinity, and wave parameters for oceanographic research networks.
Marine navigation anchors replacement demand; offshore oil and gas commands the premium configuration mix.
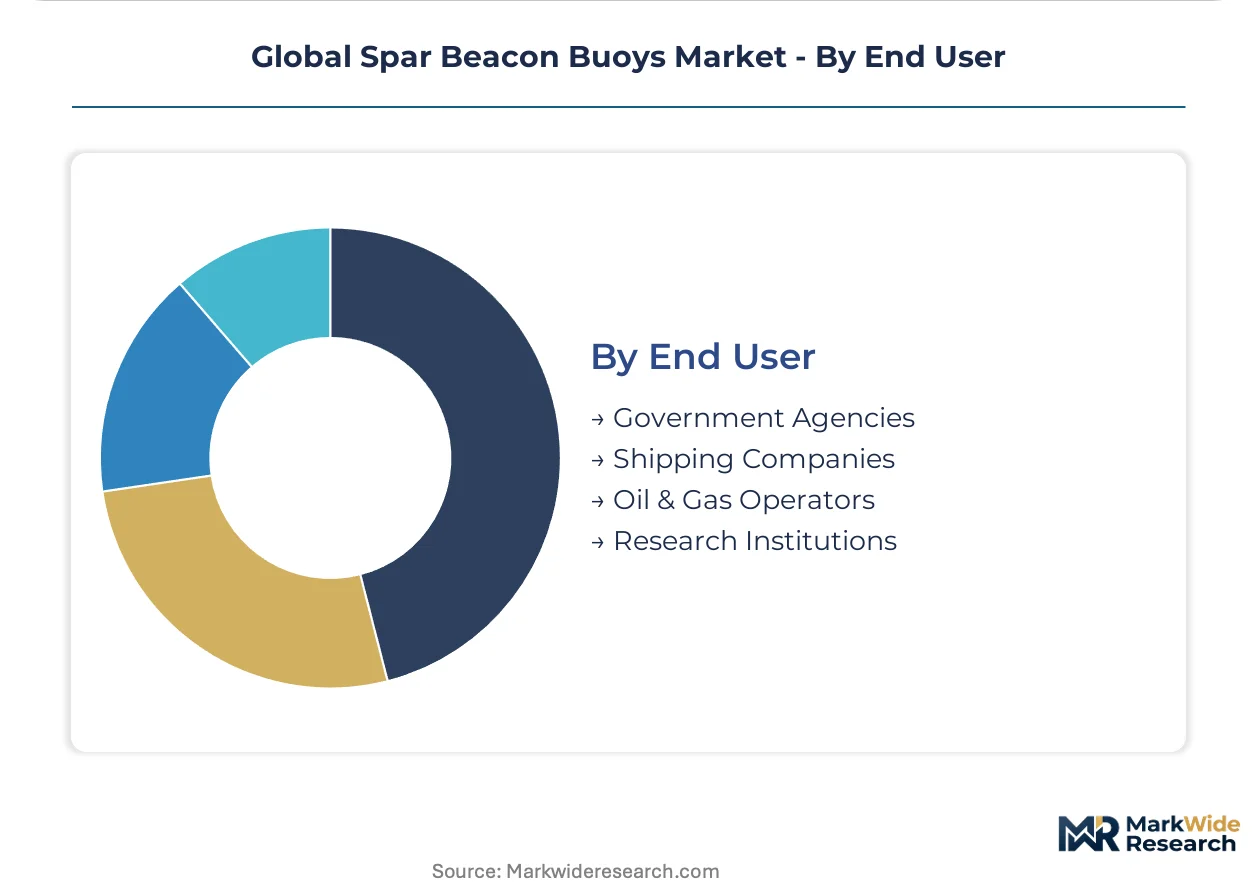
End User:
Procurement autonomy distinguishes centralized government tendering from decentralized shipping fleet maintenance, fragmenting vendor access pathways.
- Government Agencies:Coast Guard organizations and port authorities enforce type-approval regimes that filter market access, with US Coast Guard timelines extending 18-24 months for new optical configurations.
- Oil & Gas Operators:Integrated energy companies including Equinor and Aker BP maintain direct supplier relationships for field-specific safety zone marking, bypassing public procurement channels.
- Shipping Companies:Container lines and tanker operators procure portable marker buoys for temporary route adjustments and emergency channel demarcation.
- Research Institutions:Universities and oceanographic institutes acquire instrumented platforms for long-term mooring deployments in climate monitoring arrays.
Government agencies dominate tender volume; oil and gas operators concentrate the highest-specification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Harbor authorities in Norway absorb premium pricing for ice-class aluminum hulls without volume elasticity, while Southeast Asian port operators drive polyethylene buoy procurement on strict unit-cost metrics.
Norway
Equinor and Aker BP field networks generate continuous replacement demand for platform safety zone marking. The Norwegian Maritime Authority enforces IALA-compliant backup power duration for North Sea installations. Bergen and Stavanger clusters concentrate fabrication and maintenance vessel logistics for offshore wind and oil infrastructure corridors.
United Kingdom
Maritime and Coastguard Agency tenders drive channel marking refresh cycles at major container terminals. SOLAS convention amendments through the Maritime and Coastguard Agency mandate visibility range upgrades for Category 1 aids. The Humber and Thames estuary port complexes are deploying LoRaWAN-integrated buoys for real-time traffic monitoring.
Germany
Offshore wind developers in the North Sea procure marker buoys for turbine field demarcation and cable protection. The EU Marine Equipment Directive 2024 amendments tightened autonomous operation certification requirements. Hamburg and Bremerhaven harbor authorities are consolidating vendor relationships around telemetry-capable systems.
Brazil
Petrobras pre-salt development off Rio de Janeiro state requires extensive shuttle tanker corridor marking. The country's national maritime regulator enforces type-approval for optical configurations in coastal waters. The Macaé and Rio de Janeiro industrial clusters concentrate fabrication capacity for deepwater field support.
Australia
Harbor authorities in Queensland and Western Australia bundle buoy provision with telemetry data subscriptions. The Australian Maritime Safety Authority administers certification for solar-powered aids to navigation. The Port of Brisbane and Fremantle clusters are transitioning from hardware ownership to full-service operational contracts.
Global Spar Beacon Buoys Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper layer controlling photovoltaic-battery integration and certification pathways while regional assemblers compete on hull fabrication speed. The middle tier fragments across polyethylene rotation molders and aluminum welding shops serving discrete geographic basins. Three archetypes dominate: integrated photonics-solar manufacturers, rotation molding specialists with harbor authority relationships, and ice-class aluminum fabricators with Arctic operator certifications. Competitive moves concentrate on strategic partnerships for telemetry integration and geographic expansion through local certification acquisition.
Among integrated photonics manufacturers, Sealite exemplifies the premium solar-powered buoy archetype through its manufacturing footprint. Mobilis occupies a position within the rotation molding specialist tier, with its Brittany production base serving North Sea offshore wind timelines. Carmanah Technologies Corporation represents the North American certification-focused archetype, navigating extended US Coast Guard type-approval pathways.
| Leading Market Players |
|---|
| Sealite |
| Resinex |
| FenderCare |
| Mobilis |
| Almarin |
| Meritaito |
| Ryokuseisha |
| Carmanah Technologies Corporation |
| Xylem |
| Others |
Value Chain & Pricing Dynamics
Long-term telemetry service contracts lock in both photovoltaic-battery supply access and price visibility for harbor authorities transitioning from hardware ownership to operational subscriptions. Norwegian and Australian port clusters now structure multi-year agreements that bundle buoy provision with data transmission, compressing upfront capital outlays while securing supplier commitment through the analysis window.
Pricing Analysis
After-sales telemetry subscriptions now drive lifetime value beyond hull and lantern hardware margins. Three-tier pricing structure across premium ice-class aluminum, standard solar-polyethylene, and economy passive-marker tiers reflects certification grade and geographic delivery cost. Price differentiation stems from IALA compliance tier and maintenance vessel accessibility — Arctic-rated variants command sustained premiums while temperate-harbor polyethylene units face cost compression from rotation-molding commoditization. Government harbor authorities exhibit highest price sensitivity; oil and gas operators prioritize specification compliance over unit cost.
Supply Chain Analysis
China and Vietnam anchor photovoltaic panel manufacturing for solar-powered buoy subsystems, while Norway and Germany concentrate LED optical engine and lithium iron phosphate battery production. Raw material flows draw from Southeast Asian wafer fabrication, Australian lithium chemical processing, and Norwegian aluminum smelting. Single-source vulnerability concentrates in photovoltaic supply given regional logistics exposure. Distribution runs through integrated marine service firms that bundle hardware with installation and telemetry management for port authority clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry data subscriptions represent the fastest-expanding revenue layer, outpacing hull and beacon hardware sales as harbor authorities outsource operational monitoring to specialist marine service firms.
For Market Incumbents: Fortify position through backward integration into lithium iron phosphate cell assembly and captive photovoltaic wafer sourcing. Sealite and Mobilis must defend against emerging rotation-molding specialists by accelerating IALA certification timelines for integrated LoRaWAN architectures. Capacity addition in Brittany and Australasian clusters preserves delivery speed advantage for North Sea offshore wind procurement cycles. For New Entrants and Emerging Players: Differentiate on rapid-certification pathways for Brazilian pre-salt and Australian full-service contract markets. Brazilian national maritime regulator enforcement gaps create white-space for telemetry-integrated suppliers willing to navigate ANVISA-aligned type-approval. Target Petrobras shuttle tanker corridor tenders through local fabrication partnerships in Macaé industrial clusters. For Investors and Strategic Acquirers: Capital is best deployed toward integrated photonics-solar manufacturers with established US Coast Guard and Maritime and Coastguard Agency certification pathways. Long-term viability hinges on recurring telemetry revenue attachment rates exceeding hardware replacement cycles. Monitor IALA standard refresh implementation velocity as inflection indicator for product refresh cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | LoRaWAN and AIS architectures embed buoys into real-time port operating systems for Copenhagen Malmö Port. |
| Photovoltaic Supply Agreement | Long-term wafer contracts with Vietnamese manufacturers insulate against logistics disruption in solar-battery buoy production. |
| Ice-Class Certification Investment | Maritime and Coastguard Agency type-approval for aluminum hull variants secures Arctic operator preference in Norway. |
| Full-Service Contract Expansion | Revenue model shift from hardware sale to telemetry subscription captures Australian harbor authority outsourcing demand. |
| Regional Fabrication Joint Venture | Local production in Rio de Janeiro state reduces delivery timelines for Petrobras pre-salt field development tenders. |
Study Parameters
Initial hypotheses were tested against primary input from harbor authority procurement directors, offshore oil and gas safety managers, marine service firm operations leads, and IALA certification engineers and refined through secondary validation. Bottom-up triangulation combined trade data from customs records, EU Marine Equipment Directive filing databases, and SEC disclosures from listed marine technology suppliers with top-down assessment of Norwegian Maritime Authority and US Coast Guard regulatory frameworks.
Variance decomposition across product type, material grade, application scope, and end-user procurement channel structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers including offshore wind capacity additions and oil field development timelines. Forecast inputs incorporated lithium iron phosphate battery cost curves and photovoltaic module efficiency trajectories specific to marine autonomous power systems.
The analysis sits within stated boundaries; outcomes outside sustained offshore energy investment and IALA digital aid adoption would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and raw material supply continuity. Recalibration cycles align with material shifts in EU Marine Equipment Directive amendments and photovoltaic supply chain concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Ship Plate Market