
 United Kingdom Electric Vehicle Battery Electrolyte Market | 2026-2036
United Kingdom Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Electric Vehicle Battery Electrolyte Market Insights
Multi-source electrolyte procurement is decoupling from traditional Asian supply dependence as UK cell manufacturers diversify formulation partners. BASF leverages its Ludwigshafen R&D base to sustain high-purity lithium salt production for British OEM qualification programs. Solvay SA anchors its fluorinated electrolyte additive portfolio through dedicated supply agreements with Midlands-based gigafactory projects. Ilika plc competes in solid-state electrolyte development, positioning its thin-film ceramic technology for next-generation UK battery architectures.
United Kingdom electric vehicle battery electrolyte encompasses the ion-conducting medium—typically lithium hexafluorophosphate dissolved in carbonate solvents for liquid systems, or sulfide-oxide ceramics for solid variants—that enables lithium-ion transport between anode and cathode during charge and discharge cycles. The formulation determines thermal stability, operating voltage window, and cycle life in high-energy-density automotive cells. Liquid electrolyte formulations currently dominate installed capacity due to mature manufacturing infrastructure and established compatibility with graphite-silicon anodes, though solid electrolyte segments are attracting concentrated R&D investment as British OEMs target cobalt-free cell architectures. Passenger vehicle applications lead volume consumption, while commercial vehicle fleets are shifting toward advanced electrolyte additives that extend cycle life under high-utilization duty cycles.
The UK's Office for Product Safety and Standards enforces battery cell and pack certification under the Electrical Equipment (Safety) Regulations, while the Environment Agency governs hazardous substance handling in electrolyte manufacturing facilities. BSI standards for lithium-ion cell testing, aligned with UN 38.3 transport protocols, shape product qualification timelines for suppliers entering the UK market. Stakeholders must monitor evolving post-Brexit chemical registration requirements and domestic content thresholds under the UK Battery Strategy as these frameworks determine market access conditions and supply chain localization incentives.
Market Dynamics
The UK government's ZEV mandate is compressing qualification timelines for domestic electrolyte suppliers as British cell manufacturers race to localize supply chains ahead of 2030 content thresholds. This regulatory pressure is restructuring procurement relationships across the Midlands battery cluster and South Wales gigafactory corridor.
Growth Catalysts
- ZEV Mandate:The UK's zero-emission vehicle sales requirements are forcing OEMs to secure qualified local electrolyte sources, accelerating supplier onboarding for domestic gigafactory projects.
- Solid-state R&D:Thin-film ceramic electrolyte development is attracting capital from British automotive OEMs targeting cobalt-free architectures with higher energy density ceilings.
- Midlands Cluster Effect:Concentrated cell manufacturing investment around Coventry and Warwickshire is creating captive demand for just-in-time electrolyte formulation services.
Market Restraints
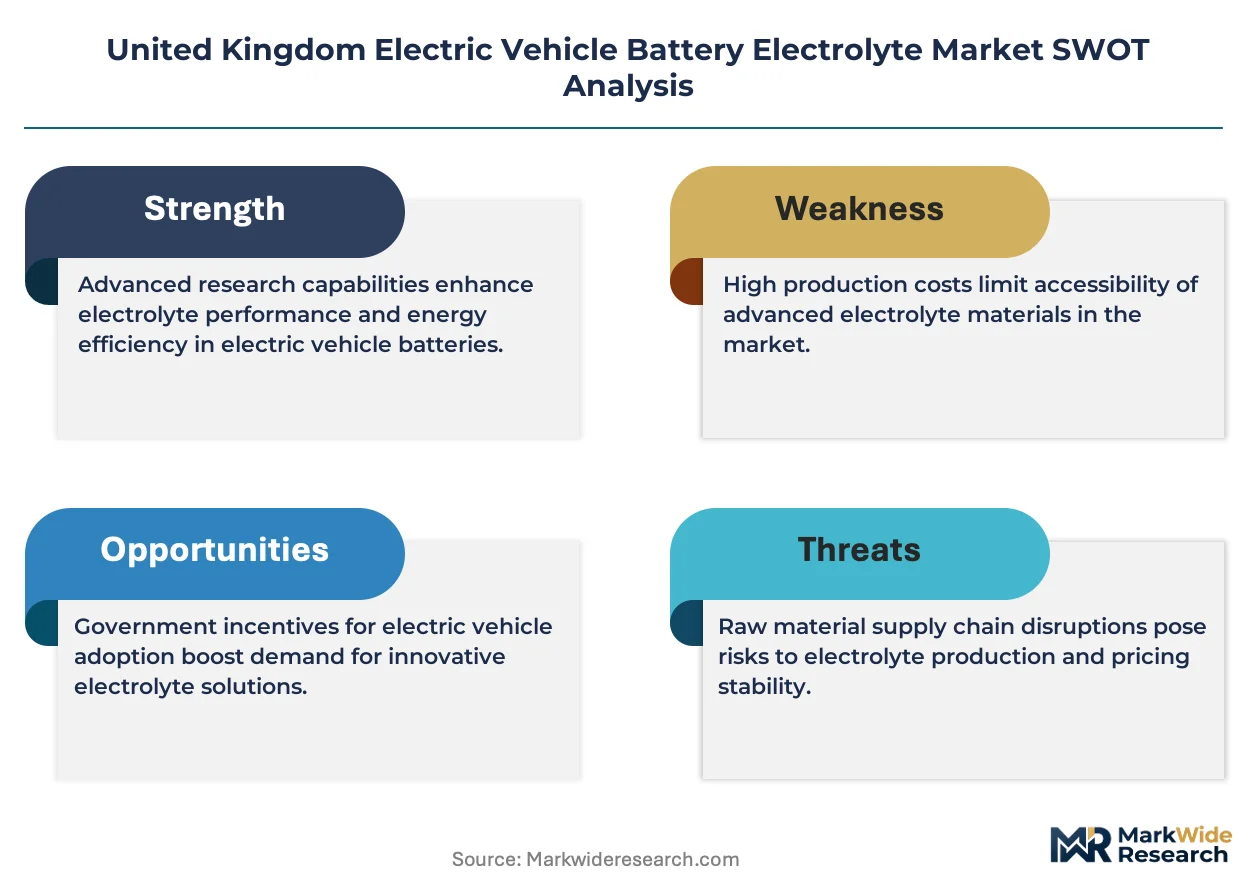
- Lithium Hexafluorophosphate Concentration:High-purity lithium salt production remains concentrated in German and Asian chemical bases, exposing UK formulators to input cost volatility and currency risk.
- Fluorinated Additive Dependence:Specialized electrolyte additives for high-voltage cathodes rely on limited European fluorochemical supply chains subject to REACH authorization delays.
- Liquid Electrolyte Lock-in:Existing graphite-silicon anode infrastructure creates technical friction for solid-state electrolyte adoption, extending qualification cycles for novel formulations.
Strategic Opportunities
- South Wales Gigafactory Corridor:Emerging cell production capacity around Newport and Bridgend offers greenfield electrolyte supply contracts without incumbent displacement costs.
- Recycling Integration:Spent battery black mass processing is converging with electrolyte salt recovery, enabling closed-loop lithium sourcing for Midlands-based formulators.
- UK Battery Strategy Incentives:Domestic content thresholds and R&D tax credits are subsidizing pilot-scale solid-state electrolyte production for British-qualified suppliers.
Industry Challenges
- Electrochemist Talent Scarcity:British universities produce insufficient formulation specialists with lithium-ion cell experience, forcing gigafactory projects to recruit from Asian and German competitor pools.
- UN 38.3 Certification Bottlenecks:Transport safety testing for novel electrolyte formulations faces backlogged BSI laboratory capacity, delaying customer qualification programs by 6-12 months.
- Post-Brexit Chemical Registration:Divergence from EU REACH data requirements is creating dual compliance burdens for electrolyte suppliers serving both UK and continental European cell manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Electric Vehicle Battery Electrolyte Market |
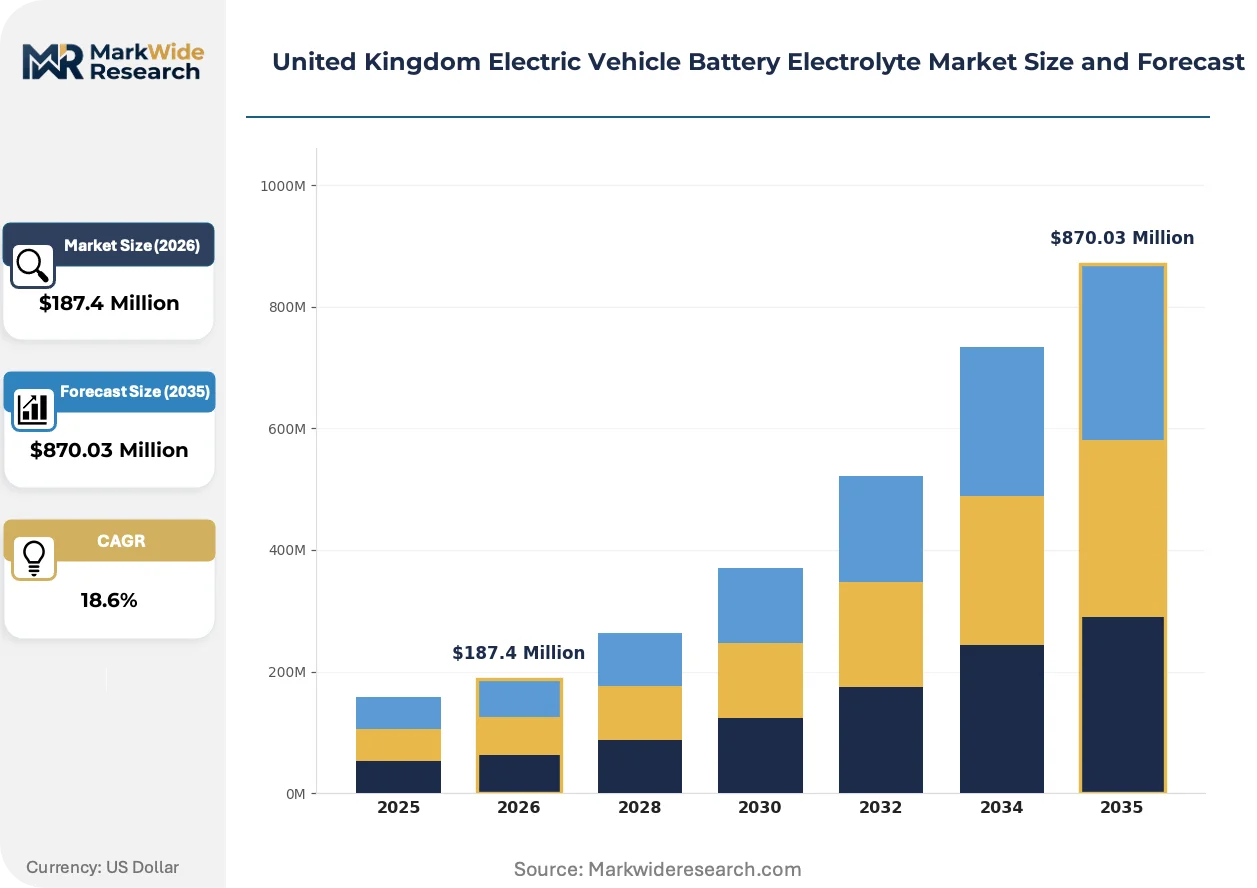
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Solid Electrolyte, Liquid Electrolyte, Polymer Electrolyte Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Agricultural Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Conventional, Advanced, Emerging, Next-Gen |
| Companies Covered | BASF, Mitsubishi Chemical, Solvay SA, Ilika plc, LiNa Energy, 3M, Contemporary Amperex Technology, LG Energy Solution, Samsung, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Electric Vehicle Battery Electrolyte Market Trends and Innovations
Electrolyte chemistry is diverging from standardized carbonate formulations as British OEMs specify customized additive packages for their proprietary cell architectures. This specialization is fragmenting supplier relationships and compressing development cycles.
Sulfide-based solid electrolytes are converging with oxide ceramic thin-film deposition techniques to enable all-solid-state cell prototypes. British automotive OEMs are qualifying these materials for 2028-2030 platform launches. The technology convergence is displacing conventional liquid electrolyte R&D investment in UK university battery programs.
The UK's post-Brexit chemical regulatory framework is diverging from EU REACH substance authorization timelines, creating parallel compliance tracks for electrolyte manufacturers. British suppliers must now maintain dual registration dossiers for lithium salts and fluorinated additives. Small and mid-sized formulators are consolidating to spread regulatory affairs overhead across larger product portfolios.
Fleet operators are consolidating electrolyte procurement through long-term offtake agreements with Midlands gigafactory projects, bypassing traditional chemical distributor channels. Direct supplier relationships are replacing spot-market purchasing for high-volume commercial vehicle applications. This channel compression is most visible in battery-electric bus and last-mile delivery van segments operating from centralized Midlands depots.
United Kingdom Electric Vehicle Battery Electrolyte Market Segmentation
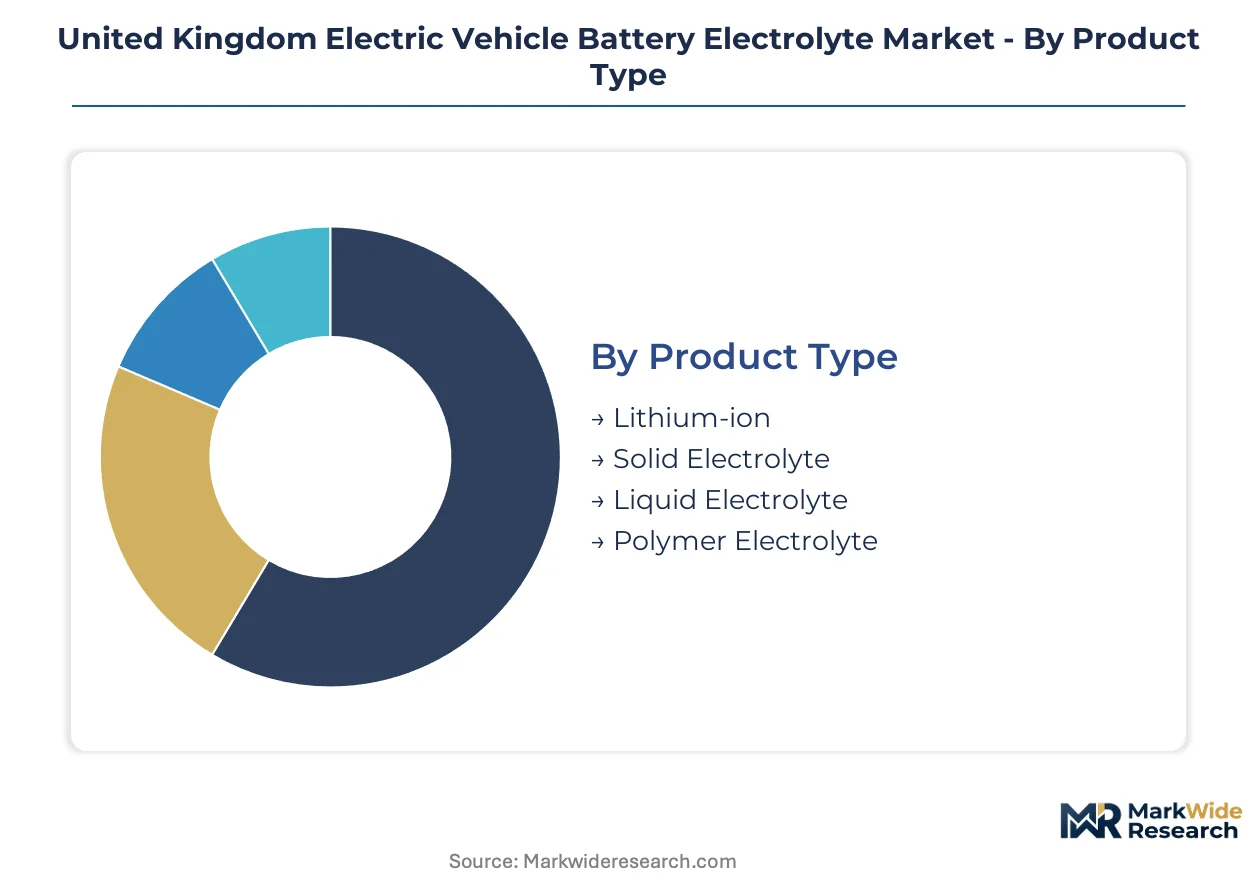
Electrolyte segmentation in the UK market determines which suppliers qualify for ZEV mandate procurement and which face exclusion due to certification gaps. British cell manufacturers specify formulations by product chemistry and vehicle application, with domestic content thresholds filtering supplier pools at each tier.
Product Type:
Certification burden varies sharply across electrolyte chemistries. Liquid formulations require UN 38.3 transport clearance and BSI cell testing alignment. Solid-state variants face extended qualification cycles under UK Battery Strategy pilot programs.
- Lithium-ion:Standard carbonate solvent systems with lithium hexafluorophosphate salt dominate installed UK capacity. Midlands gigafactory projects specify these formulations for graphite-silicon anode compatibility, though supply chains remain exposed to German and Asian lithium salt concentration.
- Solid Electrolyte:Sulfide-oxide ceramic thin-film technologies are attracting British OEM R&D capital for cobalt-free architectures. Ilika plc positions its deposition techniques for 2028-2030 platform qualifications, pending BSI laboratory capacity for transport safety testing.
- Liquid Electrolyte:Mature manufacturing infrastructure supports just-in-time delivery to South Wales gigafactory corridors. REACH authorization delays for fluorinated additives constrain high-voltage cathode formulations.
- Polymer Electrolyte:Gel-type systems occupy niche applications requiring mechanical flexibility. Limited UK production scale restricts qualification to specialty vehicle segments.
Leading the category by volume: Lithium-ion. Growing fastest: Solid Electrolyte.
Application:
Vehicle duty cycles determine additive specifications and cycle life requirements. Fleet operators consolidate procurement differently across passenger and commercial segments.
- Passenger Vehicles:Volume consumption leader with standardized electrolyte formulations for mass-market cell platforms. British OEMs customize additive packages for proprietary architectures, fragmenting supplier relationships.
- Commercial Vehicles:High-utilization duty cycles demand advanced electrolyte additives extending cycle life. Battery-electric bus and last-mile delivery van fleets operating from centralized Midlands depots bypass traditional distributor channels through direct offtake agreements.
- Two-wheelers:Compact cell formats prioritize cost-optimized liquid electrolyte formulations. Limited UK domestic production concentrates demand in aftermarket replacement segments.
- Agricultural Vehicles:Niche applications with extreme temperature tolerance requirements. Specialized formulators serve this segment through low-volume, high-margin supply contracts.
Highest procurement consolidation: Commercial Vehicles. Steepest expansion trajectory: Agricultural Vehicles as electrification extends to off-road machinery.
End User:
Customer type dictates contract structure, with OEMs driving qualification timelines and Tier-1 suppliers managing formulation risk.
- OEMs:British automotive manufacturers specify electrolyte chemistry for proprietary cell architectures, compressing supplier onboarding ahead of 2030 domestic content thresholds. Direct relationships replace spot-market purchasing for strategic formulations.
- Tier-1 Suppliers:Cell manufacturers around Coventry and Warwickshire aggregate demand for just-in-time formulation services. These intermediaries absorb lithium salt price volatility from concentrated German and Asian supply bases.
- Aftermarket Providers:Replacement cell demand supports secondary electrolyte supply channels. BSI certification requirements limit qualified suppliers serving this fragmented segment.
- Vehicle Assemblers:Final production integration points require logistics-coordinated electrolyte delivery. South Wales corridor projects offer greenfield contract opportunities without incumbent displacement costs.
Contract value concentration: OEMs. Channel compression most visible: Tier-1 Suppliers.
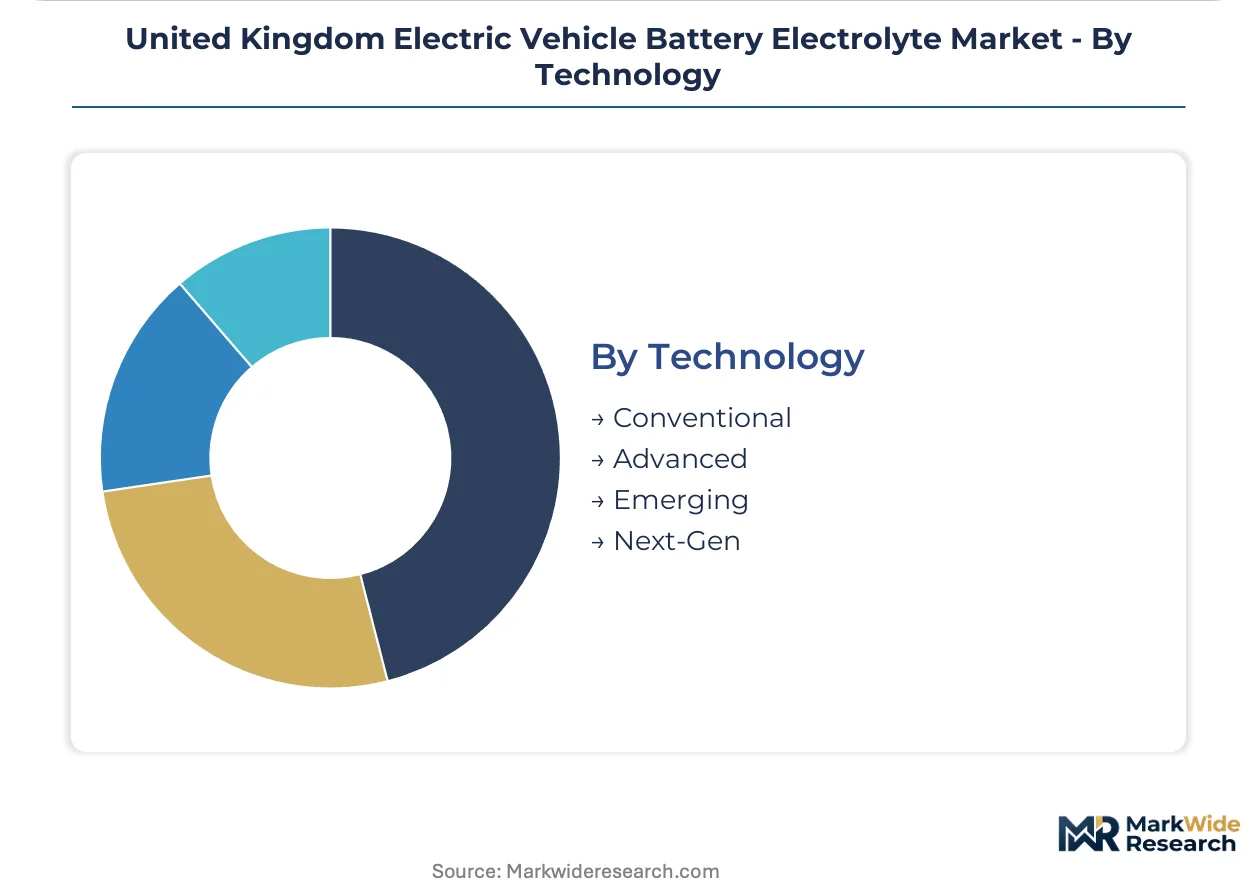
Technology:
Technology tier determines R&D tax credit eligibility and UK Battery Strategy incentive access.
- Conventional:Established carbonate formulations with mature BSI qualification pathways. Baseline technology for volume production at Midlands cluster facilities.
- Advanced:Customized additive packages for high-voltage cathodes and extended cycle life. British OEMs specify these formulations for differentiated cell performance.
- Emerging:Solid-state and semi-solid prototypes under pilot-scale production. UK government R&D subsidies support domestic qualification programs.
- Next-Gen:Cobalt-free architectures with sulfide ceramic electrolytes. University battery programs are diverting investment from liquid electrolyte research to these technologies.
Production volume leader: Conventional. Incentive capture rate highest: Next-Gen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium hexafluorophosphate salt supply from German chemical bases anchors electrolyte production economics across British manufacturing clusters. Midlands gigafactory projects and South Wales cell facilities source formulation inputs through concentrated European supply channels.
Midlands
Coventry and Warwickshire host concentrated cell manufacturing investment from British automotive OEMs. The UK Battery Strategy domestic content thresholds compress supplier qualification timelines for local electrolyte formulators. Just-in-time formulation services cluster around gigafactory sites to minimize logistics coordination costs.
South Wales
Newport and Bridgend corridors attract greenfield cell production capacity without incumbent supplier displacement. Welsh Development Bank financing supports electrolyte supply chain localization for emerging gigafactory projects. Transport infrastructure upgrades along the M4 corridor enable bulk chemical delivery to formulation facilities.
Scotland
Aberdeen's energy transition programs redirect North Sea supply chain expertise toward battery chemical logistics. Scottish Enterprise grants fund pilot-scale solid-state electrolyte research at university battery centers. Highlands renewable energy projects power low-carbon lithium salt processing demonstrations.
North England
Teesside chemical processing heritage provides skilled workforce pools for fluorinated additive manufacturing. Net Zero Teesside carbon capture infrastructure supports electrolyte solvent recycling investments. Port of Middlesbrough handles bulk carbonate imports for regional formulators.
London and Southeast
Financial services concentration enables project finance for electrolyte supply chain investments. Imperial College and Oxford University battery research programs spin out solid-state electrolyte ventures. Heathrow logistics corridors facilitate just-in-time delivery to Midlands manufacturing clusters.
United Kingdom Electric Vehicle Battery Electrolyte Market Competitive Landscape
Strategic partnerships dominate the current landscape as electrolyte suppliers align with gigafactory construction timelines. The vendor base stratifies across multinational chemical conglomerates, specialized additive manufacturers, and solid-state technology developers. Three archetypes define competitive positioning: integrated chemical producers with captive lithium salt supply, formulation specialists serving just-in-time delivery contracts, and materials science ventures commercializing next-generation ceramic electrolytes. Capacity expansion and technology licensing represent the dominant competitive moves as firms position for 2030 domestic content thresholds.
Among German chemical conglomerates, BASF anchors the integrated producer archetype through its Ludwigshafen R&D infrastructure. Solvay SA occupies a specialist position within the fluorinated additive segment. Ilika plc exemplifies the solid-state technology developer archetype, representing British venture-backed materials science ventures targeting cobalt-free cell architectures.
| Leading Market Players |
|---|
| BASF |
| Mitsubishi Chemical |
| Solvay SA |
| Ilika plc |
| LiNa Energy |
| 3M |
| Contemporary Amperex Technology |
| LG Energy Solution |
| Samsung |
| Others |
Pricing and Supply Chain Analysis
Electrochemist workforce concentration in the Midlands and South Wales corridors feeds labor-cost differentials into pricing-tier spreads across electrolyte formulation services. British cell manufacturers absorb premium pricing for just-in-time delivery contracts while fleet operators negotiate volume discounts through direct offtake agreements.
Pricing Analysis
Warranty and technical service bundling separates premium electrolyte suppliers from commodity formulators serving aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from lithium hexafluorophosphate input cost volatility originating in German chemical bases. Tier-1 suppliers exhibit highest price sensitivity due to margin compression from OEM consolidation, while OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Midlands gigafactory projects, bypassing traditional chemical distributor networks. Lithium salt production concentrates in Germany and China, while fluorinated additive manufacturing rests on limited European supply chains. Raw material dependencies span high-purity carbonate solvents, lithium hexafluorophosphate, and specialized fluorochemical precursors. Single-source vulnerability for lithium salt inputs exposes UK formulators to currency risk and REACH authorization delays. Distribution runs through concentrated chemical logistics corridors along the M4 and Midlands motorway networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK electric vehicle battery electrolyte market is accelerating into a vertical-integration race as players pursue captive lithium salt supply to escape German and Asian input cost volatility.
For Market Incumbents: Cement supply security through backward integration into lithium salt processing or binding long-term offtake agreements with German chemical producers. Solid-state electrolyte ventures threaten incumbent liquid formulation market share; BASF and Solvay SA should expand Midlands technical service capacity to compress customer qualification timelines ahead of 2030 domestic content thresholds. For New Entrants and Emerging Players: Launch via direct supply contracts with South Wales gigafactory corridor projects, where greenfield capacity lacks incumbent supplier relationships. Agricultural vehicle electrification presents the most penetrable segment, with extreme temperature tolerance requirements favoring specialized ceramic electrolyte formulations over standardized liquid products. For Investors and Strategic Acquirers: Re-rating potential sits with solid-state technology developers given British OEM cobalt-free architecture commitments and UK Battery Strategy R&D subsidies. Long-term viability favors materials science ventures with pilot-scale production capacity and BSI certification pathways. Watch for Ilika plc qualification milestones with automotive OEMs as the inflection indicator for ceramic electrolyte commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Processing | Captive supply of high-purity lithium hexafluorophosphate reduces exposure to German chemical base pricing volatility. |
| Solid-State Electrolyte Pilot Scale-Up | UK Battery Strategy R&D tax credits subsidize Ilika plc ceramic deposition technology for 2028-2030 OEM qualifications. |
| Long-Term Supply Agreement with Midlands Gigafactories | Direct offtake contracts with Coventry and Warwickshire cell manufacturers compress distributor margins and secure volume commitments. |
| Fluorinated Additive Manufacturing Expansion | Teesside chemical heritage provides skilled workforce pools to reduce REACH authorization delays for high-voltage cathode formulations. |
| Recycling Integration with Black Mass Processing | Closed-loop lithium sourcing from spent battery recovery aligns with UK Battery Strategy circular economy requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with electrolyte formulation chemists, Tier-1 cell manufacturer procurement leads, OEM platform engineers, and BSI certification laboratory directors combined with secondary validation from UN transport safety databases and UK Environment Agency hazardous substance permits. Bottom-up electrolyte volume estimates triangulated against top-down gigafactory capacity announcements across the Midlands and South Wales corridors.
Data-stream reconciliation across electrolyte chemistry tiers, vehicle application segments, and end-user contract structures shaped the analytical framework. Segmentation dimensions modeled include product chemistry, vehicle duty cycle, and domestic content qualification status. CAGRs derived from electrolyte demand intensity per gigawatt-hour of cell production capacity, with inputs from lithium salt pricing indices and fluorinated additive supply availability.
The model assumes a particular technology adoption path; alternative pathways for sulfide-based solid electrolytes would alter the outlook. Forecasts reflect assumptions regarding ZEV mandate enforcement timelines, REACH authorization progress for novel additives, and Midlands gigafactory construction schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
Battery-Powered Riveter Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Marine Low-Voltage Battery Market
Batteries
Zinc-Manganese Oxide Batteries Market
Batteries
Europe SLI Battery Market
Batteries
Europe Battery Cell Market
Batteries
Forklift Battery Rental Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
Dry Cell Battery Market
Batteries
Iron Salt Battery Market
Batteries
South Africa Battery Market
Batteries
Automotive Start-Stop Battery Market
Batteries
AAA Battery Market
Batteries
US Solar Battery Market
Batteries
South America Rechargeable Battery Market