
 Primary Lithium Battery for Industrial Market | 2026-2036
Primary Lithium Battery for Industrial Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Lithium Battery for Industrial Market Insights
Aftermarket battery replacement and lifecycle management services is reconfiguring margin distribution across the industrial lithium supply chain. Panasonic leverages its vertical integration into cathode materials and cell assembly to sustain pricing power in high-durability applications. Saft anchors European demand through specialized lithium thionyl chloride formulations for extreme environment deployments. Maxell Holdings, Ltd. competes in compact form factors for precision instrumentation.
Primary lithium batteries for industrial use are non-rechargeable electrochemical cells employing lithium metal or lithium compounds as the anode, typically delivering nominal voltages of 3.0–3.6 volts with energy densities exceeding 200 Wh/kg and operational temperature ranges from minus 55 to plus 150 degrees Celsius for specialized variants. These cells serve critical functions where charging infrastructure is inaccessible, replacement cycles span multiple years, and failure carries substantial economic or safety consequences. Lithium manganese dioxide chemistry occupies the largest installed base across industrial backup power and utility metering due to its balance of cost, safety profile, and shelf stability exceeding ten years. Remote sensors represent the fastest-expanding application segment as IoT-enabled asset monitoring proliferates across pipeline infrastructure, agricultural systems, and environmental tracking networks. Manufacturing end-use maintains mature demand patterns tied to automated equipment and robotics requiring uninterrupted power during grid instability.
EPA hazardous waste classification rules under RCRA govern end-of-life handling for lithium primary cells deployed across United States industrial facilities. REACH substance restrictions and the EU Battery Regulation's due diligence framework constrain material sourcing and mandate supply chain transparency for cells sold into European manufacturing and telecommunications infrastructure. China's GB standards and SAMR market access certification shape product specifications for industrial equipment produced within or exported from Chinese manufacturing hubs. Stakeholders must monitor evolving carbon border adjustment mechanisms and chemistry-specific recycling mandates as regulatory fragmentation intensifies between jurisdictions.
Market Dynamics
The EU Battery Regulation's carbon footprint declaration mandate is forcing cell manufacturers to requalify suppliers and reengineer production documentation, compressing margins for non-compliant producers while rewarding early adopters of lifecycle transparency systems.
Growth Catalysts
- Remote sensor proliferation:IoT-enabled pipeline monitoring networks across North American oil and gas infrastructure are multiplying deployment volumes for long-life lithium thionyl chloride cells.
- REACH substance restrictions:ECHA's tightening controls on hazardous materials are accelerating substitution toward cleaner lithium manganese dioxide chemistries in European industrial applications.
- Utility metering modernization:Smart grid rollouts in South Korea and Germany are generating sustained demand for decade-rated backup power in distribution automation equipment.
Market Restraints
- Lithium metal supply concentration:Refining capacity for battery-grade lithium metal concentrates in Argentina and Chile creates input vulnerability for thionyl chloride cell producers.
- RCRA hazardous waste classification:EPA rules governing end-of-life handling impose costly disposal protocols on US industrial facilities operating large sensor fleets.
- Solid-state battery substitution:Emerging rechargeable alternatives threaten long-cycle replacement revenues in applications where charging infrastructure becomes feasible.
Strategic Opportunities
- Carbon border adjustment preparation:The EU's CBAM implementation timeline creates first-mover advantage for suppliers with verified low-carbon production footprints.
- Agricultural sensor networks:Precision irrigation and livestock monitoring in Australian and Brazilian farming regions remain underpenetrated for industrial primary lithium solutions.
- SAMR certification alignment:China's GB standards convergence with international IEC specifications opens streamlined access for qualified exporters to industrial equipment manufacturers in Shenzhen and Suzhou clusters.
Industry Challenges
- Electrolyte formulation expertise scarcity:Specialized knowledge in non-aqueous lithium chemistry safety engineering concentrates among aging technical workforces in Japan and France.
- UN 38.3 certification timeline compression:Transport safety testing protocols for new cell formats extend product qualification cycles, delaying revenue recognition for variant launches.
- Legacy system voltage compatibility:Industrial automation equipment designed around alkaline battery discharge curves requires redesign investment to optimize lithium performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Lithium Battery for Industrial Market |
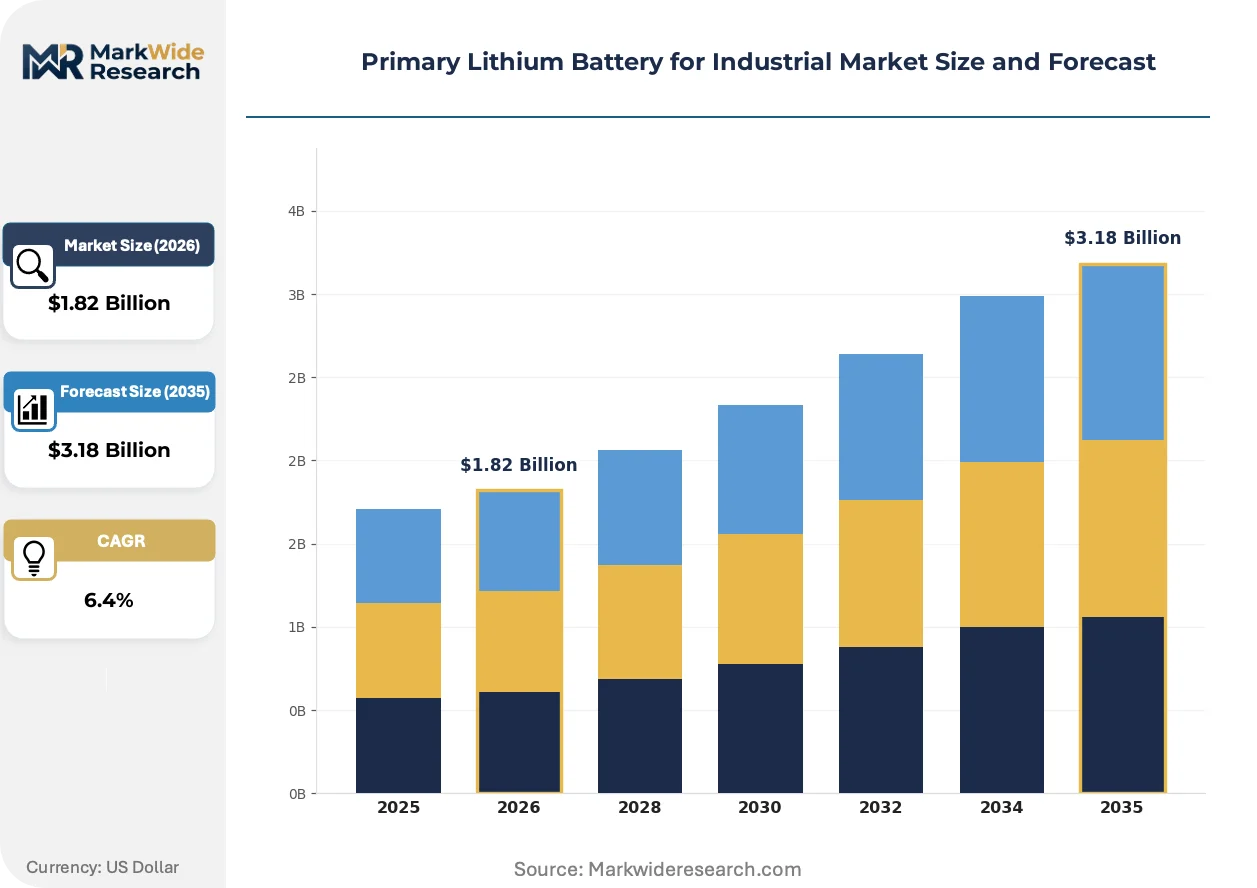
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Manganese Dioxide, Lithium Iron Phosphate, Lithium Cobalt Oxide, Lithium Nickel Manganese Cobalt End User: Manufacturing, Telecommunications, Renewable Energy, Automotive Application: Power Tools, Medical Devices, Backup Power, Remote Sensors Technology: Primary Cell, Non-Rechargeable, High Energy Density, Extended Shelf Life |
| Companies Covered | Panasonic, Wuhan FANSO Technology Co. Ltd., GP Batteries, Duracell Inc., Dongguan Large Electronic Co., Ltd, FDK Corporation, Excell Battery Co., Maxell Holdings, Ltd., Saft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Lithium Battery for Industrial Market Trends and Innovations
Cell chemistry innovation is hybridizing established formulations with emerging materials science, while regulatory transparency mandates and procurement restructuring are simultaneously reshaping how industrial buyers evaluate total cost of ownership.
Lithium thionyl chloride technology is hybridizing with solid electrolyte interfaces to extend operating temperature boundaries. Arctic exploration contractors and downhole drilling operators are piloting these formulations for minus 60 degree Celsius reliability. The convergence is compressing addressable market boundaries between primary lithium and emerging solid-state alternatives.
REACH substance restrictions are tightening disclosure requirements for conflict minerals and carbon intensity across European industrial supply chains. Battery assemblers must now document smelter origins and lifecycle emissions for qualification in German automotive and telecommunications procurement. Medium-format industrial cells face the steepest compliance cost escalation.
Industrial buyers are consolidating supplier relationships around lifecycle service bundling rather than transactional cell procurement. Oilfield services firms now contract for guaranteed replacement scheduling and waste take-back, displacing spot purchasing through distribution intermediaries. This restructuring concentrates procurement power with vertically integrated manufacturers in South Korea.
Primary Lithium Battery for Industrial Market Segmentation
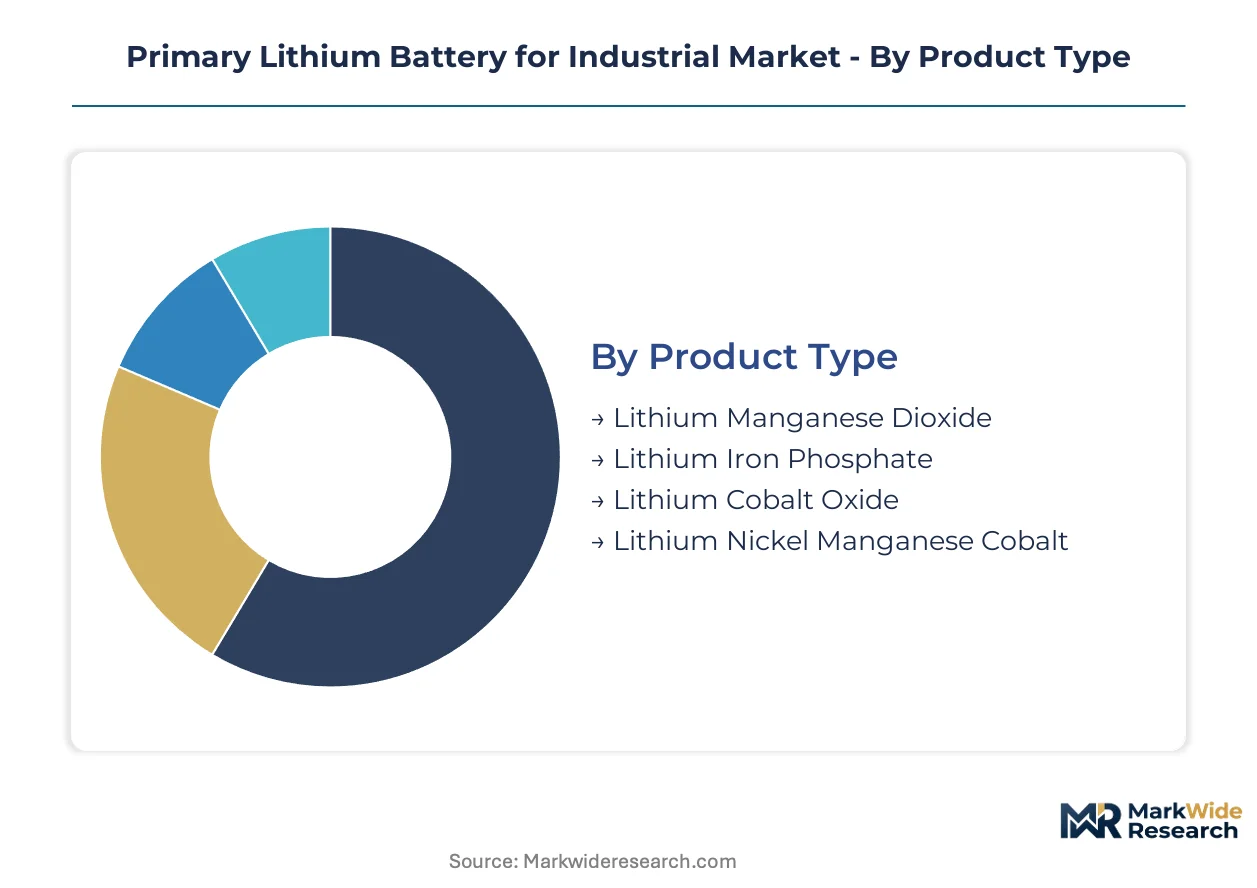
Industrial primary lithium batteries segment across chemistry, end-use, and functional specifications that determine procurement criteria. Buyers evaluate total cost of ownership through the lens of replacement cycle predictability and regulatory compliance burden rather than unit price alone.
Product Type:
Mature chemistries dominate installed base economics while emerging formulations capture specification-intensive niches.
- Lithium Manganese Dioxide:Delivers nominal 3.0V output with decade-plus shelf stability and balanced safety profile for utility metering. Demand concentrates in German smart grid infrastructure and South Korean distribution automation where REACH-compliant sourcing is mandatory.
- Lithium Iron Phosphate:Offers superior thermal stability and extended cycle tolerance for high-reliability backup systems. Deployment is accelerating across Chinese manufacturing hubs under GB standards alignment with IEC specifications for industrial equipment exports.
- Lithium Cobalt Oxide:Compact energy density suits precision instrumentation with severe space constraints.
- Lithium Nickel Manganese Cobalt:Hybrid cathode chemistry targets emerging applications requiring voltage stability across temperature extremes.
Lithium Manganese Dioxide retains volume leadership; Lithium Iron Phosphate holds the steepest expansion curve.
End User:
Customer concentration patterns split between asset-intensive process industries and infrastructure-dependent service sectors.
- Manufacturing:Automated production lines and robotics require uninterrupted power during grid instability events. Demand clusters in Shenzhen and Suzhou equipment clusters where SAMR certification gates market access.
- Telecommunications:Base station backup and network edge equipment depend on decade-rated cells for remote site reliability. German and South Korean carriers are consolidating procurement around lifecycle service bundling.
- Renewable Energy:Grid-tied storage monitoring and wind turbine control systems utilize primary cells for fail-safe instrumentation.
- Automotive:Tire pressure monitoring and telematics modules in commercial fleets specify industrial-grade primary lithium for temperature resilience.
Manufacturing commands the largest procurement volumes; Telecommunications is climbing the fastest as 5G infrastructure deployment extends.
Application:
Use-case differentiation tracks accessibility of charging infrastructure versus economic consequence of power failure.
- Remote Sensors:IoT-enabled pipeline monitoring across North American oil and gas infrastructure multiplies deployment volumes for long-life lithium thionyl chloride cells. Arctic exploration contractors are piloting minus 60 degree Celsius formulations.
- Backup Power:Distribution automation and critical control systems require predictable discharge profiles over multi-year replacement cycles. South Korean smart grid rollouts generate sustained demand for decade-rated specifications.
- Power Tools:Cordless industrial equipment specifies primary cells for explosive atmosphere compliance where rechargeable alternatives pose ignition risks.
- Medical Devices:Implantable and portable diagnostic equipment mandates traceable supply chains under FDA and EMA device regulations.
Backup Power maintains the broadest installed base; Remote Sensors are gaining share fastest as asset monitoring proliferates.
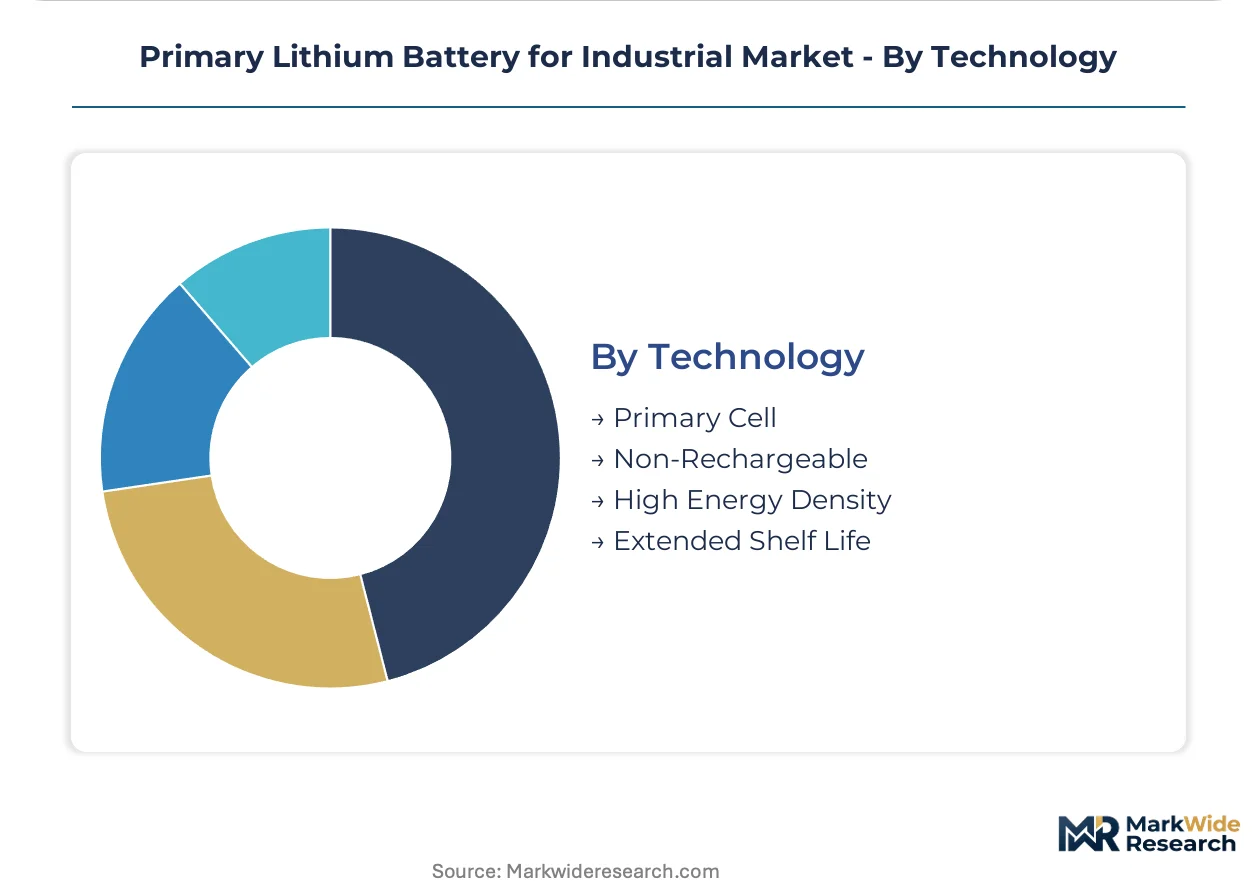
Technology:
Technical segmentation distinguishes fundamental electrochemical architecture from performance-tier specifications.
- Primary Cell:Non-reversible lithium metal anode chemistry eliminates charging infrastructure requirements. EPA RCRA hazardous waste classification governs end-of-life handling across United States industrial facilities.
- Non-Rechargeable:Single-use design mandates replacement cycle forecasting and inventory management for remote deployment sites.
- High Energy Density:Exceeding 200 Wh/kg enables compact form factors for precision instrumentation and aerospace applications.
- Extended Shelf Life:Ten-plus year stability ratings reduce total cost of ownership for infrequently accessed backup systems.
Primary Cell architecture anchors the technology base; High Energy Density specifications are expanding most quickly into weight-constrained applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial primary lithium battery consumption patterns diverge sharply between geographies: European buyers prioritize regulatory compliance and lifecycle transparency, while Asian procurement emphasizes manufacturing integration and export certification alignment. North American demand concentrates in extreme-environment applications where charging infrastructure proves infeasible.
Germany
Smart grid infrastructure and distribution automation equipment drive demand for decade-rated lithium manganese dioxide cells. The EU Battery Regulation's carbon footprint declaration mandate forces requalification of suppliers serving German telecommunications and automotive procurement. Industrial buyers in Munich and Stuttgart manufacturing clusters now bundle lifecycle services with cell purchases.
United States
IoT-enabled pipeline monitoring across Permian Basin and Bakken shale formations multiplies deployment volumes for lithium thionyl chloride cells in minus 40 degree Celsius conditions. EPA RCRA hazardous waste classification rules govern end-of-life handling for sensor fleets operated by oilfield services firms. Houston-based energy equipment distributors consolidate procurement around guaranteed replacement scheduling.
China
Automated production lines and robotics in Shenzhen and Suzhou equipment clusters require uninterrupted backup power during grid instability events. SAMR certification alignment with IEC specifications gates market access for industrial equipment exports. GB standards convergence creates streamlined qualification pathways for cell assemblers serving multinational manufacturing hubs.
South Korea
5G base station backup and network edge equipment generate sustained demand for long-life specifications in telecommunications infrastructure. Smart grid rollouts by Korea Electric Power Corporation drive decade-rated procurement for distribution automation. Seoul-based carriers consolidate supplier relationships around bundled lifecycle service contracts displacing spot purchasing.
Japan
Precision instrumentation and aerospace applications specify compact high-energy density formats exceeding 200 Wh/kg. METI industrial standards shape safety engineering requirements for non-aqueous lithium chemistry deployment. Nagoya and Osaka manufacturing clusters retain specialized electrolyte formulation expertise concentrated among aging technical workforces.
Primary Lithium Battery for Industrial Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct player categories: diversified electronics conglomerates with backward integration into cathode materials, specialized battery manufacturers with proprietary chemistry formulations, and regional fabricators serving price-sensitive industrial segments. Consolidation pressures intensify as lifecycle service bundling displaces transactional procurement. Two dominant competitive moves reshape positioning: vertical integration into raw material supply chains and strategic partnerships with industrial equipment OEMs for co-designed power systems.
Within the diversified conglomerate tier, Panasonic exemplifies scale-driven positioning through captive supply of critical components. Saft occupies a position representing European specialized manufacturing with chemistry-specific expertise for extreme environments. Among Asia-Pacific fabricators, Maxell Holdings, Ltd. and Wuhan FANSO Technology Co. Ltd. exemplify regional production concentration serving precision instrumentation and utility metering applications respectively.
| Leading Market Players |
|---|
| Panasonic |
| Wuhan FANSO Technology Co. Ltd. |
| GP Batteries |
| Duracell Inc. |
| Dongguan Large Electronic Co., Ltd |
| FDK Corporation |
| Excell Battery Co. |
| Maxell Holdings, Ltd. |
| Saft |
| Others |
Pricing and Supply Chain Analysis
Argentina and Chile lithium metal refining concentration determines both pricing tier spreads and supply chain shape for thionyl chloride cell producers, compressing margins when feedstock volatility coincides with EU carbon border adjustment timelines.
Pricing Analysis
Long-term offtake contracts dominate procurement for German telecommunications and South Korean utility buyers, while spot purchasing persists among North American oilfield services distributors. Pricing stratifies across premium, standard, and economy tiers based on REACH compliance certification and guaranteed replacement scheduling bundling. Cost compression in standard-tier cells is intensifying because Chinese GB-standard producers are expanding export capacity. Manufacturing end-users in Shenzhen equipment clusters exhibit highest price sensitivity; Arctic exploration contractors demonstrate lowest sensitivity due to failure-cost consequences.
Supply Chain Analysis
Contract manufacturing capacity for industrial primary lithium cells concentrates in South Korea, Japan, and selected Chinese provinces with SAMR-certified facilities. Production draws from battery-grade lithium metal feedstock, thionyl chloride electrolyte precursors, and specialized separator membranes. Single-source vulnerability runs through Argentine lithium metal refining infrastructure. Distribution runs through industrial equipment OEM direct procurement channels and authorized distributor networks serving oilfield and utility sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lifecycle service bundling now expands faster than hardware unit sales, transforming procurement economics for oilfield services firms and telecommunications carriers seeking guaranteed replacement scheduling.
For Market Incumbents: Pre-empt solid-state rechargeable substitution threats by deepening captive cathode material production and securing long-term lithium metal offtake from Argentine refiners. Accelerate EU Battery Regulation compliance documentation to defend qualification status in German automotive and telecommunications procurement. For New Entrants and Emerging Players: Establish a beachhead in Australian and Brazilian agricultural sensor networks where precision irrigation demand remains underpenetrated for industrial primary lithium solutions. Pursue SAMR certification alignment as the primary go-to-market pathway for equipment exports from Shenzhen and Suzhou manufacturing clusters. For Investors and Strategic Acquirers: The EU Battery Regulation's carbon footprint declaration mandate reshapes the acquisition landscape toward suppliers with verified low-carbon production footprints and lifecycle transparency systems. Target specialized electrolyte formulation capabilities concentrated among aging technical workforces in Japan and France. Watch for CBAM implementation acceleration as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Panasonic's captive manganese dioxide production sustains pricing power in German smart grid procurement. |
| Lifecycle Service Bundling | Oilfield services firms now contract guaranteed replacement scheduling, displacing spot distribution channels. |
| EU Carbon Border Adjustment Preparation | Early adopters of verified low-carbon footprints capture first-mover advantage in European telecommunications. |
| SAMR Certification Alignment | GB standards convergence with IEC specifications opens streamlined access to Chinese industrial equipment exports. |
| Electrolyte Formulation Expertise Acquisition | Specialized non-aqueous lithium chemistry knowledge concentrates among aging technical workforces in Nagoya and Osaka. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at industrial equipment manufacturers, procurement leads at oilfield services firms, telecommunications infrastructure planners, and aftermarket service heads at battery distributors, then refined through secondary validation against SEC filings, SAMR certification registries, ECHA REACH substance databases, and IEC technical committee documentation. Bottom-up demand modeling across chemistry types and end-use segments was triangulated with top-down market sizing from trade flow analysis.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled by chemistry type, end-use industry, application accessibility, and regional regulatory cluster. CAGRs were derived from replacement cycle forecasting and installed base penetration curves. Forecast inputs incorporated smart grid rollout schedules by Korea Electric Power Corporation and North American pipeline infrastructure monitoring deployment rates.
Stress conditions across lithium metal feedstock pricing, EU carbon border adjustment implementation timing, and solid-state battery commercialization velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding replacement cycle predictability and regulatory compliance cost trajectories. Quarterly review of SAMR certification queue lengths and ECHA substance restriction proposal timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Europe Industrial Battery Market
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
Micro Mobility Battery PACK Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
Custom Battery Pack Market
Batteries
Second-Life Automotive Battery Module Systems Market
Batteries
South America Consumer Battery Market
Batteries
Aluminum Based Battery Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
China Electric Vehicle Vrla Batteries Market
Batteries
Power-Sports Batteries Market
Batteries
Global Marine Battery Market
Batteries
Battery-Powered Riveter Market
Batteries
Battery Diagnostics and Repair Market
Batteries
India Battery Cell Market
Batteries
Tubular Batteries Market