
 Electric Ferry Market | 2026-2036
Electric Ferry Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Ferry Market Insights
Zero-emission certification tiers is collapsing the cost premium that diesel-hybrid systems once commanded in short-sea routes. ABB Ltd. leverages its DC grid architecture to dominate shore-to-ship power integration projects across Scandinavian terminals. Kongsberg Gruppen anchors its position through autonomous navigation software layered atop electric propulsion platforms. Wärtsilä Corporation differentiates via modular battery-hybrid packages that retrofit existing hulls without structural redesign.
An electric ferry is a passenger or vehicle-carrying vessel propelled by electric motors drawing power from batteries, fuel cells, or shore-charged hybrid systems, typically operating at service speeds of 12–25 knots with installed power ranging from 500 kW to 4 MW depending on route length and payload. These vessels eliminate onboard combustion during transit, serving commuter corridors, island supply chains, and tourism circuits where frequent port calls enable charging intervals. Catamaran hull configurations lead order books due to superior deck-area-to-drag ratios that extend battery range, while fuel-cell power sources represent the fastest-expanding segment for routes exceeding 50 nautical miles where shore charging proves impractical. Aluminum construction material commands premium positioning in lightweight, high-speed designs, though steel persists in heavy-vehicle freight services where displacement hulls tolerate greater mass.
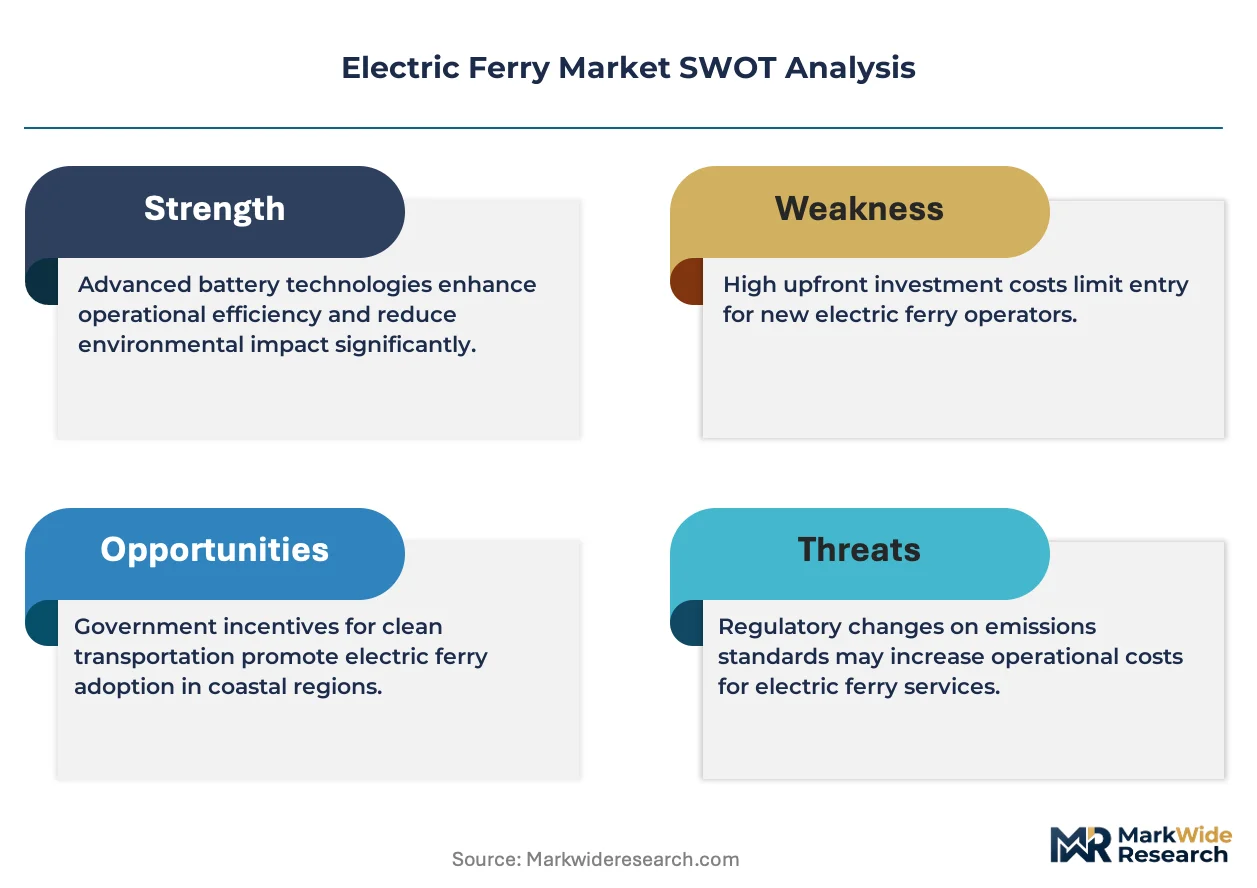
The EU Green Deal's Fit for 55 package mandates a 55% emissions reduction for maritime transport by 2030, forcing operators to retire diesel ferries or face carbon border adjustments on intra-European routes. Norway's NOx fund, administered by the country's environmental regulator, subsidizes up to 80% of cost overruns for first-of-class electric ferry conversions, directly shaping procurement timelines for municipal ferry services. Stakeholders must monitor whether battery-swapping standardization emerges as a dominant infrastructure model before committing to vessel-specific charging architectures that risk strandeding capital.
Market Dynamics
The collapse of zero-emission certification premiums is compressing vessel replacement cycles as municipal transit authorities accelerate diesel fleet retireures ahead of regulatory deadlines. Battery energy density gains and shore-side charging infrastructure buildouts are eliminating the operational range constraints that previously favored diesel-hybrid architectures on short-sea routes.
Growth Catalysts
- Norway's NOx Fund:The environmental regulator administers subsidies covering up to 80% of cost overruns for first-of-class electric ferry conversions, directly accelerating procurement timelines for municipal ferry services in Oslofjord and western fjord corridors.
- EU Green Deal Fit for 55:The 55% maritime emissions reduction mandate by 2030 forces operators to retire diesel ferries or absorb carbon border adjustments on intra-European routes, eliminating compliance alternatives for Baltic Sea operators.
- Catamaran hull configurations:Superior deck-area-to-drag ratios extend battery range sufficiently to electrify 40-60 nautical mile commuter corridors previously requiring combustion backup.
Market Restraints
- Lithium-ion cell supply concentration:Cathode active material refining concentrates in China, exposing European and North American ferry operators to input cost volatility and geopolitical supply disruption risks.
- Shore charging infrastructure capex:Grid reinforcement and high-power DC installation at remote island terminals requires capital outlays that strain municipal transit authority budgets without dedicated green infrastructure financing.
- Fuel-cell hydrogen storage density:Compressed hydrogen systems occupy 3-4x the volume of diesel equivalent, constraining passenger and vehicle payload on longer archipelago routes where battery-only operation proves insufficient.
Strategic Opportunities
- Battery-swapping standardization:Emergence of interoperable containerized battery modules would enable 15-minute turnaround times at unmanned island piers, opening electrification of seasonal tourism circuits in Greece and Croatia.
- Autonomous navigation convergence:Integration of collision-avoidance AI with electric propulsion platforms reduces crewing costs and extends viable route economics to low-density rural connections in Finland's lake districts.
- Retrofit modular battery-hybrid packages:Vessel-specific engineering services that install electric drivetrains without structural hull redesign capture the 15-20 year mid-life upgrade window for existing steel-hulled ferries.
Industry Challenges
- Marine electrical engineering talent scarcity:Specialized expertise in high-voltage DC distribution and thermal runaway containment systems remains concentrated among Scandinavian naval architects, constraining fleet expansion timelines for Mediterranean operators.
- Type certification timeline compression:Classification societies lack standardized protocols for fuel-cell propulsion, forcing case-by-case approval processes that extend newbuild delivery schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Ferry Market |
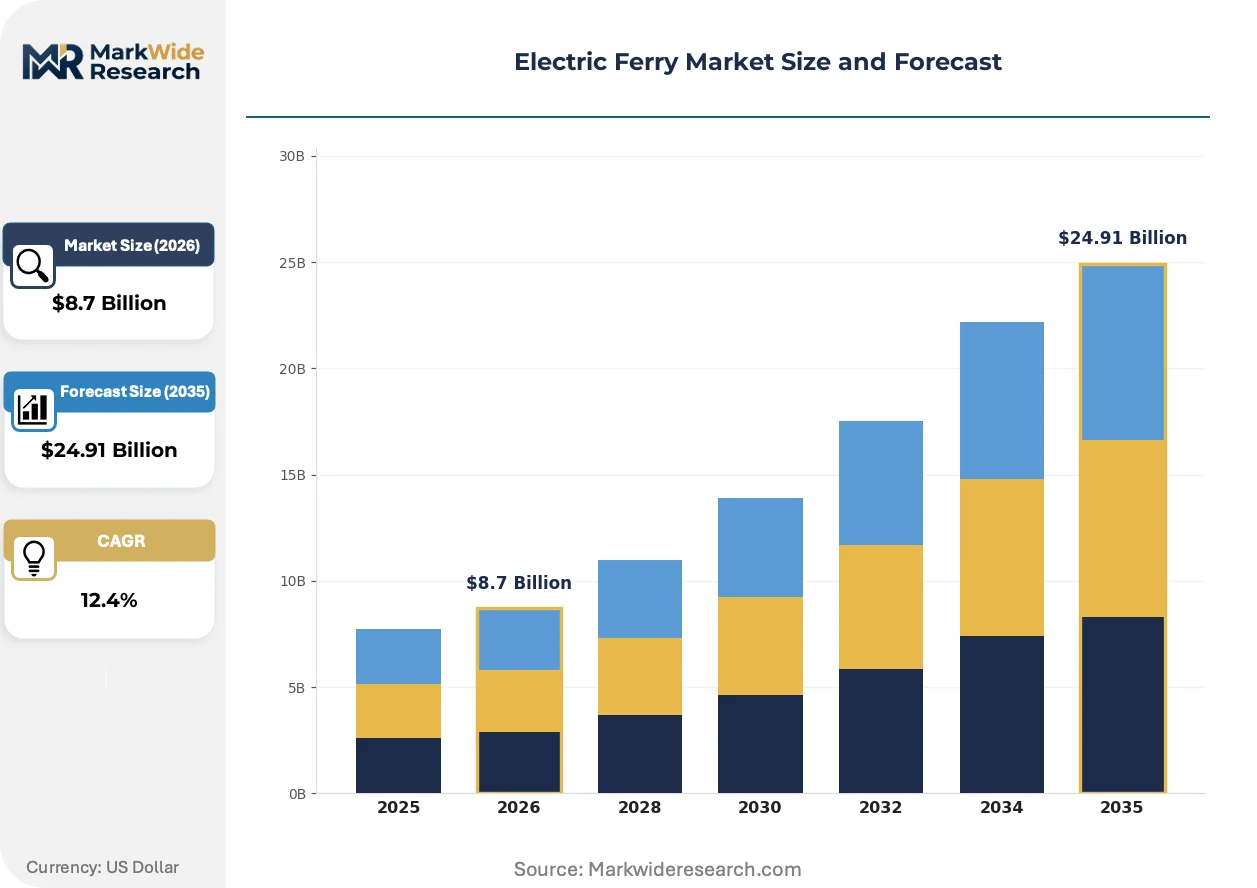
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Cataferry, Hydrofoil, Monohull, Catamaran Power Source: Battery, Hybrid, Fuel Cell, Solar End User: Public Transportation, Tourism, Freight Services, Government Construction Material: Aluminum, Steel, Composite, Others |
| Companies Covered | Kongsberg Gruppen, Mitsubishi Heavy Industries, Ltd., ABB Ltd., The Damen Group, Hyundai Heavy Industries Co., Ltd., Siemens AG, Rolls-Royce Holdings plc, Incat Tasmania Pty Ltd, Wärtsilä Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Ferry Market Trends and Innovations
Electrification architectures are diverging sharply between battery-dominant short-haul designs and fuel-cell range extenders for archipelago networks, with hull material selection and charging infrastructure models tracking these technical bifurcations.
Solid-state battery chemistries are fragmenting the propulsion supplier landscape. Silicon-anode and lithium-metal cell technologies promise 40% energy density improvements over incumbent NMC formulations. Norwegian route operators are piloting these systems on 50-nautical-mile fjord crossings. The technology is fragmenting vendor consolidation by enabling smaller battery footprints that retrofit existing hull volumes without passenger capacity sacrifice.
EU Green Deal implementation is tightening operational constraints. The Fit for 55 maritime emissions mandate eliminates grandfathering provisions for existing diesel ferries on intra-EU routes. Baltic Sea operators face carbon border adjustments beginning 2026. Island municipalities in Denmark and Sweden are responding by bundling shore charging infrastructure with vessel procurement tenders to lock in total-cost-of-ownership advantages.
Service contracting is unbundling from vessel ownership. Municipal transit authorities in Norway and Finland are shifting from capital purchase to power-by-the-hour agreements where propulsion system suppliers retain battery asset ownership and performance risk. This transfers operational technology obsolescence exposure from public balance sheets to private operators. The model is most visible in Stockholm's archipelago network and Turku's island commuter services.
Electric Ferry Market Segmentation
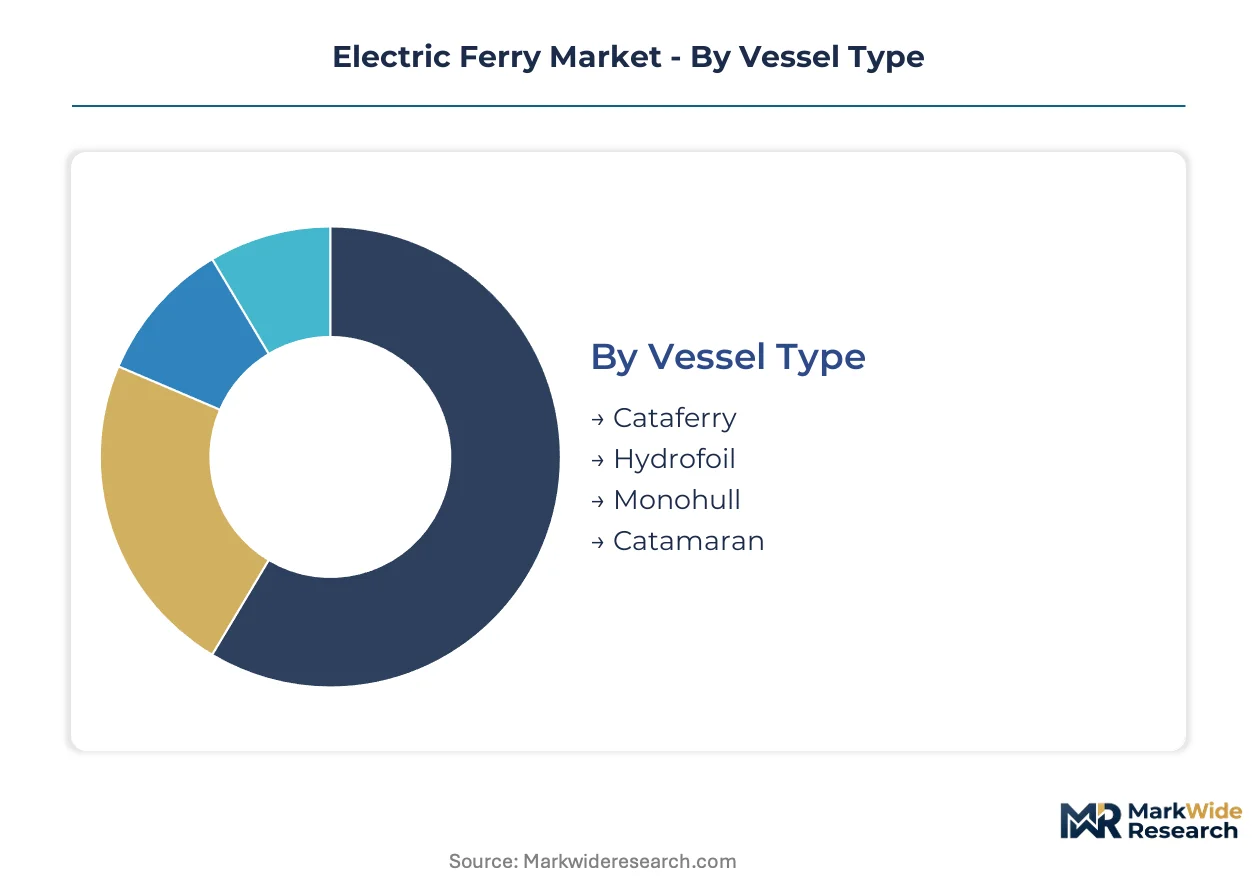
Electrification pathways diverge sharply across vessel architectures and operational profiles. Procurement channels track these technical bifurcations, with municipal transit authorities favoring standardized battery platforms while private operators experiment with fuel-cell range extenders.
Vessel Type:
Channel distribution concentrates catamaran orders through integrated fleet procurement contracts with Scandinavian municipal authorities, while monohull retrofits flow through specialized naval architecture firms serving freight operators.
- Catamaran:Twin-hull geometry delivers superior deck-area-to-drag ratios that extend battery range on 40-60 nautical mile commuter corridors. Norwegian fjord routes and Stockholm's archipelago network concentrate demand, driven by EU Green Deal compliance deadlines forcing diesel fleet replacement.
- Monohull:Displacement hulls tolerate greater structural mass for heavy-vehicle freight services where battery weight penalties prove acceptable. Baltic Sea roll-on/roll-off operators in Germany and Poland anchor procurement volumes, constrained by limited shore charging infrastructure at secondary ports.
- Cataferry:High-speed planing catamarans serve seasonal tourism circuits in Greece and Croatia where 25-knot service speeds justify premium pricing.
- Hydrofoil:Foiling hulls reduce wetted surface drag by 40-50%, enabling battery-only operation on longer archipelago spans where conventional hulls require hybrid backup.
Catamaran configurations dominate installed base. Hydrofoil designs are where expansion concentrates.
Power Source:
Cost tier stratification separates battery-dominant systems in premium short-haul applications from fuel-cell hybrids commanding mid-tier pricing on extended routes.
- Battery:Lithium-ion NMC and emerging solid-state chemistries power zero-emission transit on routes under 50 nautical miles with regular port calls. Norway's NOx Fund subsidies accelerate municipal adoption across Oslofjord and western fjord corridors.
- Fuel Cell:Proton-exchange membrane systems paired with compressed hydrogen storage enable 200+ nautical mile range without shore charging. Danish island municipalities pilot these on Bornholm and Læsø routes where grid reinforcement proves uneconomical.
- Hybrid:Diesel-electric architectures with battery load-leveling serve transitional operators in Finland's lake districts awaiting charging infrastructure completion.
- Solar:Photovoltaic deck arrays supplement auxiliary loads on small passenger ferries in Mediterranean tourism markets with high insolation and seasonal operation patterns.
Battery systems anchor current installed capacity. Fuel cell configurations are gaining share fastest.
End User:
Application-specific requirements dictate procurement channel structure, with public transportation flowing through municipal tender processes and tourism operators favoring leasing arrangements.
- Public Transportation:Municipal transit authorities in Norway, Sweden, and Denmark mandate zero-emission fleet procurement through competitive tenders bundling vessel delivery with shore charging infrastructure. EU Green Deal Fit for 55 compliance eliminates diesel alternatives for intra-European routes.
- Tourism:Seasonal operators in Greece's Cyclades and Croatia's Dalmatian coast prioritize rapid turnaround and premium passenger experience over fuel efficiency metrics.
- Freight Services:Roll-on/roll-off operators across Baltic Sea corridors face carbon border adjustments that accelerate electric conversion timelines for heavy-vehicle decks.
- Government:Naval and coast guard procurement emphasizes mission endurance and redundancy, currently favoring hybrid architectures pending fuel-cell certification standardization.
Public transportation commands the largest order backlog. Tourism applications are expanding most quickly.
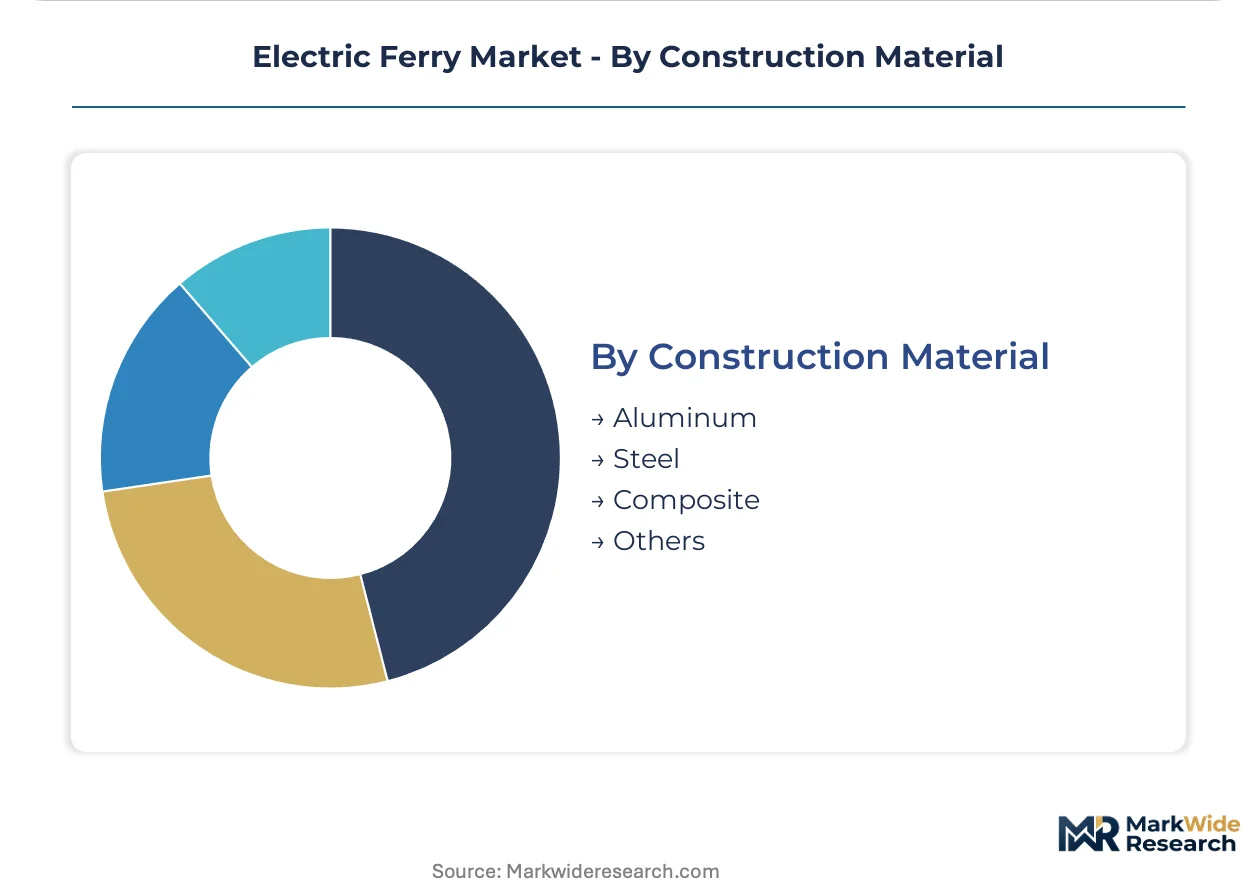
Construction Material:
Margin structure stratifies by material density and fabrication complexity, with aluminum commanding premium positioning in high-speed designs and steel retaining cost advantage in heavy-duty freight service.
- Aluminum:Lightweight alloy construction reduces hull mass by 30-40% versus steel, enabling smaller battery packs or extended range on equivalent energy storage. Norwegian high-speed commuter ferries and Swedish archipelago vessels concentrate demand.
- Steel:Conventional shipbuilding material persists in displacement hulls for heavy-vehicle freight where structural strength tolerates battery weight penalties without passenger capacity sacrifice.
- Composite:Fiber-reinforced polymer hulls serve specialized hydrofoil and small passenger craft where complex curvature and corrosion resistance justify premium material costs.
- Others:Experimental materials including recycled aluminum alloys and bio-based composites pilot in demonstration projects seeking circular economy certification.
Steel hulls retain dominant installed base share. Aluminum construction is where newbuild investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export dominance in electric ferry systems concentrates in Scandinavian engineering clusters while import demand concentrates in Mediterranean and Baltic coastal municipalities retrofitting aging diesel fleets. Norway maintains surplus capacity in battery-hybrid propulsion integration. Greek and Croatian island operators source complete vessel packages from Nordic yards.
Norway
Municipal transit authorities in Oslofjord and western fjord corridors drive procurement volumes through competitive tender bundling. The country's environmental regulator administers NOx Fund subsidies covering up to 80% of cost overruns for first-of-class conversions. Bergen and Stavanger anchor manufacturing clusters where Kongsberg Gruppen and local naval architects integrate autonomous navigation with electric platforms.
Sweden
Stockholm's archipelago network generates sustained demand for 40-60 nautical mile battery-dominant designs with rapid turnaround capability. The Swedish Transport Administration mandates zero-emission fleet procurement deadlines aligned with EU Green Deal Fit for 55 compliance. Gothenburg shipyards specialize in aluminum catamaran construction for high-speed commuter corridors.
Denmark
Island municipalities on Bornholm and Læsø pilot fuel-cell range extenders where grid reinforcement proves uneconomical. The Danish Maritime Authority streamlines type certification for hydrogen propulsion through bilateral Nordic agreements. Copenhagen terminals integrate shore-side charging infrastructure with vessel procurement to lock in total-cost-of-ownership advantages.
Germany
Baltic Sea roll-on/roll-off operators face carbon border adjustments accelerating electric conversion timelines for heavy-vehicle decks. The Federal Maritime and Hydrographic Agency enforces emissions monitoring protocols that eliminate diesel alternatives for intra-European routes. Kiel and Rostock concentrate retrofit engineering services for mid-life steel-hulled freight ferries.
Greece
Seasonal tourism circuits in the Cyclades prioritize rapid turnaround and premium passenger experience over fuel efficiency metrics. The country's national maritime regulator adapts EU Green Deal implementation timelines to accommodate seasonal operational patterns. Piraeus serves as the primary import hub for Nordic-built electric vessels entering Mediterranean service.
Electric Ferry Market Competitive Landscape
Concentration sits with integrated marine electrification specialists possessing shore-to-ship power architecture and autonomous navigation software capabilities. The vendor base organizes around three strategic archetypes: full-system integrators controlling DC grid and charging infrastructure; hull builders with captive electric propulsion engineering; and modular retrofit specialists capturing mid-life upgrade windows. Competitive moves center on power-by-the-hour service contracting and battery asset ownership retention.
Among Nordic-based system integrators, ABB Ltd. and Kongsberg Gruppen exemplify the full-architecture archetype, while Wärtsilä Corporation occupies a position within the modular retrofit tier. These entities represent divergent strategic postures—vertical control over shore-side infrastructure versus vessel-specific engineering flexibility—without exclusive segment capture.
| Leading Market Players |
|---|
| Kongsberg Gruppen |
| Mitsubishi Heavy Industries, Ltd. |
| ABB Ltd. |
| The Damen Group |
| Hyundai Heavy Industries Co., Ltd. |
| Siemens AG |
| Rolls-Royce Holdings plc |
| Incat Tasmania Pty Ltd |
| Wärtsilä Corporation |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month battery module lead times from Korean cell suppliers concentrate pricing power among Scandinavian system integrators who locked in cathode supply contracts before lithium carbonate volatility spiked. Municipal transit authorities in Norway and Sweden absorb these premiums through NOx Fund subsidies, while Greek and Croatian operators face sticker shock on Nordic-built hulls.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures where vessel procurement bundles shore charging infrastructure and 15-year service contracts. Pricing stratifies across fully electric, battery-hybrid, and fuel-cell range-extender tiers based on route length certification and autonomous navigation capability inclusion. Cost compression in battery-dominant configurations is intensifying because solid-state chemistry pilots are collapsing energy density premiums. Freight operators in Baltic Sea corridors exhibit highest price sensitivity due to carbon border adjustment exposure, while Norwegian municipal authorities show lowest sensitivity given subsidy coverage.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg has extended inbound logistics cycles for aluminum hull sections sourced from Norwegian extrusion plants, forcing Gothenburg shipyards to carry 90-day fabricator inventory. Cathode active material refining concentrates in China, South Korea, and Japan, while aluminum smelting feeds from Norwegian hydroelectric facilities and German rolling mills. Single-source vulnerability sits with Chinese lithium hydroxide processing. Distribution runs through integrated fleet procurement contracts with municipal transit authorities rather than spot vessel sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU Green Deal compliance deadlines and NOx Fund subsidy structures creates defensive moats for incumbent system integrators with established shore-to-ship power architectures.
For Market Incumbents: Consolidate control over shore charging infrastructure deployment to lock out modular retrofit specialists attempting to bypass DC grid integration. Deepen captive supply of solid-state battery modules through Korean cathode partnerships before chemistry standardization settles. Threat exposure from Chinese lithium refining concentration demands alternative supply anchoring. For New Entrants and Emerging Players: Differentiate on battery-swapping standardization for unmanned island piers in Greece and Croatia where grid reinforcement costs exclude conventional charging. Target seasonal tourism circuits with containerized lease structures that transfer technology obsolescence risk. Go-to-market leverage rests on 15-minute turnaround guarantees versus 45-minute conventional fast-charge cycles. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EU Fit for 55 mandates eliminate diesel alternatives regardless of hydrogen cost parity timelines. Acquisition targets should display integrated shore-power engineering capabilities and existing Nordic municipal contract relationships. Signal to watch is battery-swapping standardization adoption rates in Mediterranean markets.| Strategic Initiative | Industry Significance |
|---|---|
| Shore Charging Infrastructure Bundling | Municipal tenders in Norway and Sweden now mandate integrated vessel-charging packages, locking in total-cost-of-ownership advantages. |
| Solid-State Battery Pilot Programs | Norwegian route operators testing silicon-anode cells on 50-nautical-mile fjord crossings are fragmenting vendor consolidation. |
| Fuel-Cell Range Extender Certification | Danish Maritime Authority bilateral agreements with Nordic regulators accelerate hydrogen propulsion approval timelines. |
| Autonomous Navigation Convergence | Kongsberg Gruppen integration of collision-avoidance AI reduces crewing costs for low-density Finnish lake district connections. |
| Retrofit Modular Battery-Hybrid Deployment | Wärtsilä Corporation engineering services capture 15-20 year mid-life upgrade windows for existing steel-hulled Baltic freight ferries. |
Research Methodology
Cross-validation between primary interviews with ferry procurement officers, naval architects, and shore infrastructure engineers and secondary validation through EU Green Deal implementation documents, NOx Fund disbursement records, and classification society type certification databases anchors the qualitative findings. Bottom-up vessel order book aggregation triangulates against top-down market sizing from maritime trade associations and port authority fleet registry data.
Sensitivity analysis across battery chemistry adoption curves, hydrogen storage density improvements, and shore charging infrastructure buildout rates frames the analytical approach over the projection horizon. Segmentation dimensions modeled include vessel architecture, power source configuration, end-use application, and construction material grade. CAGRs derive from route electrification timelines tied to regulatory compliance deadlines and municipal procurement cycle analysis.
Material uncertainties — lithium-ion cell supply disruption, fuel-cell certification timeline extensions, and battery-swapping standardization adoption — sit outside the modeled envelope. Forecasts reflect assumptions around subsidy continuity and cathode material cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Global Discount-Marine Trenchers Market
Marine
Marine Base Steering Gear Market
Marine
Marine Navigation System Market
Marine
Tele-Operated Marine Drone Market
Marine
Marine Trenchers Market
Marine
Marine Bearings Market
Marine
Ship Rudders Market
Marine
Marine Chronometers Market
Marine
North Sea Offshore Support Vessels Market
Marine
Global Marine Gearbox Market
Marine
Marine Elevators Market
Marine
Azimuth Thrusters Market
Marine
Marine Interiors Market
Marine
Autonomous Ships Market
Marine
Buoys and Beacon Market
Marine
Marine Communication Market