
 Laser Interferometer Market | 2026-2036
Laser Interferometer Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Interferometer Market Outlook
Software-defined interferometry with subscription-based analytics is consolidating the value proposition around predictive maintenance rather than hardware ownership alone. Renishaw plc leverages its encoder and calibration heritage to anchor premium positioning in semiconductor fab installations. Zygo Corporation sustains dominance in optical surface profiling through captive polishing and coating capabilities that tighten specification control. Keysight Technologies competes by extending test-and-measurement software stacks into interferometric data workflows.
A laser interferometer measures optical path differences with sub-wavelength resolution, typically employing helium-neon lasers at 632.8 nanometers to detect displacements below one nanometer for dimensional metrology and motion control. Michelson architectures occupy the largest installed base due to proven stability in cleanroom environments, while Fabry-Pérot configurations represent the fastest-growing category as cavity-enhanced sensing penetrates gravitational wave detection and quantum research. Precision Measurement applications command the deepest margin pools because semiconductor and optics manufacturers require NIST-traceable certificates for process qualification.
FDA device-quality regulations and ISO 14253 uncertainty standards shape product design and calibration service bundling in the United States, while REACH and CE marking constrain optical coating chemistries and laser safety classifications across European sales channels. The EU AI Act introduces emerging compliance dimensions for automated defect-classification algorithms embedded in modern interferometer software. Stakeholders must weigh capital deployment between hardware refresh cycles and analytics platform subscriptions as procurement criteria shift from specification sheets to total cost of ownership models.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are driving metrology capital deployment as EUV lithography nodes below 3nm tighten dimensional tolerances to sub-nanometer thresholds. This precision imperative is compressing calibration cycles and forcing interferometer vendors to bundle predictive analytics with hardware.
Growth Catalysts
- ISO 230 traceability mandates:EU Machinery Directive compliance requirements are pushing European machine tool builders toward laser-based calibration systems with NIST-traceable certificates.
- Gravitational wave detection infrastructure:Fabry-Pérot cavity-enhanced interferometry architectures are penetrating advanced physics research facilities, expanding addressable instrumentation demand.
- Taiwan semiconductor corridor:TSMC and foundry suppliers are expanding metrology budgets to qualify EUV process chambers, anchoring regional equipment procurement.
Market Restraints
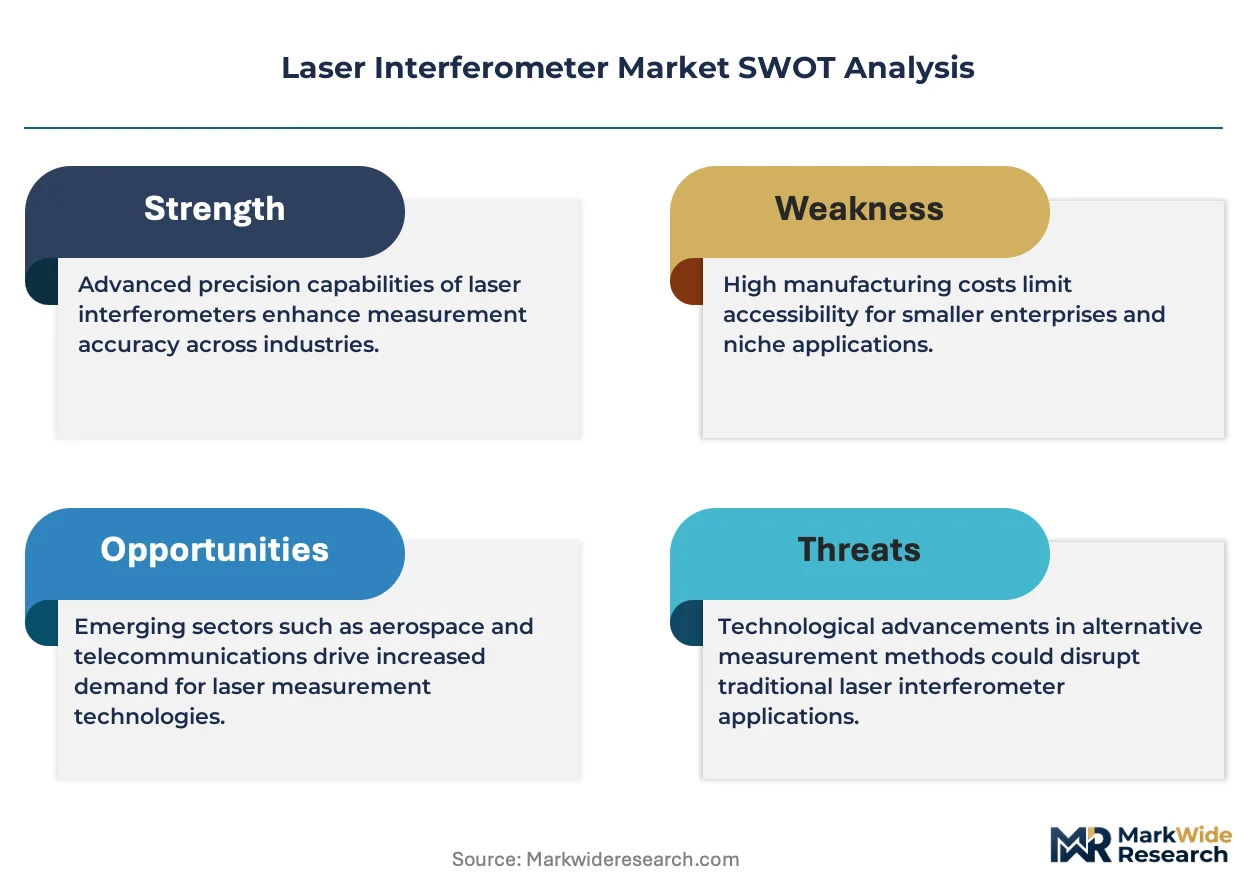
- Helium-neon laser supply concentration:Specialty gas supply chains for 632.8nm laser tubes concentrate in limited geographic corridors, creating input cost volatility.
- Cleanroom infrastructure requirements:Michelson architecture stability demands vibration-isolated environments, constraining deployment in legacy manufacturing floors.
- Atomic force microscopy substitution:AFM systems below 50nm resolution are capturing surface profiling applications from optical interferometry in certain semiconductor inspection workflows.
Strategic Opportunities
- India PLI scheme alignment:Production-linked incentives for semiconductor fabs in Gujarat and Tamil Nadu are creating greenfield metrology demand as domestic fabrication capacity scales.
- Quantum sensing convergence:Integration of squeezed-light interferometry with cold-atom platforms is opening cavity-based sensing applications beyond traditional dimensional metrology.
- Subscription analytics platforms:Software-defined interferometry with predictive maintenance algorithms is displacing perpetual-license models, capturing recurring revenue streams.
Industry Challenges
- Interferometric data science talent scarcity:Shortages of physicists capable of bridging optical hardware with machine-learning defect classification are constraining vendor R&D velocity.
- ISO 14253 uncertainty certification timelines:Extended calibration validation cycles for NIST-traceable instruments are delaying fab qualification schedules and compressing vendor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Interferometer Market |
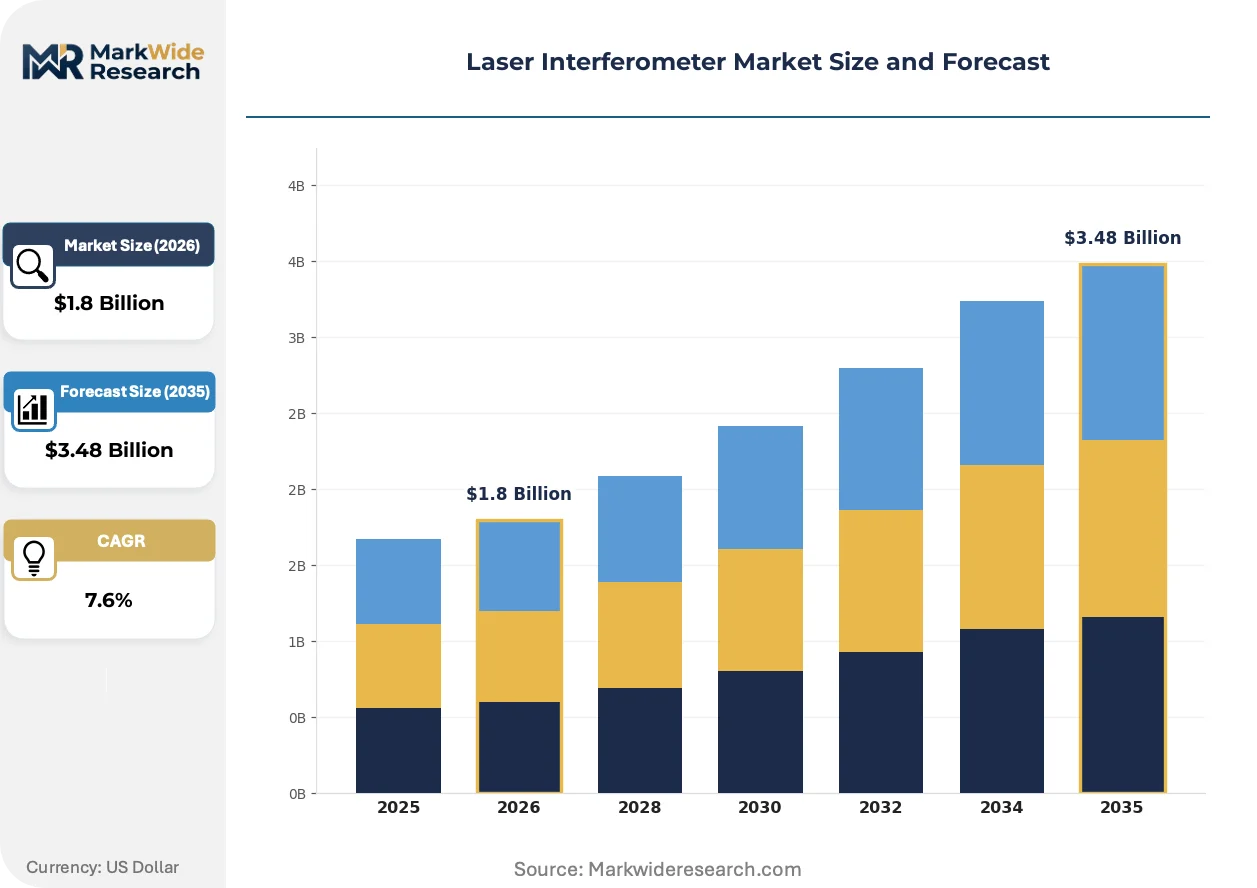
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Fizeau, Michelson, Fabry-Pérot, Homodyne Application: Precision Measurement, Distance Measurement, Surface Profiling, Structural Monitoring End User: Aerospace, Automotive, Electronics, Manufacturing Component: Laser Source, Beam Splitter, Detector, Lens |
| Companies Covered | Renishaw plc, Zygo Corporation, Keysight Technologies, SIOS Meßtechnik GmbH, ZEISS Group, Mahr GmbH, AMETEK, Inc., Bruker Corporation, Optodyne, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Interferometer Market Strategic Shifts
Machine-learning defect classification algorithms embedded in interferometer control software are compressing inspection cycle times and shifting competitive advantage toward analytics capabilities. Vendors are racing to automate interpretation workflows that previously required specialized optical physicists.
Convolutional neural networks trained on interferometric fringe patterns are automating surface defect identification in semiconductor wafer inspection. Leading foundries in Taiwan and South Korea are deploying these systems at 100% incoming inspection stations. The technology is automating what previously required human operator judgment, compressing throughput bottlenecks in high-volume manufacturing.
REACH restrictions on optical coating chemistries are forcing European interferometer manufacturers to reformulate anti-reflective stacks and laser cavity materials. ECHA substance evaluations have flagged several legacy fluorinated compounds used in low-scatter mirrors. German and Swiss optical houses are responding by accelerating plasma-deposited oxide alternatives through qualification pipelines.
Fab operators are unbundling after-sales calibration contracts from initial hardware purchases, treating metrology services as consumable operational expenditures rather than capital attachments. This reconfiguration is most visible in South Korean memory manufacturing corridors where Samsung and SK Hynix procurement teams negotiate service-level agreements separately from equipment tenders. Vendors must now price hardware and analytics subscriptions independently while maintaining integrated system performance guarantees.
Laser Interferometer Market Segmentation
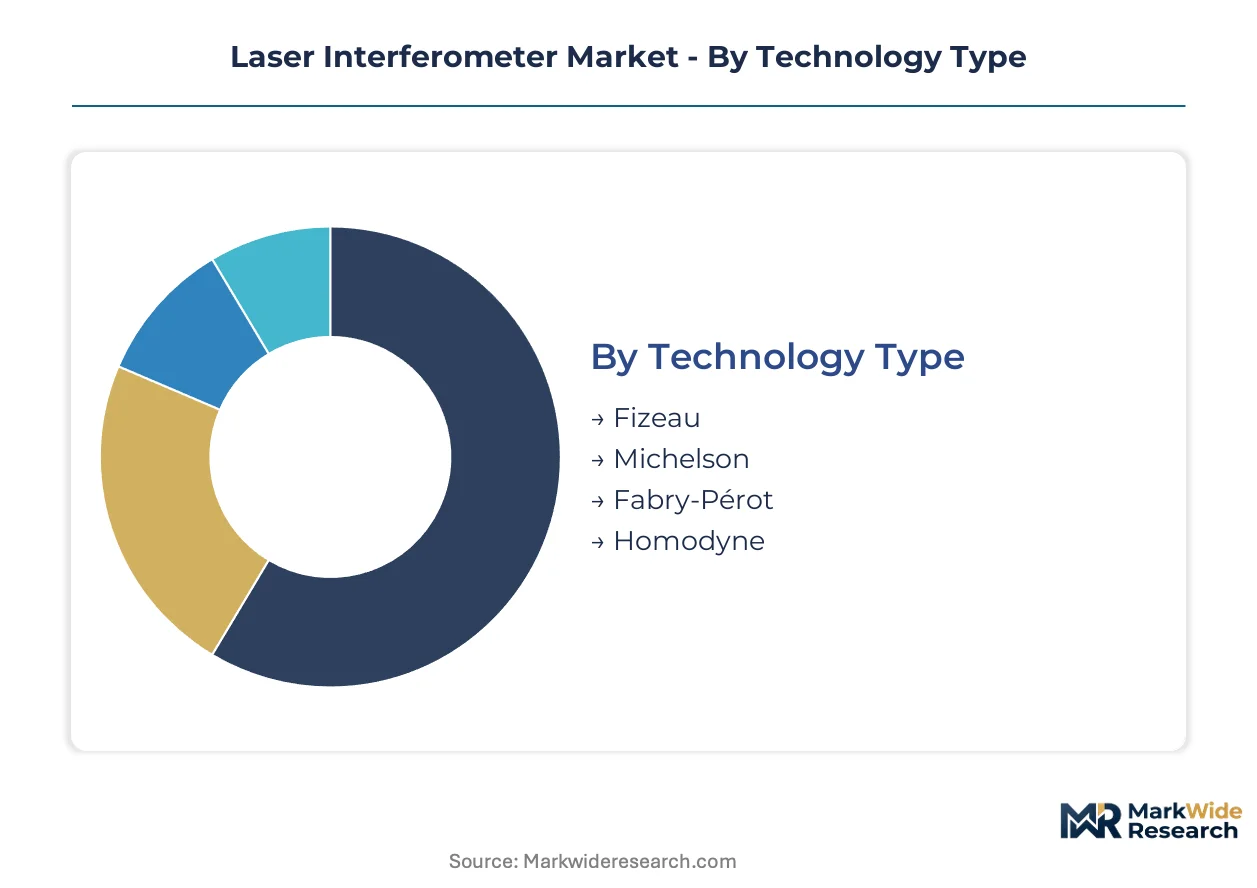
Segmentation in laser interferometry reveals how precision requirements cascade through technology choices, application workflows, and component architectures. Each dimension exposes distinct margin structures and vendor positioning strategies that shape procurement patterns across semiconductor fabs, aerospace calibration labs, and optical manufacturing facilities.
Technology Type:
Michelson architectures dominate standalone metrology installations where vibration isolation is achievable, while Fabry-Pérot configurations embed into integrated sensing systems for cavity-enhanced detection.
- Michelson:Two-beam interference geometry splits a coherent source into reference and measurement arms, recombining them to detect sub-nanometer displacements. Taiwan and South Korea semiconductor fabs deploy these in EUV lithography qualification chambers where NIST-traceable dimensional verification governs yield. ISO 230 calibration mandates compress replacement cycles for aging installations.
- Fabry-Pérot:Multiple-beam interference within a resonant cavity amplifies sensitivity to optical path length changes. Gravitational wave observatories in the United States and Germany anchor demand as LIGO and Virgo infrastructure expands detection bandwidth. Cavity-enhanced sensing penetrates quantum research facilities seeking squeezed-light measurement limits.
- Fizeau:Common-path interferometry using a partially reflecting reference surface enables rapid optical testing of flat and spherical components. Lens manufacturers in Japan and Germany employ Fizeau configurations for production-line surface figure verification.
- Homodyne:Single-frequency detection scheme measures phase shifts through direct intensity comparison. Cost-sensitive industrial alignment systems in Chinese manufacturing corridors adopt homodyne architectures for machine tool positioning feedback.
Volume placements concentrate in Michelson architectures for precision metrology; the faster expansion belongs to Fabry-Pérot cavity systems.
Application:
Application segmentation separates process-qualification workflows requiring certified uncertainty budgets from production-line monitoring where throughput dominates specification priorities.
- Precision Measurement:Dimensional metrology for semiconductor wafer geometry and optical component figure verification demands NIST-traceable uncertainty statements. TSMC and Samsung foundries in Taiwan and South Korea drive capital deployment as EUV nodes tighten tolerances below one nanometer.
- Surface Profiling:Non-contact topography mapping of polished optics and thin-film coatings relies on phase-shifting interferometry. German and Swiss optical houses use these systems for EUV mirror qualification under REACH-compliant coating chemistries.
- Distance Measurement:Long-range displacement tracking for machine tool calibration and large-structure alignment employs heterodyne detection. European machine builders satisfy EU Machinery Directive traceability through laser-based calibration protocols.
- Structural Monitoring:Continuous deformation tracking for bridges, dams, and aerospace structures deploys fiber-coupled interferometric sensors. Infrastructure projects in Japan and California integrate these for seismic response characterization.
Revenue depth pools in Precision Measurement for semiconductor process control; Surface Profiling climbs fastest as EUV optics manufacturing scales.
End User:
End user segmentation distinguishes capital-intensive fabs with dedicated metrology teams from discrete manufacturers purchasing calibration services.
- Electronics:Semiconductor and display manufacturers operate the largest installed interferometer bases. Memory fabs in South Korea unbundle hardware purchases from predictive analytics subscriptions, treating metrology as operational expenditure.
- Aerospace:Satellite optics and precision guidance system manufacturers require vacuum-compatible interferometry for space-qualified component verification. Northrop Grumman and Airbus Defence facilities in the United States and France maintain captive calibration laboratories.
- Automotive:Powertrain precision and autonomous sensor alignment drive demand for portable laser calibration systems. German OEMs integrate interferometric feedback into electric motor assembly lines.
- Manufacturing:General machine tool builders and precision component suppliers purchase interferometry as contracted calibration services rather than capital equipment. Indian PLI scheme beneficiaries in Gujarat establish greenfield metrology capabilities.
Electronics commands the deepest margin pools; Manufacturing expands most quickly as subscription analytics penetrate mid-tier suppliers.
Component:
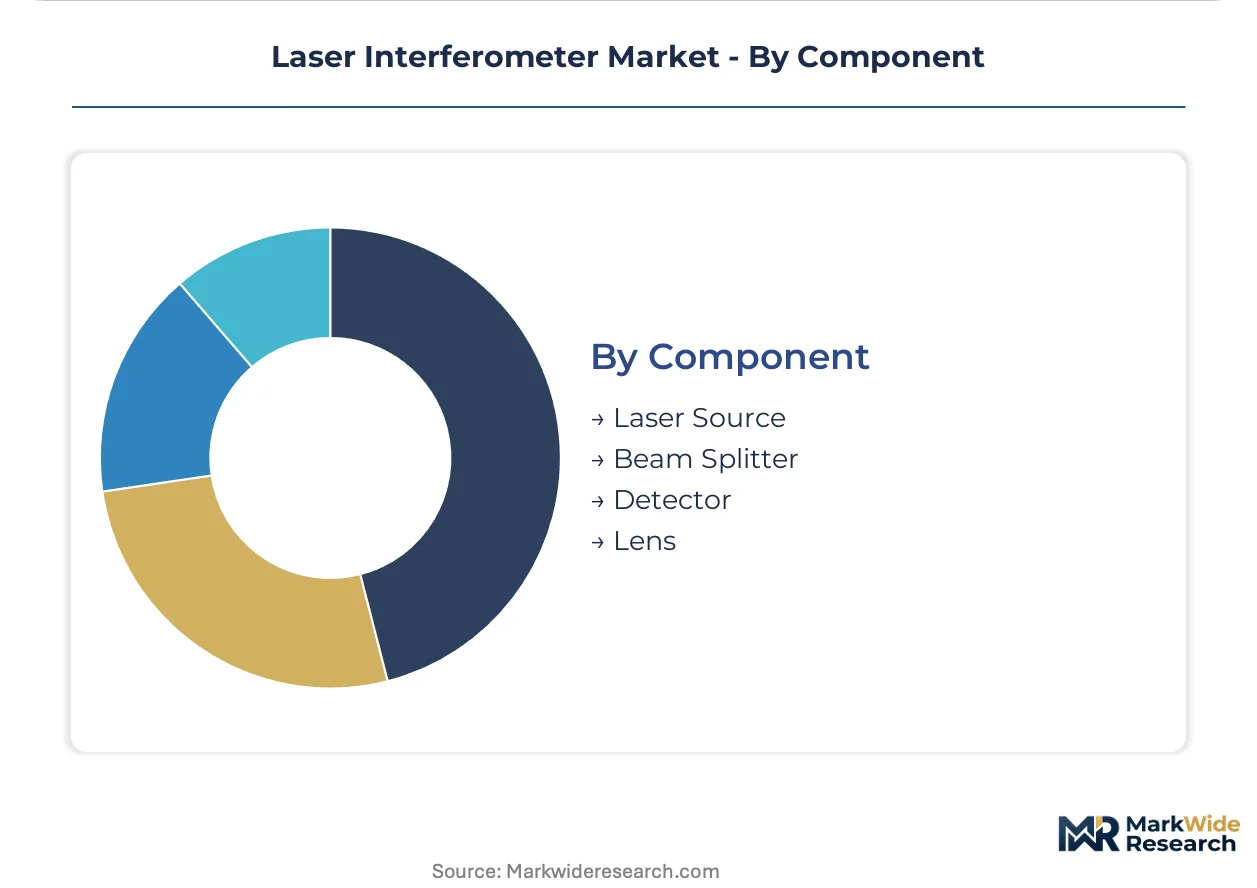
Component segmentation exposes supply vulnerabilities in specialized laser sources versus commoditized optical elements.
- Laser Source:Helium-neon tubes at 632.8 nanometers remain the metrology standard despite supply concentration in limited specialty gas corridors. Frequency-stabilized designs for precision applications carry premium pricing.
- Detector:CMOS and CCD arrays with high dynamic range capture interferometric fringe patterns for automated analysis. Machine-learning defect classification algorithms now process detector outputs in real time.
- Beam Splitter:Dielectric-coated cube and plate designs separate reference and measurement arms with polarization control. Anti-reflective coating reformulations respond to ECHA substance restrictions on fluorinated compounds.
- Lens:Collimating and imaging optics with λ/20 surface figure complete interferometer optical trains. Custom aspheric designs for Fabry-Pérot cavities require captive polishing capabilities.
Procurement value concentrates in Laser Source subsystems; Detector technology gains share fastest as computational imaging displaces human interpretation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian economies consume the majority of interferometer installations for semiconductor metrology, while European and North American facilities concentrate on calibration services and advanced research applications. Production of precision optical components clusters in Germany, Switzerland, and Japan, creating a geographic split between component supply and end-use demand.
United States
LIGO gravitational wave observatories in Washington and Louisiana anchor demand for Fabry-Pérot cavity systems, while FDA device-quality regulations shape calibration service bundling for medical optics manufacturers. Precision measurement laboratories in California and Massachusetts maintain NIST-traceable standards for semiconductor equipment suppliers.
Germany
Machine tool builders in Baden-Württemberg and Bavaria deploy Michelson interferometers to satisfy EU Machinery Directive traceability mandates. ECHA REACH restrictions on optical coating chemistries force reformulation of anti-reflective stacks at Zeiss and Leica facilities in Oberkochen and Wetzlar.
Japan
Fizeau interferometry dominates optical testing at lens manufacturers in Tokyo and Osaka prefectures, where METI industrial standards govern surface figure verification. Infrastructure monitoring projects in Kobe and Sendai integrate fiber-coupled sensors for seismic deformation tracking.
South Korea
Memory fabs in Gyeonggi Province unbundle hardware purchases from predictive analytics subscriptions, treating metrology as operational expenditure under MFDS quality frameworks. Samsung and SK Hynix procurement teams negotiate service-level agreements separately from EUV lithography equipment tenders.
Taiwan
TSMC foundry suppliers in Hsinchu Science Park expand metrology budgets to qualify EUV process chambers below 3nm nodes. Domestic fabrication equipment vendors source calibration protocols from Japanese and German optical houses while building captive interferometer capabilities.
Laser Interferometer Market Competitive Environment
Top-tier vendors anchor premium positioning in semiconductor fab installations, while mid-tier specialists compete on regional service proximity and application-specific customization. The vendor base stratifies across three archetypes: heritage metrology houses with encoder calibration legacies, captive optics manufacturers with polishing and coating integration, and test-and-measurement platforms extending software stacks into interferometric workflows. Consolidation pressure manifests through strategic partnerships between hardware OEMs and analytics providers, plus selective technology licensing for quantum sensing convergence.
Among heritage British metrology specialists, Renishaw plc occupies a position exemplifying premium-tier anchoring in fab installations. German precision optics conglomerates ZEISS Group and Mahr GmbH represent the captive-manufacturing archetype, leveraging in-house polishing capabilities to tighten specification control. California-based test-and-measurement platforms exemplified by Keysight Technologies sit within the software-extension tier, competing through data workflow integration rather than hardware ownership alone.
| Leading Market Players |
|---|
| Renishaw plc |
| Zygo Corporation |
| Keysight Technologies |
| SIOS Meßtechnik GmbH |
| ZEISS Group |
| Mahr GmbH |
| AMETEK, Inc. |
| Bruker Corporation |
| Optodyne, Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive polishing and coating capabilities at German and Swiss optical houses anchor supply positioning and pricing power for EUV mirror qualification tiers. This backward integration into precision optics manufacturing insulates premium vendors from helium-neon laser tube volatility while commanding certification-grade premiums.
Pricing Analysis
Margin tightening in standard-grade Michelson systems reflects helium-neon laser supply concentration and AFM substitution pressure. Three-tier pricing structure across NIST-traceable premium, ISO-certified standard, and uncertified economy levels separates fab qualification budgets from machine tool calibration spend. Semiconductor fabs in Taiwan and South Korea show lowest price sensitivity due to yield-loss exposure, while Indian PLI-scheme manufacturers negotiate aggressively on initial hardware.
Supply Chain Analysis
NIST-traceable calibration certificate requirements gate supplier qualification, concentrating laser source production in Germany, Japan, and the United States. Helium-neon tubes, frequency-stabilized cavities, and REACH-compliant anti-reflective coatings draw from specialty gas and precision coating corridors. Single-source vulnerability persists in 632.8nm laser tube manufacturing. Distribution runs through direct fab integration for semiconductor customers and regional calibration service networks for machine tool builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined interferometry with embedded machine-learning defect classification is displacing legacy hardware-centric procurement models. This technology transition compresses inspection cycle times and shifts vendor value toward analytics capabilities.
For Market Incumbents: Cement premium positioning in EUV lithography qualification chambers through captive polishing capabilities and NIST-traceable certificate bundling. Counter AFM substitution threat by accelerating predictive analytics subscription attach rates. Prioritize ISO 14253 uncertainty certification investment to defend fab qualification timelines.
For New Entrants and Emerging Players: Enter via quantum sensing convergence applications for gravitational wave detection infrastructure, where Fabry-Pérot cavity demand outpaces heritage vendor capacity. Target Indian PLI-scheme beneficiaries in Gujarat and Tamil Nadu with portable calibration systems priced for greenfield operational expenditure budgets. Lead with service-level agreement structures that unbundle hardware from analytics.
For Investors and Strategic Acquirers: Exit pathways concentrate in analytics-platform acquisitions by test-and-measurement conglomerates seeking interferometric data workflow integration. Long-term viability favors vendors with software subscription recurrence above hardware refresh dependence. Watch helium-neon laser supply disruption as inflection signal for frequency-stabilized solid-state substitution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Interferometry Platform Launch | Captures recurring revenue from predictive maintenance algorithms displacing perpetual licenses. |
| REACH-Compliant Coating Reformulation | Preserves European market access as ECHA restrictions eliminate legacy fluorinated compounds. |
| Fabry-Pérot Cavity Manufacturing Scale-Up | Addresses LIGO and Virgo infrastructure expansion in gravitational wave detection. |
| India PLI Scheme Distribution Partnership | Establishes early presence in Gujarat and Tamil Nadu semiconductor greenfield corridors. |
| Machine-Learning Defect Classification Acquisition | Accelerates automated fringe pattern interpretation for 100% incoming inspection stations. |
Study Parameters
SEC filings, ECHA substance evaluations, and ISO calibration standard documentation formed the secondary backbone, cross-referenced with primary interviews across metrology equipment procurement managers, precision optics manufacturing engineers, and semiconductor fab process qualification leads. Bottom-up installation data triangulated against top-down capital expenditure disclosures from TSMC, Samsung, and SK Hynix.
Historical trendline analysis across Michelson, Fabry-Pérot, Fizeau, and homodyne technology deployments established baseline penetration curves. The analytical framework modeled technology type, application workflow, end-user industry, and component subsystem dimensions over the projection horizon. CAGRs derived from weighted average of equipment replacement cycles, EUV node transition timelines, and subscription analytics adoption curves. Forecast inputs incorporated helium-neon laser supply constraints and REACH coating reformulation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EUV lithography node transition delays or quantum sensing infrastructure funding volatility. Model assumptions reflect documented procurement pattern shifts toward operational expenditure treatment of metrology services. A model refresh is warranted upon material change in EUV yield-loss economics or helium-neon supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Ultrasonic Testing Equipment Market
Test and Measurement
Backside Power Delivery Network (BPDN) Analysis Test Equipment Market
Test and Measurement
AI Accelerator Thermal Management and Hot Spot Mapping Test Platforms Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
One-Box Testers Market
Test and Measurement
APAC NDT Equipment Market
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Production Testing Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
Battery Resistance Tester Market
Test and Measurement
Bend Testing Machine Market
Test and Measurement
Slovakia and Czech Republic Calibration Services Market
Test and Measurement
Satellite Communications and Direct-to-Device RF Test Platforms Market
Test and Measurement
Glow Wire Test Apparatus Market