
 Curve Tracer Market | 2026-2036
Curve Tracer Market Size, Share, and Industry Trends Forecast 2026-2036
Curve Tracer Market Outlook
East Asian test equipment manufacturing is consolidating as regional producers scale automated fabrication lines for precision instruments. Keysight Technologies leverages vertical integration across measurement IP and software ecosystems to sustain premium positioning in semiconductor validation. Tektronix anchors North American supply through deep relationships with defense and aerospace qualification labs. Chroma ATE dominates Taiwan's foundry-adjacent test segment with localized service networks.
A curve tracer is an electronic test instrument that characterizes the current-voltage relationships of semiconductor devices, typically measuring parameters such as breakdown voltage, leakage current, and gain across multiple sweep ranges. Engineers deploy these instruments to verify transistor, diode, and thyristor performance against datasheets during design validation and failure analysis. Benchtop configurations lead the product type landscape due to their superior channel density and thermal management for high-power device characterization. Digital technology platforms represent the fastest-expanding segment as software-defined measurement and automated compliance scripting displace analog architectures in volume manufacturing environments.
FDA calibration traceability requirements for medical device component testing shape procurement specifications in North American healthcare electronics. IEC 61010 safety standards and ISO 17025 accreditation frameworks govern laboratory instrument deployment across European and Asian certification bodies. Semiconductor Testing applications face tightening MEE environmental compliance in China regarding hazardous substance documentation for exported equipment. Stakeholders must weigh regional certification divergence against platform standardization when configuring global test floor deployments.
Market Dynamics
Semiconductor complexity escalation is forcing test equipment buyers to consolidate procurement around platforms capable of multi-parameter automation, compressing vendor selection cycles and elevating software-defined architectures over discrete instrument purchasing.
Growth Catalysts
- Memory foundry expansion:South Korea's Samsung and SK Hynix fabs are scaling 3D NAND and HBM test capacity, pulling high-channel-density curve tracers into volume production lines for wafer-level characterization.
- IEC 61010-1 safety standard harmonization:European certification bodies are mandating reinforced isolation and touch-current limits, creating replacement demand for aging analog units in calibration laboratories.
- Silicon carbide qualification protocols:Power semiconductor manufacturers in China require extended voltage sweep ranges up to 3kV for EV traction inverter validation, expanding the addressable instrument specification envelope.
Market Restraints
- Precision analog component concentration:Specialized ADC and precision amplifier supply concentrates among Japanese and US semiconductor suppliers, exposing instrument manufacturers to 26-week lead time volatility.
- Capital intensity threshold:Automated test system integration requires $2-4 million floor commitments, excluding mid-tier contract manufacturers from in-house characterization capabilities.
- Substitution by parametric testers:Advantest and Teradyne systems with embedded source-measure units are capturing discrete device test slots previously served by dedicated curve tracers.
Strategic Opportunities
- India PLI scheme for semiconductors:The country's production-linked incentive framework for compound semiconductor fabs creates greenfield test equipment demand without incumbent vendor lock-in.
- Medical device component traceability:FDA 21 CFR Part 820 quality system regulations are extending calibration documentation requirements to implantable device supply chains, opening healthcare electronics as a new vertical.
- Cloud-native instrument control:Browser-based measurement software and API-first architectures are enabling remote diagnostics and subscription revenue models for distributed R&D teams.
Industry Challenges
- Metrology engineer scarcity:Specialized expertise in high-voltage safety design and RF isolation is concentrating among aging workforces in Germany and Japan, constraining product development velocity.
- Multi-standard certification complexity:Simultaneous IEC 61010, UL 61010-1, and GB 4793.1 compliance for a single platform extends time-to-market by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curve Tracer Market |
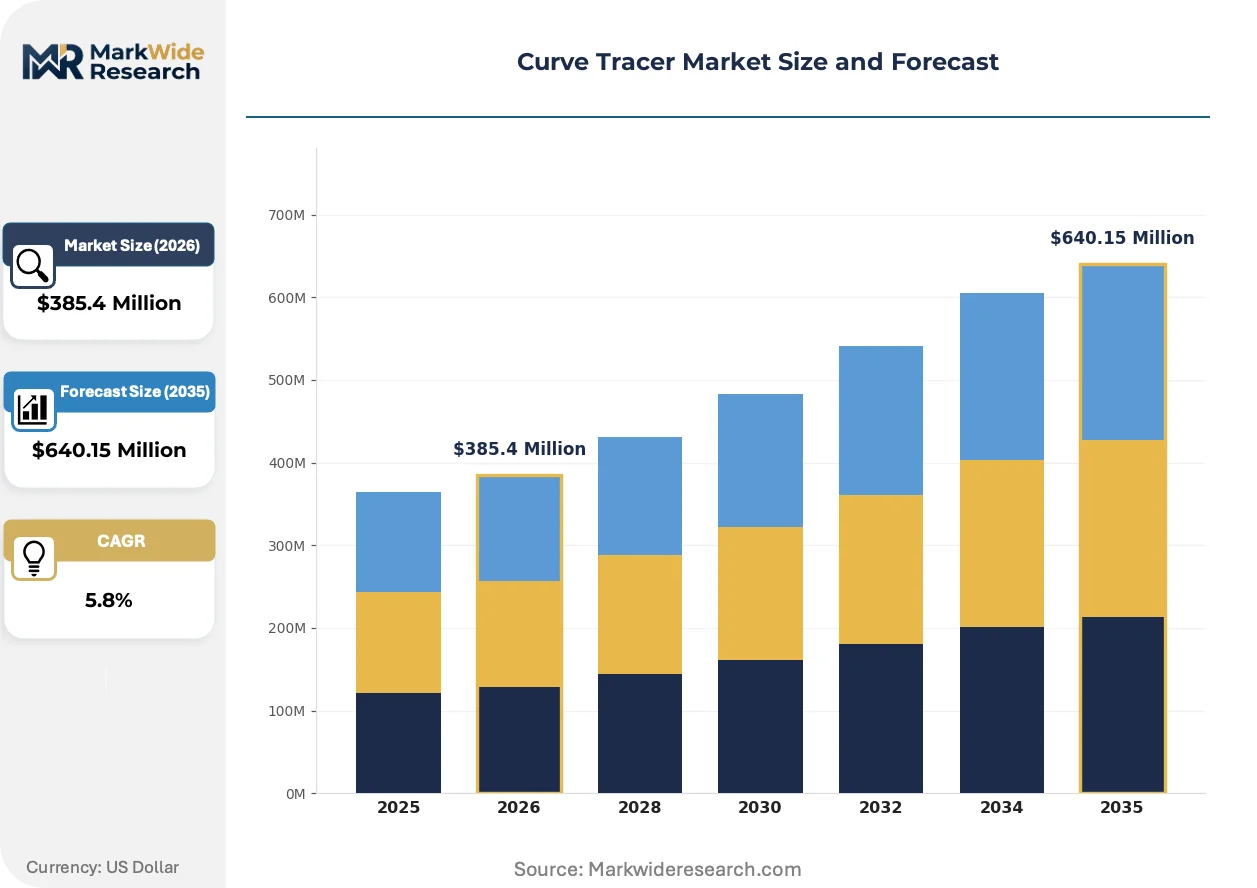
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Handheld, Portable, Integrated End User: Manufacturers, R&D Labs, Educational Institutions, Service Centers Technology: Analog, Digital, Hybrid, Wireless Application: Semiconductor Testing, Component Analysis, Circuit Design, Functional Testing |
| Companies Covered | Keysight Technologies, Tektronix, Chroma ATE, Fluke Corporation, Agilent Technologies, Keithley Instruments, Yokogawa Test & Measurement Corporation, Fortive Corporation, ABI Electronics Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curve Tracer Market Strategic Shifts
Software-defined measurement architectures are compressing hardware refresh cycles while regulatory documentation requirements are elevating data integrity features from optional to mandatory specifications.
Artificial intelligence-assisted test sequence optimization is automating parameter extraction for complex device models. Memory foundries in South Korea are deploying machine learning algorithms to predict failure modes from IV curve signatures, reducing characterization time per wafer by half. This compression is automating the transition from engineering validation to production screening without manual script development.
China's MEE hazardous substance documentation rules are tightening material disclosure requirements for exported test equipment. Manufacturers must now submit full substance declarations under GB/T 26572 for RoHS-equivalent compliance, adding supplier audit layers. Power semiconductor test platforms face the steepest compliance burden due to high-voltage insulation materials and leaded solder exemptions.
Buying committees are consolidating instrument procurement under centralized metrology groups rather than distributed engineering budgets. Defense and aerospace primes in the US are mandating enterprise-wide calibration management systems, displacing departmental purchasing autonomy. This concentration is most visible among FAA-certified repair stations seeking streamlined audit trails for traceability compliance.
Curve Tracer Market Segmentation
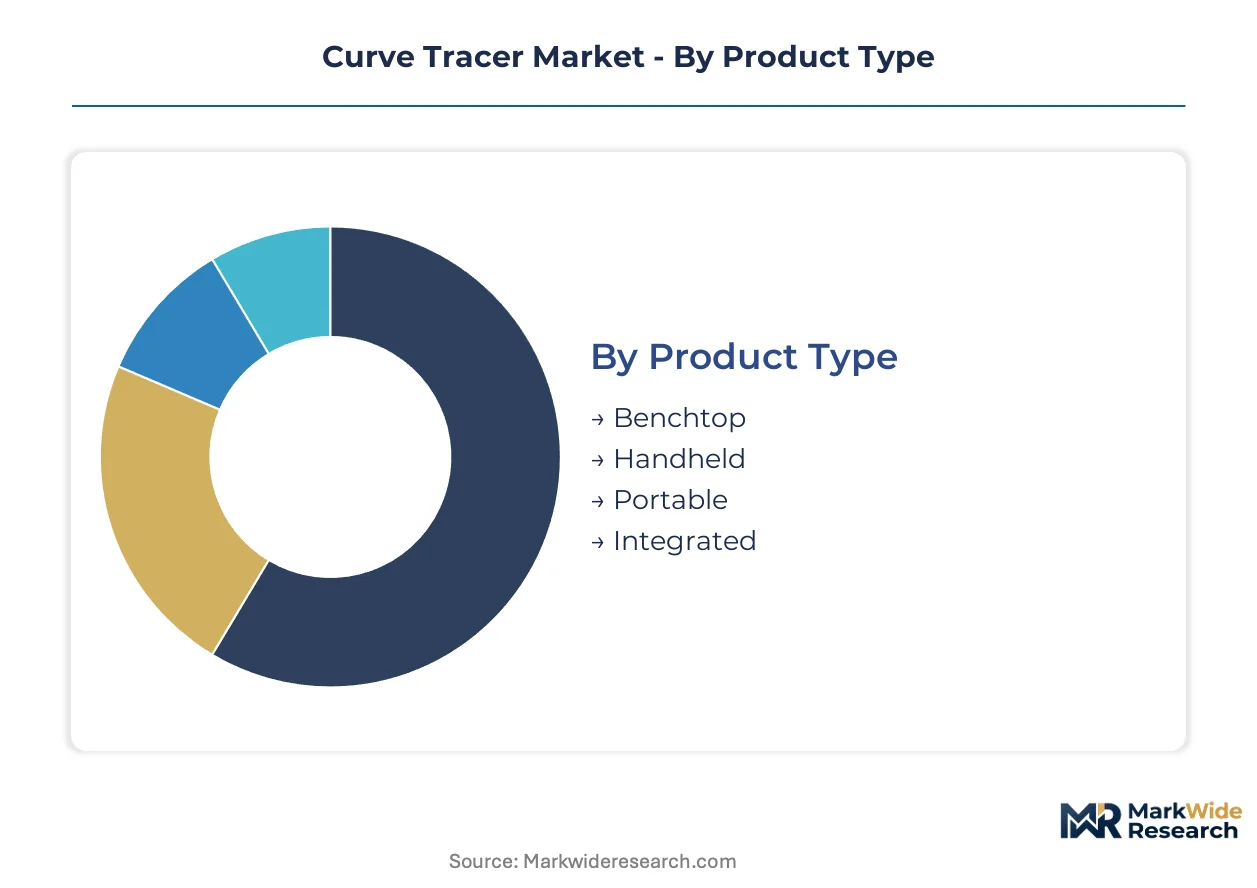
Curve tracer procurement patterns diverge sharply across deployment contexts, with semiconductor fabs prioritizing channel density while field service operations trade precision for portability. Understanding these segment boundaries clarifies why vendor portfolios span incompatible specification envelopes rather than converging on universal platforms.
Product Type:
Supply concentrates among Japanese and German precision instrument specialists for high-channel-density configurations, while portable variants draw from broader electronics manufacturing bases in Taiwan and South Korea.
- Benchtop:These systems integrate multiple source-measure units with thermal management for high-power device characterization up to 3kV. Demand clusters in South Korea's HBM foundries and China's silicon carbide qualification labs where wafer-level throughput dominates procurement specifications. Benchtop configurations absorb the bulk of installed capacity; Handheld is expanding most quickly.
- Handheld:Battery-operated units with simplified sweep ranges serve field diagnostics and repair depot workflows. South Korean memory manufacturers deploy these for rapid line-side verification during equipment maintenance windows.
- Portable:Transportable chassis with AC power requirements bridge laboratory precision and site mobility. Chinese power semiconductor engineers favor these for EV inverter validation at tier-one supplier facilities.
- Integrated:Embedded curve tracing modules within automated test handlers eliminate standalone instrument footprint. Japanese automotive electronics suppliers specify these for transistor lot screening in high-volume production.
Benchtop systems absorb the bulk of installed capacity; Handheld is expanding most quickly.
End User:
Cost tier stratification separates capital-intensive fab operators from budget-constrained academic and service segments, with procurement authority concentrating in centralized metrology groups among large manufacturers.
- Manufacturers:Semiconductor and power electronics producers operate the highest specification instruments with automated compliance scripting. Samsung and SK Hynix fabs in South Korea drive demand for multi-channel systems with machine learning-assisted failure prediction. Manufacturers absorb the bulk of installed capacity; R&D Labs are expanding most quickly.
- R&D Labs:Corporate engineering centers and national research institutes prioritize measurement flexibility over throughput. German automotive suppliers and Japanese materials science laboratories specify these for next-generation device characterization.
- Educational Institutions:University electrical engineering programs require durable, instructionally oriented units with simplified interfaces. Indian technical institutes under the PLI scheme for compound semiconductors represent emerging procurement volume.
- Service Centers:Independent calibration houses and OEM repair depots focus on traceability documentation and rapid turnaround. FAA-certified US repair stations mandate enterprise calibration management systems for these deployments.
Manufacturers absorb the bulk of installed capacity; R&D Labs are expanding most quickly.
Technology:
Volume deployment favors software-defined architectures that compress hardware refresh cycles, while legacy analog retains position in safety-critical calibration chains where traceability documentation spans decades.
- Digital:Software-defined measurement platforms with API-first control and automated compliance scripting displace analog architectures in volume manufacturing. South Korean memory foundries deploy these for IV curve signature analysis with machine learning integration. Digital platforms absorb the bulk of installed capacity; Hybrid is expanding most quickly.
- Analog:Discrete component architectures with manual sweep controls persist in European calibration laboratories requiring IEC 61010-1 safety standard harmonization. German metrology institutes specify these for primary reference standards.
- Hybrid:Combined analog signal conditioning with digital control interfaces bridges legacy workflows and modern automation. Chinese power semiconductor test houses adopt these for silicon carbide qualification protocols requiring extended voltage ranges.
- Wireless:Bluetooth and Wi-Fi enabled remote monitoring supports distributed R&D teams and cloud-native instrument control architectures. US defense primes evaluate these for secure facility deployments with centralized data aggregation.
Digital platforms absorb the bulk of installed capacity; Hybrid is expanding most quickly.
Application:
Application maturity separates established semiconductor testing workflows from emerging functional testing demands in automotive and medical electronics, with component analysis serving as the migration pathway between them.
- Semiconductor Testing:Wafer-level and packaged device characterization against datasheet parameters dominates foundry procurement. South Korean 3D NAND and HBM facilities specify high-channel-density systems for production screening. Semiconductor Testing absorbs the bulk of installed capacity; Functional Testing is expanding most quickly.
- Component Analysis:Discrete transistor, diode, and thyristor verification supports failure analysis and counterfeit detection workflows. Chinese EV traction inverter suppliers drive demand for extended voltage sweep capabilities.
- Circuit Design:Engineering validation of discrete devices within prototype assemblies requires flexible triggering and waveform capture. Japanese consumer electronics developers prioritize these for power management IC verification.
- Functional Testing:System-level verification of complete modules including curve-traced components emerges in automotive and medical electronics. FDA 21 CFR Part 820 traceability requirements shape procurement for implantable device supply chains.
Semiconductor Testing absorbs the bulk of installed capacity; Functional Testing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision analog component supply concentrates in Japanese and German manufacturing bases, while test equipment assembly clusters in South Korean and Chinese industrial zones.
South Korea
Samsung and SK Hynix fabs scale 3D NAND and HBM test capacity, pulling high-channel-density curve tracers into volume production lines. The country's national semiconductor regulator enforces strict calibration documentation for export-bound memory components. Seoul Capital Area hosts the densest concentration of foundry-adjacent test equipment procurement in East Asia.
China
Power semiconductor manufacturers require extended voltage sweep ranges up to 3kV for EV traction inverter validation. MEE hazardous substance documentation rules under GB/T 26572 tighten material disclosure requirements for exported test equipment. Yangtze River Delta industrial zones concentrate silicon carbide qualification labs and domestic instrument assembly operations.
United States
FAA-certified repair stations mandate enterprise-wide calibration management systems for traceability compliance in defense and aerospace applications. FDA 21 CFR Part 820 quality system regulations extend calibration documentation requirements to implantable device supply chains. Greater Boston and Pacific Northwest host dense clusters of metrology engineering expertise for high-voltage safety design.
Germany
Automotive suppliers prioritize measurement flexibility for next-generation device characterization in power electronics development. IEC 61010-1 safety standard harmonization mandates reinforced isolation and touch-current limits, creating replacement demand in calibration laboratories. Bavaria and Baden-Württemberg anchor European precision instrument manufacturing and primary reference standards deployment.
Japan
Specialized ADC and precision amplifier supply concentrates among domestic semiconductor suppliers, exposing instrument manufacturers to lead time volatility. METI industrial standards govern laboratory instrument deployment across certification bodies. Kanto and Kansai regions concentrate aging workforces with specialized expertise in high-voltage safety design and RF isolation.
Curve Tracer Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cloud-native instrument control and API-first architectures. The vendor base stratifies across three tiers: precision instrument specialists with captive analog component supply, software-defined measurement platforms with vertical integration into measurement IP, and regional fabricators with localized service networks. Consolidation pressure intensifies as procurement committees centralize under enterprise metrology groups. Dominant competitive moves include strategic partnerships for automated compliance scripting and geographic expansion into India's PLI scheme greenfield fabs.
Within the precision measurement tier, Keysight Technologies and Tektronix exemplify contrasting geographic anchoring strategies. Keysight occupies a position representing software-defined architectures with measurement IP integration. Tektronix sits within the North American defense-aerospace qualification ecosystem. Chroma ATE anchors the Taiwan-based foundry-adjacent segment with localized service network concentration.
| Leading Market Players |
|---|
| Keysight Technologies |
| Tektronix |
| Chroma ATE |
| Fluke Corporation |
| Agilent Technologies |
| Keithley Instruments |
| Yokogawa Test & Measurement Corporation |
| Fortive Corporation |
| ABI Electronics Ltd |
| Others |
Value Chain & Pricing Dynamics
Specialized ADC and precision amplifier procurement from Japanese and German semiconductor suppliers cascades through three distinct pricing tiers, with calibration-grade benchtop systems commanding premiums over field-service handheld units due to traceability documentation burdens.
Pricing Analysis
Extended warranty and calibration service bundling separate premium tier positioning from unbundled economy configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—ISO 17025-accredited systems for metrology laboratories versus production-floor units with simplified documentation. Cost compression in the economy tier is intensifying because Chinese power semiconductor manufacturers are qualifying domestic alternatives to established brands. Contract manufacturers and educational institutions exhibit the highest price sensitivity, while South Korean memory foundries prioritize channel density over unit cost.
Supply Chain Analysis
Ocean freight and air cargo volatility from East Asian industrial zones to European calibration laboratories shapes inventory positioning strategies among precision instrument distributors. Component supply concentrates in Japan, Germany, and the United States for high-precision analog semiconductors, with Taiwanese and South Korean facilities handling final assembly and test. Critical dependencies include specialized ADCs, precision amplifiers, and high-voltage isolation components. Single-source vulnerability for 26-week lead-time components exposes instrument manufacturers to allocation risk. Distribution runs through authorized metrology distributors with calibration service capabilities, bypassing general electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into precision analog semiconductor supply is reshaping competitive positioning, as vendors secure captive sourcing for ADC and amplifier components to compress lead times and defend margin structures.
For Market Incumbents: Extend software-defined measurement platform roadmaps to capture parametric tester substitution threats from Advantest and Teradyne. Invest in IEC 61010-1 safety certification harmonization to accelerate replacement cycles in European calibration laboratories. Deepen service network density in South Korea's Seoul Capital Area to defend against Chroma ATE's foundry-adjacent positioning.
For New Entrants and Emerging Players: Begin with cloud-native instrument control architectures targeting distributed R&D teams in US defense primes and German automotive suppliers. India's PLI scheme for compound semiconductors offers the most penetrable geography without incumbent vendor lock-in. API-first measurement software with subscription revenue models provides the strongest go-to-market angle against capital-intensive hardware incumbents.
For Investors and Strategic Acquirers: Consolidation of procurement authority under enterprise metrology groups is the leading indicator that software-defined platform vendors will capture disproportionate value versus discrete instrument specialists. Five-to-ten year viability favors vendors with measurement IP integration and automated compliance scripting capabilities. Acquisition target archetype: regional fabricators with localized service networks in underserved geographies. Watch for FDA 21 CFR Part 820 enforcement patterns in medical device supply chains as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captive ADC and amplifier supply insulates Keysight and Tektronix from Japanese semiconductor allocation volatility. |
| Cloud-Native Instrument Control Platform | Browser-based measurement software enables subscription revenue models for distributed R&D teams in defense primes. |
| Automated Compliance Scripting Development | Machine learning-assisted test sequence optimization reduces characterization time per wafer at Samsung and SK Hynix fabs. |
| Geographic Expansion into India PLI Scheme | Greenfield compound semiconductor fabs create test equipment demand without entrenched vendor relationships. |
| Enterprise Calibration Management System Partnership | FAA-certified repair stations mandate centralized traceability documentation, displacing departmental purchasing autonomy. |
Study Parameters
Trade publications, IEC and FDA regulatory filings, and semiconductor equipment customs records formed the secondary backbone, supplemented by primary interviews with metrology engineering directors, test floor managers at memory foundries, biomedical equipment procurement leads, and precision instrument distribution channel heads. Bottom-up segment sizing across product type, technology platform, and application dimensions was cross-validated against top-down equipment spending estimates from national semiconductor industry associations.
Historical trendline analysis of test equipment procurement patterns informed the projection framework, with growth rates derived from segment-specific adoption curves across the analysis window. Modeled dimensions include benchtop versus portable form factors, digital versus analog versus hybrid architectures, and semiconductor testing versus functional testing applications. Forecast inputs incorporated foundry capital expenditure plans, EV traction inverter qualification protocol expansions, and medical device traceability regulation enforcement trajectories.
Underlying measurement precision varies by segment; semiconductor testing and R&D lab deployments carry tighter precision than educational institution and service center estimates. Forecasts reflect documented assumptions regarding memory foundry expansion timelines, silicon carbide qualification protocol adoption, and multi-standard certification complexity resolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Electrical Testing Services Market
Test and Measurement
Flow Meter Market
Test and Measurement
Tensile Testers Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Fogging Tester Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Calibration Services Market
Test and Measurement
High-Throughput Liquid Handling Robot Performance Test Equipment Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
5G Testing Equipment Market
Test and Measurement
Data Acquisition Equipment Market