
 Tensile Testing Machine Market | 2026-2036
Tensile Testing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tensile Testing Machine Market Intelligence
Metrology technician shortages across North America and Western Europe is bifurcating the competitive landscape into high-automation and service-intensive camps. Instron leverages its vertical integration into load cell manufacturing to control component quality and delivery timelines. ZwickRoell sustains dominance in European aerospace certification through deep calibration service networks. MTS Systems Corporation anchors its position in servo hydraulic systems for high-load polymer and composite testing.
A tensile testing machine applies controlled axial tension to a specimen until failure, measuring ultimate tensile strength, yield point, and elongation through precision load cells and extensometers calibrated to ISO 7500-1 accuracy classes. These systems verify that metals, polymers, textiles, and composites meet design specifications before entering structural or consumer applications. Universal testing machines occupy the broadest installed base across manufacturing laboratories due to multi-mode versatility, while micro tensile testers represent the fastest-expanding category as semiconductor and biomedical device manufacturers demand sub-newton resolution for thin-film characterization. Digital electromechanical units are displacing legacy hydraulic configurations in quality assurance centers seeking cleaner operation and reduced maintenance overhead.
FDA device validation requirements and FAA material qualification protocols in the United States, alongside ECHA REACH substance testing mandates and CE marking conformity assessments in Europe, compel end users to document traceable calibration chains and software-locked test methods. ISO 6891 and ASTM E8 standards further tighten the specification envelope for equipment sold into cross-border certification agency workflows. Stakeholders must weigh capital deployment toward automated digital control architectures against the embedded base of hydraulic systems still prevalent in heavy metallurgy testing facilities.
Market Dynamics
Digital electromechanical architectures are displacing legacy hydraulic configurations across quality assurance laboratories, driven by ISO 6891 material verification protocols and aerospace composite characterization requirements in Germany and the United States. This structural shift compresses maintenance overhead while demanding recalibration of technician skill bases and capital deployment timelines.
Growth Catalysts
- ISO 6891 Protocol Adoption:Stricter material verification standards in European certification agencies are compelling laboratories to upgrade from manual to digital electromechanical units, creating replacement demand across installed bases.
- Aerospace Composite Expansion:Manufacturers in Germany and the United States are expanding quality assurance budgets for composite characterization equipment as next-generation airframe programs advance through qualification phases.
- China's State-Backed Modernization:Industrial testing corridors in China are witnessing facility upgrades as certification agencies modernize regional infrastructure under national quality infrastructure development programs.
Market Restraints
- Load Cell Supply Concentration:Precision sensor manufacturing concentrates among specialized German and Japanese suppliers, exposing equipment OEMs to extended lead times and input cost volatility.
- Hydraulic System Embedded Base:Heavy metallurgy testing facilities retain substantial investments in servo-hydraulic configurations, creating substitution friction and compressed replacement cycles for electromechanical alternatives.
- Metrology Technician Scarcity:North American and Western European labor markets face acute shortages of calibration-certified technicians, constraining service network expansion and field support capacity.
Strategic Opportunities
- Micro Tensile Testing White Space:Semiconductor and biomedical device manufacturers in Taiwan and South Korea are demanding sub-newton resolution systems for thin-film characterization, opening premium pricing tiers.
- FAA Material Qualification Alignment:United States-based testing laboratories serving defense and commercial aviation supply chains can capture recurring revenue through software-locked test method subscriptions tied to airworthiness certification.
- Remote Calibration Service Models:Cloud-connected load cell verification and AI-assisted diagnostic protocols are enabling geographic expansion of service coverage without proportional technician headcount growth.
Industry Challenges
- ISO 7500-1 Calibration Certification Pipeline:Laboratories face compressed timelines to maintain accuracy class compliance as audit frequencies intensify and documentation requirements expand.
- Legacy System Integration Complexity:Digital control architectures must interface with existing data management infrastructure in mature testing facilities, extending deployment cycles and technical validation phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tensile Testing Machine Market |
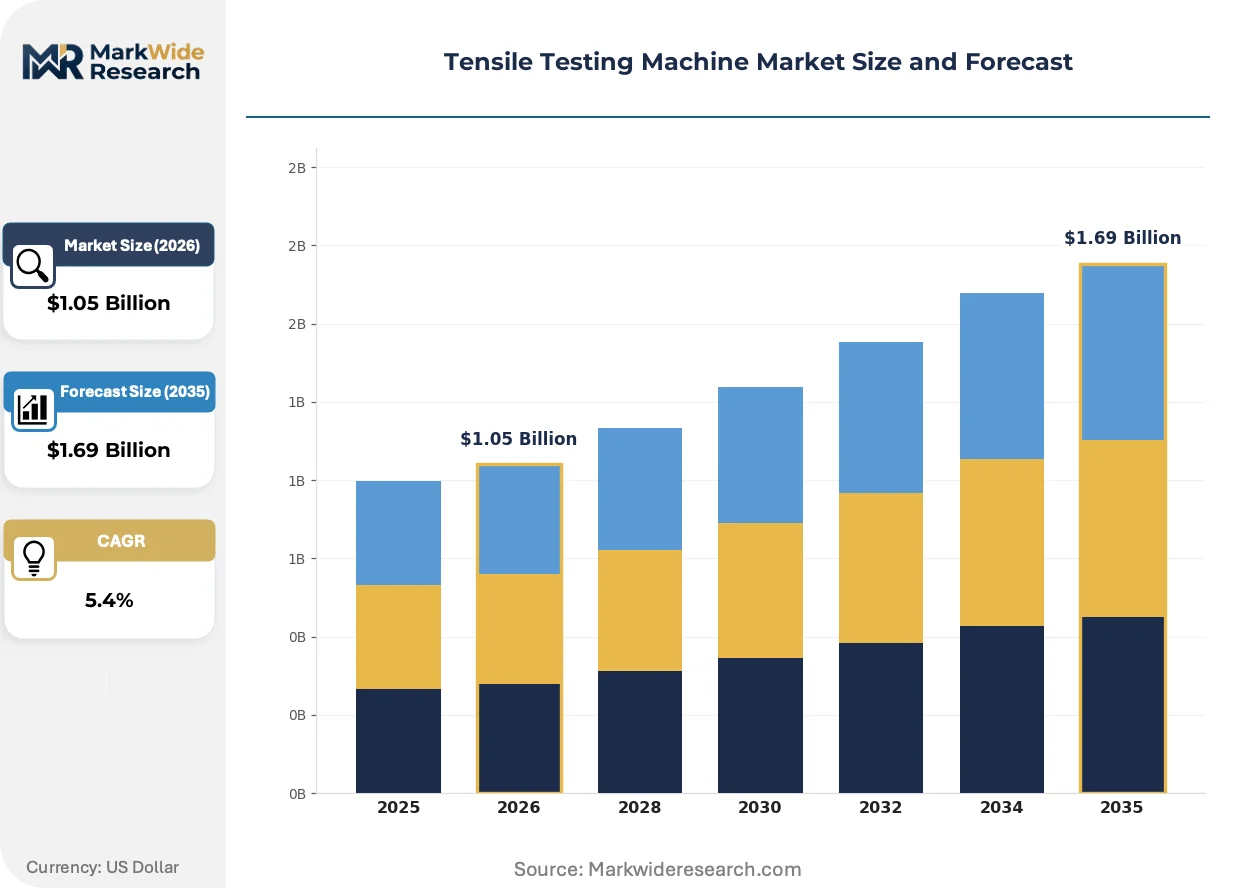
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Testing Machines, Servo Hydraulic Machines, Digital Electromechanical Units, Manual Testing Machines, Micro Tensile Testers Technology: Load Cell, Extensometer, Hydraulic System, Digital Control, Pneumatic System, Strain Gauge Application: Metallurgy Testing, Polymer Analysis, Textile Strength Testing, Composite Characterization, Aerospace Component Testing, Packaging Material Testing End User: Manufacturing Laboratories, Quality Assurance Centers, Academic Research Institutes, Material Testing Facilities, Certification Agencies |
| Companies Covered | Instron, ZwickRoell, Shimadzu Corporation, MTS Systems Corporation, Tinius Olsen, ADMET, Inc., Hegewald & Peschke, AMETEK, Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tensile Testing Machine Market Strategic Shifts & Innovations
Automation architectures and connected calibration protocols are restructuring competitive positioning across the tensile testing value chain. Equipment manufacturers are racing to embed predictive maintenance capabilities and remote diagnostic functions that alter ownership economics and service delivery models.
Cloud-native data acquisition software is decomposing traditional hardware-software bundling arrangements in universal testing machine configurations. Automotive and aerospace Tier-1 suppliers in Germany and Japan are adopting subscription-based analytics platforms that separate capital equipment from recurring software revenue streams. This decomposition compresses upfront procurement thresholds while elongating vendor-customer relationship lifecycles through embedded calibration and compliance modules.
REACH substance testing mandates from ECHA are tightening documentation requirements for polymer and composite characterization workflows in European manufacturing laboratories. The regulation's emphasis on traceable calibration chains is forcing equipment vendors to pre-certify software-locked test methods before shipment. Medical device and chemical processing end-uses in France and the Netherlands are experiencing the most acute compliance timeline pressures, accelerating replacement of open-architecture legacy systems.
Consolidated procurement functions at multinational manufacturers are unbundling after-sales service contracts from initial equipment purchases. Quality directors at United States-based medical device and automotive OEMs are negotiating separate calibration service agreements with third-party metrology providers, bypassing incumbent equipment vendors. This pattern concentrates in FDA-regulated device manufacturing clusters around Boston and Minneapolis, where validation documentation requirements favor specialized calibration houses over generalist service arms.
Tensile Testing Machine Market Segmentation
Tensile testing machine segmentation reflects divergent technical requirements across industrial certification workflows. Equipment specifications vary sharply between heavy metallurgy facilities and semiconductor cleanrooms, with calibration protocols and load resolution demands driving purchasing decisions.
Product Type:
Domestic production concentrates in Germany, the United States, and Japan, while export demand flows toward China's industrial testing corridors and Taiwan's semiconductor manufacturing clusters.
- Universal Testing Machines:Multi-mode configurations accommodate tension, compression, and flexure testing through interchangeable grips and fixtures. Manufacturing laboratories in Germany and the United States deploy these systems for batch qualification across metals, polymers, and composites under ISO 7500-1 accuracy protocols. Aerospace Tier-1 suppliers favor modular architectures that reduce capital redundancy.
- Digital Electromechanical Units:Brushless servo motors and precision ball screws deliver cleaner operation than hydraulic alternatives, with reduced maintenance overhead and quieter laboratory environments. Quality assurance centers in France and the Netherlands are displacing legacy systems to meet ECHA REACH documentation requirements for traceable calibration chains.
- Servo Hydraulic Machines:High-force configurations dominate heavy metallurgy and construction material testing where loads exceed 600 kN.
- Manual Testing Machines:Entry-level units persist in educational settings and developing-market certification agencies with constrained capital budgets.
- Micro Tensile Testers:Sub-newton resolution systems serve semiconductor wafer and biomedical thin-film characterization in Taiwan and South Korea.
Universal testing machines hold the largest share; momentum sits with micro tensile testers.
Technology:
Cost tiers separate premium precision components from commodity sensing elements, with calibration-certified load cells commanding three-to-five-year replacement cycles against disposable strain gauge alternatives.
- Load Cell:Strain-gauge-based force transducers convert mechanical deformation into electrical signals with ISO 7500-1 Class 0.5 to Class 1 accuracy ratings. German and Japanese suppliers concentrate precision manufacturing, exposing equipment OEMs to extended lead times and input cost volatility.
- Extensometer:Contact and non-contact displacement sensors measure specimen elongation with resolution down to 0.1 micrometers. Aerospace composite characterization workflows in the United States demand video extensometry for non-destructive strain mapping of anisotropic materials.
- Digital Control:Real-time feedback loops and adaptive PID tuning enable automated test execution with software-locked method compliance.
- Hydraulic System:Piston-and-cylinder architectures retain installed base in high-force metallurgy applications.
- Pneumatic System:Compressed-air actuation serves textile and packaging testing where rapid cycling and clean operation outweigh force requirements.
- Strain Gauge:Foil and semiconductor gauges provide cost-effective force measurement in entry-level and portable configurations.
Load cell technology dominates revenue; digital control architectures are climbing the fastest.
Application:
Volume concentration tracks manufacturing output geography, with metallurgy and polymer analysis anchored to industrial corridors while aerospace testing clusters around certification hubs.
- Metallurgy Testing:Tensile, yield, and elongation characterization of ferrous and non-ferrous alloys per ASTM E8 and ISO 6891 protocols. Steel mills and aluminum processors in Germany and China maintain high-throughput quality assurance lines with automated specimen handling.
- Composite Characterization:Anisotropic material testing for carbon fiber reinforced polymers in airframe and wind turbine blade applications. Boeing and Airbus qualification programs in the United States and France are expanding quality assurance budgets for through-thickness and interlaminar shear characterization.
- Aerospace Component Testing:FAA and EASA material qualification workflows demand software-locked test methods with audit trail documentation.
- Polymer Analysis:Stress-strain behavior of thermoplastics and elastomers for automotive and consumer goods.
- Textile Strength Testing:Fabric tear and tensile resistance for apparel and industrial belting.
- Packaging Material Testing:Seal integrity and burst resistance for food and pharmaceutical containers.
Metallurgy testing holds the largest share; composite characterization shows the steepest expansion trajectory.
End User:
Customer type determines procurement authority and service contract structure, with multinational manufacturers unbundling calibration agreements from equipment purchases.
- Quality Assurance Centers:Dedicated facilities within automotive, aerospace, and medical device OEMs execute batch qualification and supplier audit testing. FDA-regulated device manufacturers around Boston and Minneapolis favor specialized calibration houses over generalist vendor service arms for validation documentation.
- Certification Agencies:State-backed and third-party conformity assessment bodies perform regulatory compliance testing for CE marking and export certification. China's national quality infrastructure programs are modernizing regional facilities in industrial testing corridors.
- Manufacturing Laboratories:In-house R&D and production support testing within material processors and component fabricators.
- Academic Research Institutes:University materials science departments and national laboratories pursuing fundamental deformation mechanism studies.
- Material Testing Facilities:Independent commercial laboratories serving construction, infrastructure, and legal dispute resolution markets.
Quality assurance centers hold the largest share; certification agencies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA material qualification protocols in the United States anchor the most stringent certification workflows worldwide, driving equipment specifications that propagate across aerospace supply chains. ISO 6891 adoption in European certification agencies creates parallel upgrade cycles. State-backed modernization programs in China concentrate procurement authority in industrial testing corridors.
United States
Boeing and defense contractors in Seattle and St. Louis expand composite characterization capacity for next-generation airframe programs. FAA protocols demand software-locked test methods with audit trail documentation. Boston and Minneapolis medical device clusters favor specialized calibration houses over generalist vendor service arms for FDA validation requirements.
Germany
Airbus qualification programs in Hamburg and Munich drive through-thickness and interlaminar shear testing demand. ECHA REACH substance testing mandates tighten documentation requirements for polymer characterization workflows. Stuttgart and Munich automotive Tier-1 suppliers adopt subscription-based analytics platforms that separate capital equipment from recurring software revenue.
China
Steel mills and aluminum processors in Hebei and Shandong provinces maintain high-throughput quality assurance lines with automated specimen handling. SAMR national quality infrastructure programs modernize regional certification facilities. Yangtze River Delta industrial testing corridors witness facility upgrades as state-backed agencies consolidate procurement authority.
Japan
Automotive and electronics manufacturers in Aichi and Kanagawa prefectures deploy multi-mode universal testing machines for batch qualification across metals and polymers. METI industrial standards enforcement drives ISO 7500-1 accuracy class compliance. Nagoya and Osaka precision equipment clusters source load cells from domestic suppliers to mitigate lead time exposure.
South Korea
Samsung and SK Hynix semiconductor fabrication in Gyeonggi Province demands sub-newton resolution micro tensile testers for thin-film characterization. MFDS medical device validation requirements align with FDA-equivalent documentation standards. Seoul Capital Area biomedical device manufacturers represent the fastest-expanding premium equipment category.
Tensile Testing Machine Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the tensile testing machine market. Premium-tier vendors concentrate in Germany, the United States, and Japan, where calibration service networks and vertical integration into precision component manufacturing defend margin positions. Mid-tier fabricators in China and Taiwan compete on capital equipment pricing while third-party metrology providers unbundle calibration services. Strategic moves center on backward integration into load cell manufacturing and cloud-native software architectures that enable subscription revenue models.
Within the precision instrumentation tier, Instron and ZwickRoell exemplify divergent geographic anchoring strategies. Instron represents North American vertical integration archetypes with in-house load cell production capabilities. ZwickRoell occupies the European calibration service density position. Shimadzu Corporation anchors Japanese precision manufacturing heritage in electromechanical architectures. These three entities collectively illustrate how regional regulatory alignment—FAA protocols, ECHA REACH mandates, and METI standards enforcement—shapes competitive positioning without requiring identical capability profiles.
| Leading Market Players |
|---|
| Instron |
| ZwickRoell |
| Shimadzu Corporation |
| MTS Systems Corporation |
| Tinius Olsen |
| ADMET, Inc. |
| Hegewald & Peschke |
| AMETEK |
| Illinois Tool Works Inc. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at precision load cell foundries in Germany and Japan shapes both supply concentration and price floors for tensile testing equipment. Scale economies in strain-gauge manufacturing compress per-unit sensor costs while ISO 7500-1 calibration certification requirements sustain premium pricing tiers for aerospace-qualified configurations.
Pricing Analysis
German-manufactured electromechanical units command 40-60% premiums over Chinese alternatives in European certification agency procurement. Pricing stratifies across premium, standard, and economy tiers based on ISO accuracy class and software-locked method compliance. Cost compression in mid-tier configurations is intensifying as domestic Chinese OEMs achieve Class 0.5 calibration equivalence. Academic research institutes exhibit highest price sensitivity, while FAA-regulated aerospace laboratories demonstrate lowest sensitivity due to audit documentation requirements.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes extend inbound logistics timelines for precision ball screw assemblies sourced from Japanese suppliers. Manufacturing concentration in Germany, the United States, and Japan draws from specialized German and Japanese load cell producers, exposing equipment OEMs to single-source vulnerability in strain-gauge substrates. Distribution runs through direct sales forces for premium-tier aerospace applications and third-party metrology distributors for standard industrial configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital electromechanical displacement of legacy hydraulic systems constitutes a high-growth disruption, with ISO 6891 protocol adoption serving as the regulatory inflection compressing replacement cycles across installed bases.
For Market Incumbents: Secure backward integration into load cell manufacturing to mitigate lead time exposure from German and Japanese sensor suppliers. Anchor service network density in FAA-regulated aerospace clusters to defend against third-party metrology providers unbundling calibration contracts from equipment purchases.
For New Entrants and Emerging Players: CE marking fast-track certification for polymer characterization workflows opens immediate access to ECHA REACH-mandated laboratory upgrades in France and the Netherlands. Target China's state-backed industrial testing corridors through partnerships with SAMR regional certification agencies. Lead with cloud-native software architectures that separate recurring analytics revenue from capital equipment transactions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment vendors with embedded calibration service subscriptions and software-locked test method platforms. Long-term viability favors acquisition targets combining precision manufacturing heritage with cloud-connected diagnostic capabilities. Watch for inflection in remote calibration service adoption rates as an indicator of technician scarcity mitigation and geographic expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Load Cell Manufacturing | Captive supply of precision sensors insulates Instron and ZwickRoell from Japanese supplier lead time volatility. |
| Cloud-Native Software Platform Launch | Subscription-based analytics platforms separate capital equipment from recurring revenue streams at Stuttgart automotive Tier-1 suppliers. |
| Remote Calibration Service Expansion | AI-assisted diagnostic protocols enable geographic coverage expansion without proportional technician headcount growth in North America. |
| Micro Tensile Tester Product Line Extension | Sub-newton resolution systems capture premium pricing tiers from Samsung and SK Hynix semiconductor fabrication in Gyeonggi Province. |
| FAA Material Qualification Alignment | Software-locked test method subscriptions generate recurring revenue from Boeing and defense contractor qualification programs. |
Research Approach
Cross-validation between primary interviews with quality assurance directors and secondary validation through ISO calibration certification databases anchors the qualitative findings. Conversations with metrology technicians, aftermarket service heads at equipment OEMs, procurement managers at aerospace Tier-1 suppliers, and laboratory directors at FDA-regulated medical device manufacturers combined with customs trade data, SEC equipment manufacturer filings, SAMR infrastructure program disclosures, and ASTM/ISO standards documentation. Bottom-up equipment shipment analysis and top-down end-use industry demand estimation provided triangulation across the analysis window.
Sensitivity analysis around load cell supply disruption scenarios and ISO protocol adoption timelines shaped the analytical framework. Segmentation dimensions modeled include product type, technology architecture, application workflow, and end-user procurement authority across the projection horizon. CAGRs derived from equipment replacement cycle analysis and certification agency modernization budget trajectories incorporated semiconductor fabrication capacity expansion and aerospace composite airframe program advancement as industry-specific demand drivers.
Underlying assumptions cover sustained ISO 6891 enforcement intensity and stable precision sensor supply from established German and Japanese manufacturers, with deviation risk concentrated in metrology technician availability constraints and trade policy disruptions affecting load cell component flows. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Gauss Meter Market
Test and Measurement
Leak Testing Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
Sand Abrasion Tester Market
Test and Measurement
In-Process Composite Layup Monitoring Sensors and Test Equipment Market
Test and Measurement
Ultrasonic Wall Thickness Gauges Market
Test and Measurement
Coaxial Profile Projectors Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market
Test and Measurement
Hardware-Assisted Verification Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Signal Generator Market
Test and Measurement
5G Testing Devices Market