
 High-Throughput Liquid Handling Robot Performance Test Equipment Market | 2026-2036
High-Throughput Liquid Handling Robot Performance Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
High-Throughput Liquid Handling Robot Performance Test Equipment Market Insights
Multi-source procurement for precision test modules is shifting toward vertically integrated supply arrangements among top-tier vendors. Thermo Fisher Scientific leverages its captive manufacturing of calibration substrates to control lead times for drug-discovery clients. Agilent Technologies anchors its position through deep R&D spending on throughput analyzer architectures. Danaher competes by extending its life-sciences diagnostics footprint into adjacent test-equipment categories.
High-throughput liquid handling robot performance test equipment comprises instrumented systems that measure positional accuracy, dispense repeatability, and contamination rates across nanoliter-to-milliliter volumes, primarily serving automated laboratory workflows in pharmaceutical and genomic research. Throughput analyzers lead equipment-type revenue due to their role in validating speed claims for multi-channel pipetting stations, while flow meters capture fastest-growing interest as bioprocessing scales demand real-time volumetric verification. Drug discovery applications command the largest application share, though diagnostics development segments attract widening equipment procurement as regulatory filing requirements stiffen.
FDA 21 CFR Part 11 and ISO 8655 standards shape equipment design by mandating traceable calibration records and gravimetric verification protocols, directly influencing vendor R&D priorities. EPA Good Laboratory Practice guidelines and EU REACH chemical-handling rules further constrain material choices for fluid-contact components, raising compliance costs for non-conforming suppliers. Stakeholders must weigh regulatory trajectory against equipment refresh cycles when committing capital to test-platform standardization.
Market Dynamics
Pharmaceutical manufacturers are consolidating validation workflows under single-vendor platforms to compress regulatory audit cycles and eliminate inter-equipment calibration drift. This buyer-side consolidation is compressing vendor margins while rewarding integrated solution providers with multi-year service contracts.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates force automated audit trails for liquid handling validation, expanding replacement demand for legacy manual test stations across US drug development facilities.
- Cell and gene therapy manufacturing:Precision dosing requirements in viral vector production pull gravimetric verification systems into bioprocessing suites previously served by manual pipette checks.
- Boston-San Francisco biotech corridor:Venture-funded discovery labs cluster procurement of throughput analyzers to accelerate IND filing timelines and secure follow-on financing rounds.
Market Restraints
- Precision component supply concentration:German and Swiss load-cell manufacturers control 70% of gravimetric sensor supply, exposing lead times to single-source disruption risks.
- Platinum-group metal volatility:Flow meter electrodes incorporate iridium and rhodium, tying production costs to London Metal Exchange price swings without pass-through pricing power.
- ISO 8655 gravimetric protocols:Mandatory 10-fold measurement repetition for nanoliter verification extends test cycle times, capping effective equipment utilization rates.
Strategic Opportunities
- India contract research expansion:CDSCO-aligned bioequivalence labs in Hyderabad and Bengaluru underinvest in automated validation, creating first-mover advantage for localized test equipment distribution.
- AI-driven predictive calibration:Machine learning models trained on dispense history data enable shift-from-scheduled to condition-based maintenance, differentiating service revenue streams.
- EU MDR in-vitro diagnostic requirements:Strengthened design-control documentation for companion diagnostics forces IVD manufacturers to upgrade from paper-based to instrumented liquid handling verification.
Industry Challenges
- Metrology technician scarcity:Gravimetric analysis requires ASQ-certified calibration specialists, with US community college programs graduating fewer than 200 qualified technicians annually against expanding demand.
- Multi-vendor integration complexity:Test equipment from disparate suppliers generates incompatible data formats, forcing buyers to fund custom LIMS middleware development for unified audit reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Throughput Liquid Handling Robot Performance Test Equipment Market |
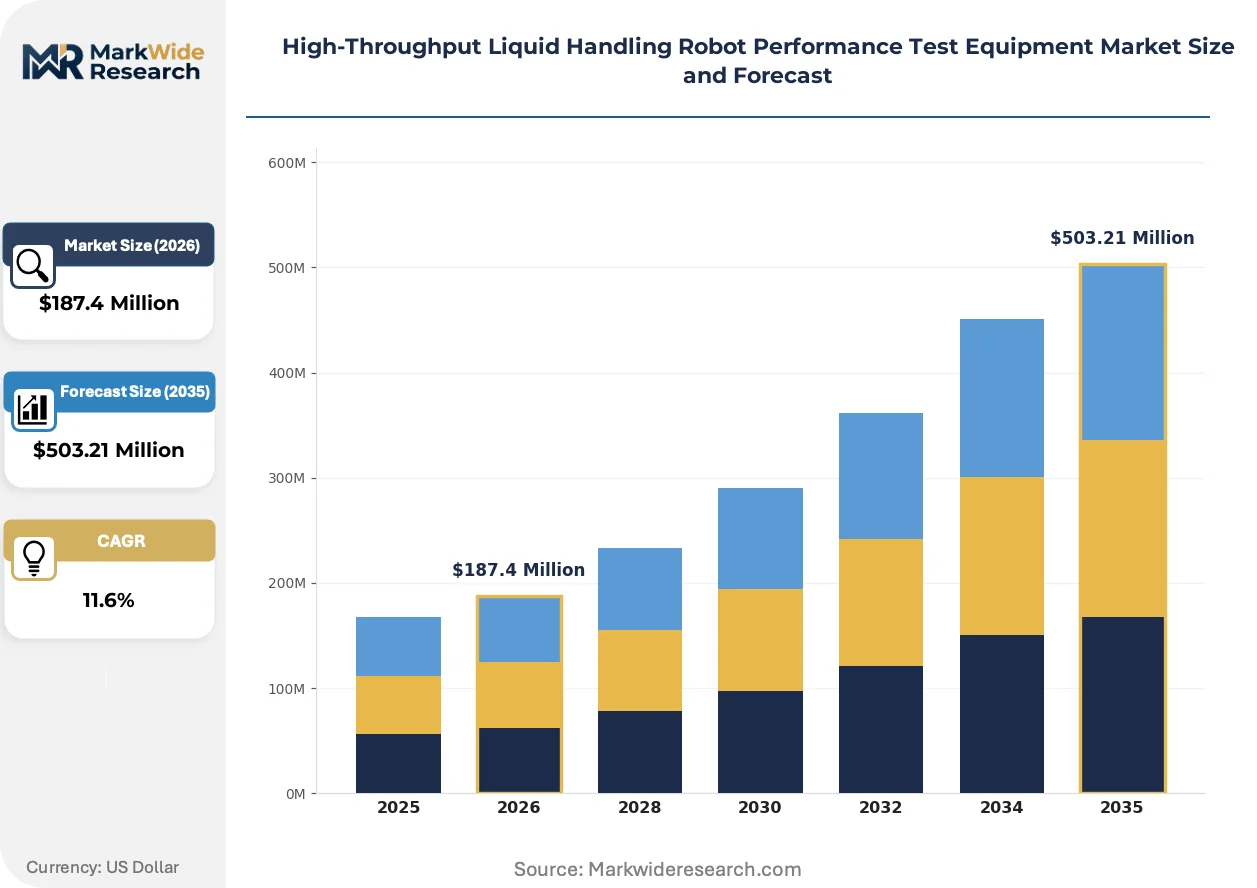
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Calibration Systems, Throughput Analyzers, Precision Balancers, Flow Meters, Viscosity Sensors Performance Metric: Accuracy, Speed, Repeatability, Liquid Volume Range, Contamination Control Application: Drug Discovery, Genomics Research, Proteomics Studies, Diagnostics Development, Bioprocessing End User: Contract Research Organizations, Biotechnology Firms, Pharmaceutical Manufacturers, Academic Laboratories, Clinical Testing Facilities |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Danaher, Tecan Trading AG, Hamilton Company, Eppendorf, PerkinElmer, QIAGEN, METTLER TOLEDO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Throughput Liquid Handling Robot Performance Test Equipment Market Trends and Innovations
Test equipment architectures are absorbing embedded intelligence to shift validation from episodic bench testing to continuous in-line monitoring, collapsing the feedback loop between dispense execution and quality documentation.
Capacitive droplet sensors are absorbing real-time volume verification duties previously assigned to offline gravimetric stations. Gene therapy CDMOs in Maryland and North Carolina deploy these sensors to catch nanoliter dispense deviations within 50 milliseconds, triggering automatic well rejection before plate completion. This capability is absorbing capital allocation away from standalone analyzers toward integrated sensor-robot platforms.
REACH Annex XVII restrictions on perfluorinated compounds are forcing fluid-contact material substitutions in test equipment manifolds. European vendors reformulate pump diaphragms and valve seals using hydrogenated nitrile rubber to maintain chemical compatibility without SVHC classification. German analytical instrument manufacturers absorb compliance costs through captive polymer compounding facilities.
Service unbundling is fragmenting traditional capital-sale models. Pharmaceutical procurement teams in Massachusetts negotiate calibration-as-a-subscription contracts covering multi-site equipment fleets, transferring metrology labor liability to vendors. This purchasing pattern concentrates in mid-cap biotechs lacking internal quality infrastructure, with subscription penetration highest among Series C-funded companies preparing for FDA pre-approval inspections.
High-Throughput Liquid Handling Robot Performance Test Equipment Market Segmentation
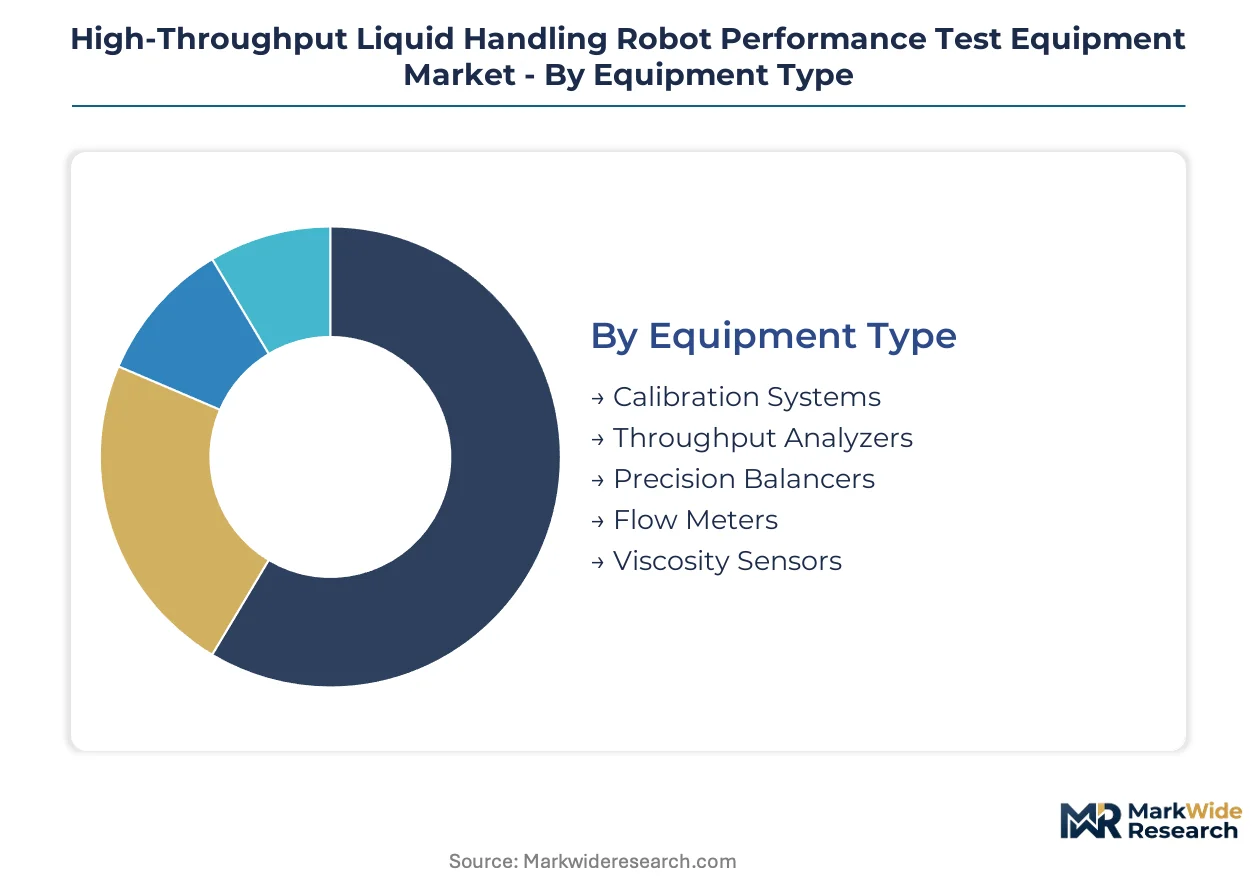
Equipment specifications diverge sharply across liquid handling test workflows, with capital commitments ranging from benchtop calibration units to integrated multi-parameter validation suites. Procurement patterns cluster around regulatory filing timelines, forcing vendors to align segment portfolios with specific compliance checkpoints rather than generic laboratory needs.
Equipment Type:
Capital intensity peaks in integrated throughput analyzer platforms, where multi-channel validation architectures command premium pricing against modular single-function alternatives.
- Throughput Analyzers:These systems integrate multi-channel pipetting validation with real-time data capture for IND submission packages. Massachusetts and North Carolina gene therapy CDMOs deploy these analyzers to compress pre-approval inspection timelines, with procurement concentrated among Series C-funded biotechs preparing for FDA engagement.
- Flow Meters:Real-time volumetric verification devices utilizing iridium-plated electrodes for nanoliter precision. Steepest expansion trajectory occurs in Maryland viral vector manufacturing suites, where continuous bioprocessing scale-up demands inline gravimetric alternatives to offline bench testing.
- Calibration Systems:Gravimetric reference stations traceable to NIST standards for audit trail documentation.
- Precision Balancers:Sub-milligram resolution load-cell arrays for dispense weight verification in high-value reagent workflows.
- Viscosity Sensors:Shear-rate adaptive probes for non-Newtonian fluid characterization in cell therapy formulations.
Most installed capacity flows through Throughput Analyzers. Expansion is steepest in Flow Meters.
Performance Metric:
Testing protocol design prioritizes speed verification for high-throughput screening environments, while accuracy dominates cell therapy dosing applications where therapeutic index margins narrow.
- Accuracy:Positional deviation measurement against ISO 8655 gravimetric protocols, requiring 10-fold repetition cycles. German load-cell supply concentration creates lead time vulnerability for US pharmaceutical manufacturers seeking traceable calibration chains.
- Contamination Control:Cross-well carryover detection through fluorescent tracer methods. Boston-area discovery labs prioritize this metric for CRISPR library screening, where single contaminated wells corrupt entire plate statistical power.
- Speed:Cycle-time validation for multi-channel parallel dispensing operations.
- Repeatability:Coefficient of variation tracking across extended run durations.
- Liquid Volume Range:Dynamic range verification from nanoliter to milliliter setpoints.
Accuracy claims dominate current procurement specifications. Contamination Control is gaining specification weight fastest in cell therapy segments.
Application:
Application mix reflects regulatory filing intensity, with drug discovery absorbing validation capacity during IND preparation and diagnostics development accelerating through EU MDR implementation.
- Drug Discovery:High-throughput screening validation for compound library management and hit-to-lead progression. San Francisco venture-funded labs cluster procurement to secure follow-on financing, with equipment deployment tied to milestone-based funding triggers.
- Diagnostics Development:Companion diagnostic liquid handling verification under strengthened EU MDR design-control documentation. IVD manufacturers upgrade from paper-based to instrumented validation to satisfy notified body scrutiny of analytical performance claims.
- Genomics Research:Next-generation sequencing library preparation accuracy testing.
- Proteomics Studies:Mass spectrometry sample handling repeatability verification.
- Bioprocessing:Viral vector and cell therapy manufacturing dose consistency validation.
Drug Discovery retains the largest installed base. Diagnostics Development is expanding specification requirements most rapidly.
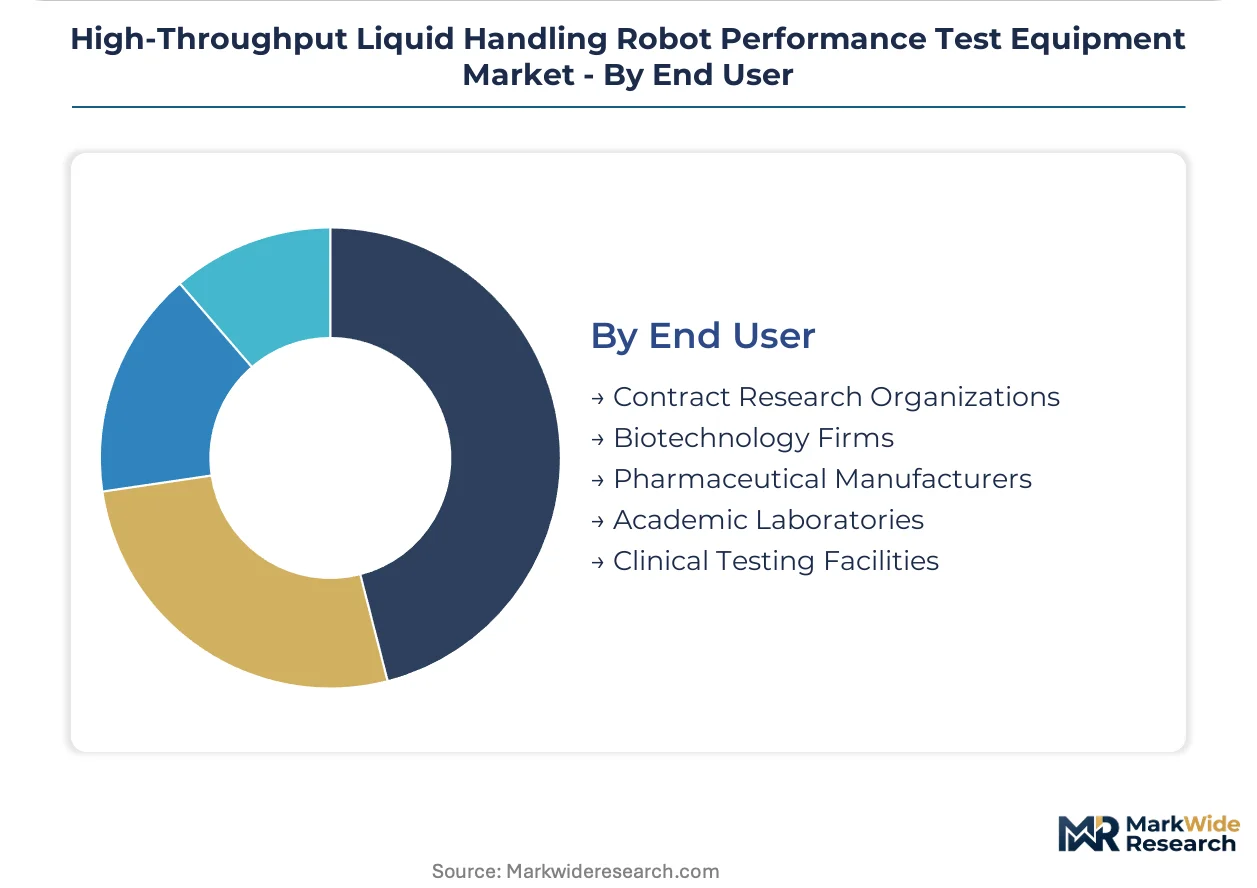
End User:
End-user economics stratify around in-house metrology capability, with pharmaceutical manufacturers absorbing capital costs directly while contract research organizations negotiate service-inclusive pricing.
- Pharmaceutical Manufacturers:Integrated validation platform deployment across multi-site quality networks. These buyers consolidate vendor relationships to compress regulatory audit cycles, favoring single-source calibration service contracts over equipment-only procurement.
- Contract Research Organizations:Equipment procurement aligned with sponsor audit requirements and CDSCO bioequivalence lab expansion in Hyderabad and Bengaluru. Indian CROs underinvest in automated validation relative to US and European counterparts, creating distribution opportunity for localized service capabilities.
- Biotechnology Firms:Venture-stage discovery operations with milestone-tied capital deployment.
- Academic Laboratories:Grant-funded precision medicine research with shared core facility access models.
- Clinical Testing Facilities:CLIA-regulated diagnostic testing with proficiency testing alignment requirements.
Pharmaceutical Manufacturers deploy the most installed units. Contract Research Organizations are expanding procurement fastest in Asia-Pacific contract research expansion zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redistributing test equipment procurement toward jurisdictions with streamlined compliance pathways. Manufacturers gravitate toward markets where FDA 21 CFR Part 11 alignment intersects with favorable R&D tax treatment.
United States
Venture-funded biotechs in Massachusetts and California drive throughput analyzer procurement tied to IND filing milestones. FDA pre-approval inspection requirements force instrumented validation upgrades across gene therapy CDMOs. The Boston-San Francisco corridor concentrates equipment deployment for CRISPR library screening workflows.
Germany
Gravimetric sensor supply concentration in Baden-Württemberg and Bavaria exposes lead time vulnerabilities for pharmaceutical clients. REACH Annex XVII compliance costs for fluid-contact materials are absorbed through captive polymer compounding. Stuttgart-area analytical instrument manufacturers reformulate pump diaphragms to eliminate SVHC-classified perfluorinated compounds.
Switzerland
Precision load-cell manufacturing clusters around Basel and Zurich anchor European gravimetric verification supply chains. Swissmedic device regulations align with EU MDR documentation standards for companion diagnostics. Roche-affiliated CDMOs in the Basel biotech hub deploy integrated validation platforms for viral vector production.
India
CDSCO-aligned bioequivalence labs in Hyderabad and Bengaluru underinvest in automated validation relative to US counterparts. The country's national pharmaceutical regulator is tightening analytical method validation requirements for export-oriented generics. Contract research expansion in Genome Valley creates distribution opportunity for localized test equipment service capabilities.
United Kingdom
Post-Brexit divergence from EU MDR is slowing IVD manufacturer equipment refresh cycles. MHRA recognition agreements with FDA are preserving US market access for British diagnostic developers. The Cambridge-Oxford-London golden triangle sustains academic procurement of precision balancers for mass spectrometry sample preparation.
High-Throughput Liquid Handling Robot Performance Test Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded sensor integration and subscription-based calibration services. The vendor base stratifies around captive manufacturing depth versus modular specialization. Three archetypes dominate: vertically integrated life-science conglomerates, precision instrumentation specialists, and robotics-originated platform developers. Consolidation pressures favor multi-year service contract bundling over equipment-only sales; geographic expansion into underpenetrated Asian CRO markets represents the second dominant competitive vector.
Among US-based diversified life-science groups, Thermo Fisher Scientific and Danaher exemplify the integrated-platform archetype through captive supply chain control and diagnostics footprint extension. Agilent Technologies anchors the precision instrumentation tier with R&D-intensive throughput analyzer architectures. These three occupy positions that reward consolidated vendor relationships with pharmaceutical manufacturers seeking compressed regulatory audit cycles.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Danaher |
| Tecan Trading AG |
| Hamilton Company |
| Eppendorf |
| PerkinElmer |
| QIAGEN |
| METTLER TOLEDO |
| Others |
Pricing and Supply Chain Analysis
ASQ-certified metrology technician scarcity in the United States widens pricing-tier spreads between premium integrated platforms and modular alternatives, as labor-cost differentials force mid-cap biotechs toward subscription-based calibration services while pharmaceutical manufacturers absorb capital premiums for single-vendor consolidation.
Pricing Analysis
Distributor margins on precision test modules compress as direct-to-OEM arrangements expand among top-tier vendors. Pricing stratifies across premium, standard, and economy tiers based on calibration traceability grade and after-sales service bundling. Cost compression in standard-tier equipment intensifies because German and Swiss load-cell supply concentration limits pass-through pricing power. Mid-cap biotechs lacking internal quality infrastructure exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize audit-cycle compression over unit economics.
Supply Chain Analysis
Gravimetric sensor supply rests on German and Swiss load-cell manufacturers controlling specialized production of sub-milligram resolution arrays. Iridium and rhodium feedstock for flow meter electrodes draws from South African and Russian mining operations, tethering component costs to London Metal Exchange volatility. Single-source vulnerability in precision sensor supply exposes lead times to geopolitical disruption. Distribution runs through authorized life-science distributors with certified metrology service capabilities, concentrating in Boston and San Francisco biotech corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FDA 21 CFR Part 11 electronic records mandates forcing replacement cycles that compound demand across successive compliance deadlines.
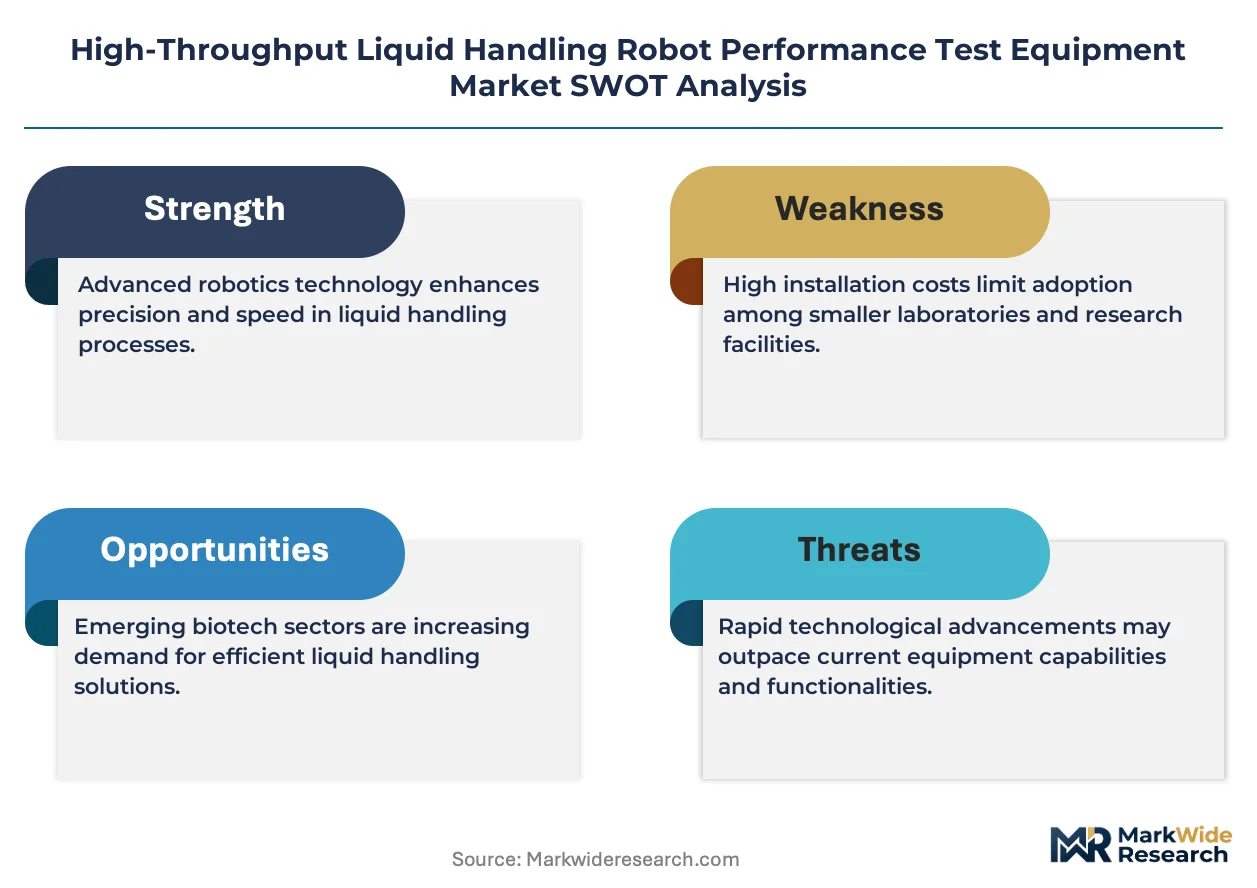
For Market Incumbents: Anchor multi-year service contract penetration through captive calibration substrate manufacturing, compressing lead times for drug-discovery clients facing IND filing pressure. Deepen R&D spending on throughput analyzer architectures to defend against embedded sensor-robot platforms displacing standalone analyzers. Extend diagnostics footprint into adjacent test-equipment categories before emerging robotics-originated platform developers capture modular integration share. For New Entrants and Emerging Players: Capture first-mover advantage in CDSCO-aligned bioequivalence labs across Hyderabad and Bengaluru, where Indian CROs underinvest in automated validation relative to US counterparts. Target AI-driven predictive calibration services as the most penetrable segment, enabling condition-based maintenance differentiation. Deploy localized distribution partnerships with metrology service capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among precision instrumentation specialists lacking integrated platform breadth but holding captive gravimetric sensor supply relationships. Long-term viability over the mid-term projection horizon favors vendors with backward integration into calibration substrates and polymer compounding for REACH-compliant fluid-contact materials. Watch FDA pre-approval inspection timelines as the signal indicating inflection in gene therapy CDMO equipment refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration-as-a-Subscription Launch | Transfers metrology labor liability to vendors serving Series C-funded biotechs in Massachusetts. |
| Embedded Sensor-Robot Platform Integration | Collapses feedback loops between dispense execution and quality documentation for viral vector CDMOs. |
| Captive Polymer Compounding Investment | Absorbs REACH Annex XVII compliance costs for hydrogenated nitrile rubber pump diaphragms in Germany. |
| Localized Service Capability Expansion | Addresses underinvestment in automated validation across Genome Valley contract research clusters. |
| AI-Driven Predictive Calibration Development | Enables shift-from-scheduled to condition-based maintenance using dispense history machine learning models. |
Research Methodology
Coverage spans the United States, Germany, Switzerland, India, and the United Kingdom, with primary inputs from each market cluster combined with secondary validation. Primary interviews engaged drug development executives, regulatory affairs leads, biomedical engineers, and GPO contracts managers alongside metrology service heads at precision instrumentation vendors. Secondary sources included FDA 510(k) filings, EMA design-dossier submissions, ISO 8655 calibration protocol documentation, and SEC 10-K disclosures from diversified life-science groups. Bottom-up equipment unit estimates triangulated against top-down market sizing derived from pharmaceutical R&D expenditure allocations.
Granularity-level modeling addressed equipment type, performance metric, application, and end user across national regulatory clusters and venture-funding stage. CAGRs were derived from regression analysis of historical procurement patterns against regulatory milestone timelines, with cross-validation through vendor shipment disclosures. Forecast inputs incorporated IND filing velocity from Massachusetts and California biotech clusters, EU MDR implementation pacing for companion diagnostics, and CDSCO bioequivalence lab expansion trajectories in Hyderabad and Bengaluru.
Platinum-group metal price volatility, German load-cell supply disruption, and FDA inspection timeline acceleration are the dominant revision risks to projection assumptions. Forecasts reflect documented assumptions about regulatory enforcement continuity and venture capital availability for discovery-stage biotechs. A small set of named triggers—REACH Annex XVII expansion, Swissmedic-EU MDR alignment shifts, and Indian CDSCO method validation tightening—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
AI-Enabled Testing Tools Market
Test and Measurement
Calibration Services Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Fogging Tester Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
Video Measuring System Market
Test and Measurement
Wireless Network Test Equipment Market
Test and Measurement
United States Borescope Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Network Tester Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
Flow Meter Calibration Market