
 LAN Tester Market | 2026-2036
LAN Tester Market Size, Share, and Industry Trends Forecast 2026-2036
LAN Tester Market Foresight
Copper-centric certification platforms is consolidating around fiber-capable architectures as single-mode and multimode deployments displace legacy Cat 6A dominance in hyperscale environments. Fluke Networks leverages its channel density across North American distributor networks to sustain service-level agreements with enterprise cabling contractors. Keysight Technologies anchors its position through R&D intensity in high-speed Ethernet validation, while EXFO Inc. specializes in fiber-optic test modules that address data center interconnect scaling.
A LAN tester is an electronic instrument that verifies continuity, wire mapping, attenuation, and crosstalk in structured cabling systems, typically supporting frequencies up to 2 GHz for Category 8 certification and optical loss measurements for fiber links. Its primary commercial purpose is to certify that installed infrastructure meets TIA and ISO performance standards before network equipment activation. Cable testers occupy the mature core of the product mix, where margin pools have compressed due to commoditization of basic wire-mapping functions. Network testers represent the fastest-growing product type, driven by Power over Ethernet loading validation and 10GBASE-T deployment in smart building retrofits.
The FCC's broadband infrastructure mandates shape demand for field-portable certification tools among contractor fleets deploying fiber-to-the-home networks. TIA and ISO cabling standards directly determine which performance tiers qualify for warranty coverage, forcing manufacturers to align firmware and measurement algorithms with evolving threshold specifications. Stakeholders must monitor how 800 Gigabit Ethernet draft standards recalibrate the boundary between copper and fiber tester portfolios.
Market Dynamics
The migration from copper certification to fiber-capable validation architectures is compressing legacy product cycles while forcing R&D recalibration across the supply base. This technology displacement concentrates procurement power among hyperscale operators who specify multi-protocol test platforms.
Growth Catalysts
- Hyperscale data center buildouts:Cloud operators in the United States, Germany, and Japan are mandating certification-grade testers for pre-activation validation of 400G and 800G fiber links. This sustains replacement demand for obsolete copper-only instruments.
- FCC broadband equity deployment:The United States' infrastructure funding programs require field-portable testers for fiber-to-the-home contractor fleets, elevating procurement volumes for wire-mapping and optical loss measurement tools.
- East Asian manufacturing integration:Contract electronics producers in Taiwan, South Korea, and Vietnam have embedded LAN validation into production line quality protocols, creating captive demand for high-throughput automated testers.
Market Restraints
- Semiconductor component volatility:FPGA and high-speed ADC supply constraints from concentrated foundry sources in Taiwan create lead time uncertainty for tester manufacturers.
- Technical obsolescence pressure:Rapid IEEE 802.3 standard evolution for 800 Gigabit Ethernet compresses product lifecycles before R&D amortization completes.
- Substitution by embedded diagnostics:Smart switch and router platforms with built-in cable qualification functions reduce standalone tester necessity in enterprise retrofits.
Strategic Opportunities
- India broadband expansion:The country's national digital infrastructure mission creates underpenetrated demand for cost-optimized certification tools among regional cabling contractors.
- Power over Ethernet validation convergence:Integrated load-testing for 90W PoE++ alongside data certification opens retrofit opportunities in smart building and industrial IoT deployments.
- Cloud-based test data management:SaaS platforms for centralized certification documentation and warranty tracking represent channel innovation beyond hardware-only sales models.
Industry Challenges
- Calibration technician scarcity:Precision metrology skills required for ISO 17025-compliant tester maintenance are concentrated among aging specialist workforces in Germany and Japan.
- Firmware certification lag:TIA and ISO threshold updates demand 6-12 month validation cycles before manufacturers can claim warranty-eligible measurement accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAN Tester Market |
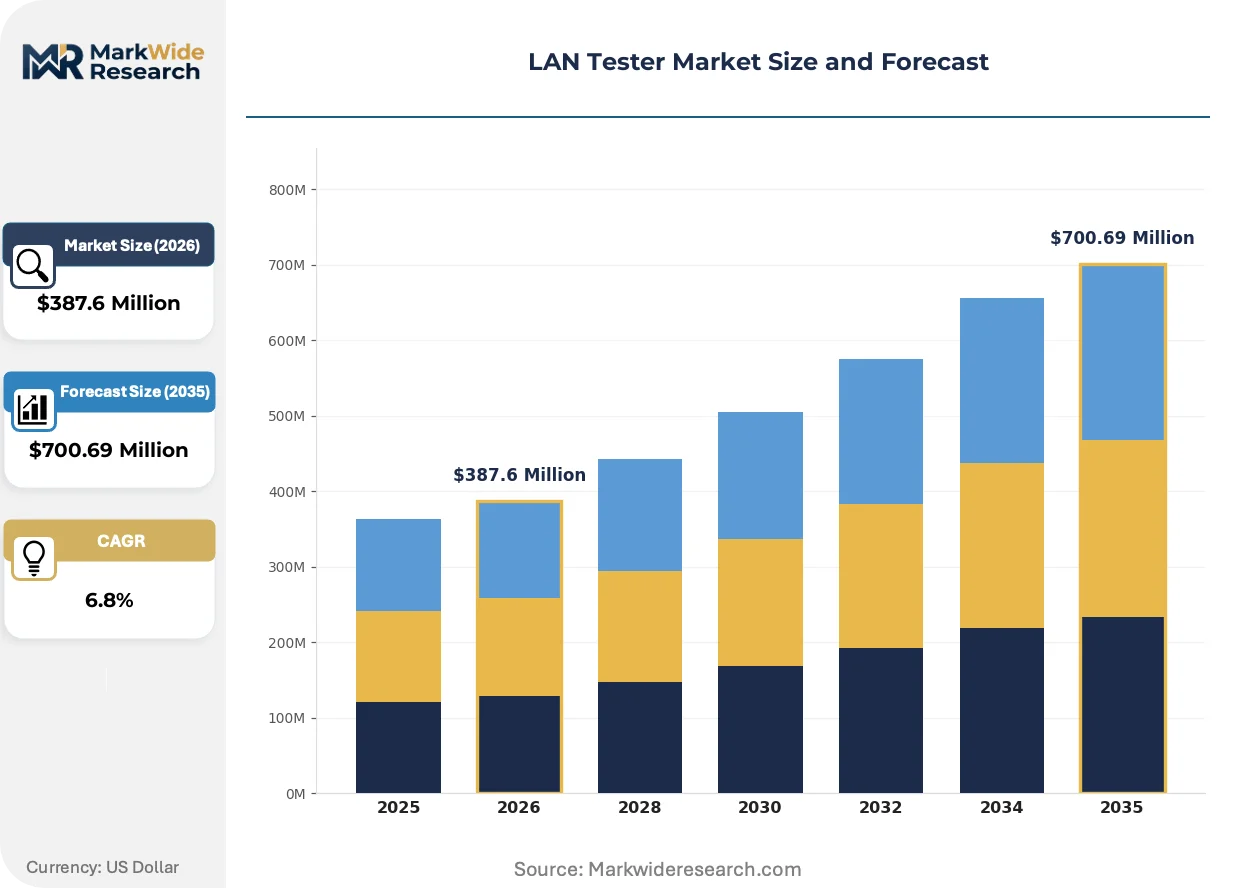
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable Tester, Network Tester, Signal Tester, Multimeter End User: Telecommunications, IT Services, Educational Institutions, Government Agencies Technology: Ethernet, Fiber Optics, Coaxial, Wireless Application: Network Installation, Troubleshooting, Maintenance, Performance Monitoring |
| Companies Covered | VIAVI Solutions, TREND Networks, Fluke Networks, Klein Tools, NetScout Systems, Keysight Technologies, EXFO Inc., B&K Precision, Anritsu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAN Tester Market Shifts & Advancements
Test platform architectures are converging around software-defined measurement engines that decouple hardware from protocol-specific certification algorithms. This shift enables faster standard adaptation without full instrument replacement.
Cloud-native test automation is automating the execution of complex certification sequences across distributed technician fleets. Enterprise cabling contractors in the United States are deploying tablet-integrated testers that synchronize measurement data directly to project management platforms. This architecture is automating the elimination of manual result transcription errors and compressing project closeout timelines from days to hours.
The European Union's CSRD sustainability disclosure requirements are mandating embodied carbon documentation for network infrastructure assets. Data center operators in Germany, France, and the Netherlands must now certify cable plant environmental footprints alongside performance metrics. This regulatory layer is elevating demand for testers with integrated material traceability and lifecycle assessment data capture.
Buyer consolidation among national cabling contractors is fragmenting historical distributor relationships. Large integrated facilities firms in the United States and United Kingdom are negotiating direct procurement agreements with tester manufacturers, bypassing traditional electrical supply houses. This channel compression is most visible in metropolitan smart building retrofit markets where volume concentration justifies dedicated account management structures.
LAN Tester Market Segmentation
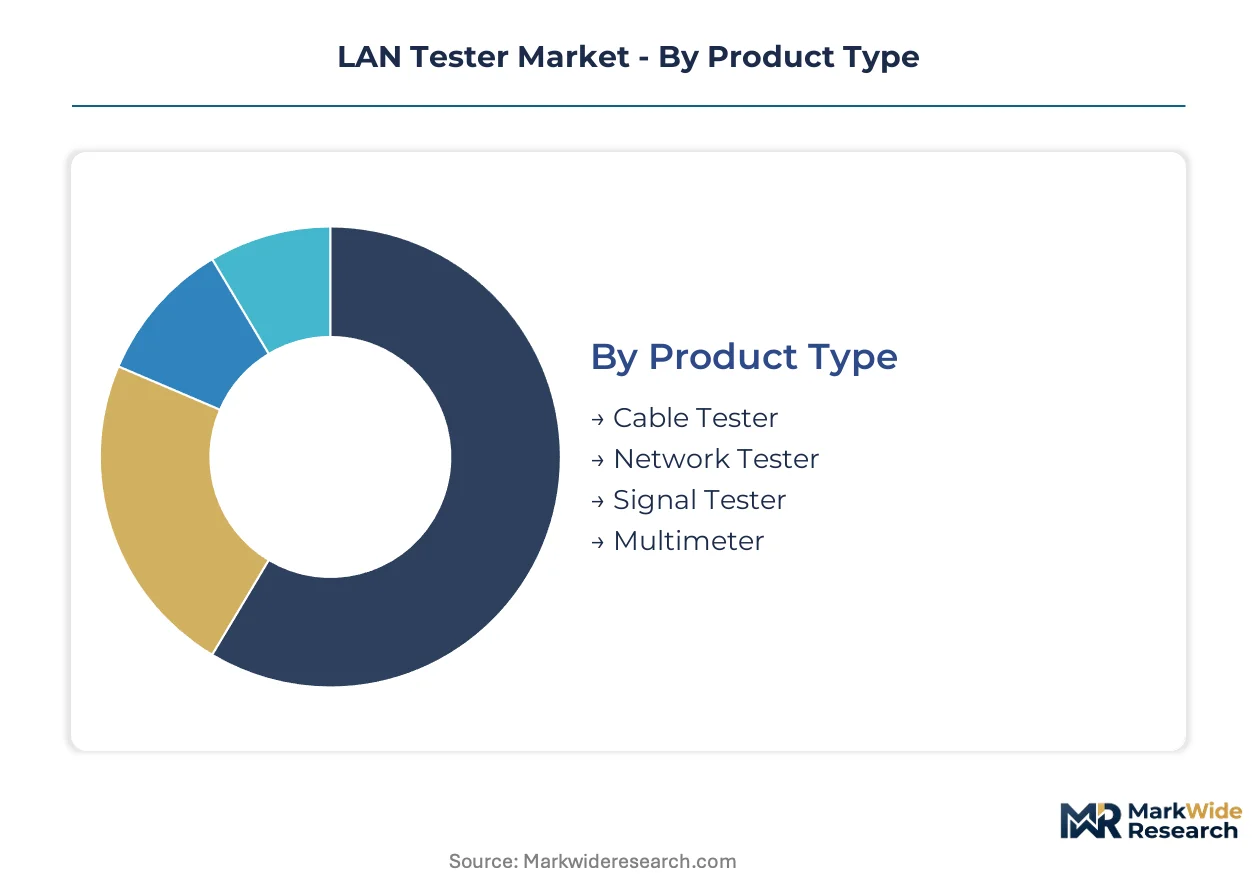
Segmentation in the LAN tester market reveals how certification requirements, technology transitions, and end-use economics fragment procurement patterns. Each dimension carries distinct TIA and ISO compliance burdens that shape product specification and channel strategy.
Product Type:
Cable testers carry the heaviest certification burden under TIA-568 and ISO 11801 standards, requiring traceable calibration for warranty eligibility. Network testers face evolving IEEE 802.3 protocol validation demands.
- Cable Tester:Instruments validating wire mapping, continuity, and crosstalk in structured copper cabling up to Category 8 frequencies. Demand concentrates among contractor fleets deploying fiber-to-the-home networks in the United States under FCC broadband equity mandates, where field-portable certification tools require ISO 17025-compliant calibration maintenance.
- Network Tester:Platforms integrating Power over Ethernet load validation with 10GBASE-T performance verification. Hyperscale data center operators in Germany and Japan specify these for pre-activation validation of 400G and 800G fiber links, driving replacement of obsolete copper-only instruments.
- Signal Tester:Specialized instruments for analog and digital signal integrity measurement in legacy infrastructure.
- Multimeter:General-purpose electrical measurement tools with basic LAN troubleshooting capabilities.
Leading the category by volume: Cable Tester. Expanding most quickly: Network Tester.
End User:
Cost tier segmentation separates enterprise-grade certification platforms from contractor-optimized field units. Procurement scale and calibration infrastructure access determine specification thresholds.
- Telecommunications:Carriers and service providers deploying last-mile fiber and 5G fronthaul infrastructure. Volume procurement in Taiwan, South Korea, and Vietnam contract manufacturing clusters drives captive demand for high-throughput automated validation systems integrated into production lines.
- IT Services:Enterprise cabling contractors and systems integrators performing smart building retrofits. Large integrated facilities firms in the United States and United Kingdom negotiate direct procurement agreements, bypassing traditional electrical supply houses.
- Educational Institutions:Universities and technical colleges with network engineering training laboratories.
- Government Agencies:Public sector infrastructure deployments with mandated domestic sourcing requirements.
Highest procurement concentration: Telecommunications. Fastest specification evolution: IT Services.
Technology:
Application maturity varies sharply across transmission media, with fiber architectures displacing copper dominance in hyperscale environments and driving R&D recalibration.
- Ethernet:Copper-based twisted-pair validation from 10BASE-T through 10GBASE-T. Smart building retrofits in the United States sustain demand for Power over Ethernet certification alongside data performance testing.
- Fiber Optics:Single-mode and multimode optical loss measurement for data center interconnect scaling. Cloud operators mandate certification-grade validation, compressing legacy copper product cycles while concentrating procurement power among hyperscale operators specifying multi-protocol test platforms.
- Coaxial:Legacy broadband and video distribution infrastructure testing.
- Wireless:Wi-Fi spectrum analysis and RF validation for converged network deployments.
Dominant by installed base: Ethernet. Steepest expansion trajectory: Fiber Optics.
Application:
Customer workflow integration determines whether testers serve as installation commissioning tools or ongoing operational diagnostics, shaping software and connectivity requirements.
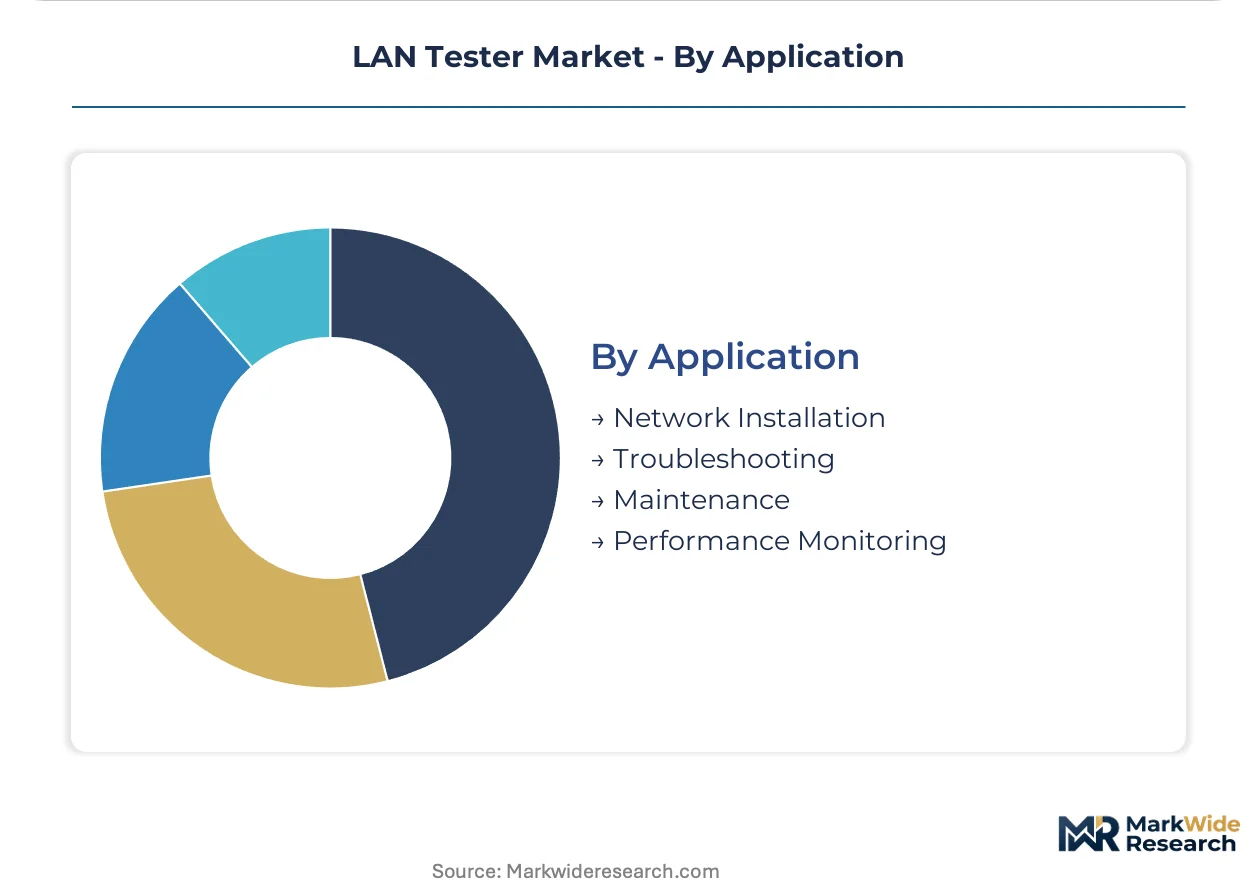
- Network Installation:Pre-activation certification for new infrastructure deployment. European Union CSRD sustainability disclosure requirements now mandate embodied carbon documentation alongside performance metrics, elevating demand for testers with integrated material traceability.
- Troubleshooting:Fault isolation in operational networks. Cloud-native test automation synchronizes measurement data directly to project management platforms, eliminating manual result transcription errors.
- Maintenance:Scheduled validation and preventive testing programs.
- Performance Monitoring:Continuous link quality assessment in critical infrastructure.
Largest addressable segment: Network Installation. Gaining share fastest: Troubleshooting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Taiwan and Vietnam concentrate contract electronics manufacturing, driving captive demand for automated LAN validation systems integrated into production lines. Data center clusters in Northern Virginia, Frankfurt, and Tokyo sustain procurement of certification-grade fiber testers. Government broadband programs in the United States, Germany, and India channel infrastructure funding toward field-portable installation tools.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth mandate pre-activation validation of 400G and 800G fiber links. The FCC's broadband equity deployment programs require contractor fleets to deploy fiber-to-the-home networks with certified installation tools. Enterprise cabling contractors in metropolitan smart building markets negotiate direct procurement agreements with tester manufacturers.
Germany
Data center operators in Frankfurt and Munich must certify cable plant environmental footprints under the European Union's CSRD sustainability disclosure requirements. TIA and ISO cabling standards determine warranty eligibility, forcing firmware alignment with evolving threshold specifications. Precision metrology skills for ISO 17025-compliant tester maintenance concentrate among specialist workforces in Bavaria and Baden-Württemberg.
Japan
METI's digital infrastructure initiatives sustain enterprise demand for high-speed Ethernet validation platforms. Cloud operators in Tokyo and Osaka specify multi-protocol test architectures that displace legacy copper-only instruments. Aging specialist workforces in the Kanto and Kansai regions concentrate the scarce calibration technician skills required for precision metrology maintenance.
Taiwan
Contract electronics producers in Hsinchu Science Park and Taichung have embedded LAN validation into production line quality protocols. Semiconductor component volatility from concentrated foundry sources creates lead time uncertainty for FPGA and high-speed ADC supply. The island's special economic zones drive captive demand for high-throughput automated testers among integrated circuit packaging facilities.
India
The national digital infrastructure mission creates underpenetrated demand for cost-optimized certification tools among regional cabling contractors. TRAI's broadband expansion mandates channel funding toward network infrastructure in Maharashtra and Karnataka. Smart building retrofits in Bangalore and Hyderabad sustain demand for Power over Ethernet validation alongside data performance testing.
LAN Tester Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with certification-grade platforms consolidating around multi-protocol architectures while field-portable units fragment across regional distributors. The vendor base organizes into three strategic archetypes: precision instrumentation conglomerates with R&D intensity in high-speed validation, fiber-optic specialists addressing data center interconnect scaling, and electrical tool manufacturers extending into network diagnostics. Dominant competitive moves include backward integration into semiconductor component sourcing and geographic expansion through direct procurement agreements with national cabling contractors.
Among precision instrumentation specialists, VIAVI Solutions and Keysight Technologies exemplify the R&D-intensive archetype, while Fluke Networks occupies a position within the channel-dense electrical testing tier. EXFO Inc. represents the fiber-optic specialization vector. These three companies collectively illustrate how competitive positioning diverges between protocol validation depth and distribution reach.
| Leading Market Players |
|---|
| VIAVI Solutions |
| TREND Networks |
| Fluke Networks |
| Klein Tools |
| NetScout Systems |
| Keysight Technologies |
| EXFO Inc. |
| B&K Precision |
| Anritsu Corporation |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up electrical testing specialists have consolidated regional distributor networks across North America and Western Europe, tightening pricing discipline while compressing procurement cycles for FPGA and high-speed ADC components sourced from Taiwanese foundries. This ownership pattern concentrates volume leverage among hyperscale data center operators who negotiate direct certification-grade tester agreements, bypassing traditional markup layers.
Pricing Analysis
Premium pricing for sub-8-week lead times separates urgent fiber-certification deployments from standard 12-16 week delivery schedules. Three-tier pricing structure across certification-grade, field-portable, and economy wire-mapping tiers reflects ISO 17025 calibration bundling and firmware update entitlements. Cost compression in economy copper testers intensifies because smart switch embedded diagnostics substitute standalone validation functions. Regional cabling contractors in India exhibit highest price sensitivity, while hyperscale cloud operators in Northern Virginia and Frankfurt accept premium positioning for multi-protocol fiber platforms.
Supply Chain Analysis
Precision metrology technician scarcity in Bavaria, Baden-Württemberg, and Japan's Kanto region constrains calibration infrastructure expansion despite surging demand for ISO 17025-compliant maintenance. Component sourcing draws from Taiwan for FPGA and high-speed ADC supply, Germany for precision mechanical assemblies, and Japan for optical measurement modules. Single-source vulnerability around Taiwanese foundry concentration creates lead time uncertainty that ripples through certification-grade tester production schedules. Distribution runs through national electrical supply houses in fragmented contractor markets, while direct manufacturer agreements dominate hyperscale data center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAN tester market has become a vertical-integration race, with players pursuing backward control over semiconductor component supply to escape foundry lead time volatility and firmware certification lag cycles.
For Market Incumbents: Acquire FPGA and high-speed ADC design capabilities or captive foundry allocation agreements to secure component supply against Taiwanese concentration risk. Consolidate calibration service infrastructure in Germany and Japan where aging specialist workforces threaten ISO 17025 compliance capacity. Defend against embedded smart switch diagnostics by bundling cloud-based test data management SaaS with hardware certification platforms. For New Entrants and Emerging Players: Direct-to-contractor digital channels bypassing traditional electrical supply houses offer lowest-friction entry into India's underpenetrated regional cabling contractor market. Target cost-optimized fiber-to-the-home certification tools for Maharashtra and Karnataka broadband deployment zones. White-space opportunity exists in automated production-line testers for Vietnam and Taiwan contract electronics manufacturers integrating LAN validation into quality protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision metrology service specialists in Germany and Japan with captive calibration technician workforces and established ISO 17025 laboratory infrastructure. Long-term viability hinges on multi-protocol test platform architectures adaptable to 800 Gigabit Ethernet standard evolution without full instrument replacement. Monitor IEEE 802.3 draft standard progression as inflection signal for R&D recalibration timing across portfolio holdings.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captive FPGA supply from Taiwanese foundries insulates against lead time volatility affecting certification-grade production. |
| Cloud-Based Test Data Management Platform Launch | SaaS documentation layers defend hardware margins against embedded smart switch substitution in enterprise retrofits. |
| Calibration Infrastructure Acquisition in Germany | ISO 17025 laboratory networks in Bavaria capture scarce precision metrology technician capacity for warranty-eligible maintenance. |
| Direct Procurement Agreement with Hyperscale Operators | Bypassing distributor markup layers secures volume commitment from Northern Virginia and Frankfurt data center clusters. |
| PoE++ Load Testing Module Development | 90W validation convergence opens smart building retrofit opportunities alongside standard data certification offerings. |
Research Methodology
Trade publications, TIA and ISO standards documentation, and FCC broadband infrastructure filings formed the secondary backbone, cross-referenced against hyperscaler capex disclosures and contract electronics manufacturing production data. Primary interviews with enterprise cabling contractors, data center facilities engineers, calibration laboratory technicians, and electrical supply house procurement managers validated demand patterns and pricing dynamics. Bottom-up unit shipment estimates by product type and technology triangulated against top-down infrastructure spending projections across the analysis window.
Historical trendline analysis of certification-grade tester procurement cycles anchored the projection framework, with segmentation across copper and fiber architectures, cable versus network tester categories, and telecommunications versus IT services end-use channels. CAGRs were derived from infrastructure deployment timelines, standard evolution schedules, and replacement cycle compression factors. Hyperscale data center buildout trajectories in Northern Virginia, Frankfurt, and Tokyo, alongside FCC broadband equity program disbursement schedules, informed fiber-tester demand modeling.
The model holds under steady IEEE 802.3 standard evolution and stable Taiwanese foundry output; deviation in semiconductor supply disruption or accelerated 800 Gigabit Ethernet ratification would shift replacement cycle assumptions. Forecasts reflect documented infrastructure spending commitments and regulatory funding authorizations without contingency for program cancellation or tariff restructuring. Material deviation in foundry capacity allocation or broadband subsidy appropriation levels warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Dew Point Apparatus Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Wafer-Level Test and Burn-In [WLTBI] Market
Test and Measurement
Automatic Impact Testing Machine Market
Test and Measurement
LAMEA Semiconductor Metrology and Inspection Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Europe Electronic Test and Measurement Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
United States Signal Generator Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Surface Measurement Equipment and Tools Market