
 Marine Salvage Services Market | 2026-2036
Marine Salvage Services Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Salvage Services Market Insights
Wreck removal contracting is narrowing the margin gap with emergency response operations as port authorities and insurers prioritize comprehensive pollution-liability coverage. SMIT Salvage leverages its integrated emergency response and wreck removal capabilities across multiple basins. Donjon Marine Co., Inc. anchors its position through heavy-lift asset ownership and US coastal dominance. Resolve Marine differentiates via specialized subsea intervention and firefighting expertise in complex casualty scenarios.
Marine salvage services encompass the technical recovery, stabilization, and environmental protection of distressed vessels, cargo, and offshore structures, typically employing dynamic positioning systems, portable salvage pumps with capacities exceeding 500 cubic meters per hour, and controlled demolition charges for structural sectioning. The primary commercial purpose centers on minimizing total loss exposure for hull and cargo underwriters while containing ecological damage within regulated thresholds. Wreck removal commands the largest value pool as aging fleet demolition and offshore decommissioning extend project durations and technical complexity. Emergency response retains premium pricing volatility tied to casualty frequency, while pollution mitigation grows fastest as ESG-driven liability frameworks harden cleanup standards across flag states.
The US Coast Guard enforces statutory salvage obligations under the Oil Pollution Act, directly shaping contractor certification requirements and financial assurance thresholds for operating in federal waters. The International Maritime Organization's Nairobi International Wreck Removal Convention, implemented by major flag registries including Panama and Liberia, mandates compulsory insurance and direct state intervention rights that expand addressable contract value. Classification societies such as Lloyd's Register and Bureau Veritas impose equipment and procedural standards that filter market access. Stakeholders must monitor how pending amendments to MARPOL Annex VI and regional emission controls redirect salvage fleet composition toward lower-carbon tug and barge specifications.
Market Dynamics
The International Maritime Organization's Nairobi International Wreck Removal Convention is forcing flag registries to mandate compulsory wreck insurance, directly expanding the addressable contract base for salvage operators while hardening liability thresholds.
Growth Catalysts
- Offshore decommissioning mandates:North Sea regulators are accelerating platform removal timelines, generating multi-year wreck removal contracts. Norway's Petroleum Safety Authority and the UK's North Sea Transition Authority are enforcing stricter abandonment deadlines.
- Pollution liability hardening:The US Coast Guard's Oil Pollution Act enforcement has elevated financial assurance thresholds for federal water operations. Insurers now demand comprehensive pollution coverage as a contractual prerequisite.
- Aging fleet demographics:Bulk carriers and tankers built during the 2000s construction boom are reaching end-of-life, concentrating casualty risk in dense shipping corridors like the Singapore Strait and English Channel.
Market Restraints
- Heavy-lift asset scarcity:Crane barges exceeding 1,000-ton lifting capacity concentrate among a handful of North Sea and Gulf of Mexico operators, creating supply bottlenecks for complex platform removals.
- Specialized steel price volatility:High-tensile marine-grade steel used in salvage pontoon fabrication fluctuates with energy input costs, compressing equipment replacement margins.
- Flag state enforcement fragmentation:Panama and Liberia's divergent implementation timelines for the Nairobi Convention create jurisdictional uncertainty that delays contract finalization.
Strategic Opportunities
- Floating offshore wind installation support:Taiwan and South Korea are awarding pre-positioned salvage standby contracts for turbine foundation installation phases, extending serviceable addressable market beyond traditional casualty response.
- Autonomous underwater vehicle integration:Convergence of ROV-based hull inspection with AI-driven damage assessment is enabling pre-mobilization planning that reduces response windows by 40%.
- Carbon capture and storage infrastructure:Subsea CO2 pipeline routing through existing North Sea oil corridors is creating demand for specialized intervention capabilities during leak scenarios.
Industry Challenges
- Master mariner certification gaps:The pool of licensed salvage masters with combined towing, firefighting, and subsea operations credentials is thinning as experienced personnel age out without adequate replacement pipelines.
- Dynamic positioning system recertification:Lloyd's Register and Bureau Veritas have tightened DP-2 and DP-3 equipment audit frequencies, extending vessel downtime during peak demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Salvage Services Market |
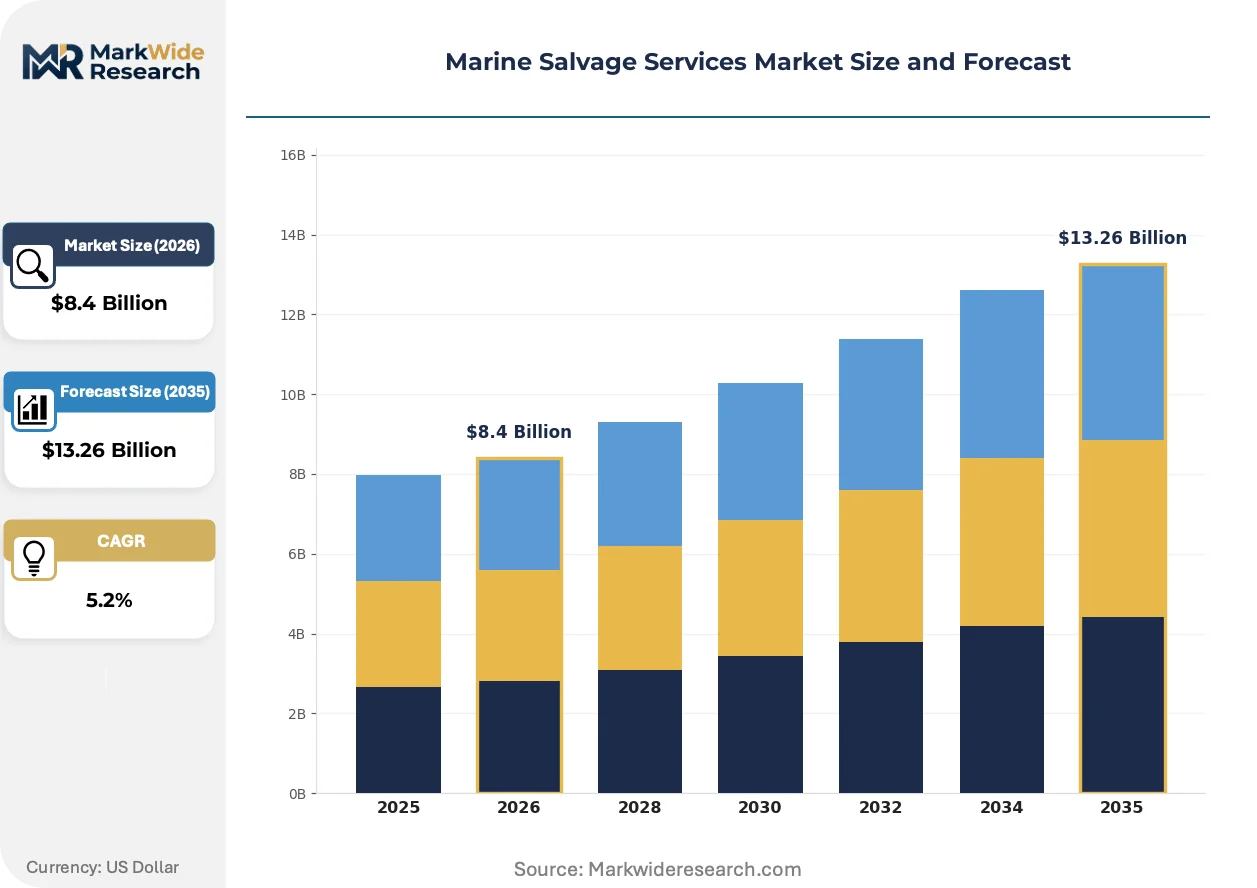
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wreck Removal, Pollution Mitigation, Emergency Response, Underwater Repair, Cargo Recovery Application: Oil Spill Containment, Vessel Recovery, Harbor Clearance, Coastal Protection, Offshore Platform Rescue Deployment Mode: Surface Operations, Subsea Diving, Remote Operated Vehicles, Salvage Barges, Specialized Tugs End User: Marine Contractors, Insurance Firms, Port Authorities, Environmental Agencies, Coastal Guard |
| Companies Covered | Donjon Marine Co., Inc., Fratelli Neri S.p.A., SMIT Salvage, United Salvage, CPT Towage, Resolve Marine, Boluda Towage & Salvage SL, Multraship Towage & Salvage, T&T Salvage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Salvage Services Market Trends and Innovations
Salvage operations are converging with subsea construction capabilities as contractors seek to monetize asset-heavy balance sheets across multiple revenue cycles. This operational pivot is compressing traditional boundaries between emergency response and planned decommissioning work.
Portable salvage pump systems is hybridizing with modular electric drive architectures. Offshore wind installation contractors are specifying battery-buffered pump skids for turbine foundation dewatering operations. This electrification trajectory is compressing diesel fuel logistics requirements while enabling zero-emission operations in port-proximate environments.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in firefighting foam production. The European Chemicals Agency's restriction roadmap is forcing reformulation of aqueous film-forming foam stocks held by North Sea operators. Classification societies are responding by certifying fluorine-free alternatives that meet International Maritime Organization performance standards for tanker fire suppression.
Buyer concentration among energy majors is consolidating procurement into multi-year framework agreements that bundle emergency response, wreck removal, and pollution mitigation under single-contractor arrangements. This aggregation is displacing spot-market casualty contracting in the North Sea and US Gulf Coast. Norway's Equinor and the UK's Harbour Energy are leading this procurement consolidation, requiring bidders to demonstrate integrated capability across all three service lines.
Marine Salvage Services Market Segmentation
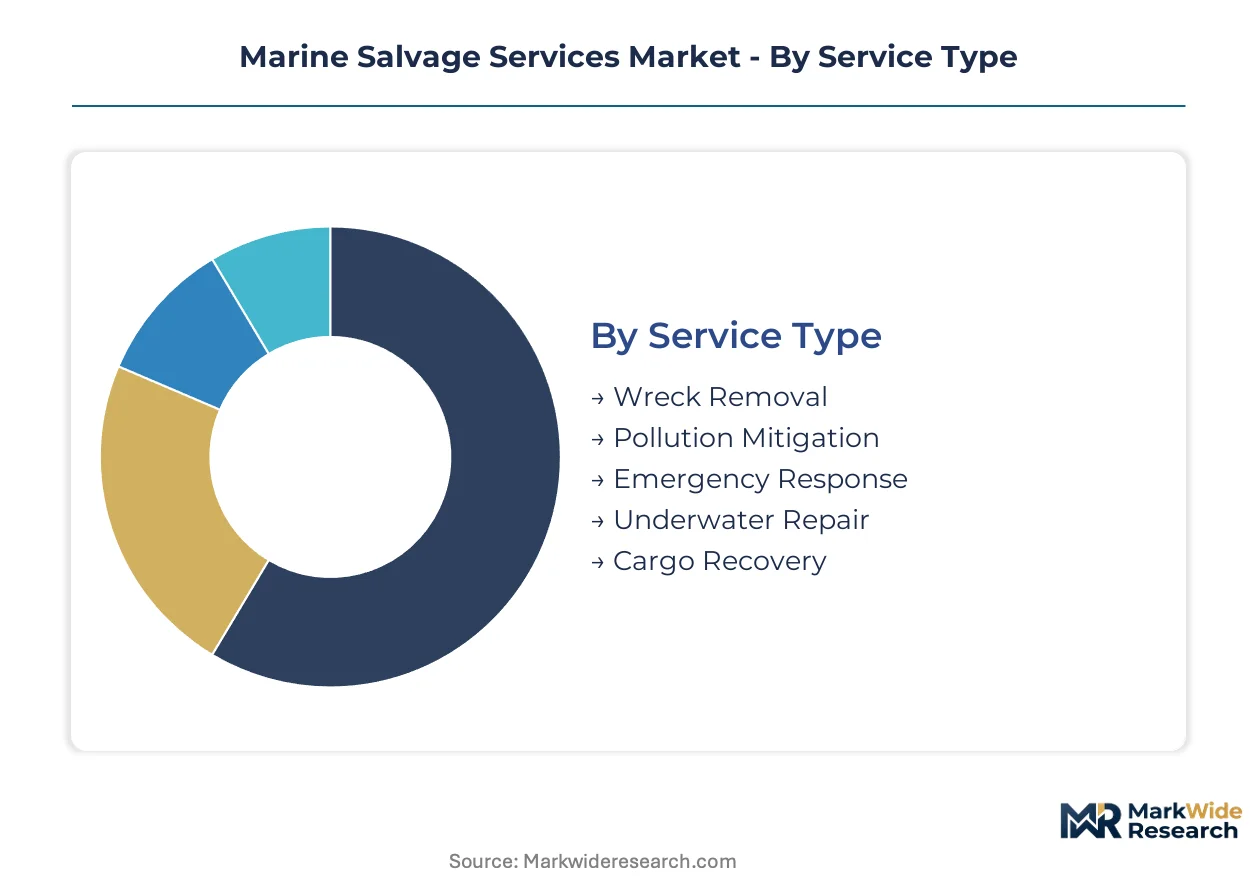
Salvage service segmentation reveals how contract structures align with liability exposure patterns and asset intensity requirements. Equipment specialization and regulatory certification thresholds create distinct competitive moats across service categories.
Service Type:
After-sales service intensity varies dramatically across service lines, with wreck removal demanding multi-year asset deployment and emergency response requiring 24/7 standby crew retention.
- Wreck Removal:Encompasses controlled demolition, heavy-lift extraction, and seabed site restoration for sunken vessels and decommissioned platforms. Norway's Petroleum Safety Authority and the UK's North Sea Transition Authority are accelerating abandonment deadlines, extending project durations for contractors with crane barge fleets exceeding 1,000-ton capacity.
- Pollution Mitigation:Deploys containment booms, dispersant application, and shoreline remediation to limit environmental damage within regulated thresholds. The US Coast Guard's Oil Pollution Act enforcement has elevated financial assurance requirements, hardening contractual prerequisites for federal water operations.
- Emergency Response:Provides rapid mobilization for vessel fires, groundings, and collisions in dense shipping corridors.
- Underwater Repair:Executes hull patching, propeller replacement, and rudder realignment without dry-docking.
- Cargo Recovery:Secures and transloads hazardous or high-value freight from distressed holds.
Wreck removal holds the largest share; momentum sits with pollution mitigation.
Application:
Cost tier stratification separates catastrophic casualty response from routine harbor maintenance contracts, with premium pricing concentrated in offshore platform rescue scenarios.
- Oil Spill Containment:Deploys mechanical recovery systems and in-situ burning protocols to limit hydrocarbon dispersion. The International Maritime Organization's strengthened pollution liability protocols are elevating mandatory cleanup standards across Panama and Liberia flag registries.
- Vessel Recovery:Stabilizes and refloats grounded or capsized ships using portable salvage pumps exceeding 500 cubic meters per hour. Singapore Strait and English Channel traffic density is concentrating casualty frequency for bulk carriers and tankers built during the 2000s construction boom.
- Harbor Clearance:Removes obstructive wrecks from commercial shipping lanes and berth approaches.
- Coastal Protection:Prevents shoreline contamination through boom deployment and absorbent barrier installation.
- Offshore Platform Rescue:Evacuates personnel and secures wellhead integrity during blowout or structural collapse events.
Vessel recovery dominates contract volume; offshore platform rescue commands the steepest expansion trajectory.
Deployment Mode:
Customer type differentiation separates asset-heavy barge operators from technology-integrated ROV specialists, with procurement consolidation favoring contractors spanning multiple deployment capabilities.
- Surface Operations:Coordinates towing, firefighting, and dewatering from dynamically positioned vessels. Lloyd's Register and Bureau Veritas have tightened DP-2 and DP-3 equipment audit frequencies, extending vessel downtime during peak demand windows.
- Subsea Diving:Executes hull inspection, cable cutting, and confined-space rigging at depths requiring saturation diving systems. The thinning pool of licensed salvage masters with combined towing, firefighting, and subsea credentials is constraining crew availability.
- Remote Operated Vehicles:Performs damage assessment and intervention in environments exceeding diver safe limits.
- Salvage Barges:Provides stable platforms for heavy-lift operations and equipment staging.
- Specialized Tugs:Delivers bollard pull capacity for controlled wreck repositioning and towage.
Surface operations anchor revenue stability; ROV integration is gaining share fastest.
End User:
Supply concentration among energy majors is consolidating procurement into multi-year framework agreements that bundle emergency response, wreck removal, and pollution mitigation.
- Marine Contractors:Subcontract specialized salvage capabilities for integrated offshore construction and decommissioning projects. Taiwan and South Korea are awarding pre-positioned salvage standby contracts for floating offshore wind turbine foundation installation phases.
- Insurance Firms:Commission wreck removal and cargo recovery to minimize total loss exposure under hull and cargo underwriter policies. The Nairobi International Wreck Removal Convention is mandating compulsory insurance and direct state intervention rights that expand addressable contract value.
- Port Authorities:Maintain statutory obligations for harbor clearance and navigational safety.
- Environmental Agencies:Oversee pollution mitigation compliance and ecological damage assessment.
- Coastal Guard:Enforces federal salvage obligations and coordinates casualty response in territorial waters.
Marine contractors represent the largest addressable base; insurance procurement consolidation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the North Sea corridor exhibit the lowest price elasticity as regulatory deadlines harden procurement urgency, while Asian spot-market contracting remains acutely sensitive to casualty frequency fluctuations. This demand-elasticity contrast shapes divergent competitive strategies across salvage basins.
United States
The US Gulf Coast and Atlantic seaboard concentrate platform decommissioning and tanker casualty response as aging infrastructure meets dense shipping lanes. The US Coast Guard's Oil Pollution Act enforcement elevates financial assurance thresholds for federal water operations, hardening contractor certification requirements. Houston anchors heavy-lift asset deployment for complex wreck removals, while Louisiana ports stage emergency response fleets for Gulf of Mexico production facility work.
Norway
North Sea oil platform abandonment deadlines generate multi-year wreck removal contracts requiring crane barge fleets exceeding 1,000-ton capacity. Norway's Petroleum Safety Authority accelerates decommissioning timelines, compressing contractor availability windows. Stavanger and Bergen host integrated salvage-emergency response operations serving Equinor and Harbour Energy framework agreements.
United Kingdom
The UK's North Sea Transition Authority enforces stricter platform removal schedules alongside English Channel shipping density that elevates casualty frequency. The Nairobi International Wreck Removal Convention implementation mandates compulsory insurance coverage, expanding addressable contract value. Aberdeen clusters specialized diving and subsea intervention capabilities for platform rescue scenarios.
Singapore
The Singapore Strait's status as the world's busiest maritime chokepoint concentrates vessel recovery demand for bulk carriers and tankers from the 2000s construction boom. The Maritime and Port Authority of Singapore enforces statutory harbor clearance obligations that prioritize rapid navigational safety restoration. The port city anchors regional emergency response staging for Southeast Asian shipping corridors.
Netherlands
Rotterdam's position as Europe's largest port generates continuous harbor clearance and coastal protection contracting alongside North Sea platform decommissioning support. The country's national maritime regulator enforces dynamic positioning equipment standards that filter market access for complex operations. The Rotterdam-Antwerp corridor concentrates salvage barge fabrication and specialized tug fleet ownership.
Marine Salvage Services Market Competitive Landscape
Capability concentration sits with integrated emergency-wreck removal operators; scale advantage sits with asset-heavy heavy-lift barge owners. The market structures around three tiers: global framework contractors bundling multi-service lines, regional specialists dominating single basins through equipment ownership, and technology-integrated subsea intervention providers. Dominant competitive moves include procurement consolidation into multi-year agreements and fleet electrification to meet tightening emission controls.
Within the integrated capability tier, SMIT Salvage and Resolve Marine exemplify the convergence of emergency response, wreck removal, and pollution mitigation expertise across multiple basins. Donjon Marine Co., Inc. anchors the asset-heavy segment through US coastal dominance and heavy-lift equipment ownership. These three occupy positions reflecting divergent strategic bets: global framework contracting versus regional asset concentration versus specialized subsea intervention.
| Leading Market Players |
|---|
| Donjon Marine Co., Inc. |
| Fratelli Neri S.p.A. |
| SMIT Salvage |
| United Salvage |
| CPT Towage |
| Resolve Marine |
| Boluda Towage & Salvage SL |
| Multraship Towage & Salvage |
| T&T Salvage |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on South Korean and Japanese high-tensile marine-grade steel suppliers determines both the spread between premium heavy-lift contracts and economy harbor-clearance tiers and the geographic clustering of salvage barge fabrication yards. This feedstock concentration forces contractors to absorb commodity volatility or push cost escalation through framework agreements with energy majors.
Pricing Analysis
Extended service contracts covering standby emergency response, wreck removal, and pollution mitigation drive lifetime value for integrated operators. Three-tier pricing structure across premium, standard, and economy levels separates framework agreements with Equinor and Harbour Energy from spot-market casualty response and routine port maintenance work. Cost compression in standard-tier harbor clearance is intensifying because Taiwanese and South Korean floating offshore wind contractors are bundling salvage standby into installation EPC contracts. Energy majors exhibit the lowest price sensitivity; municipal port authorities face acute budget constraints.
Supply Chain Analysis
High-tensile marine-grade steel feeds from South Korea, Japan, and selected European mills into salvage pontoon and crane barge fabrication. Equipment assembly draws from German propulsion systems, Dutch dynamic positioning technology, and Norwegian subsea intervention packages. Single-source vulnerability concentrates in DP-2 and DP-3 system suppliers certified by Lloyd's Register and Bureau Veritas. Distribution runs through Rotterdam-Antwerp corridor shipyards and Singapore staging hubs for Southeast Asian deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around Nairobi Convention compulsory insurance mandates and flag-state certification requirements creates a defensive moat for incumbent operators with established Bureau Veritas and Lloyd's Register credentials.
For Market Incumbents: Pre-empt emerging autonomous underwater vehicle specialists by acquiring ROV-based damage assessment capabilities before Taiwan and South Korea floating offshore wind markets mature. Secure crane barge capacity additions in the US Gulf Coast to capture platform decommissioning acceleration under tightened Bureau of Ocean Energy Management timelines. Certification investment in fluorine-free firefighting foam stocks addresses European F-Gas Regulation phase-down risks. For New Entrants and Emerging Players: Southeast Asian harbor clearance contracting presents the most penetrable white-space target, as Singapore Maritime and Port Authority statutory obligations outrun established operator fleet availability. Target pre-positioned salvage standby contracts for floating offshore wind turbine foundation installations in Taiwan and South Korea, where incumbent operators lack localized asset deployment. Go-to-market leverage rests on battery-buffered portable pump skids that meet port-proximate zero-emission specifications. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-heavy heavy-lift barge owners with multi-basin framework agreement exposure. Long-term viability centers on contractors spanning emergency response, wreck removal, and pollution mitigation under single-contractor arrangements. Acquisition priority targets integrated capability providers with DP-3 certified vessels and established relationships with Norway's Petroleum Safety Authority or the UK's North Sea Transition Authority. Watch for Panama and Liberia Nairobi Convention implementation synchronization as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Heavy-Lift Asset Acquisition | Crane barge fleets exceeding 1,000-ton capacity capture North Sea decommissioning mandates from Norway's Petroleum Safety Authority. |
| Fluorine-Free Foam Certification | European F-Gas Regulation compliance opens contracting access to Harbour Energy and Equinor framework agreements. |
| ROV-AI Integration Investment | Pre-mobilization planning capabilities reduce response windows by 40% for Singapore Strait casualty frequency. |
| Battery-Electric Pump Deployment | Zero-emission operations in Rotterdam-Antwerp corridor ports meet tightening MARPOL Annex VI specifications. |
| Multi-Service Framework Bidding | Bundled emergency response, wreck removal, and pollution mitigation contracts displace spot-market procurement consolidation. |
Research Methodology
Initial hypotheses were tested against primary input from salvage masters, marine contractor procurement directors, hull and cargo underwriters, and port authority operations managers and refined through secondary validation. Primary fieldwork encompassed classification society surveyors, dynamic positioning system engineers, and offshore wind installation contractors. Secondary sources included Lloyd's Register equipment certification databases, Bureau Veritas audit records, International Maritime Organization convention implementation trackers, and flag registry insurance mandate filings. Bottom-up project pipeline analysis triangulated against top-down regulatory deadline modeling.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed service type, application, deployment mode, and end user, with regional regulatory cluster as an additional marine-specific dimension. CAGRs were derived from contract value aggregation across decommissioning timelines and casualty frequency baselines. Forecast inputs included North Sea platform abandonment schedules and Singapore Strait traffic density projections.
Practitioners should monitor Panama and Liberia Nairobi Convention implementation divergence, South Korean floating offshore wind auction timelines, and European F-Gas Regulation enforcement intensity for early signals. Forecasts reflect assumptions around regulatory deadline adherence and heavy-lift asset availability without contingency for abrupt commodity price spikes. Quarterly review of flag-state insurance mandate filings and classification society equipment audit backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Tele-Operated Marine Drone Market
Marine
India Boat Davits Market
Marine
Marine Communication Market
Marine
US Fish Finders Market
Marine
Marine Engines Market
Marine
Marine Asset Integrity Services Market
Marine
Marine Fuel Injector Market
Marine
Furnace Boats Market
Marine
Electric Ferry Market
Marine
Marine Shackle Market
Marine
Marine Diesel Engine Market
Marine
Marine Strip Market
Marine
LNG Bunkering Vessel Market
Marine
Trim Tabs Market
Marine
Global Marine Gearbox Market
Marine
Marine Fin Stabilizer Market