
 Clover Leaf Oil Market | 2026-2036
Clover Leaf Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Clover Leaf Oil Market Analytics
Pharmaceutical-grade certification is collapsing the gap between commodity distillates and premium therapeutic extracts. Young Living Essential Oils leverages proprietary seed-to-seal protocols to sustain North American distribution dominance. Biolandes anchors European supply through backward integration into wild clover harvesting cooperatives in France.
Clover leaf oil is a steam-distilled essential oil containing eugenol, methyl salicylate, and trace coumarins extracted from Trifolium pratense foliage, primarily functioning as a topical anti-inflammatory and fragrance fixative in cosmetic formulations. Cold pressed variants command premium positioning in clean-label cosmetics where heat-sensitive bioactives retain full therapeutic index, while refined grades dominate pharmaceutical compounding due to standardized eugenol concentrations and extended shelf stability. Aromatherapy applications represent the fastest-expanding consumption channel as wellness clinics and spa chains adopt clover leaf oil in diffusion protocols for stress-reduction therapies.
REACH registration requirements in Europe and FDA cosmetic ingredient labeling rules in the United States enforce disclosure of geographic sourcing and extraction solvent residues, compelling suppliers to rebuild documentation systems. Organic certification under USDA National Organic Program and EU Organic Regulation creates parallel supply tiers with divergent pricing structures and audit burdens. Stakeholders must monitor evolving allergen labeling mandates in multiple jurisdictions and pre-position compliant inventory before enforcement windows tighten.
Market Dynamics
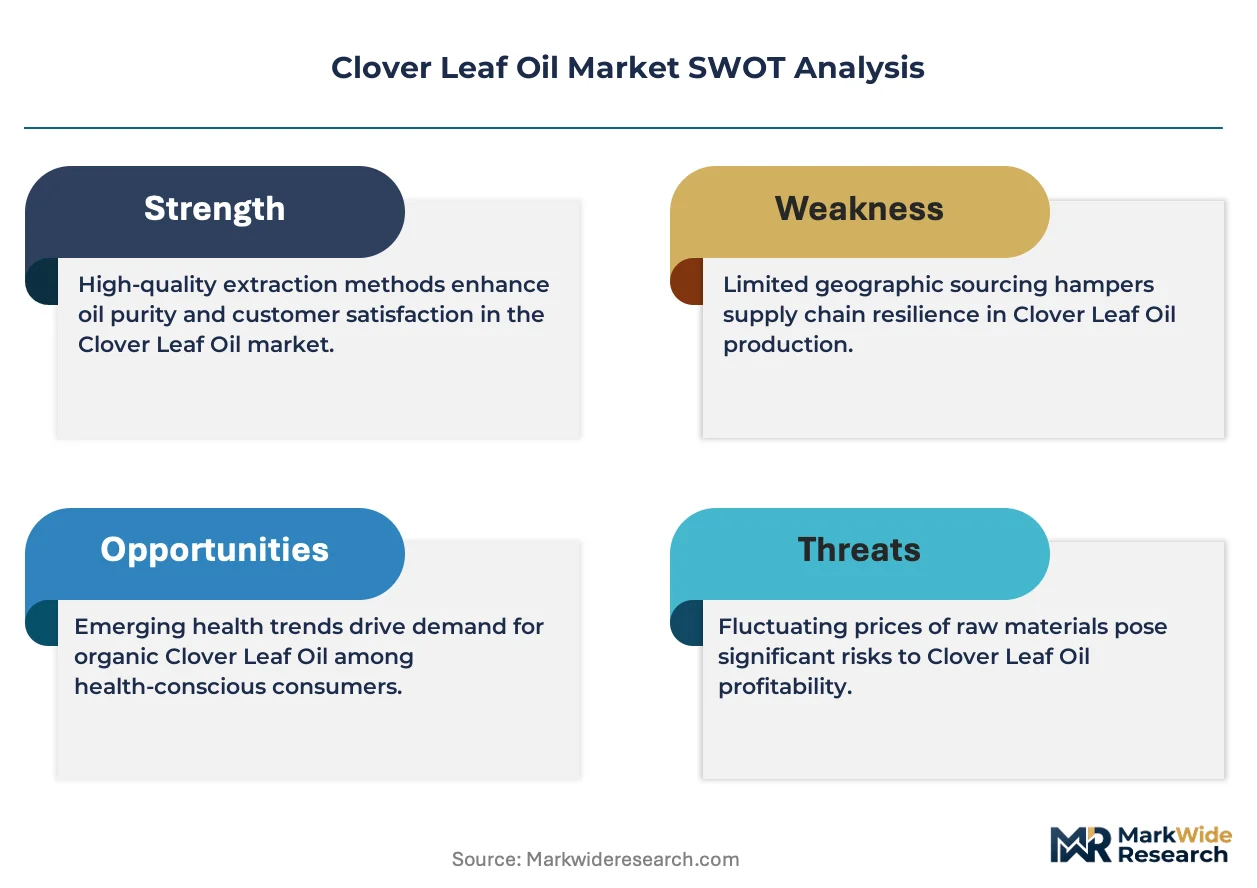
Pharmaceutical-grade certification requirements are compressing margins for commodity distillers while rewarding suppliers with traceable seed-to-seal documentation systems. REACH compliance deadlines and FDA cosmetic ingredient labeling rules are forcing documentation rebuilds across European and North American supply chains.
Growth Catalysts
- Aromatherapy protocol adoption:Wellness studios in France, Germany, and the United States are integrating clover leaf oil into diffusion-based stress-reduction therapies, expanding certified organic grade consumption.
- REACH registration mandates:ECHA disclosure requirements for geographic sourcing and solvent residues are accelerating supplier consolidation toward compliant documentation systems.
- Clean-label cosmetic formulation:Cold pressed variants with retained heat-sensitive bioactives are capturing premium positioning as formulators abandon heat-degraded alternatives.
Market Restraints
- Wild harvest supply concentration:French cooperative networks dominate raw material sourcing, creating geographic concentration risk for European processors.
- Eugenol standardization costs:Pharmaceutical compounding demands refined grades with standardized concentrations, requiring capital-intensive distillation infrastructure.
- Synthetic fragrance substitution:Methyl salicylate isolates from petrochemical sources compete on cost for non-therapeutic fragrance applications.
Strategic Opportunities
- USDA Organic Program certification:Parallel supply tiers with divergent audit burdens create pricing power for certified operators in North American distribution.
- Spa chain direct procurement:Wellness clinic networks are bypassing traditional distributors, creating channel innovation opportunities for traceable suppliers.
- EU Organic Regulation alignment:Pre-positioning compliant inventory ahead of enforcement window tightening captures premium positioning in European cosmetic formulation.
Industry Challenges
- Documentation system rebuilds:Suppliers face compressed timelines to install geographic sourcing traceability before REACH disclosure deadlines.
- Allergen labeling mandate fragmentation:Multiple jurisdiction requirements for coumarin disclosure create compliance complexity without harmonized standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clover Leaf Oil Market |
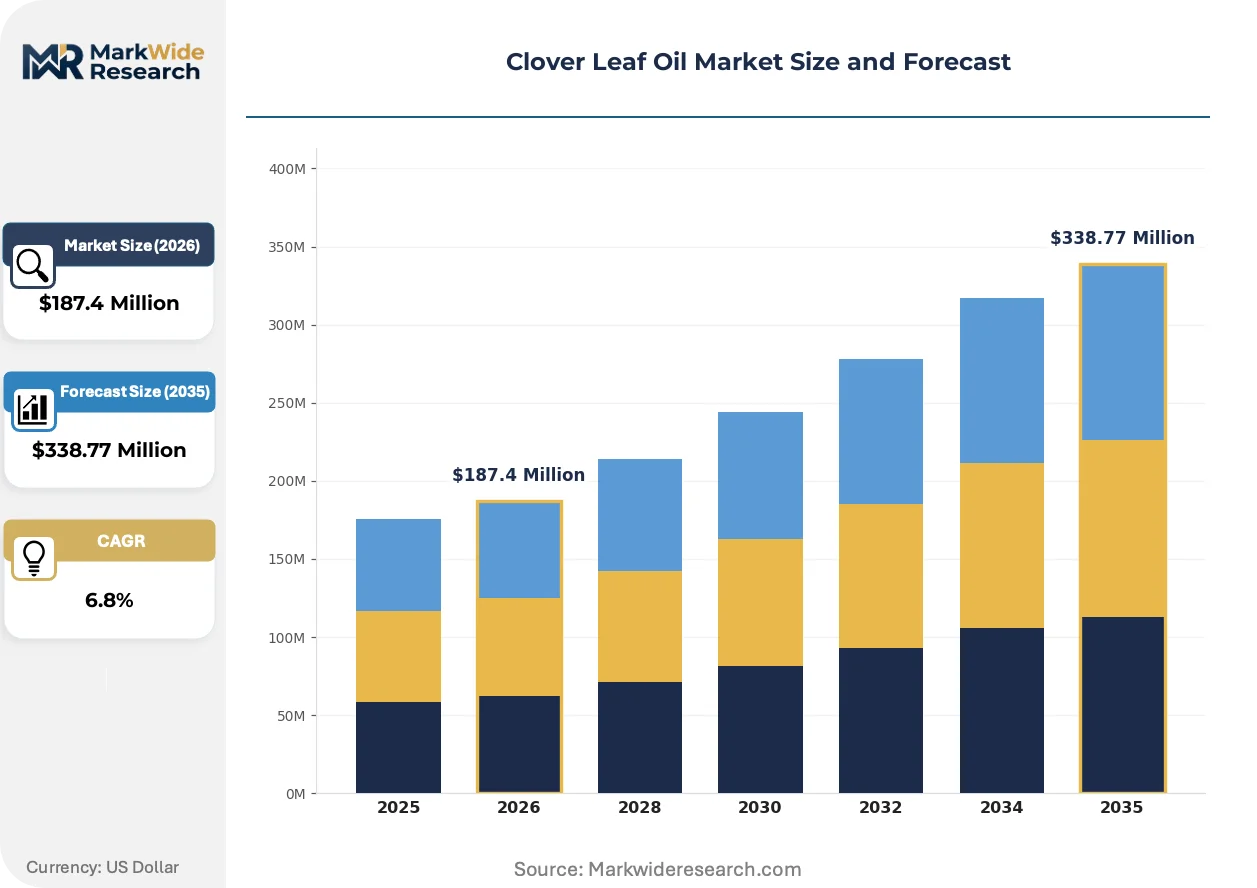
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Pressed, Refined, Organic, Natural Application: Cosmetics, Food Industry, Pharmaceuticals, Aromatherapy End User: Manufacturers, Retailers, Distributors, Consumers Packaging Type: Bottles, Drums, Pouches, Bulk |
| Companies Covered | IL Health & Beauty Natural Oils, Shaanxi Guanjie Technology, Plant Therapy Essential Oils, Greenleaf Extractions, Young Living Essential Oils, Green Fields Oil Factory, Aksuvital, Biolandes, Aromaaz International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clover Leaf Oil Market Evolving Landscape
Extraction technology evolution and regulatory disclosure mandates are restructuring competitive advantage around documentation depth rather than volume scale. Suppliers are racing to deploy traceability systems before compliance windows tighten.
Supercritical CO2 extraction is supplanting conventional steam distillation for premium therapeutic grades. Cosmetic formulators in France and Germany are adopting CO2 extracts at accelerating pace to preserve full bioactive profiles. This technology is supplanting heat-dependent methods in clean-label segments where therapeutic index retention commands price premiums.
REACH registration requirements are forcing disclosure of extraction solvent residues and geographic sourcing coordinates. European suppliers must rebuild documentation systems to maintain market access. Cosmetic formulators in Germany face the steepest compliance burden as ECHA enforcement intensifies for botanical imports.
Direct contracting between wellness clinic chains and certified organic suppliers is compressing traditional distributor margins. Spa networks in the United States are establishing captive supply relationships with traceable harvest cooperatives. France exhibits the most advanced clinic-direct procurement models, with Biolandes-style backward integration becoming the reference architecture.
Clover Leaf Oil Market Segmentation
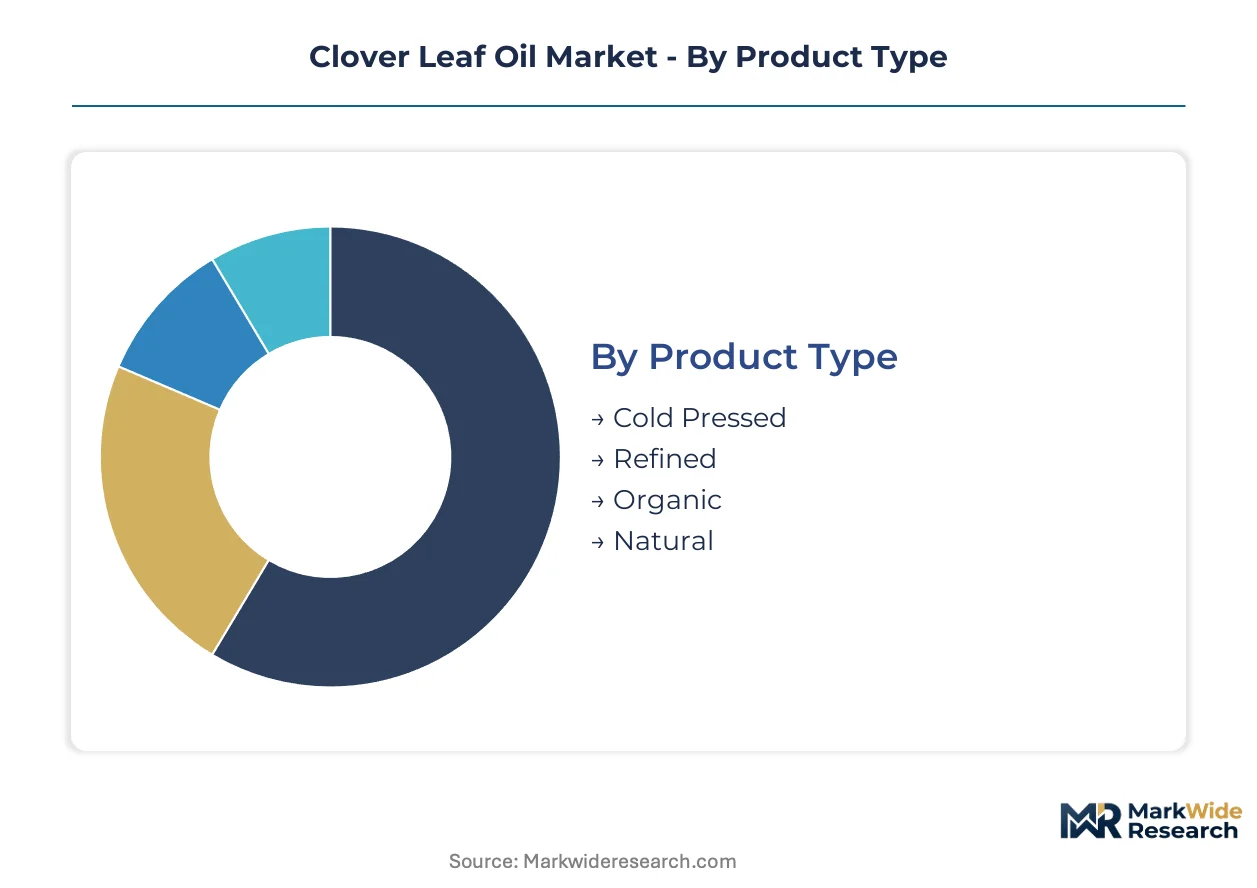
Clover leaf oil segmentation reflects divergent extraction technologies, regulatory compliance tiers, and end-use specifications that reshape procurement patterns across wellness, pharmaceutical, and cosmetic channels. Channel mix varies sharply by segment, with aromatherapy clinics sourcing certified organic grades direct from harvest cooperatives while pharmaceutical compounders rely on refined grades through established distributors.
Product Type:
Cold pressed and refined grades dominate divergent channel architectures, with wellness studios and cosmetic formulators pursuing distinct procurement pathways based on heat sensitivity requirements and certification thresholds.
- Cold Pressed:Heat-free mechanical extraction preserves methyl salicylate and eugenol integrity for therapeutic-grade applications. Wellness studios in France and Germany source directly from certified organic cooperatives, bypassing traditional distributors to secure full bioactive retention for diffusion protocols.
- Refined:Standardized distillation yields consistent eugenol concentrations for pharmaceutical compounding. FDA cosmetic ingredient labeling rules and REACH registration mandates compel processors to maintain exhaustive solvent residue documentation, concentrating supply among ECHA-compliant European operators.
- Organic:USDA National Organic Program and EU Organic Regulation certification creates parallel audit-intensive supply tiers with premium positioning in North American and European cosmetic formulation.
- Natural:Unspecified extraction methods serve cost-sensitive fragrance applications where synthetic methyl salicylate isolates exert pricing pressure.
By volume, refined grades lead through pharmaceutical distributor networks. By growth pace, cold pressed variants are expanding most quickly as clean-label cosmetic formulators abandon heat-degraded alternatives.
Application:
End-use concentration determines margin structure, with therapeutic applications commanding certification premiums while industrial fragrance usage competes on cost against petrochemical substitutes.
- Cosmetics:Fragrance fixative and topical anti-inflammatory functions in premium skincare formulations. REACH compliance deadlines in Germany and France drive formulators toward traceable botanical supply chains with disclosed geographic sourcing coordinates.
- Pharmaceuticals:Standardized eugenol concentrations for topical anti-inflammatory compounding. FDA labeling rules enforce disclosure of extraction solvent residues, favoring suppliers with rebuilt documentation systems.
- Aromatherapy:Diffusion-based stress-reduction therapies in wellness clinic chains represent the steepest expansion trajectory as spa networks in the United States establish captive supply relationships with traceable harvest cooperatives.
- Food Industry:Limited flavoring applications face intense regulatory scrutiny from EFSA and national food safety authorities, constraining volume relative to cosmetic and therapeutic channels.
Cosmetics generates the largest absolute revenue pool. Aromatherapy climbs the fastest as clinic-direct procurement models compress traditional distributor margins.
End User:
Procurement authority concentration varies by scale, with manufacturer consolidation contrasting against fragmented retail and consumer channels.
- Manufacturers:Pharmaceutical and cosmetic compounders with volume purchasing power and stringent certification requirements. ECHA enforcement intensification in Germany concentrates procurement among REACH-registered suppliers.
- Retailers:Specialty wellness and natural product stores curating certified organic assortments for consumer self-care segments.
- Distributors:Traditional intermediaries facing margin compression as spa chains and wellness clinics adopt direct procurement from traceable harvest cooperatives.
- Consumers:Individual aromatherapy practitioners and home-use purchasers through e-commerce channels with limited quality verification mechanisms.
Manufacturers dominate procurement value. Distributors are losing share fastest to direct contracting models.
Packaging Type:
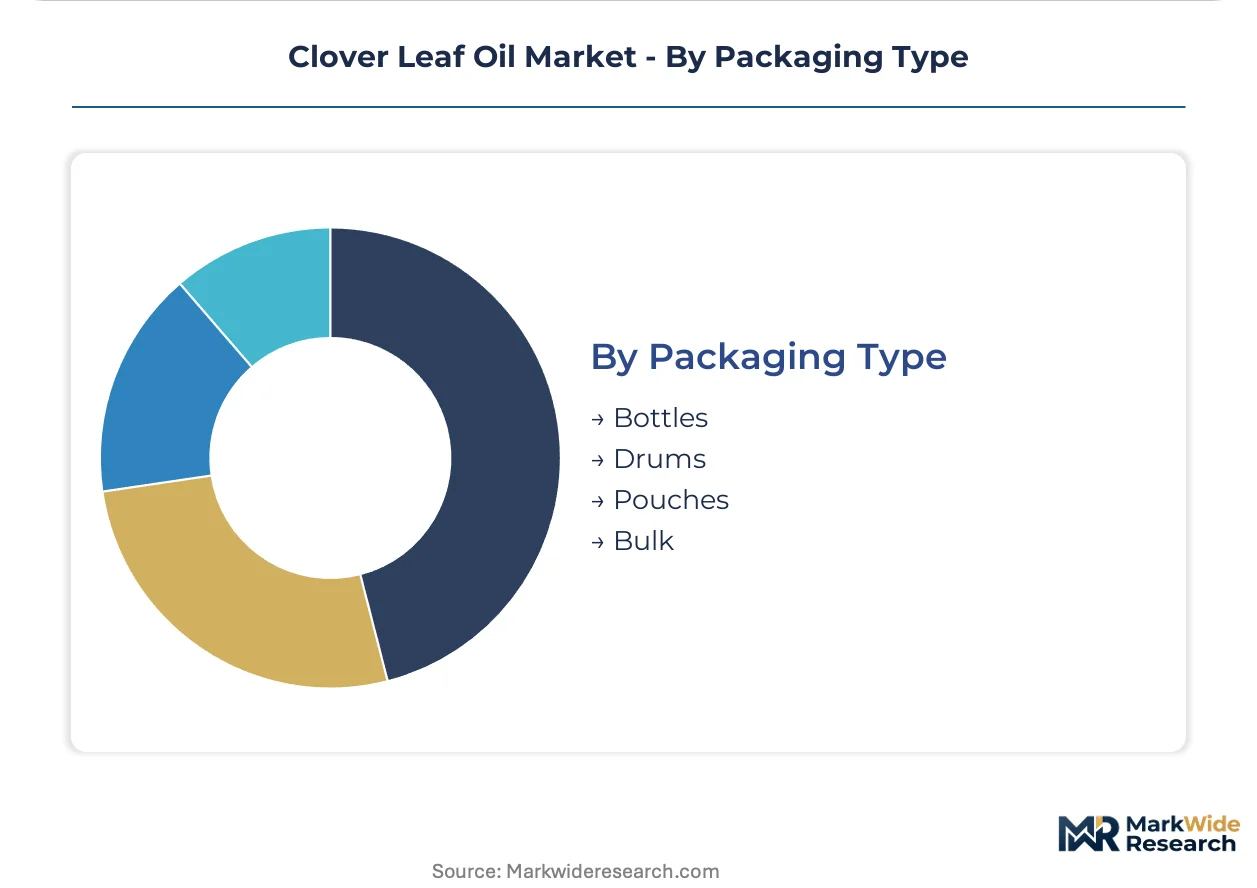
Packaging configuration aligns with end-use scale and shelf stability requirements, from individual practitioner quantities to industrial pharmaceutical volumes.
- Bottles:Small-format retail packaging for consumer and practitioner aromatherapy use with UV-protective glass specifications.
- Drums:Intermediate bulk containers for cosmetic manufacturer formulation batches requiring controlled atmosphere storage.
- Pouches:Flexible retail formats for sample distribution and travel-size wellness product lines.
- Bulk:Tanker and tote configurations for pharmaceutical compounders with standardized eugenol concentration requirements and extended shelf stability protocols.
Bulk shipments dominate pharmaceutical channel volume. Bottles gain share fastest through wellness clinic retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wild clover harvesting cooperatives in France concentrate raw material supply for European processors, while certified organic certification programs in North America and Asia-Pacific expand procurement alternatives for wellness clinic chains.
France
Aromatherapy diffusion protocols in Paris and Lyon wellness studios drive certified organic grade consumption. ECHA REACH registration mandates enforce disclosure of geographic sourcing coordinates for all botanical imports. Biolandes anchors supply through backward integration into wild clover harvesting cooperatives in Provence-Alpes-Côte d'Azur.
Germany
Cosmetic formulators in Hamburg and Frankfurt seek traceable supply chains with full solvent residue documentation. ECHA enforcement intensifies for botanical imports, compelling documentation system rebuilds. The Baden-Württemberg cluster concentrates pharmaceutical-grade refining capacity for standardized eugenol production.
United States
Spa chains in California and New York establish captive supply relationships with traceable harvest cooperatives. FDA cosmetic ingredient labeling rules enforce disclosure of extraction methods and geographic origins. The Pacific Northwest hosts expanding organic certification capacity under USDA National Organic Program standards.
China
Shaanxi Province extraction facilities supply refined grades for pharmaceutical compounding across Asia-Pacific. GB standards for essential oil quality create domestic compliance thresholds for export-oriented processors. The Yangtze River Delta concentrates clean-label cosmetic formulation demand for cold pressed variants.
India
Ayurvedic wellness centers in Maharashtra and Karnataka integrate clover leaf oil into traditional stress-reduction therapies. FSSAI scrutiny of botanical ingredient safety creates regulatory friction for food industry applications. Gujarat hosts expanding steam-distillation capacity serving both domestic and export markets.
Clover Leaf Oil Market Competitive Landscape
Concentration sits with vertically integrated harvest cooperatives and certified organic specialists. The vendor base spans multinational essential oil houses, regional extraction facilities, and wellness brand captive supply operations. Three archetypes dominate: seed-to-seal protocol operators, backward-integrated harvest networks, and pharmaceutical-grade refiners. Competitive moves center on documentation system deployment ahead of REACH deadlines and direct contracting with spa chain networks.
Within the seed-to-seal protocol tier, Young Living Essential Oils and Plant Therapy Essential Oils exemplify North American operators building traceable supply architectures. Biolandes occupies a position among European harvest-integrated specialists with cooperative network control. Shaanxi Guanjie Technology represents Chinese extraction capacity serving pharmaceutical standardization requirements.
| Leading Market Players |
|---|
| IL Health & Beauty Natural Oils |
| Shaanxi Guanjie Technology |
| Plant Therapy Essential Oils |
| Greenleaf Extractions |
| Young Living Essential Oils |
| Green Fields Oil Factory |
| Aksuvital |
| Biolandes |
| Aromaaz International |
| Others |
Value Network & Pricing Analysis
REACH registration requirements gate both supply qualification and price differentiation simultaneously, compelling European processors to rebuild documentation systems while certified organic tiers capture premium positioning in wellness and cosmetic channels.
Pricing Analysis
REACH dictates the pricing tier structure across European distribution, separating ECHA-registered suppliers from non-compliant distillers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence and solvent residue documentation depth. Cost compression in commodity distillates is intensifying because synthetic methyl salicylate isolates exert substitution pressure. Pharmaceutical compounders show least price sensitivity due to eugenol standardization mandates, while fragrance formulators exhibit highest elasticity to petrochemical alternatives.
Supply Chain Analysis
France and China anchor wild clover harvesting and extraction capacity respectively, with Provence-Alpes-Côte d'Azur cooperatives supplying raw biomass to European refiners and Shaanxi Province facilities serving Asia-Pacific pharmaceutical standardization. Trifolium pratense foliage, steam distillation infrastructure, and CO2 extraction equipment constitute critical input dependencies. Single-source vulnerability concentrates in French cooperative networks controlling premium organic biomass. Distribution runs through wellness clinic direct procurement, pharmaceutical distributor networks, and cosmetic formulator long-term contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification audit services and traceability documentation subscriptions expand faster than raw oil extraction, creating recurring revenue layers that outperform commodity volume growth.
For Market Incumbents: Shield market position through captive supply relationships with harvest cooperatives and preemptive USDA Organic Program certification investment. Synthetic fragrance substitution and ECHA enforcement intensification threaten commodity distillers with margin collapse. Backward integration into Provence-Alpes-Côte d'Azur wild clover networks secures biomass access before consolidation accelerates. For New Entrants and Emerging Players: Anchor in aromatherapy clinic direct procurement channels where traceability premiums exceed distributor-served cosmetics. Spa chain networks in California and New York represent the most penetrable white space. Seed-to-seal protocol marketing with disclosed geographic sourcing coordinates provides differentiated go-to-market positioning against established essential oil houses. For Investors and Strategic Acquirers: EU Organic Regulation enforcement window tightening reshapes the acquisition landscape toward documentation-compliant operators with installed audit systems. Five-to-ten year viability favors backward-integrated harvest networks over standalone refiners facing REACH compliance rebuild costs. Monitor ECHA disclosure deadline adherence as inflection indicator for supplier distress opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Harvest Cooperatives | Provence-Alpes-Côte d'Azur cooperative control secures premium organic biomass access before consolidation. |
| Supercritical CO2 Extraction Capacity Addition | Baden-Württemberg pharmaceutical cluster demands full bioactive retention for therapeutic-grade output. |
| REACH Documentation System Deployment | ECHA compliance deadlines force supplier consolidation toward traceable geographic sourcing architectures. |
| Direct Spa Chain Procurement Contracts | Wellness clinic networks in California bypass distributors, compressing traditional channel margins. |
| USDA Organic Program Certification Investment | Pacific Northwest certification capacity expansion captures North American clean-label cosmetic demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across wellness clinic procurement directors, cosmetic formulator R&D leads, pharmaceutical compounding supervisors, essential oil distributor account managers, and wild clover harvest cooperative coordinators. Secondary validation drew from ECHA REACH registration databases, FDA cosmetic ingredient labeling guidance, USDA National Organic Program audit records, EU Organic Regulation compliance filings, and customs trade flow data. Bottom-up volume triangulation against top-down value estimation anchored forecast robustness.
Across the analysis window, projections reflect segmented modeling across extraction technology type, certification tier, end-use application, and geographic regulatory cluster. CAGRs were derived from slope-log regression on normalized volume trajectories. Forecast inputs incorporated aromatherapy clinic network expansion rates, ECHA enforcement intensity indices, and synthetic methyl salicylate price elasticity estimates.
Material uncertainties — regulatory deadline delays, harvest yield volatility from climate stress, and synthetic substitute cost breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these exogenous triggers. Recalibration cycles align with material shifts in ECHA enforcement patterns and wellness clinic procurement model adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
Asia-Pacific Rapeseed Oil Market
Agriculture and Agri Products
Bee Pollen Market
Agriculture and Agri Products
Japan Animal Protein Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Organic Soymeal Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
Italy Animal Protein Market
Agriculture and Agri Products
India Agriculture Market