
 Guarana Market | 2026-2036
Guarana Market Size, Share, and Industry Trends Forecast 2026-2036
Guarana Market Analysis
Project finance for smallholder cooperatives is fragmenting competitive entry barriers in guarana supply chains. Ambev leverages its captive Amazon sourcing network to secure volume commitments from indigenous collectors. Prover Brasil anchors its position through specialized extract purification capabilities that command premium positioning in European nutraceutical channels. Nutra Green Biotechnology Co., Ltd. competes on backward integration into seed cultivation, reducing raw material cost volatility for its capsule and powder lines.
Guarana refers to the dried seed of Paullinia cupana, a climbing plant native to the Amazon basin containing caffeine, theobromine, and tannin complexes typically standardized at 10-22% caffeine content for commercial extracts. The seed undergoes roasting, milling, and solvent or supercritical CO2 extraction to produce ingredients for stimulant and weight-management formulations. Powder and extract categories dominate current revenue, with extract grades capturing disproportionate margin pools due to pharmaceutical and cosmetics-grade certification requirements. Beverages represent the fastest-expanding application segment, driven by energy drink and functional soda reformulations targeting health-conscious general consumers.
Brazil's ANVISA oversees botanical ingredient safety assessments and Good Manufacturing Practice enforcement for domestic guarana processors. The European Union's EFSA novel food and health claims frameworks determine market access for extract suppliers seeking positioning in nutrition supplements and functional drinks across member states. ECHA REACH compliance obligations for imported botanical extracts further filter supplier eligibility in European cosmetics and pharmaceutical channels. Stakeholders must monitor evolving caffeine content disclosure mandates and synthetic additive substitution incentives, as these regulatory trajectories will determine which extraction technologies and certification investments yield durable competitive advantage.
Market Dynamics
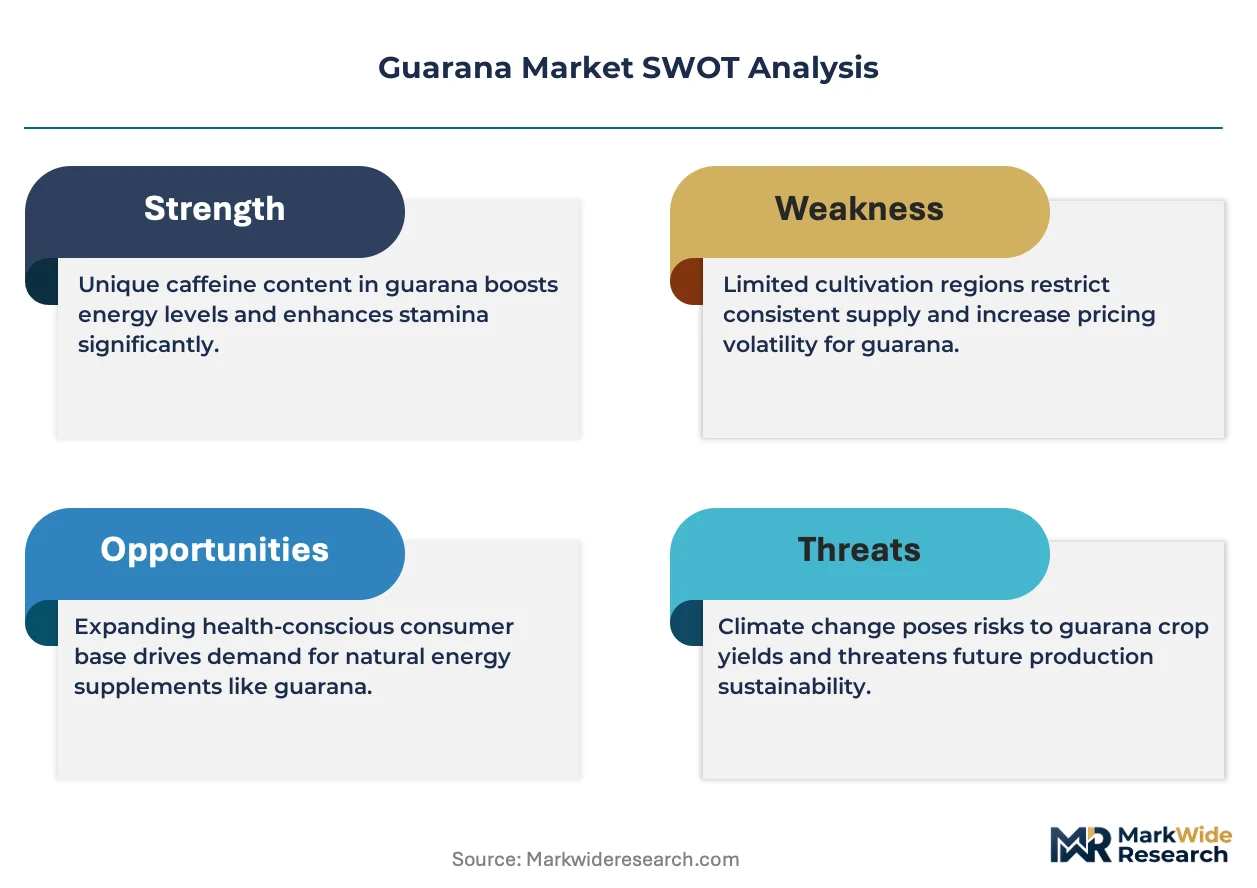
Clean-label formulation mandates across beverage and nutraceutical channels are compressing synthetic caffeine substitution timelines, forcing extract suppliers to accelerate certification investments and captive sourcing arrangements.
Growth Catalysts
- EFSA Novel Food Framework:Streamlined safety assessments for Paullinia cupana extracts are accelerating European market entry for certified Brazilian suppliers, displacing unverified botanical imports.
- Energy Drink Reformulation:Major beverage manufacturers in Brazil and Germany are replacing synthetic caffeine with standardized guarana seed extracts to meet clean-label positioning requirements.
- Amazonas Processing Clusters:Concentrated roasting and milling infrastructure near Manaus is reducing logistics costs for export-oriented extract producers serving pharmaceutical-grade buyers.
Market Restraints
- Seed Price Volatility:Rainfall irregularity in Roraima and Pará collection zones creates raw material cost swings that compress margins for non-integrated processors.
- ECHA REACH Compliance Burden:European cosmetics and pharmaceutical channel entry requires toxicological dossier investments that filter out small-scale extract suppliers lacking regulatory capital.
- Synthetic Caffeine Cost Advantage:Laboratory-produced caffeine from Chinese chemical manufacturers maintains a 40-60% price discount versus natural extracts, limiting penetration in cost-sensitive beverage segments.
Strategic Opportunities
- India Nutraceutical Expansion:FSSAI's evolving botanical ingredient standards and rising functional beverage consumption in Mumbai and Bangalore create first-mover positioning for certified extract suppliers.
- Supercritical CO2 Extraction Convergence:Combination of precision caffeine standardization with solvent-free processing is unlocking pharmaceutical-grade certification premiums previously captured by synthetic suppliers.
- Direct-to-Brand Sourcing Platforms:Digital procurement channels connecting Amazon cooperatives with European nutraceutical formulators are compressing traditional trader margins and capturing traceability premiums.
Industry Challenges
- Phytochemical Standardization Expertise Gap:Consistent theobromine and tannin profiling requires analytical chemistry capabilities scarce among traditional seed processors, forcing reliance on third-party testing.
- Organic Certification Timeline Compression:IFOAM and USDA Organic conversion periods of 24-36 months delay premium positioning for cooperatives transitioning from conventional collection practices.
- Indigenous Knowledge Documentation Requirements:Nagoya Protocol compliance for benefit-sharing agreements with Amazon collectors adds legal complexity and negotiation friction to sourcing contracts.
Report Scope
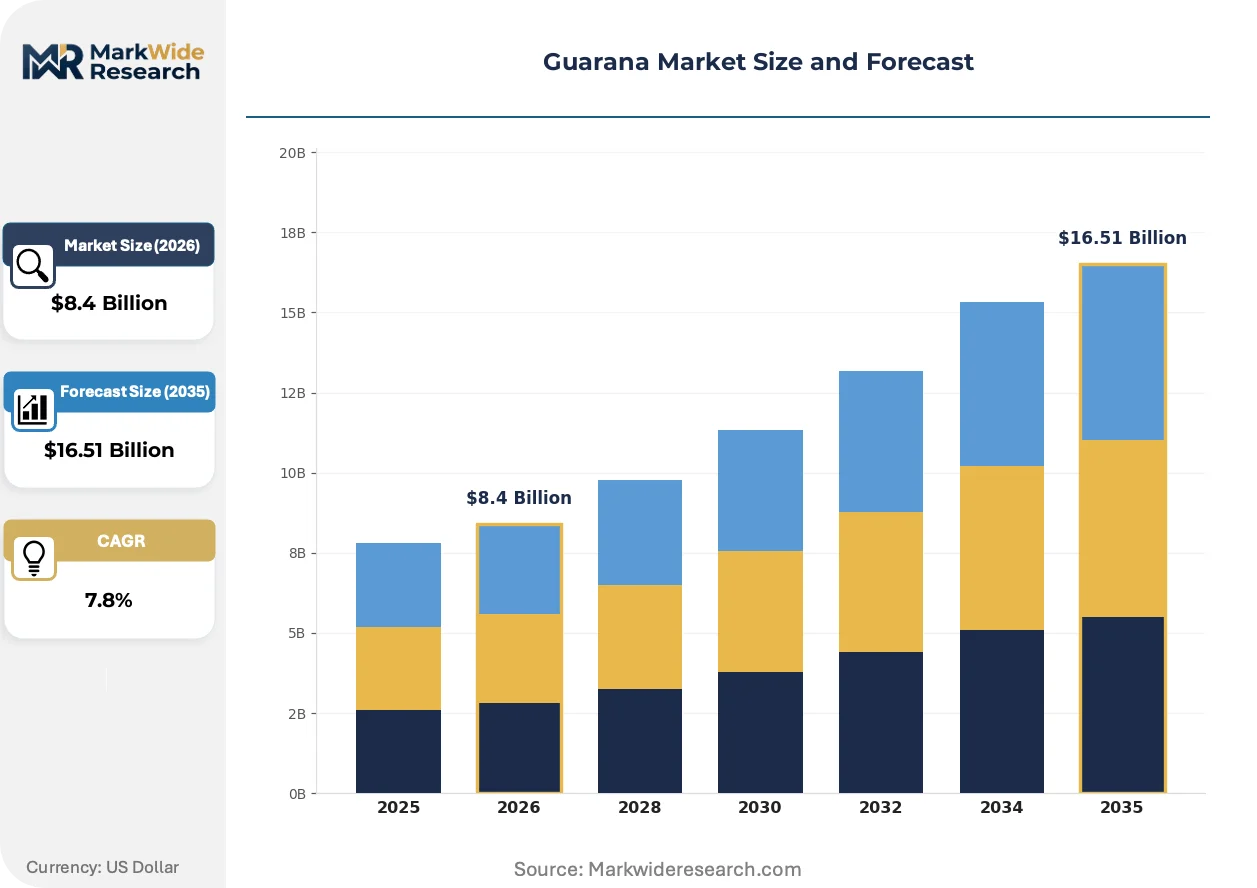
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guarana Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Extract, Capsules, Beverages Application: Nutrition Supplements, Functional Drinks, Cosmetics, Pharmaceuticals End User: Health Enthusiasts, Athletes, General Consumers, Manufacturers Distribution Channel: Online Retail, Health Stores, Supermarkets, Specialty Stores |
| Companies Covered | Iris Trade Inc., Vitaspice, Ambev, Nutra Green Biotechnology Co., Ltd., Prover Brasil, Duas Rodas Industrial, The Green Labs LLC, Natural Amazon Herbs Producao De Extratos Ltd, Herboflora, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guarana Market Emerging Trajectories
Extraction technology maturation and regulatory disclosure tightening are converging to reward suppliers with verifiable supply chain control and precision standardization capabilities.
Supercritical CO2 extraction systems are digitizing quality control workflows through integrated spectroscopic monitoring that delivers real-time caffeine content verification. Pharmaceutical and cosmetics-grade buyers in Germany and Switzerland are mandating this technology for new supplier qualification, compressing the viable vendor pool to equipment-capitalized processors. The shift is digitizing batch-to-batch consistency guarantees that previously required extensive laboratory validation.
EFSA's evolving caffeine labeling requirements and health claims scrutiny are forcing extract suppliers to invest in clinical substantiation dossiers. The regulatory pressure is restructuring competitive positioning toward suppliers with documented safety profiles and standardized polyphenol matrices. European functional beverage and supplement manufacturers are responding by consolidating procurement around ANVISA-registered Brazilian processors with existing EFSA novel food approvals.
Brand-direct sourcing contracts are replacing traditional trader-mediated procurement for premium extract grades. Nutraceutical formulators in France and the Netherlands are establishing multi-year volume commitments with specific Amazon cooperatives, bypassing São Paulo-based intermediaries. This disintermediation is most visible in certified organic and fair-trade segments where traceability commands measurable price premiums over conventional supply.
Guarana Market Segmentation
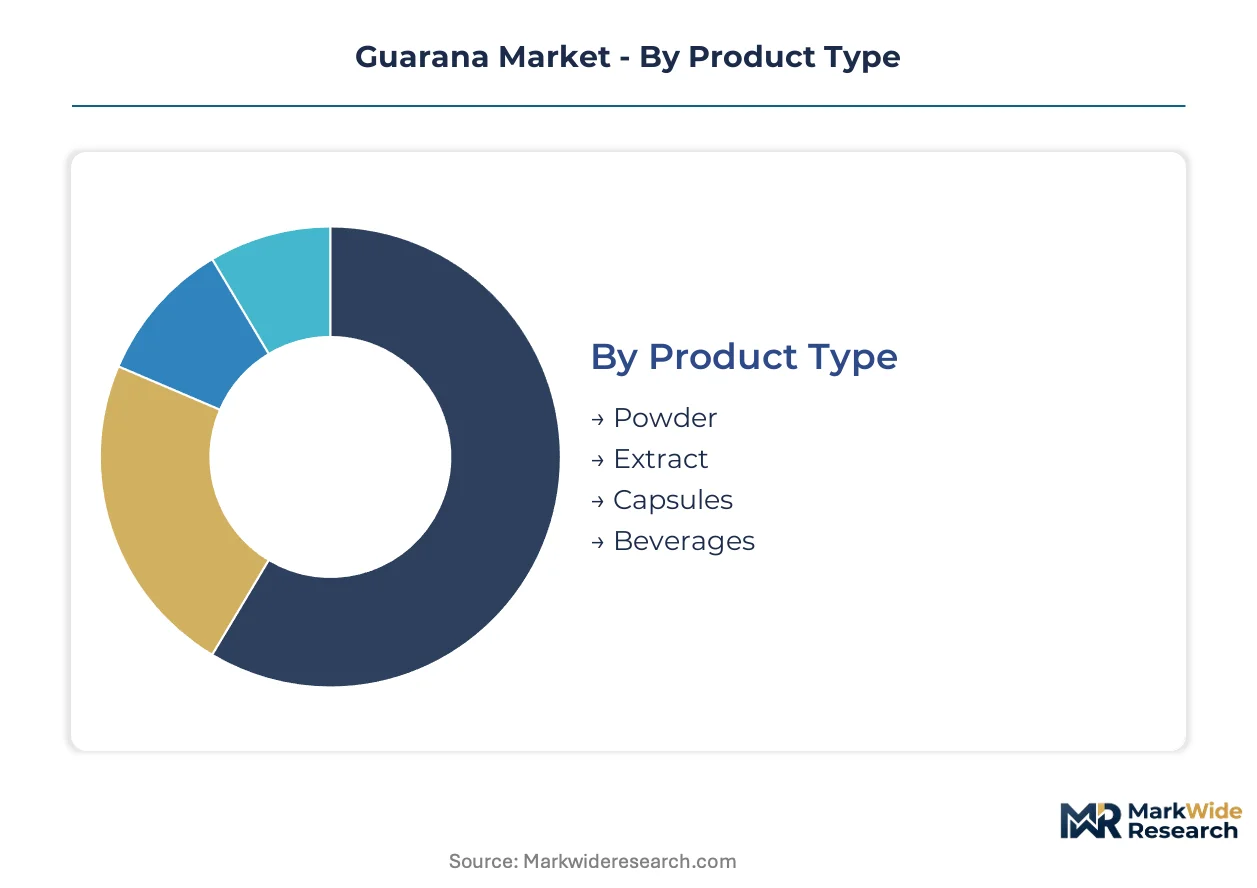
Guarana's commercial architecture splits across four intersecting dimensions that determine margin capture and regulatory exposure. Product form dictates extraction investment requirements, while application channels filter suppliers through divergent certification barriers. End-user sophistication and distribution reach complete the value chain topology.
Product Type:
Mature commodity formats coexist with emerging precision-extraction grades in a bifurcated supply structure.
- Powder:Roasted and milled seed material typically standardized at 10-12% caffeine content through basic processing. Demand concentrates in Brazilian domestic beverage manufacturing and cost-sensitive nutraceutical blending where ANVISA registration suffices for market access.
- Extract:Solvent or supercritical CO2-derived concentrates achieving 22% caffeine standardization with controlled theobromine and tannin profiles. European pharmaceutical and cosmetics manufacturers in Germany and Switzerland mandate this grade for ECHA REACH compliance and EFSA novel food positioning.
- Capsules:Encapsulated powder or extract formulations serving direct-to-consumer supplement channels with dosage precision requirements.
- Beverages:Ready-to-drink functional formulations incorporating guarana as primary or secondary stimulant source.
Extract handles the majority of throughput; Beverages is the fastest mover on share.
Application:
Regulatory stringency escalates sharply from food-grade functional positioning toward pharmaceutical dossier requirements.
- Nutrition Supplements:Capsule, tablet, and powder formulations targeting energy and weight management positioning. EFSA health claims scrutiny is forcing clinical substantiation investments that filter supplier pools toward ANVISA-registered Brazilian processors with existing novel food approvals.
- Functional Drinks:Energy beverages and reformulated sodas replacing synthetic caffeine with natural alternatives. Major manufacturers in Brazil and Germany are accelerating procurement from certified extract suppliers to meet clean-label mandates.
- Cosmetics:Topical formulations leveraging guarana's stimulant and astringent properties for cellulite and skin firming applications.
- Pharmaceuticals:Prescription and over-the-counter stimulant formulations requiring full toxicological dossiers under EMA and national pharmaceutical regulator frameworks.
Functional Drinks dominates volume flows; Pharmaceuticals commands the steepest margin expansion trajectory.
End User:
Customer sophistication spans from ingredient-agnostic mass consumers to specification-driven industrial buyers.
- Health Enthusiasts:Premium-positioned consumers prioritizing organic certification and Amazon traceability in supplement procurement.
- Athletes:Performance-oriented users seeking standardized caffeine dosing with batch-tested purity guarantees.
- General Consumers:Mass-market beverage drinkers responding to clean-label positioning without ingredient-level scrutiny.
- Manufacturers:Industrial formulators in nutraceutical, cosmetic, and pharmaceutical channels with binding specification requirements and audit obligations.
Manufacturers controls procurement volume; Health Enthusiasts is gaining share fastest on traceability premiums.
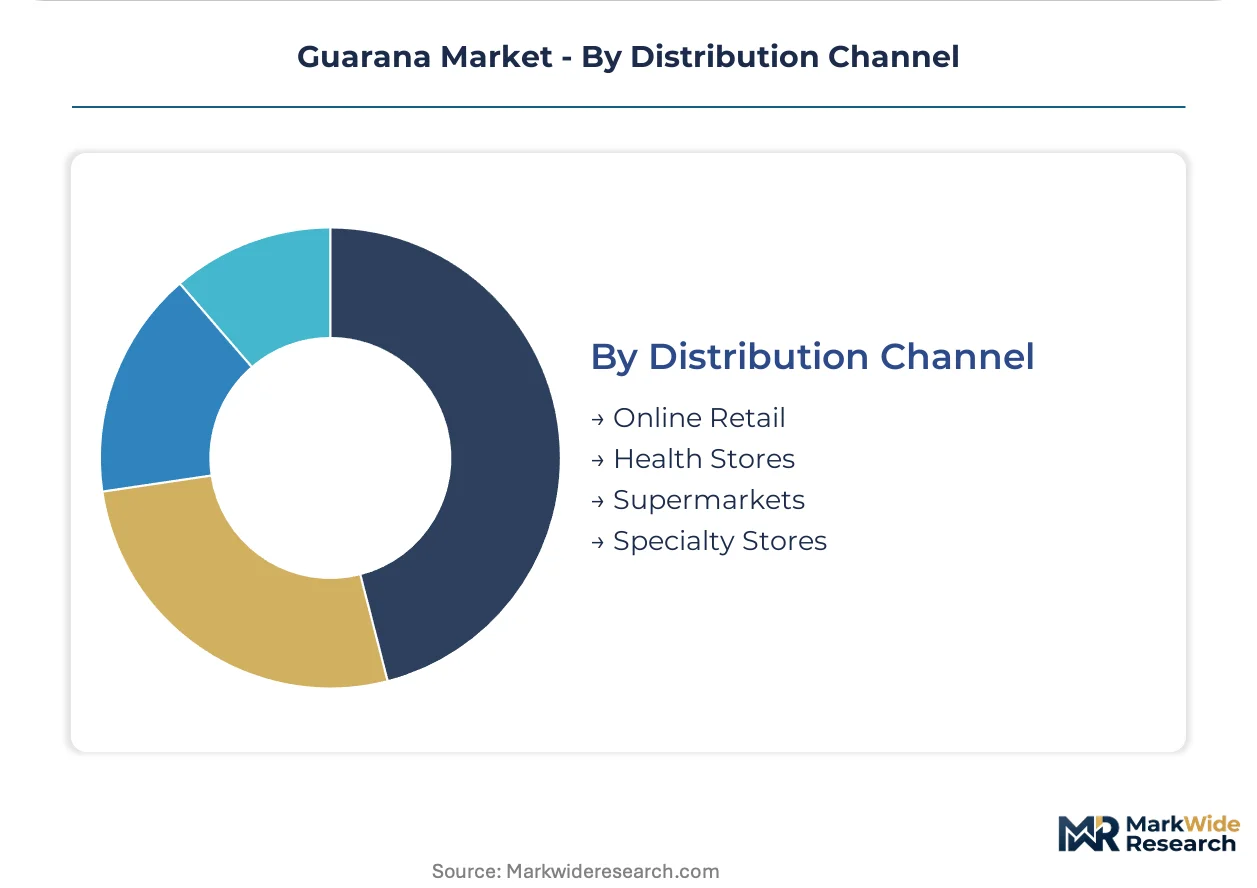
Distribution Channel:
Channel economics fragment between disintermediated digital procurement and relationship-dependent specialty retail.
- Online Retail:Direct-to-consumer platforms and B2B marketplaces compressing traditional trader margins. Digital procurement channels connecting Amazon cooperatives with European formulators are capturing traceability premiums previously absorbed by São Paulo intermediaries.
- Health Stores:Specialty retailers curating certified organic and fair-trade SKUs with staff-assisted consultation.
- Supermarkets:Mass-market beverage and supplement placement requiring scale supply commitments and promotional investment.
- Specialty Stores:Cosmetics and pharmaceutical dispensaries with trained personnel and regulatory compliance verification.
Online Retail is expanding most quickly; Health Stores maintains margin leadership on certified product positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious beverage formulators in Germany and clean-label supplement manufacturers in Brazil drive procurement concentration. ANVISA-registered processors and EFSA-certified extract suppliers command premium positioning. Industrial buyers prioritize traceability from Amazon collection zones to European pharmaceutical channels.
Brazil
Ambev and domestic beverage giants source raw seed from Amazonas state cooperatives near Manaus. ANVISA enforces Good Manufacturing Practice standards for botanical ingredient processors. Roasting and milling clusters in Manaus export pharmaceutical-grade extracts to European nutraceutical buyers under EFSA novel food frameworks.
Germany
Energy drink reformulators at major beverage manufacturers substitute synthetic caffeine with standardized guarana extracts. EFSA health claims scrutiny and ECHA REACH compliance filter supplier eligibility toward certified Brazilian processors. Hamburg and Munich serve as distribution hubs for pharmaceutical-grade extracts entering cosmetics and supplement channels.
United States
FDA dietary supplement regulations and FTC advertising enforcement shape demand for certified organic extracts in energy and weight-management positioning. Health enthusiasts in California and New York Metro prioritize Amazon traceability and organic certification. Direct-to-brand digital procurement platforms compress traditional importer margins.
India
FSSAI's evolving botanical ingredient standards create first-mover positioning for certified extract suppliers in Mumbai and Bangalore functional beverage markets. Domestic nutraceutical manufacturers seek ANVISA-registered Brazilian partners for novel food compliance. Import channel development concentrates in Maharashtra and Karnataka processing hubs.
Switzerland
Swissmedic pharmaceutical-grade requirements and cosmetics manufacturers in Basel and Zurich mandate supercritical CO2 extraction certification. Precision caffeine standardization commands premium pricing over solvent-based alternatives. Swiss buyers consolidate procurement around digitized batch-to-batch consistency guarantees from equipment-capitalized Brazilian processors.
Guarana Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a bifurcated supply structure. Beverage manufacturers with captive Amazon sourcing networks secure volume commitments from indigenous collectors, while extract specialists command pharmaceutical-grade certification premiums. Three archetypes dominate: integrated beverage conglomerates with backward supply control, purification-focused extract processors, and biotechnology-backed capsule manufacturers. Competitive moves center on certification investments for EFSA and ECHA compliance, plus direct-to-brand digital procurement platform development.
Among Brazil-based processors, Ambev and Prover Brasil exemplify divergent strategic positions. Ambev anchors the integrated beverage archetype through captive Amazon sourcing networks. Prover Brasil occupies the extract-specialist tier with purification capabilities targeting European nutraceutical channels. Nutra Green Biotechnology Co., Ltd. represents the biotechnology-integrated archetype, with Chinese manufacturing structure and backward seed cultivation control. Duas Rodas Industrial and The Green Labs LLC sit within the mid-tier extract processing segment, while Iris Trade Inc. and Vitaspice exemplify trading and distribution-focused positioning.
| Leading Market Players |
|---|
| Iris Trade Inc. |
| Vitaspice |
| Ambev |
| Nutra Green Biotechnology Co., Ltd. |
| Prover Brasil |
| Duas Rodas Industrial |
| The Green Labs LLC |
| Natural Amazon Herbs Producao De Extratos Ltd |
| Herboflora |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Amazonas state roasting clusters is forcing extract processors to absorb seed price volatility while defending contract margins, compressing working capital cycles and accelerating supplier consolidation toward integrated beverage networks.
Pricing Analysis
Certification level creates the primary spread across guarana extract tiers, with EFSA novel food approval and ECHA REACH compliance commanding substantial premiums over ANVISA-registered grades. Three-tier pricing structure separates pharmaceutical-grade supercritical CO2 extracts from solvent-based nutraceutical grades and commodity powder, with synthetic caffeine from Chinese manufacturers applying persistent downward pressure on natural extract positioning in cost-sensitive beverage formulations. Brand-direct procurement contracts are compressing traditional trader margins, while health enthusiasts demonstrate lowest price sensitivity due to traceability premiums.
Supply Chain Analysis
Extended payment terms from European nutraceutical formulators are straining Amazon cooperative liquidity, forcing reliance on São Paulo-based trade finance facilities. Supply concentrates in Brazil's Amazonas state, with secondary processing clusters in Germany and Switzerland serving pharmaceutical-grade buyers. Raw material flows draw from Roraima and Pará collection zones, with caffeine-rich seed varieties and organic-certified harvests commanding priority allocation. Single-source vulnerability around Manaus logistics infrastructure creates concentration risk, while distribution runs through digital procurement platforms disintermediating traditional trader networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EFSA novel food dossiers and ANVISA GMP certification creates durable defensive moats for incumbent extract processors, as switching costs for pharmaceutical and cosmetics buyers escalate with each qualification cycle.
For Market Incumbents: Entrench positioning through captive seed sourcing agreements with Amazon cooperatives under Nagoya Protocol benefit-sharing frameworks, while accelerating supercritical CO2 extraction capacity additions near Manaus to capture Swissmedic-grade certification premiums. Synthetic caffeine substitution timelines in German energy drink reformulation represent the critical threat vector requiring defensive certification investments.
For New Entrants and Emerging Players: Build out direct-to-brand digital procurement platforms connecting Amazon collectives with European nutraceutical formulators, bypassing São Paulo intermediary margins. India's FSSAI-evolving botanical standards and underdeveloped certified supplier base offer the most penetrable white-space opportunity, with Mumbai and Bangalore functional beverage manufacturers seeking ANVISA-registered partners for novel food compliance.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extract specialists with EFSA-approved dossiers and multi-year pharmaceutical supply contracts, as these relationships exhibit decade-long renewal patterns with minimal churn. Acquisition targets should demonstrate existing ECHA REACH compliance and digitized batch-to-batch consistency infrastructure. The signal to monitor is EFSA caffeine labeling mandate tightening, which would accelerate procurement consolidation toward pre-qualified Brazilian processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Swissmedic and EMA pharmaceutical-grade certification unlocks premium positioning in Basel and Zurich cosmetics channels. |
| Direct-to-Brand Sourcing Platform | Digital procurement connecting Amazon cooperatives with French and Dutch formulators captures traceability premiums from health enthusiasts. |
| EFSA Novel Food Dossier Investment | Streamlined safety assessments for Paullinia cupana extracts accelerate European market entry against unverified botanical imports. |
| Backward Integration into Seed Cultivation | Captive Amazon sourcing networks reduce rainfall-driven volatility from Roraima and Pará wild collection zones. |
| India Market Entry Partnership | FSSAI-compliant extract supply addresses rising functional beverage consumption in Mumbai and Bangalore manufacturing hubs. |
Methodological Framework
Initial hypotheses were tested against primary input from extract purification specialists, ANVISA regulatory affairs leads, European nutraceutical procurement managers, and Amazon cooperative coordinators, then refined through secondary validation against EFSA novel food registers, ANVISA GMP inspection records, ECHA REACH dossier databases, and Brazilian customs export statistics. Bottom-up volume modeling from seed collection zones through processing clusters was triangulated against top-down demand estimates from beverage manufacturer reformulation disclosures and pharmaceutical-grade buyer procurement patterns.
Demand-supply balance dynamics across the projection horizon were modeled through segmented analysis by product form, application channel, certification tier, and geographic regulatory cluster, with CAGRs derived from volume trajectory convergence between upstream seed availability constraints and downstream clean-label substitution rates. Forecast inputs incorporated supercritical CO2 extraction capacity expansion timelines, EFSA health claims scrutiny evolution, and FSSAI botanical standard development progress.
Sensitivities concentrate around rainfall irregularity in Amazon collection zones, synthetic caffeine cost competitiveness from Chinese manufacturers, and EFSA caffeine disclosure mandate acceleration. Forecasts reflect documented assumptions regarding regulatory trajectory continuity and clean-label formulation commitment durability across beverage and nutraceutical channels. Macroeconomic contraction in European functional beverage consumption, regulatory deviation in novel food approval timelines, or technological breakthrough in laboratory caffeine production would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Organic Cassava Flour Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Prunus Africana Market
Agriculture and Agri Products
Kuwait Poultry Meat Market
Agriculture and Agri Products
Global Coco Peat Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
Europe Alfalfa Hay Market