
 Honeysuckle Market | 2026-2036
Honeysuckle Market Size, Share, and Industry Trends Forecast 2026-2036
Honeysuckle Market Outlook
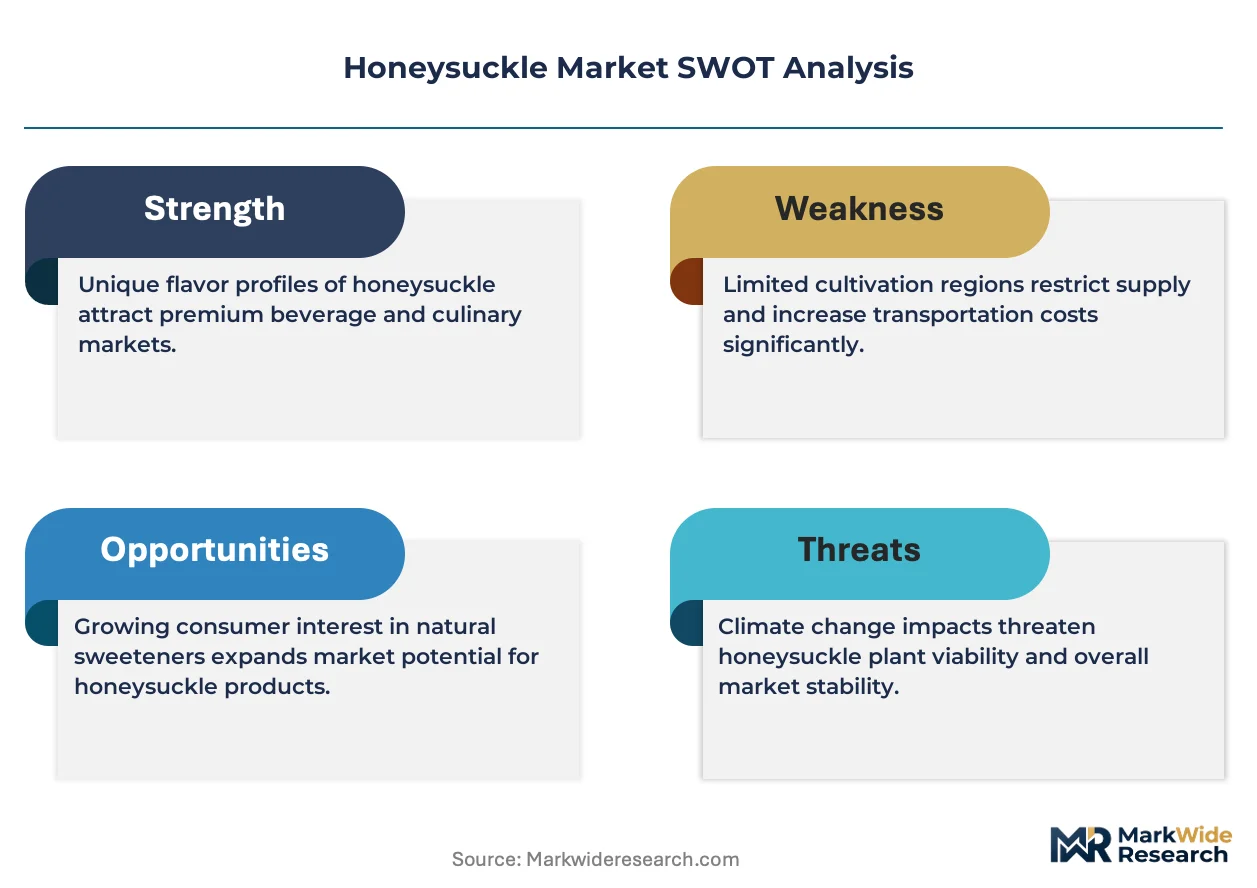
Subscription-based raw material assurance programs is restructuring how honeysuckle processors contract with growers. Symrise leverages long-term botanical sourcing agreements to secure extract volumes across temperate growing zones. Fuzhou Farwell anchors its position through backward integration into Fujian Province cultivation networks. Damin Foodstuff specializes in certified organic dried flower grades for European botanical buyers.
Honeysuckle comprises the dried flowers, buds, and extracts of Lonicera japonica and related species, containing chlorogenic acid, luteolin, and volatile oils typically recovered through steam distillation or solvent extraction, used primarily for antiviral, anti-inflammatory, and antioxidant applications in formulated products. Essential oils command premium positioning due to concentration-intensive distillation requirements and pharmaceutical-grade purity standards, while extracts are gaining fastest in functional beverage and nutraceutical formulations where standardization to marker compounds drives procurement decisions. Herbal supplements remain the most mature segment, with margin pools shifting toward clinical-trial-backed extract specifications.
China's NMPA enforces botanical drug master file requirements for honeysuckle-derived ingredients entering pharmaceutical channels, while the US FDA monitors dietary supplement cGMP compliance for herbal supplement imports. The EU's REACH framework and EFSA novel food assessments shape market access for non-traditional honeysuckle applications. Stakeholders must track evolving pharmacopeial monograph revisions and dual-use food-pharma regulatory boundaries to anticipate compliance-driven sourcing shifts.
Market Dynamics
China's NMPA botanical drug master file requirements are compressing supplier margins while pharmaceutical formulators consolidate procurement around certified extraction protocols, reshaping contract structures between processors and temperate-zone growers.
Growth Catalysts
- Antiviral formulation demand:Pharmaceutical laboratories are expanding honeysuckle extract procurement for respiratory and anti-inflammatory drug pipelines, with chlorogenic acid standardization becoming a procurement prerequisite.
- REACH framework adaptation:European botanical buyers are driving certified organic dried flower grades through EFSA novel food assessment pathways, opening functional beverage applications.
- Zhejiang Province cluster concentration:Traditional medicine corridors in East Asia are anchoring volume demand through backward integration into Fujian and Zhejiang cultivation networks.
Market Restraints
- Steam distillation cost structure:Essential oil recovery requires concentration-intensive processing that elevates unit economics above solvent extraction alternatives.
- Single-origin supply risk:Temperate growing zone dependence creates harvest volatility exposure for processors lacking multi-source contracts.
- Dual-use regulatory friction:NMPA pharmaceutical channel requirements and FDA dietary supplement cGMP compliance create parallel certification burdens for cross-border suppliers.
Strategic Opportunities
- South Korean herbal processing expansion:MFDS regulatory alignment with traditional medicine standards is creating certified extract demand for clinical-trial-backed specifications.
- Functional beverage convergence:Luteolin-standardized extracts are penetrating ready-to-drink formulations as marker compound transparency becomes a consumer-facing differentiator.
- Subscription contracting models:Raw material assurance programs are displacing spot-market purchasing for processors seeking volume predictability.
Industry Challenges
- Pharmacopeial monograph revision cycles:Evolving purity standards for volatile oils and chlorogenic acid content create reformulation lag times for existing product lines.
- Extraction technology capex requirements:Pharmaceutical-grade distillation infrastructure demands capital deployment that mid-scale processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Honeysuckle Market |
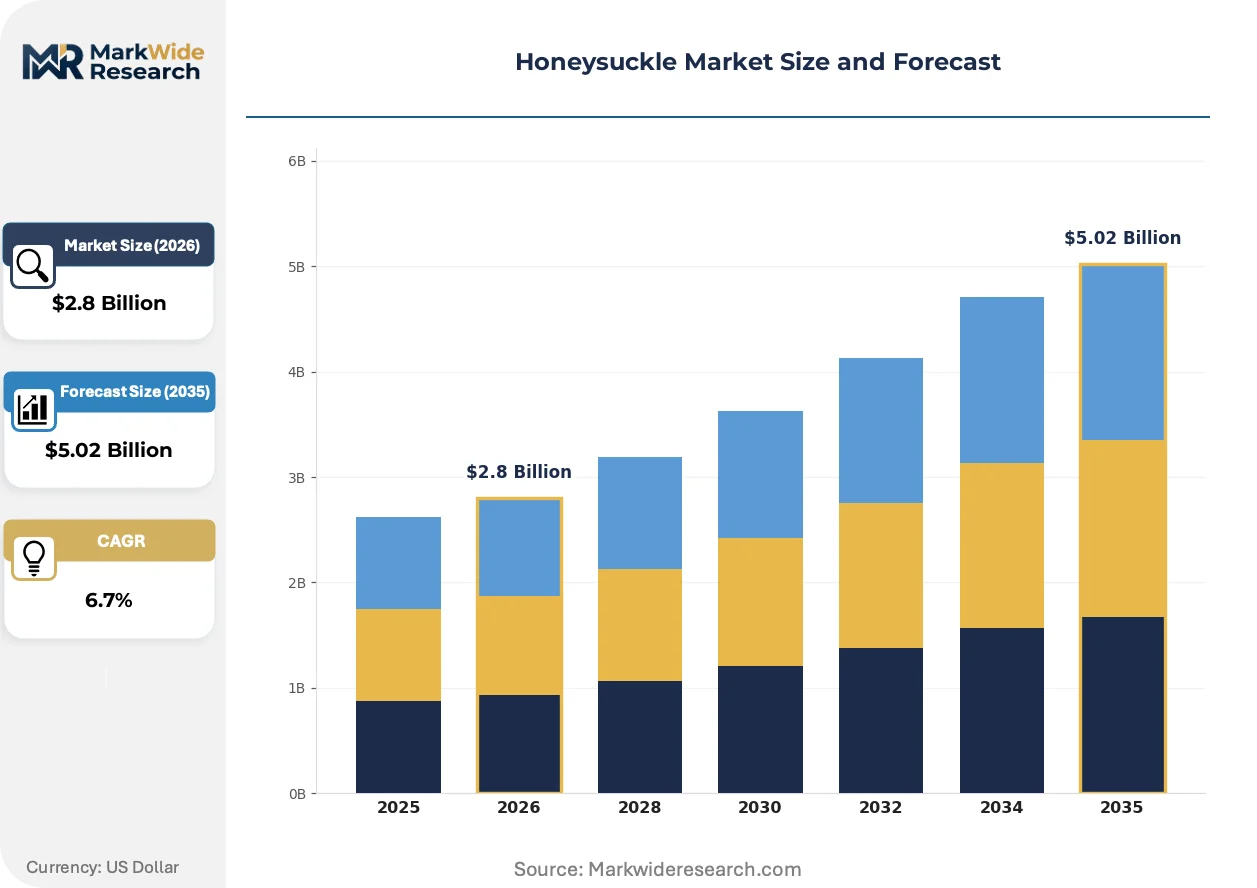
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Dried Flowers, Herbal Supplements, Extracts Application: Cosmetics, Pharmaceuticals, Aromatherapy, Food Flavoring End User: Health Enthusiasts, Aromatherapists, Manufacturers, Retailers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Wholesale |
| Companies Covered | Symrise, Fuzhou Farwell, Damin Foodstuff, Nutra Green Biotechnology, India Essential Oils, Shannxi Undersun Biomedtech, Novoherb Technologies, Mountain Rose Herbs, INDIA AROMA OILS AND COMPANY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honeysuckle Market Strategic Shifts
Supercritical CO2 extraction technology is compressing processing timelines while regulatory documentation automation is reducing compliance overhead, together enabling faster pharmaceutical qualification cycles.
Supercritical CO2 extraction systems are recovering volatile oils and chlorogenic acid without thermal degradation. Pharmaceutical formulators in South Korea and Japan are adopting these systems to meet PMDA and MFDS purity documentation requirements. This technology is electrifying competitive positioning by collapsing the 18-24 month qualification timeline for new extract suppliers.
China's NMPA tightened botanical ingredient documentation requirements in 2024, mandating batch-level traceability for honeysuckle entering pharmaceutical channels. Processors must now maintain extraction protocol certifications that mirror drug master file standards. Suppliers with captive Fujian Province cultivation networks are responding fastest, while spot-market dependent traders face exclusion.
Buyers are consolidating procurement around long-term sourcing agreements with certified processors, abandoning auction-based spot purchasing. Functional beverage and nutraceutical manufacturers in Europe and East Asia are driving this shift, prioritizing marker compound consistency over price volatility. Zhejiang Province processing clusters exhibit the most advanced contract structures, with volume commitments tied to harvest yield insurance mechanisms.
Honeysuckle Market Segmentation
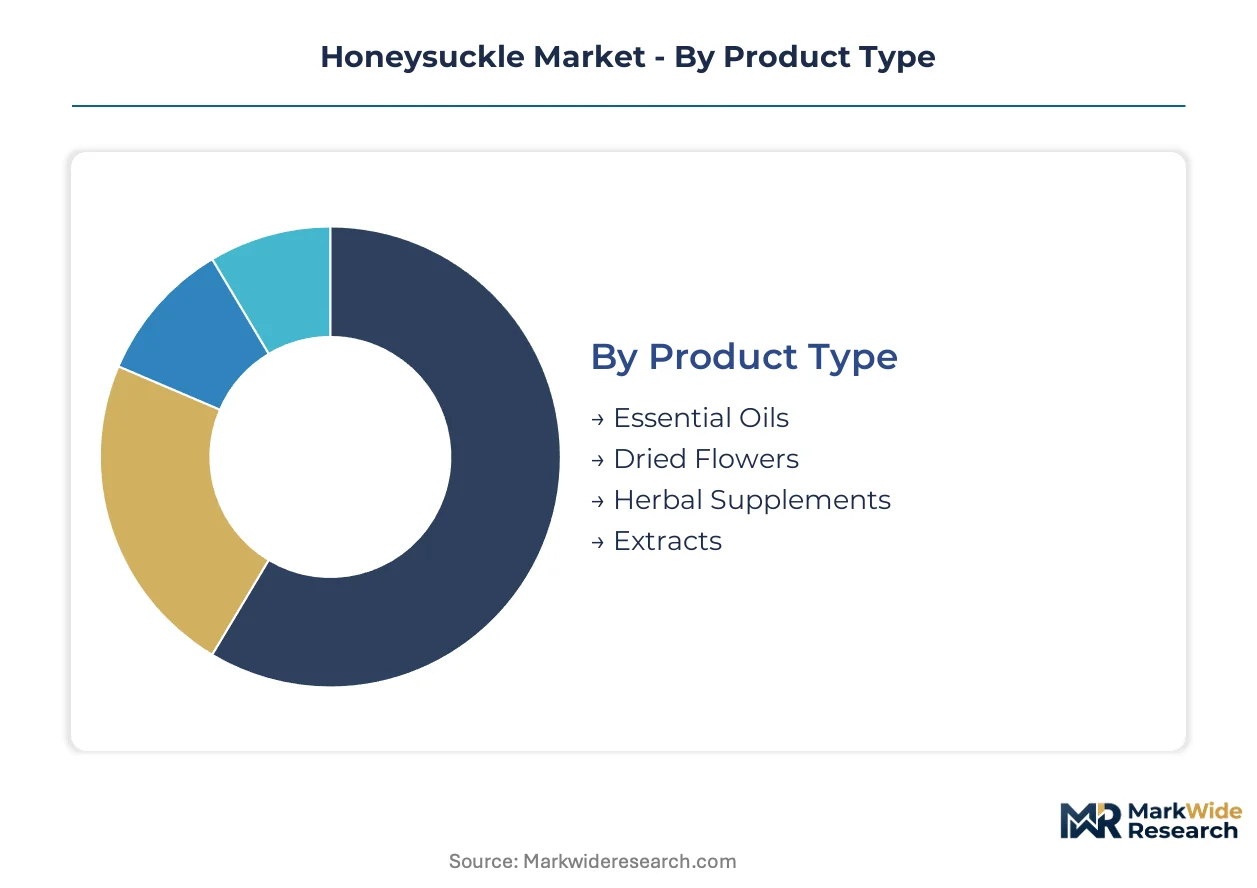
Honeysuckle procurement patterns diverge sharply between standalone botanical ingredients and embedded formulation inputs. Understanding these integration pathways clarifies why pharmaceutical buyers prioritize certified extracts while cosmetic formulators favor essential oils.
Product Type:
Standalone botanical grades command premium positioning through purity documentation, while embedded extracts penetrate volume formulations through standardization protocols.
- Essential Oils:Concentrated volatile oil fractions recovered through steam distillation or supercritical CO2 extraction, typically standardized for linalool and benzyl acetate content. Pharmaceutical laboratories in South Korea specify these for respiratory antiviral formulations where MFDS documentation requirements elevate procurement thresholds.
- Extracts:Solvent-derived or aqueous concentrates standardized to chlorogenic acid and luteolin markers, penetrating functional beverages and nutraceutical capsules. European buyers through EFSA novel food pathways are consolidating procurement around certified organic extract grades for ready-to-drink applications.
- Dried Flowers:Whole or cut dried Lonicera japonica florets for traditional medicine decoctions and tea blends.
- Herbal Supplements:Encapsulated or tableted whole-herb powders serving mature dietary supplement channels.
Volume placements concentrate in Extracts; the faster expansion belongs to Essential Oils.
Application:
Cost tier stratification separates clinical-grade specifications from commodity flavoring inputs, with regulatory burden determining margin capture.
- Pharmaceuticals:Antiviral and anti-inflammatory drug pipelines utilizing chlorogenic acid-standardized extracts. China's NMPA drug master file requirements compress supplier margins while consolidating procurement around Fujian Province processors with captive cultivation networks.
- Cosmetics:Antioxidant and soothing claims in skincare formulations leveraging luteolin content. Zhejiang Province extraction clusters supply Korean and Japanese cosmetic manufacturers seeking PMDA-aligned purity documentation.
- Aromatherapy:Inhalation and topical applications of volatile oil fractions.
- Food Flavoring:Natural flavor extracts for beverages and confectionery at lower specification tiers.
Margin capture peaks in Pharmaceuticals; steepest expansion trajectory runs through Cosmetics.
End User:
Customer sophistication separates specification-driven procurement from price-sensitive spot purchasing, reshaping contract structures across the value chain.
- Manufacturers:Formulators of pharmaceuticals, nutraceuticals, and cosmetics requiring batch-level traceability and extraction protocol certifications. Subscription-based raw material assurance programs are displacing auction-based purchasing for this cohort.
- Health Enthusiasts:Direct consumers of dried flowers and supplements through online and specialty channels.
- Aromatherapists:Practitioners sourcing essential oils for therapeutic application protocols.
- Retailers:Brick-and-mortar and e-commerce distributors of finished botanical products.
Contract value concentrates with Manufacturers; the fastest share gains belong to Health Enthusiasts.
Distribution Channel:
Supply concentration in East Asian processing clusters shapes channel efficiency, with digital platforms eroding traditional wholesale intermediation.
- Wholesale:Volume contracts between Fujian and Zhejiang processors and pharmaceutical formulators, incorporating harvest yield insurance mechanisms and multi-year sourcing commitments.
- Online Retail:Direct-to-consumer platforms for dried flowers and supplements, penetrating European and North American markets with organic certification transparency.
- Pharmacies:Regulated channels for pharmaceutical-grade extracts in China and South Korea.
- Specialty Stores:Brick-and-mortar botanical and natural product retailers.
Transaction volume concentrates in Wholesale; digital penetration climbs fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China cultivates the majority of global honeysuckle supply while South Korea and Japan absorb premium extract volumes for pharmaceutical applications. European buyers source certified organic grades through EFSA novel food pathways. North American demand concentrates in dietary supplement channels with FDA cGMP compliance requirements.
China
Zhejiang Province processors supply chlorogenic acid-standardized extracts to domestic pharmaceutical formulators. NMPA's 2024 botanical drug master file mandate compresses margins for uncertified traders. Fujian Province cultivation networks are consolidating through backward integration into captive growing operations.
South Korea
MFDS-aligned pharmaceutical laboratories specify honeysuckle essential oils for respiratory antiviral formulations. The country's traditional medicine standards create procurement thresholds that favor certified extraction protocols. Seoul-Gyeonggi processing clusters are expanding supercritical CO2 capacity to collapse supplier qualification timelines.
Japan
PMDA purity documentation requirements elevate procurement thresholds for cosmetic and pharmaceutical applications. The country's botanical ingredient buyers consolidate procurement around long-term sourcing agreements. Osaka-Kansai extraction facilities supply luteolin-standardized grades for skincare formulations.
Germany
REACH framework compliance drives certified organic dried flower procurement for functional beverage applications. EFSA novel food assessments shape market access for non-traditional honeysuckle ingredients. Bavarian botanical distributors are anchoring European volume demand through multi-year processor contracts.
United States
FDA dietary supplement cGMP compliance creates parallel certification burdens for cross-border extract suppliers. Health enthusiast direct purchasing through online retail channels is displacing traditional wholesale intermediation. Pacific Northwest botanical processors are developing subscription-based raw material assurance programs.
Honeysuckle Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade extraction capacity, while mid-scale processors compete on certified organic grades for European botanical buyers. The vendor base stratifies across three tiers: integrated cultivator-processors with captive Fujian supply, specialist extract standardizers serving MFDS and PMDA channels, and commodity traders facing NMPA documentation exclusion. Dominant competitive moves include backward integration into temperate growing zones and technology licensing for supercritical CO2 systems.
Among Germany-based flavor and fragrance specialists, Symrise exemplifies long-term botanical sourcing agreements across temperate growing zones. Within Chinese integrated processor archetypes, Fuzhou Farwell occupies a position representing backward integration into Fujian Province cultivation networks. Damin Foodstuff sits within the certified organic specialist tier, serving European botanical buyers through EFSA-aligned documentation protocols.
| Leading Market Players |
|---|
| Symrise |
| Fuzhou Farwell |
| Damin Foodstuff |
| Nutra Green Biotechnology |
| India Essential Oils |
| Shannxi Undersun Biomedtech |
| Novoherb Technologies |
| Mountain Rose Herbs |
| INDIA AROMA OILS AND COMPANY |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical formulator procurement consolidation around certified extraction protocols has entrenched long-term contract-based offtake as the dominant pricing model, compressing spot-market viability for uncertified traders. NMPA documentation requirements compress margins while subscription-based raw material assurance programs displace auction-based purchasing.
Pricing Analysis
Margin tightening in essential oil grades reflects concentration-intensive steam distillation requirements and pharmaceutical-grade purity documentation burdens. Three-tier pricing structure across pharmaceutical, cosmetic, and food-grade levels separates chlorogenic acid-standardized extracts from luteolin-marked cosmetic grades and commodity dried flower tiers. Cost-down pressure on mid-scale processors accelerates because NMPA batch-level traceability mandates demand capital deployment beyond their financing capacity. Health enthusiasts purchasing through online retail channels exhibit highest price sensitivity, while pharmaceutical laboratories demonstrate lowest sensitivity due to MFDS and PMDA qualification thresholds.
Supply Chain Analysis
Regional distribution centers in Zhejiang Province operate hub-and-spoke patterns radiating toward South Korean and Japanese pharmaceutical formulators. Geographic supply concentration centers on China, South Korea, and Japan, with Fujian Province cultivation networks feeding captive processing operations. Raw material dependencies rest on temperate-zone Lonicera japonica harvests, chlorogenic acid marker consistency, and volatile oil yield predictability. Single-origin supply risk from temperate growing zone dependence creates harvest volatility exposure for processors lacking multi-source contracts. Distribution runs through wholesale volume contracts incorporating harvest yield insurance mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where NMPA documentation mandates force weaker traders into exclusion, rewarding integrated cultivator-processors with captive supply networks.
For Market Incumbents: Cement dominance through backward integration into Fujian Province cultivation networks and supercritical CO2 extraction technology licensing. Threat from spot-market dependent traders facing NMPA exclusion creates acquisition opportunities. Certification investment in drug master file-aligned protocols serves as the critical lever for pharmaceutical channel retention. For New Entrants and Emerging Players: Functional beverage manufacturers in Europe represent the most penetrable channel partner type for EFSA novel food-aligned certified organic extract grades. White-space targets include luteolin-standardized ready-to-drink formulations and subscription-based raw material assurance programs for mid-scale processors. Go-to-market angle centers on marker compound transparency as consumer-facing differentiation. For Investors and Strategic Acquirers: The window for entry favors integrated cultivator-processors with captive Fujian supply networks and existing NMPA documentation infrastructure. Long-term viability hinges on regulatory compliance moats deepening through pharmacopeial monograph alignment. Acquisition target archetype encompasses mid-scale processors with supercritical CO2 capacity gaps. Signal to watch: MFDS and PMDA qualification timeline compression for new extract suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Fujian Province captive growing operations secure volume predictability against harvest volatility. |
| Supercritical CO2 Technology Licensing | Seoul-Gyeonggi processing clusters collapse 18-24 month supplier qualification timelines. |
| Long-term Sourcing Agreements | Symrise-style botanical contracts displace spot-market purchasing for pharmaceutical formulators. |
| EFSA Novel Food Certification | Certified organic grades unlock European functional beverage procurement consolidation. |
| Subscription Contracting Models | Raw material assurance programs tie volume commitments to harvest yield insurance mechanisms. |
Study Parameters
Document review covered NMPA botanical drug master file guidance, EFSA novel food assessment pathways, and MFDS traditional medicine standards, complemented by interviews with extraction technology suppliers, pharmaceutical formulators, and Zhejiang Province processing cluster managers. Secondary validation drew from pharmacopeial monograph revisions, customs trade data for honeysuckle-derived ingredients, and SEC filings of publicly traded botanical processors. Bottom-up volume modeling from cultivation hectarage and yield estimates triangulated against top-down pharmaceutical procurement value chain analysis.
Segment-level outputs across product type, application, and end-user dimensions incorporated chlorogenic acid standardization tiers, regulatory pathway clustering, and channel concentration patterns. CAGRs derived from regression analysis of historical procurement volume trends, adjusted for NMPA documentation mandate implementation effects. Industry-specific inputs encompassed supercritical CO2 adoption rates and subscription contracting penetration curves.
Caveats apply where NMPA pharmacopeial monograph revisions, EFSA novel food assessment delays, or temperate-zone climate volatility could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
South Africa Alfalfa Hay Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
Compound Horse Feedstuff Market
Agriculture and Agri Products
Sophora Japonica Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Europe Compound Feed Market