
 Africa Food Colorants Market | 2026-2036
Africa Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Food Colorants Market Outlook
Artisanal and small-scale food processors is rotating toward synthetic and natural colorant blends as urbanization accelerates formal packaged food consumption. Chr. Hansen Holding A/S leverages its fermentation-based natural color expertise to anchor supply relationships with dairy and beverage formulators across East and West Africa. DSM sustains R&D intensity in carotenoid-derived solutions, while Dohler Group competes through integrated flavor-color systems tailored to local fruit beverage profiles.
Food colorants encompass dyes, pigments, and lakes that impart, restore, or enhance visual appeal in edible products, typically formulated at concentrations between 0.01% and 0.5% by weight depending on substrate and regulatory limits. Their primary commercial purpose centers on consumer preference alignment, shelf-life perception management, and brand differentiation in competitive retail environments. Natural colors command premium positioning among health-conscious buyers, whereas synthetic colors retain cost advantages in mass-market bakery and confectionery segments where margin pools remain deepest. The beverages application category leads volume absorption, driven by carbonated soft drinks and fruit juice expansion in Nigeria, Egypt, and Kenya.
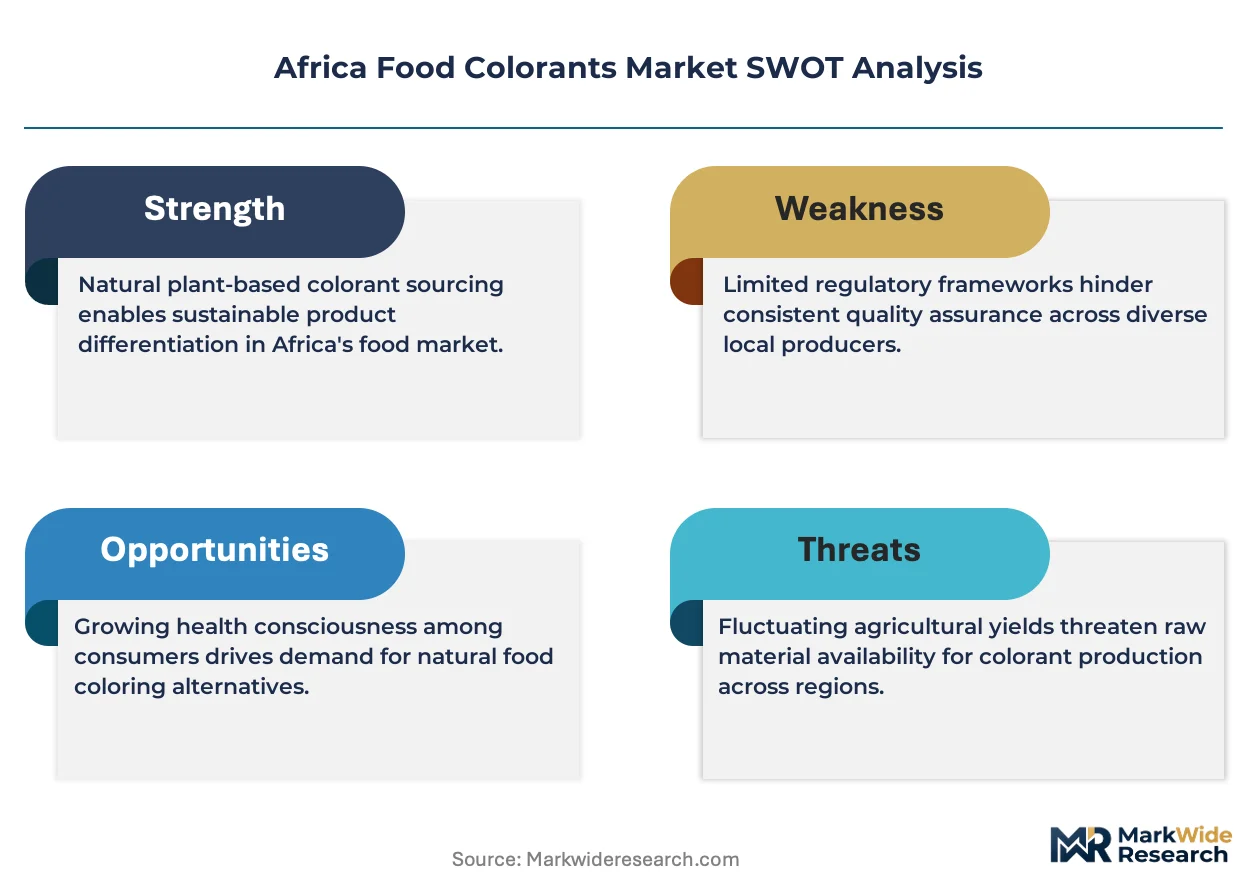
South Africa's Department of Health, Nigeria's National Agency for Food and Drug Administration and Control, and Egypt's National Food Safety Authority each enforce additive maximum limits and labeling requirements that shape product registration timelines and reformulation costs for imported and locally manufactured colorants. Compliance complexity rises as harmonization between national standards and Codex Alimentarius guidelines remains incomplete across the continent. Stakeholders must monitor regulatory convergence momentum and build flexible formulation platforms capable of rapid adaptation to tightening natural-origin mandates and evolving consumer transparency expectations.
Market Dynamics
Natural colorant fermentation capacity is concentrating among a handful of suppliers, creating supply bottlenecks as beverage formulators across Nigeria, Egypt, and Kenya scramble to secure volume commitments ahead of reformulation deadlines.
Growth Catalysts
- NAFDAC additive registration reforms:Nigeria's streamlined approval pathways for natural-origin colorants are accelerating product launches in Lagos and Kano processing corridors.
- Urban packaged food penetration:Formal retail expansion in Nairobi and Accra is pulling artisanal processors toward standardized colorant sourcing.
- Carotenoid extraction yield improvements:Enzymatic processing advances are compressing unit costs for orange-red natural formulations targeting juice applications.
Market Restraints
- Annatto and turmeric supply volatility:Weather-dependent harvests in East African growing regions create input cost swings that synthetic alternatives avoid.
- South African import dependency:Regional colorant formulation concentrates in Gauteng-based facilities, exposing Nigerian and Kenyan buyers to rand-denominated pricing risk.
- Solubility limitations in carbonated matrices:Natural colorants struggle with pH stability in low-pH beverage systems, locking synthetics into cola and lemon-lime segments.
Strategic Opportunities
- Ethiopian beverage manufacturing greenfield:Addis Ababa's industrial park incentives and underdeveloped colorant supply create first-mover positioning for natural formulation specialists.
- Clean-label confectionery pivot:Ghanaian cocoa processors are retrofitting chocolate lines to accommodate beet-derived reds and spirulina blues for export markets.
- East African dairy cooperative integration:Direct supply relationships with Ugandan and Tanzanian milk processors bypass Johannesburg distribution layers.
Industry Challenges
- Fermentation technologist scarcity:Natural colorant production requires microbial cultivation expertise that African technical institutes rarely graduate.
- Multi-jurisdiction label compliance:Exporters to the EU must reconcile EFSA additive codes with NAFDAC and Egyptian National Food Safety Authority classification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Food Colorants Market |
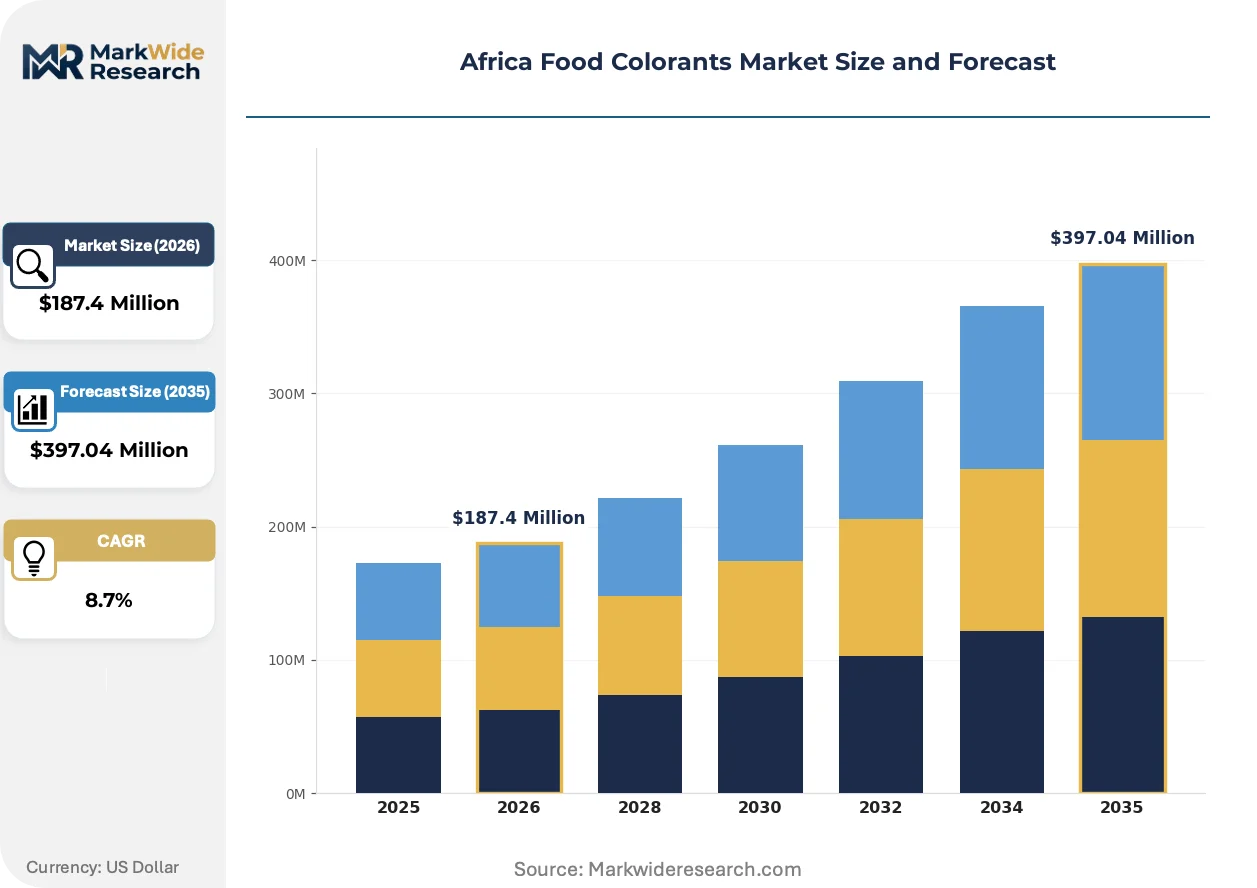
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Synthetic Colors, Color Additives, Color Enhancers Application: Beverages, Bakery Products, Dairy, Confectionery End User: Food Manufacturers, Beverages Industry, Retailers, Ingredients Suppliers Distribution Channel: Direct Sales, Retail Stores, E-commerce, Distributors |
| Companies Covered | Aromatagroup Srl, D.D. Williamson & Co., DSM, Dohler Group, Chr. Hansen Holding A/S, Sensient Technologies Corporation, BASF SE, Tate & Lyle, Givaudan SA, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Food Colorants Market Strategic Shifts
Fermentation-derived natural colors are separating from botanical extracts as distinct technology platforms, with each path commanding different buyer segments and pricing power across African beverage and dairy applications.
Microbial pigment production through engineered yeast and fungal strains is bifurcating the natural colorant supply base. East African dairy cooperatives are adopting fermentation-derived beta-carotene for butter and cheese applications at accelerating rates. This technology is compressing the cost gap with synthetic alternatives while creating captive supply relationships that exclude traditional botanical extractors from volume accounts.
Egypt's National Food Safety Authority has tightened maximum permissible limits for synthetic azo dyes in children's food categories, mirroring EFSA precautionary guidelines. Industrial consequence includes mandatory reformulation timelines for Cairo-based confectionery manufacturers. Juice and flavored milk segments are responding fastest, with several processors completing natural color transitions ahead of enforcement windows.
Direct procurement from colorant manufacturers is displacing layered distributor relationships among large Nigerian beverage groups. Lagos and Ibadan formulators are negotiating annual volume contracts with fermentation specialists, bypassing traditional chemical distributors. This pattern is most visible in carbonated soft drink and fruit nectar verticals, where scale concentration enables supply base consolidation.
Africa Food Colorants Market Segmentation
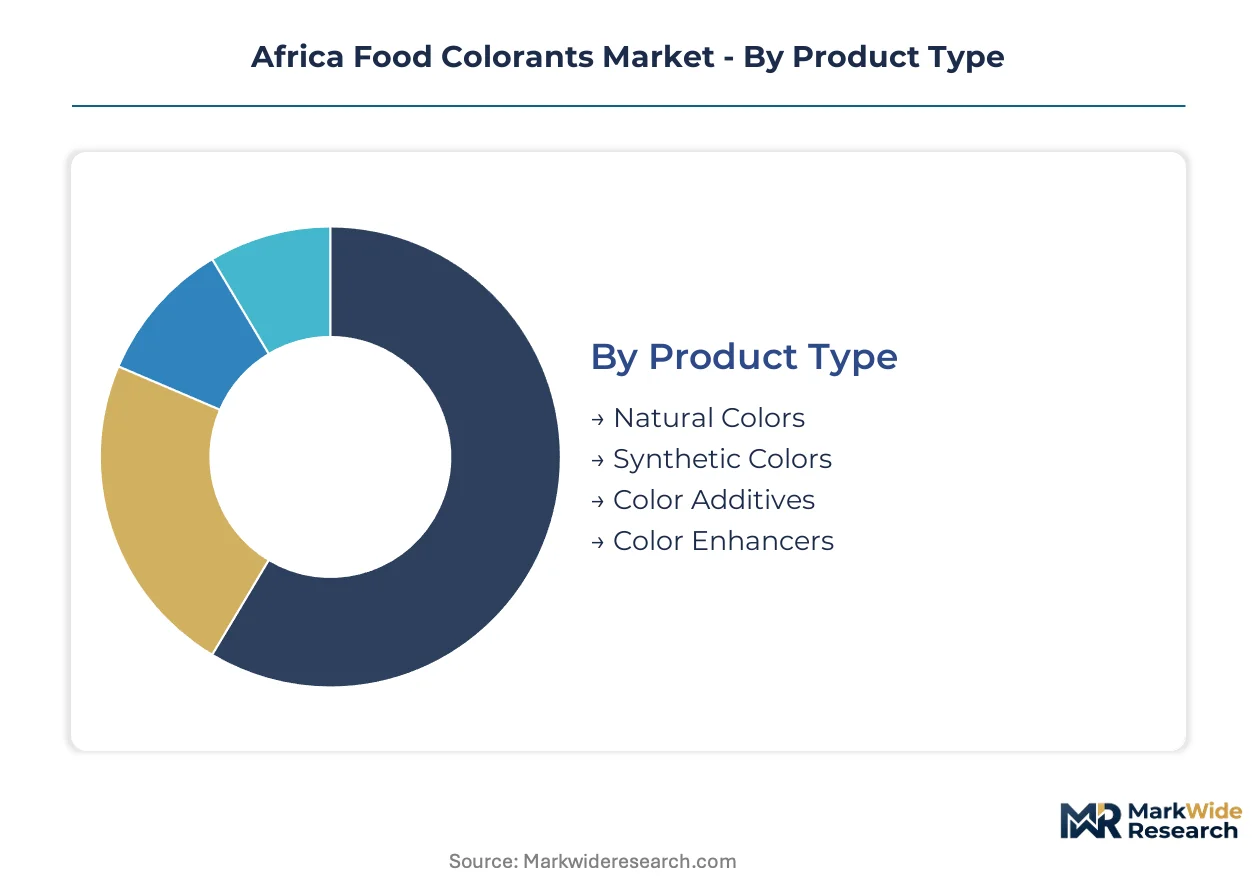
Food colorant procurement patterns across Africa diverge sharply between domestic formulators serving local taste preferences and exporters navigating EU and Gulf state clean-label mandates. Understanding these segment boundaries clarifies where technology investments concentrate versus where cost optimization dominates.
Product Type:
Natural colorants serve predominantly export-oriented processors in Accra and Nairobi seeking EU retail access, while synthetic formulations anchor domestic mass-market production in Lagos and Cairo where margin pressure is most acute.
- Natural Colors:Fermentation-derived beta-carotene and spirulina formulations dominate dairy and beverage applications across East African cooperatives. Nigerian juice manufacturers are accelerating procurement of beet-derived reds and turmeric yellows ahead of anticipated NAFDAC labeling reforms.
- Synthetic Colors:Azo dyes and aluminum lakes retain cost advantages in carbonated soft drinks and mass-market confectionery. Cairo-based manufacturers continue bulk purchasing of sunset yellow and tartrazine despite Egyptian National Food Safety Authority's tightened limits for children's food categories.
- Color Additives:Lake pigments provide light and pH stability for coated confectionery and compressed tablets.
- Color Enhancers:Blended systems combining pigments with emulsifiers address solubility challenges in low-pH beverage matrices.
Synthetic colors command the established base. The steepest expansion runs through natural colorants.
Application:
Volume concentration varies by manufacturing infrastructure maturity, with beverage processing clusters in Nigeria and Egypt absorbing disproportionate colorant tonnage relative to their population share.
- Beverages:Carbonated soft drinks, fruit nectars, and flavored waters represent the dominant absorption channel. Lagos and Ibadan formulators are consolidating direct procurement relationships with fermentation specialists, bypassing traditional chemical distributors entirely.
- Bakery Products:Margarine-based icings and packaged bread rely on annatto and turmeric for yellow-orange hues. Kenyan millers face input cost volatility from weather-dependent East African harvests.
- Dairy:Butter and cheese applications in Uganda and Tanzania are adopting microbial-derived beta-carotene at accelerating rates.
- Confectionery:Ghanaian cocoa processors are retrofitting chocolate lines for beet-derived reds and spirulina blues targeting export markets.
Beverages absorb the highest volume tonnage. Dairy is climbing the fastest as cooperative processing scales.
End User:
Procurement sophistication stratifies sharply between multinational beverage groups with technical formulation teams and artisanal processors dependent on distributor technical support.
- Food Manufacturers:Large-scale baked goods and packaged food producers in Kano and Accra standardizing colorant specifications for formal retail penetration.
- Beverages Industry:Carbonated and juice formulators driving fermentation-derived natural color adoption through direct manufacturer contracts.
- Retailers:Private-label development in South African supermarket chains creating specification pressure on upstream suppliers.
- Ingredients Suppliers:Regional distributors in Johannesburg consolidating warehousing and technical service capabilities for sub-Saharan markets.
Food manufacturers anchor current procurement volume. Beverages industry buyers are gaining share fastest through supply base consolidation.
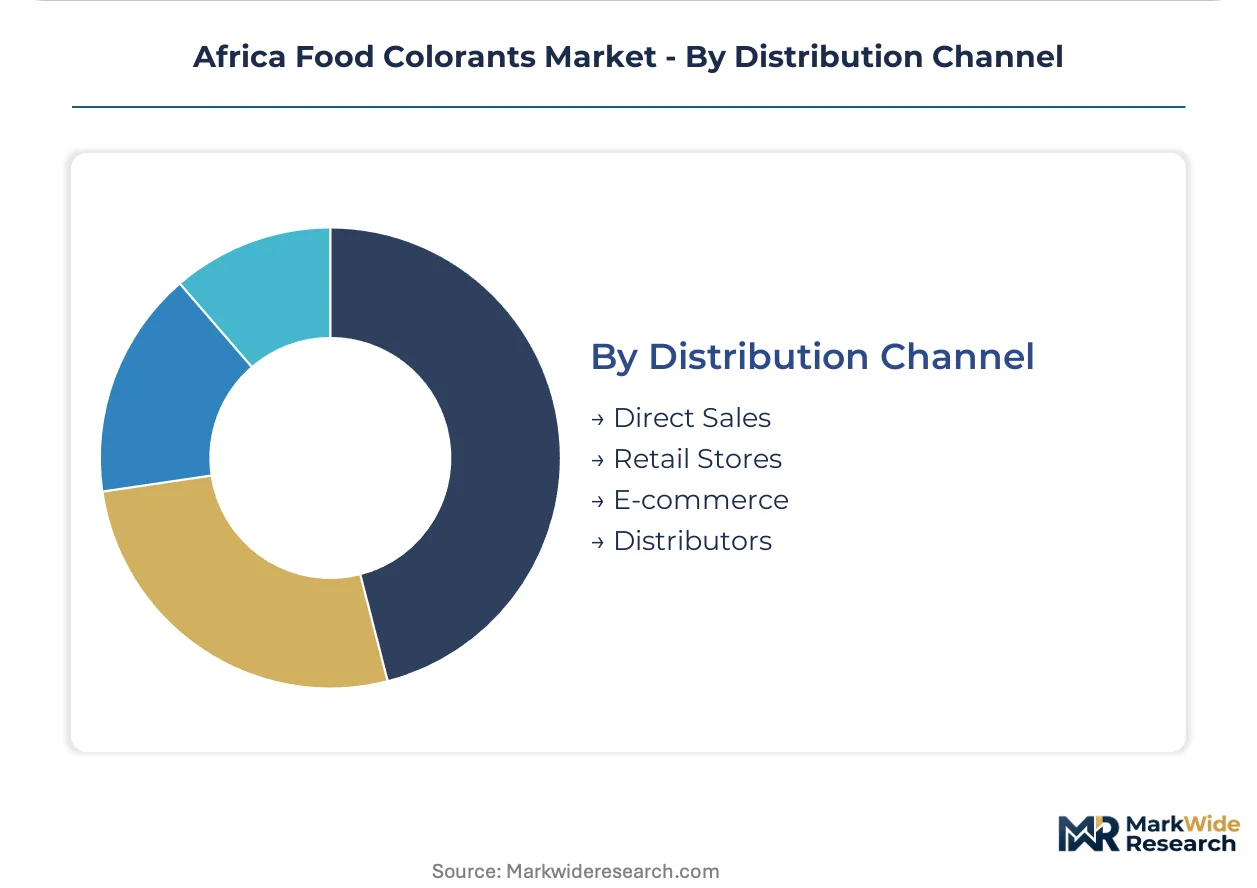
Distribution Channel:
Channel selection correlates directly with buyer scale and technical capability, with direct relationships displacing intermediaries among volume accounts.
- Direct Sales:Annual volume contracts between Nigerian beverage groups and fermentation specialists eliminating distributor margins. Technical support and formulation collaboration bundled into supply agreements.
- Retail Stores:Small-scale artisanal processors in informal sectors sourcing through agricultural supply shops and chemical traders.
- E-commerce:Emerging procurement channel for specialty natural colors among Nairobi and Lagos food startups with limited warehousing.
- Distributors:Gauteng-based regional distributors maintaining inventory positions for Kenyan and Nigerian buyers exposed to rand-denominated pricing risk.
Distributors still handle the majority of transaction volume. Direct sales are expanding most quickly as buyer concentration enables supply base bypass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Apapa port complex in Lagos anchors West African colorant import flows, while the Maputo Corridor rail link channels South African formulation outputs into neighboring markets. These infrastructure assets define regional supply geometries.
Nigeria
Lagos and Kano beverage corridors drive fermentation-derived natural color procurement as carbonated soft drink volumes expand. NAFDAC's streamlined additive registration reforms accelerate product launch timelines for natural-origin formulations. Direct annual volume contracts between Ibadan formulators and fermentation specialists are displacing traditional chemical distributors entirely.
South Africa
Gauteng-based formulation facilities concentrate regional colorant production capacity for sub-Saharan distribution. The Department of Health enforces strict food additive labeling requirements under national foodstuffs regulations that shape import registration costs. Johannesburg distributors maintain rand-denominated inventory positions exposing Kenyan and Nigerian buyers to exchange rate volatility.
Egypt
Cairo-based confectionery manufacturers face mandatory reformulation timelines as the National Food Safety Authority tightens maximum permissible limits for synthetic azo dyes in children's food categories. Juice and flavored milk processors are completing natural color transitions ahead of enforcement windows. Industrial park incentives in 6th of October City attract formulation specialists serving North African export markets.
Kenya
Nairobi's formal retail expansion pulls artisanal processors toward standardized colorant sourcing for packaged bread and margarine applications. Weather-dependent East African annatto and turmeric harvests create input cost volatility that millers struggle to hedge. Direct supply relationships with Ugandan and Tanzanian dairy cooperatives bypass Johannesburg distribution layers entirely.
Ethiopia
Addis Ababa's industrial park incentives and underdeveloped colorant supply create first-mover positioning opportunities for natural formulation specialists. Beverage manufacturing greenfield investments are accelerating as regional brands seek manufacturing alternatives to established East African hubs. Technical service capabilities remain scarce, requiring foreign suppliers to embed direct support teams.
Africa Food Colorants Market Competitive Environment
Listed leaders compete with private specialists across fermentation technology and botanical extraction capabilities. The supplier base concentrates around three technology platforms: microbial pigment production, plant-derived extraction systems, and synthetic azo dye manufacturing. Strategic archetypes include fermentation specialists with captive biotech capabilities, integrated flavor-color system providers, and diversified chemical conglomerates with African distribution networks. Competitive moves center on direct procurement relationship formation with large beverage groups and backward integration into raw material cultivation.
Within the fermentation-specialist tier, Chr. Hansen Holding A/S and DSM exemplify technology-driven positioning through microbial cultivation expertise. Among diversified chemical suppliers, BASF SE occupies a position representing synthetic colorant scale advantages. Sensient Technologies Corporation sits within the integrated solutions archetype, bridging natural and synthetic formulation capabilities for African beverage and dairy processors.
| Leading Market Players |
|---|
| Aromatagroup Srl |
| D.D. Williamson & Co. |
| DSM |
| Dohler Group |
| Chr. Hansen Holding A/S |
| Sensient Technologies Corporation |
| BASF SE |
| Tate & Lyle |
| Givaudan SA |
| Others |
Value Chain & Pricing Dynamics
NAFDAC's streamlined additive registration reforms in Nigeria simultaneously gate supplier qualification and stratify price tiers, as only fermentation specialists with compliance documentation command premium positioning while undocumented botanical extractors compete on raw cost.
Pricing Analysis
Volume-discount tiering separates annual-contract beverage manufacturers from spot-buying artisanal processors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and technical service bundling. Cost compression in synthetic azo dyes is intensifying because Egyptian National Food Safety Authority's tightened children's food limits are forcing rapid reformulation. Mass-market confectionery segments exhibit highest price sensitivity, while export-oriented Ghanaian cocoa processors prioritize color stability over unit cost.
Supply Chain Analysis
Apapa port congestion and container availability constraints on the Lagos-Asia trade lane inflate inbound logistics costs for fermentation-derived inputs. Manufacturing gravity centers on South Africa, Nigeria, and Egypt, with raw material dependencies spanning East African annatto harvests, Indian turmeric cultivation, and Chinese spirulina production. Single-source vulnerability runs through Gauteng-based formulation facilities exposing regional buyers to rand-denominated pricing risk. Distribution runs through Johannesburg distributors maintaining inventory positions for sub-Saharan markets, though direct manufacturer relationships are displacing intermediaries among large Nigerian beverage groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where NAFDAC registration timelines and Egyptian reformulation mandates create switching costs that lock processors into validated supplier relationships.
For Market Incumbents: Compound formulation expertise advantages by embedding technical service teams directly within Lagos and Nairobi beverage corridors. Deepen backward integration into East African annatto cultivation to hedge weather-dependent harvest volatility. Capacity addition in Ethiopian industrial parks captures first-mover positioning ahead of regional manufacturing migration.
For New Entrants and Emerging Players: Technical service scarcity among Gauteng-based distributors creates white-space for fermentation specialists offering embedded formulation support. Ethiopian beverage manufacturing greenfields represent the most penetrable geography given underdeveloped local supply and industrial park incentives. A direct-procurement go-to-market angle bypassing Johannesburg distribution layers secures volume commitments from consolidating Nigerian beverage groups.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across fermentation-derived natural colorants as enzymatic processing advances compress unit costs. Long-term viability favors platform players spanning microbial cultivation and botanical extraction capabilities. Acquisition targets should demonstrate captive relationships with East African dairy cooperatives. The signal to monitor is NAFDAC's pace of natural-origin labeling mandate expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Cultivation | Captive annatto supply from Ugandan cooperatives insulates against East African harvest volatility. |
| Direct Procurement Relationship Formation | Annual volume contracts with Lagos formulators eliminate Johannesburg distributor margins entirely. |
| Fermentation Capacity Expansion | Microbial pigment production scale-up addresses supply bottlenecks constraining Nigerian beverage reformulation. |
| Technical Service Team Embedding | On-site formulation support in Nairobi and Accra differentiates from Gauteng-based distributors. |
| Regulatory Pre-Registration Investment | Early NAFDAC dossier submission secures priority positioning ahead of anticipated natural-origin mandates. |
Study Parameters
A standing panel of beverage formulation managers, dairy cooperative procurement leads, regulatory affairs specialists at NAFDAC, and Johannesburg distribution channel heads provided ongoing calibration throughout the study. Primary interview insights combined with secondary validation from customs import records, South African Department of Health foodstuffs regulations, Egyptian National Food Safety Authority guidance documents, and Codex Alimentarius additive standards. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Consistency checks validated outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type tier, application vertical, end-user scale category, and regional regulatory cluster. CAGRs derived from annualized growth rate analysis applied to base-year sizing. Industry-specific forecast inputs incorporated fermentation yield improvement trajectories and urban packaged food penetration rates.
Forecasts assume regulatory continuity in Nigerian NAFDAC reforms, Egyptian children's food category limits, and South African labeling requirements; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Carotenoids Pigment Market
Flavorings and Food Additives
Fenchol Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Original and Flavored Syrup Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Vanilla Extract Market
Flavorings and Food Additives
Bitter Apricot Extract Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
South America Food Flavor Market