
 Betanin Food Color Market | 2026-2036
Betanin Food Color Market Size, Share, and Industry Trends Forecast 2026-2036
Betanin Food Color Market Outlook
The EU Green Deal's F-Gas Regulation and broader Farm-to-Fork strategy is restructuring how European food manufacturers source colorants, pushing reformulation timelines toward beet-derived solutions. Döhler GmbH leverages its integrated beet supply chain from German agricultural cooperatives to sustain cost advantages in liquid betanin extraction. GNT Group anchors its competitive position through vertical control of beet cultivation in the Netherlands, competing on batch-to-batch color consistency that synthetic alternatives cannot match.
Betanin is a water-soluble, nitrogen-containing pigment extracted primarily from red beetroot (Beta vulgaris) through aqueous or ethanol-based processes, yielding color values measured by E% (1cm, 1%) at 535-540 nm wavelength; its pH-dependent stability range of 4.0-7.0 makes it suitable for neutral to mildly acidic food matrices where it replaces synthetic Red No. 40 and Carmine. The liquid product type dominates commercial volumes due to ease of dosing in continuous manufacturing lines, while powder formats command premium positioning in dry-mix applications where water activity constraints matter. Food & beverage end users represent the mature demand base, whereas nutraceuticals is the fastest-growing segment as beetroot's nitrate-betanin synergy drives supplement formulation trends.
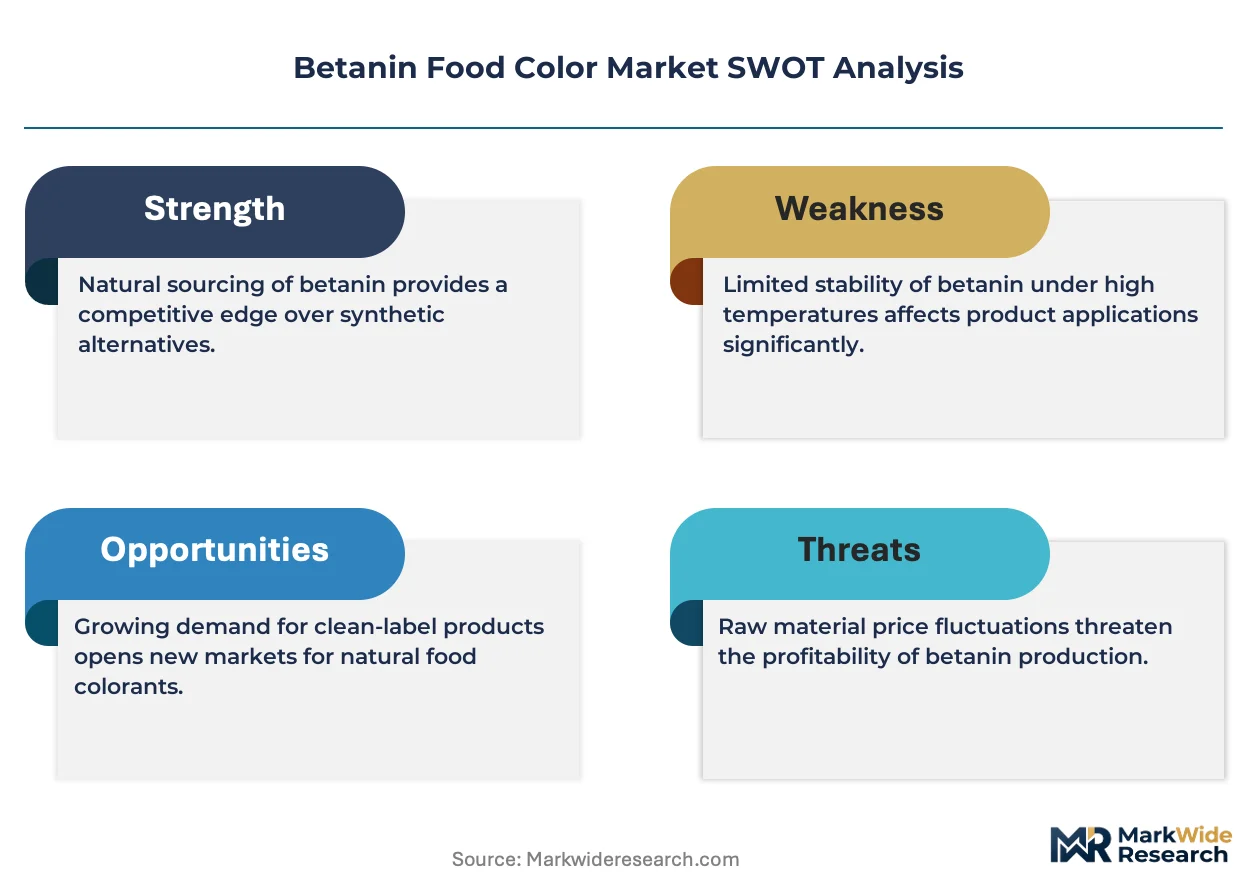
EMA food additive evaluations, EFSA purity specifications, and REACH chemical registration requirements collectively define the compliance threshold for betanin market access across Europe, with EFSA's ongoing re-evaluations of synthetic dye safety profiles indirectly accelerating natural colorant qualification timelines. Germany's Federal Institute for Risk Assessment (BfR) maintains stricter maximum residue limits for processing aids than EU baseline standards, creating a dual-track compliance environment that favors suppliers with in-house analytical capabilities. Stakeholders must monitor pending EFSA opinions on betalain stability data and position their extraction technology investments before regulatory deadlines crystallize competitive moats.
Market Dynamics
The EU Green Deal's phased elimination of synthetic azo dyes is compressing reformulation timelines across European food manufacturing, redirecting procurement budgets toward beet-derived extraction technologies and rewiring supplier qualification protocols.
Growth Catalysts
- REACH chemical registration thresholds:ECHA's tightening purity specifications for synthetic food colorants are accelerating natural alternative qualification pipelines among mid-tier manufacturers seeking preemptive compliance.
- Bakery sector clean-label mandates:German and Dutch retail chains now require plant-derived colorant disclosure on packaged goods, pulling reformulation demand through the supply chain.
- Liquid betanin dosing systems:Continuous manufacturing line retrofits in dairy and beverage plants favor aqueous extraction formats that integrate with existing CIP infrastructure.
Market Restraints
- Beetroot input cost volatility:Weather-driven yield fluctuations in German and Dutch agricultural cooperatives create margin pressure on extraction facilities with fixed-price supply contracts.
- pH stability ceiling:Betanin's 4.0-7.0 functional range excludes high-acid applications below pH 3.5, ceding citrus and pickled product segments to anthocyanin alternatives.
- Extraction technology concentration:Proprietary aqueous extraction IP remains concentrated among three German and Dutch processor clusters, limiting new entrant scale-up velocity.
Strategic Opportunities
- Nutraceutical encapsulation formats:Beetroot nitrate-betanin synergy is driving softgel and tablet demand among sports nutrition formulators seeking dual-functional positioning.
- BfR analytical capability premium:Suppliers with in-house HPLC stability testing can command positioning in Germany's dual-track compliance environment where residue limits exceed EU baselines.
- Powder format dry-mix penetration:Water activity-stable betanin powders remain underrepresented in instant beverage and baking premix channels, opening premium positioning for spray-drying investments.
Industry Challenges
- Betalain stability data gaps:EFSA's pending re-evaluation timelines force suppliers to commit capital to accelerated degradation studies without confirmed regulatory deadlines.
- Legacy synthetic colorant inventory:Food manufacturers face stranded asset risk in existing Red No. 40 stockpiles as EU phase-out dates approach, complicating parallel run qualification schedules.
- Cross-batch color consistency:Agricultural beetroot variability requires real-time spectrophotometric adjustment during extraction, demanding skilled process engineering talent in short supply across Central European processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Betanin Food Color Market |
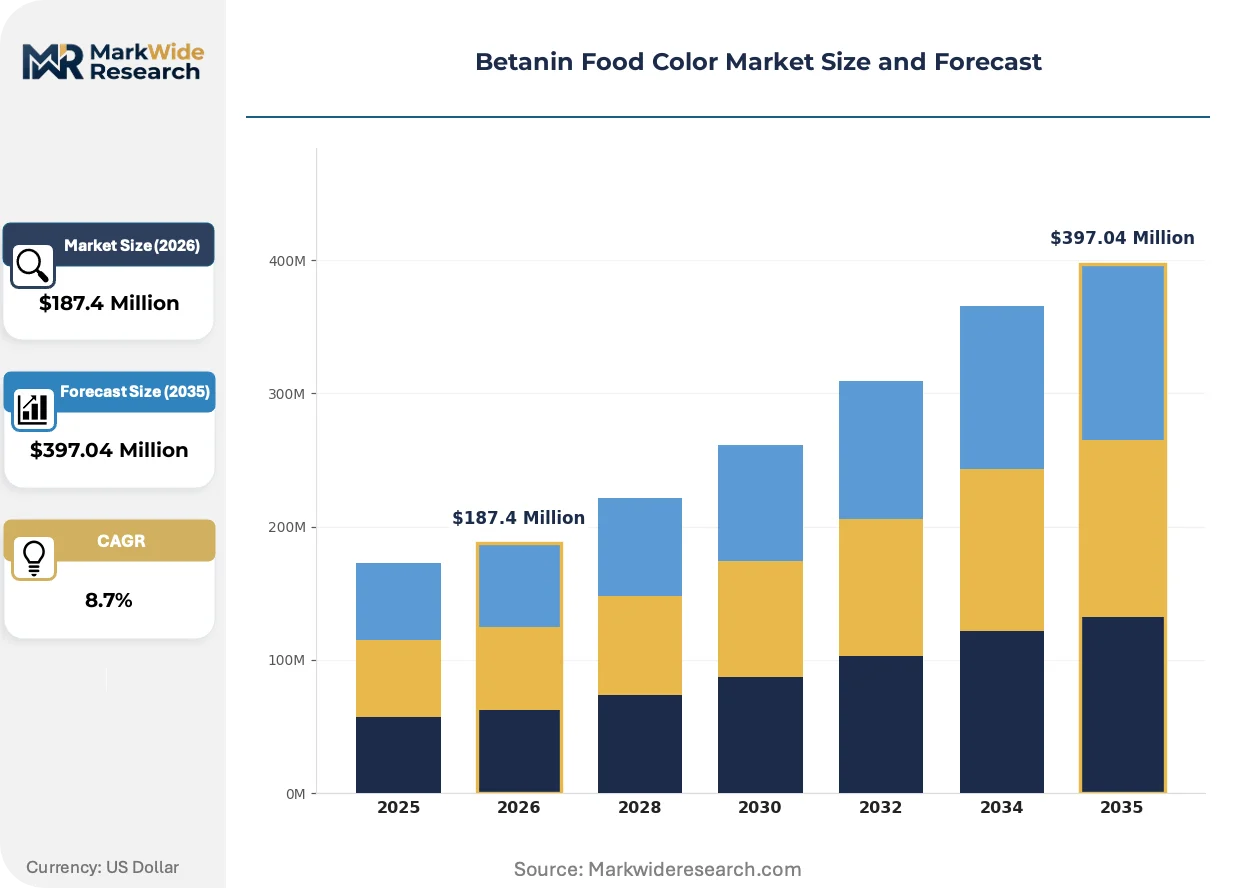
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Paste End User: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals Application: Bakery Products, Dairy Products, Confectionery, Beverages Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Döhler GmbH, Kalsec Inc., GNT Group, LAECO Corp., DDW The Color House, Oterra, Archer Daniels Midland Company, DSM, Sensient Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Betanin Food Color Market Strategic Shifts
Extraction technology refinement and regulatory chemistry are converging to redefine colorant performance benchmarks, while procurement protocols adapt to traceability requirements that synthetic alternatives cannot satisfy.
Membrane filtration concentration systems are expanding into commercial-scale betanin production, replacing thermal evaporation with low-temperature nanofiltration that preserves heat-labile betalain structures. German extraction facilities are retrofitting aqueous processing lines with ceramic membrane cascades, reducing energy input per unit color value by half. The technology is expanding into premium nutraceutical applications where degradation-sensitive nitrate retention commands formulation premiums.
EFSA's ongoing re-evaluation of synthetic dye safety profiles is compressing grandfathered approval timelines, indirectly accelerating natural colorant database submissions. Food manufacturers now face dual-track compliance where German BfR maximum residue limits exceed EU baseline standards, forcing suppliers to maintain parallel analytical protocols. Dairy and infant nutrition segments are responding with accelerated beet-derived reformulation to preempt liability exposure from pending azo dye restrictions.
Direct-supplier relationships are displacing distributor-mediated colorant procurement as traceability documentation requirements intensify. Large bakery and dairy manufacturers in the Netherlands and Germany now mandate farm-to-facility beetroot chain-of-custody records, bypassing traditional ingredient distributors. This pattern concentrates most visibly in private-label retail supply contracts where EUDR-aligned due diligence protocols require primary source verification.
Betanin Food Color Market Segmentation
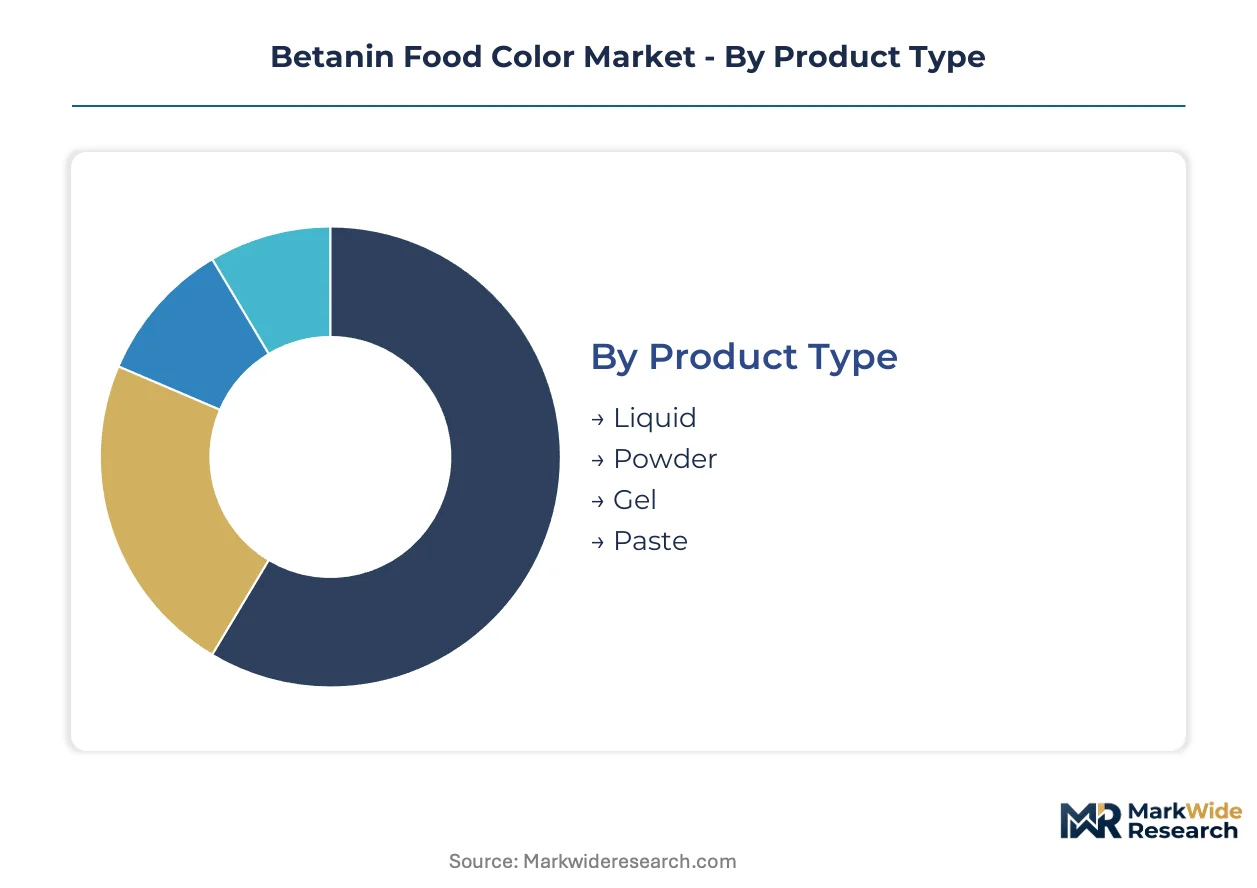
Betanin procurement patterns diverge sharply between high-volume liquid formats for continuous manufacturing and premium-positioned powders for dry-mix stability. Segmentation discipline reveals where extraction technology investments concentrate and which compliance thresholds filter supplier qualification.
Product Type:
Liquid formats dominate commercial volumes through dosing-line compatibility, while powder and gel variants occupy premium tiers defined by water activity constraints and shear-thinning requirements.
- Liquid:Aqueous extraction yields aqueous concentrates measured by E% color value at 535-540 nm wavelength, with pH buffering to 4.0-7.0 for neutral-to-acidic matrices. Dairy and beverage manufacturers in Germany deploy these formats through existing CIP infrastructure, pulled by clean-label mandates from Dutch and German retail chains.
- Powder:Spray-dried or freeze-dried formats achieve water activity stability below 0.6 for dry-mix applications where moisture migration degrades performance. Instant beverage premix and baking blend channels in the Netherlands favor these variants despite extraction energy premiums.
- Gel:Thickened aqueous suspensions with hydrocolloid stabilization for viscous dosing in confectionery and decorative icing applications.
- Paste:High-solids concentrates for artisan bakery and small-batch confectionery segments requiring spoonable consistency without dilution.
Mature deployment sits with Liquid. Newer deployment is concentrated in Powder.
End User:
Food and beverage manufacturers anchor baseline demand, while nutraceutical formulators drive specification tightening around nitrate-betanin synergy and encapsulation compatibility.
- Food & Beverage:Mature demand base spanning bakery, dairy, and beverage reformulation triggered by EU Green Deal synthetic dye phase-outs. German Federal Institute for Risk Assessment residue limits exceed EU baselines, filtering supplier qualification.
- Nutraceuticals:Sports nutrition and cardiovascular supplement segments exploit beetroot nitrate-betanin bioactive synergy. Softgel and tablet encapsulation demands accelerated degradation studies to satisfy EFSA stability data requirements.
- Cosmetics:Colorant applications in lip and cheek products where carmine replacement meets vegan positioning requirements.
- Pharmaceuticals:Excipient-grade colorant demand for tablet coating and liquid dosage forms with pharmacopeial monograph compliance.
Volume concentration remains in Food & Beverage. Steepest expansion trajectory appears in Nutraceuticals.
Application:
Bakery and dairy segments concentrate reformulation investment as retail chains mandate plant-derived colorant disclosure, while beverage applications face pH stability ceilings that exclude high-acid citrus matrices.
- Bakery Products:Clean-label mandates from German and Dutch retail chains pull reformulation through packaged goods supply chains. EU Green Deal azo dye reduction timelines compress qualification schedules for red velvet and fruit-flavored bakery applications.
- Dairy Products:Yogurt and flavored milk applications leverage betanin's 4.0-7.0 pH stability window without precipitation. Infant nutrition segments accelerate beet-derived adoption to preempt liability from pending synthetic dye restrictions.
- Confectionery:Hard candy and gummy applications where thermal stability during cooking limits betanin to low-temperature or surface-decoration uses.
- Beverages:Neutral pH fruit drinks and smoothies where anthocyanin alternatives dominate acidic citrus segments below pH 3.5.
Procurement scale concentrates in Bakery Products. Emerging specification intensity clusters in Dairy Products.
Distribution Channel:
Direct-supplier relationships displace traditional distribution as EUDR-aligned traceability requirements demand farm-to-facility chain-of-custody documentation.
- Direct Sales:Large bakery and dairy manufacturers in Germany and the Netherlands mandate primary source verification, bypassing distributors for beetroot cultivation records. Private-label retail contracts drive this pattern most visibly.
- Wholesalers:Remain relevant for mid-tier manufacturers lacking in-house analytical capabilities for BfR dual-track compliance testing.
- Online:E-procurement platforms serving small-batch artisan producers and R&D sampling requirements.
- Retail:Limited to hobbyist and small commercial bakery supply through specialty ingredient stores.
Established volume flows through Direct Sales. Channel experimentation is concentrated in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction facilities cluster around Hamburg and the Lower Saxony beet-growing belt, where German agricultural cooperatives supply raw material to integrated processors serving pan-European reformulation demand.
Germany
Clean-label mandates from Aldi and REWE compress bakery reformulation timelines, while the Federal Institute for Risk Assessment enforces dual-track residue limits exceeding EU baselines. Döhler GmbH operates aqueous extraction lines in Hamburg and Lower Saxony, leveraging captive beet supply from regional cooperatives.
Netherlands
GNT Group anchors color consistency standards through vertical control of Dutch beet cultivation, serving dairy manufacturers accelerating infant nutrition reformulation. The Dutch Food and Consumer Product Safety Authority enforces EUDR-aligned traceability protocols that bypass traditional distributors. Extraction facilities concentrate in Groningen and Flevoland polder regions with controlled irrigation infrastructure.
France
ANSM monitoring of synthetic dye safety profiles accelerates natural colorant qualification among Paris-region confectionery manufacturers. The EU Green Deal's azo dye reduction timeline forces stranded inventory decisions at legacy formulation facilities. Industrial beet processing clusters in Picardy and Champagne-Ardenne supply aqueous concentrates to dairy and beverage plants.
United Kingdom
Post-Brexit divergence from EFSA timelines creates parallel compliance tracks for FSA-registered colorant suppliers serving bakery and dairy reformulation. UK retail chains now mandate plant-derived disclosure on private-label packaged goods. Manufacturing concentrates in Yorkshire and the Midlands where continuous dosing line retrofits favor liquid betanin integration.
Italy
Specialty pasta and confectionery manufacturers in Emilia-Romagna accelerate carmine replacement programs to capture vegan positioning premiums. The Ministry of Health enforces EU baseline additive standards without German-style dual-track overlays. Extraction capacity remains limited, pulling supply from German and Dutch processor networks via direct procurement relationships.
Betanin Food Color Market Competitive Environment
The competitive structure tilts toward integrated extraction specialists with captive agricultural supply. German and Dutch processor clusters dominate aqueous extraction technology, while North American and Asian players compete on formulation services rather than primary extraction. Three archetypes define positioning: cooperative-integrated European processors, formulation-centric North American ingredient houses, and diversified global nutrition conglomerates. Capacity expansion and direct-supplier relationship building constitute the dominant competitive moves as traceability requirements intensify.
Among cooperative-integrated German processors, Döhler GmbH exemplifies the archetype of agricultural supply chain control, while Oterra occupies a parallel position through Danish-German extraction infrastructure. GNT Group anchors the Dutch vertical-integration model with beet cultivation direct ownership. Kalsec Inc. represents the North American formulation-specialist archetype, competing on application technology rather than primary extraction scale. These four patterns illustrate how geographic proximity to beet cultivation and regulatory stringency shape viable competitive positioning.
| Leading Market Players |
|---|
| Döhler GmbH |
| Kalsec Inc. |
| GNT Group |
| LAECO Corp. |
| DDW The Color House |
| Oterra |
| Archer Daniels Midland Company |
| DSM |
| Sensient Technologies |
| Others |
Value Chain & Pricing Dynamics
Family-owned German agricultural cooperatives anchor upstream beet supply, translating captive cultivation control into pricing discipline that resists commodity volatility while squeezing margin pressure onto non-integrated processors dependent on spot-market root procurement.
Pricing Analysis
Value-based pricing anchored to E% color value at 535-540 nm wavelength separates premium extraction batches from standard grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier (EFSA purity specifications versus baseline EU compliance) and volume scale commitments. Cost compression in economy-tier liquid concentrates is intensifying because membrane filtration technology diffusion erodes thermal evaporation cost advantages. Mid-tier bakery manufacturers exhibit highest price sensitivity, while infant nutrition formulators accept premium positioning for batch-to-batch consistency documentation.
Supply Chain Analysis
Skilled process engineering talent shortages in Hamburg and Lower Saxony constrain extraction facility expansion velocity, forcing German and Dutch processors to compete for spectrophotometric adjustment specialists. Raw material flows draw from German agricultural cooperatives in Lower Saxony and Dutch polder cultivation zones in Groningen and Flevoland. Single-source vulnerability concentrates in aqueous extraction IP held by three processor clusters. Distribution runs through direct-supplier relationships mandated by EUDR-aligned traceability protocols, displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's phased azo dye elimination constructs a cost-of-compliance moat where EFSA stability data requirements filter out capital-constrained entrants, privileging incumbents with in-house analytical infrastructure.
For Market Incumbents: Hedge against pH stability ceiling limitations by accelerating encapsulation technology R&D for nutraceutical softgel applications, while securing long-term supply contracts with German agricultural cooperatives to defend against weather-driven beetroot yield volatility threatening margin compression. For New Entrants and Emerging Players: E-procurement platforms serving small-batch artisan producers offer the most penetrable entry vector, targeting R&D sampling requirements and specialty baking premix channels in the Netherlands where direct-supplier traceability mandates have not yet displaced distributor relationships. For Investors and Strategic Acquirers: EFSA's pending re-evaluation timelines for synthetic dye safety profiles is the leading indicator that natural colorant qualification pipelines will experience capital deployment surges; position for five-to-ten year horizon viability by acquiring mid-tier processors with membrane filtration retrofit capability and existing BfR dual-track compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beet Cultivation | Captive supply from German agricultural cooperatives insulates margin pressure from weather-driven yield fluctuations. |
| Membrane Filtration Retrofit | Ceramic nanofiltration cascades halve energy input per unit color value versus thermal evaporation systems. |
| BfR Analytical Capability Investment | In-house HPLC stability testing commands premium positioning in Germany's dual-track compliance environment. |
| Powder Format Spray-Drying Expansion | Water activity-stable formats penetrate underrepresented instant beverage and baking premix channels. |
| Direct-Supplier Relationship Building | Farm-to-facility chain-of-custody documentation satisfies EUDR-aligned private-label retail contract requirements. |
Study Parameters
EFSA additive evaluations, ECHA REACH registration databases, and German BfR residue limit specifications formed the secondary backbone, cross-referenced with primary interviews involving extraction facility plant managers, procurement leads at pan-European dairy manufacturers, Dutch retail chain category buyers, and regulatory affairs specialists at natural colorant suppliers. Bottom-up volume modeling triangulated against top-down reformulation budget projections across the EU Green Deal implementation timeline.
Historical trendline analysis of synthetic dye phase-out patterns informed projection frameworks across product type, end-use industry, application segment, and distribution channel dimensions. CAGRs were derived from segmented growth rate aggregation weighted by procurement volume concentration. Forecast inputs incorporated EU Green Deal regulatory deadline assumptions and beetroot cultivation yield variance bands.
The model holds under stable EFSA re-evaluation timelines and cooperative weather patterns; deviation in accelerated synthetic dye bans or extreme drought cycles in German growing regions would shift volume trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
China Food Colorants Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Smoke Flavorings Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Salts and Flavored Salts Market
Flavorings and Food Additives
Mint Essential Oils Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Apple Essence Market