
 Manure Handling Equipment Market | 2026-2036
Manure Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Manure Handling Equipment Market Insights
Precision sensor integration and automated telemetry is reshaping manure handling equipment from passive hardware into data-driven nutrient management systems. Samson Agro leverages its Scandinavian engineering heritage to dominate high-capacity spreader segments across Northern European markets. GEA Group anchors its position through backward integration into dairy farm automation, bundling manure systems with milking parlors. Vogelsang competes through proprietary rotary lobe pump technology that handles high-fiber slurry without clogging.
Manure handling equipment encompasses mechanical and electromechanical systems designed to collect, transport, store, treat, and apply livestock waste, typically operating at throughput rates from 5 to 500 cubic meters per hour depending on farm scale and consistency of the slurry matrix. Its primary commercial purpose centers on converting animal waste into manageable organic fertilizer while controlling odor emissions, reducing groundwater contamination risk, and recovering biogas precursors. Pumps and spreaders command the largest installed base due to universal need across all livestock categories, though electric and solar-powered technology segments are gaining traction where grid access is limited or diesel costs strain operating budgets. Dairy farming applications generate the most specialized equipment demand because milking operations produce predictable daily waste volumes that justify capital-intensive automated scraping and separation systems.
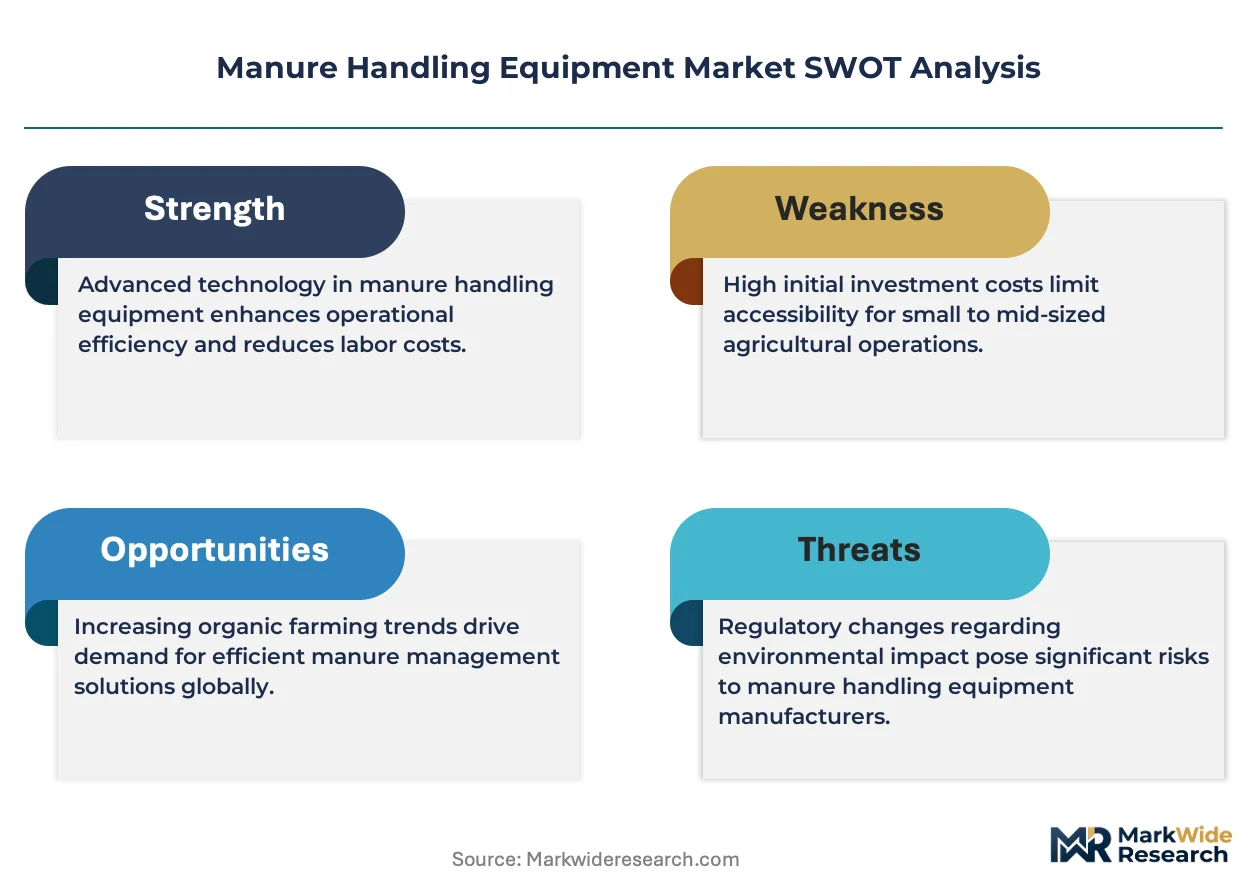
The US Environmental Protection Agency enforces Clean Water Act Concentrated Animal Feeding Operation rules that mandate nutrient management plans, directly shaping equipment specifications for lagoon agitation and precision application. In Europe, the EU Green Deal and national implementations of the Nitrates Directive in Germany, Denmark, and the Netherlands limit manure spreading periods and quantities, forcing upgrades to injection equipment and covered storage. China's Ministry of Ecology and Environment applies dual carbon goals to livestock zones, pushing anaerobic digester integration with handling systems. Stakeholders must monitor how tightening phosphorus caps and emerging carbon credit mechanisms for methane capture alter equipment selection criteria and service model economics.
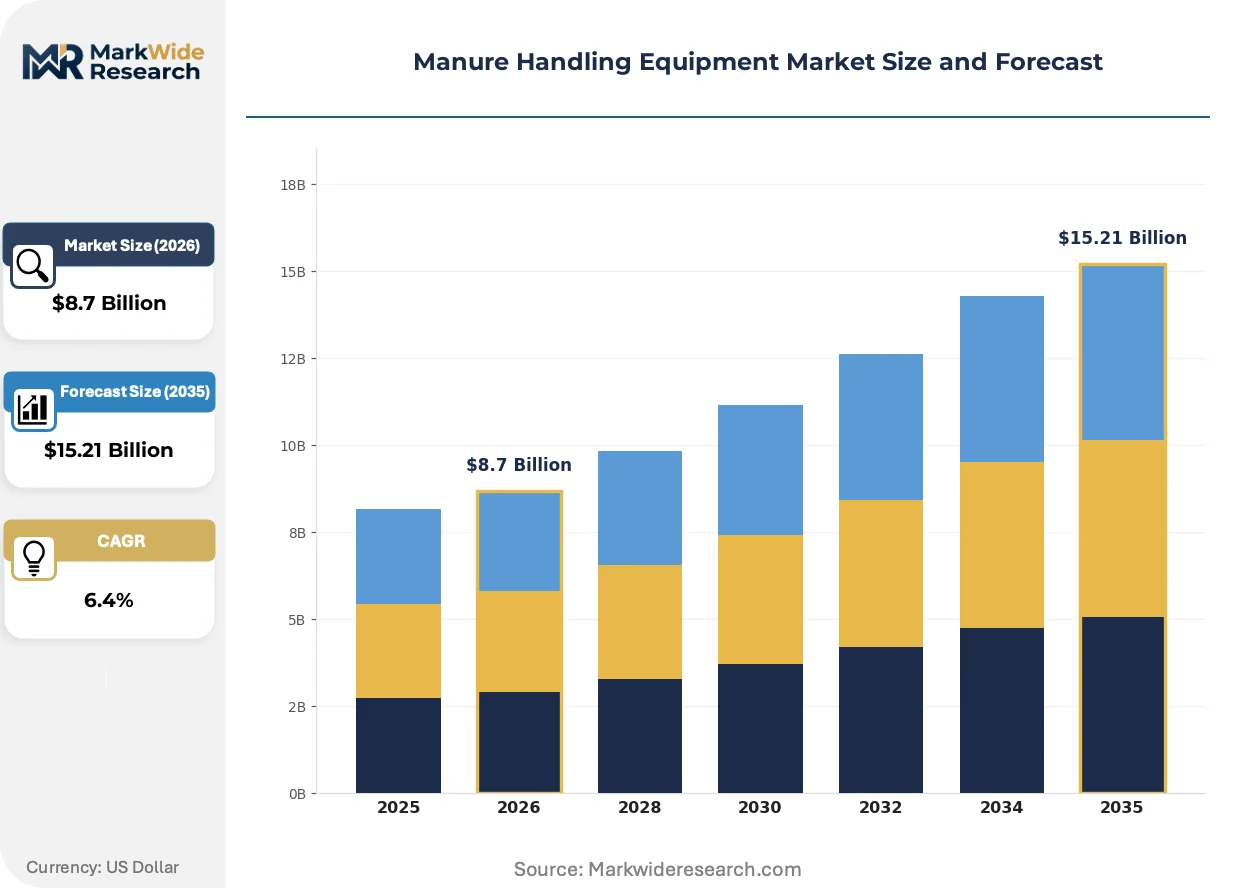
Market Dynamics
EU Green Deal nutrient management protocols are compressing discharge limits and mandating precision application infrastructure, forcing capital-intensive equipment upgrades across intensive livestock zones in Germany, Denmark, and the Netherlands.
Growth Catalysts
- EU Nitrates Directive implementation:Germany's tightened spreading windows and quantity caps are accelerating injection equipment replacement cycles.
- Biogas precursor recovery:Anaerobic digester integration with handling systems is expanding in dairy operations seeking methane capture revenue streams.
- Sensor-telemetry convergence:Precision nutrient mapping is enabling variable-rate application that cuts fertilizer input costs for arable farms.
Market Restraints
- Stainless steel input volatility:Fluctuating nickel and chromium prices destabilize manufacturing cost structures for pump and tank fabricators.
- High-fiber slurry technical limitation:Conventional centrifugal pumps face chronic clogging with straw-bedded dairy waste, restricting equipment options.
- Diesel cost pressure:Fuel price exposure strains operating budgets for tractor-drawn spreader fleets, delaying replacement decisions.
Strategic Opportunities
- Electric drivetrain white space:Battery-powered agitation and pumping systems are penetrating grid-connected farms in Denmark seeking diesel displacement.
- Carbon credit mechanism emergence:Verified methane capture protocols are creating new revenue attachment points for digester-integrated handling equipment.
- Service model unbundling:Equipment-as-a-service offerings are opening capital-constrained mid-scale dairy segments to automated scraping systems.
Industry Challenges
- Mechatronics skill scarcity:Maintenance of sensor-integrated telemetry systems requires technicians cross-trained in hydraulics and data diagnostics.
- CE-MDR certification timelines:Machinery directive compliance documentation is extending product launch cycles for novel pump architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manure Handling Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scrapers, Pumps, Conveyors, Loaders, Mixers, Spreaders Technology: Mechanical, Hydraulic, Pneumatic, Electric, Solar Powered Application: Dairy Farming, Poultry Farming, Swine Production, Aquaculture, Crop Farming End User: Farm Operators, Agricultural Contractors, Organic Growers, Livestock Integrators |
| Companies Covered | Samson Agro, GEA Group, Vogelsang, Joskin, Lely, Bauer Group, BouMatic, Valmetal, Patz Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manure Handling Equipment Market Trends and Innovations
Automation and electrification are reconfiguring equipment architecture from mechanical throughput systems to data-coupled nutrient management platforms that optimize application precision and environmental compliance.
Near-infrared spectroscopy sensors embedded in spreader booms are enabling real-time dry matter and nutrient content measurement during application. Large-scale arable contractors in the Netherlands are adopting these systems to satisfy variable-rate prescription maps. The technology is migrating from research demonstration plots to commercial fleet deployment, compressing the value capture window for traditional uniform-rate equipment.
The EU Green Deal's Farm to Fork strategy is tightening permissible nutrient loss thresholds and mandating covered storage infrastructure. Equipment specifications now prioritize injection depth and sealing mechanisms over broadcast width. German manufacturers are responding with trailing-shoe and shallow-disc injector variants purpose-built for grassland and row-crop regimes.
Consolidated dairy cooperatives are centralizing procurement decisions and unbundling after-sales service from capital purchase contracts. Independent dealer networks in Denmark face disintermediation pressure as buying groups negotiate direct manufacturer relationships for fleet standardization. This concentration is most visible in Jutland's cooperative-dominated dairy belt, where shared equipment pools reduce individual farm capital exposure.
Manure Handling Equipment Market Segmentation
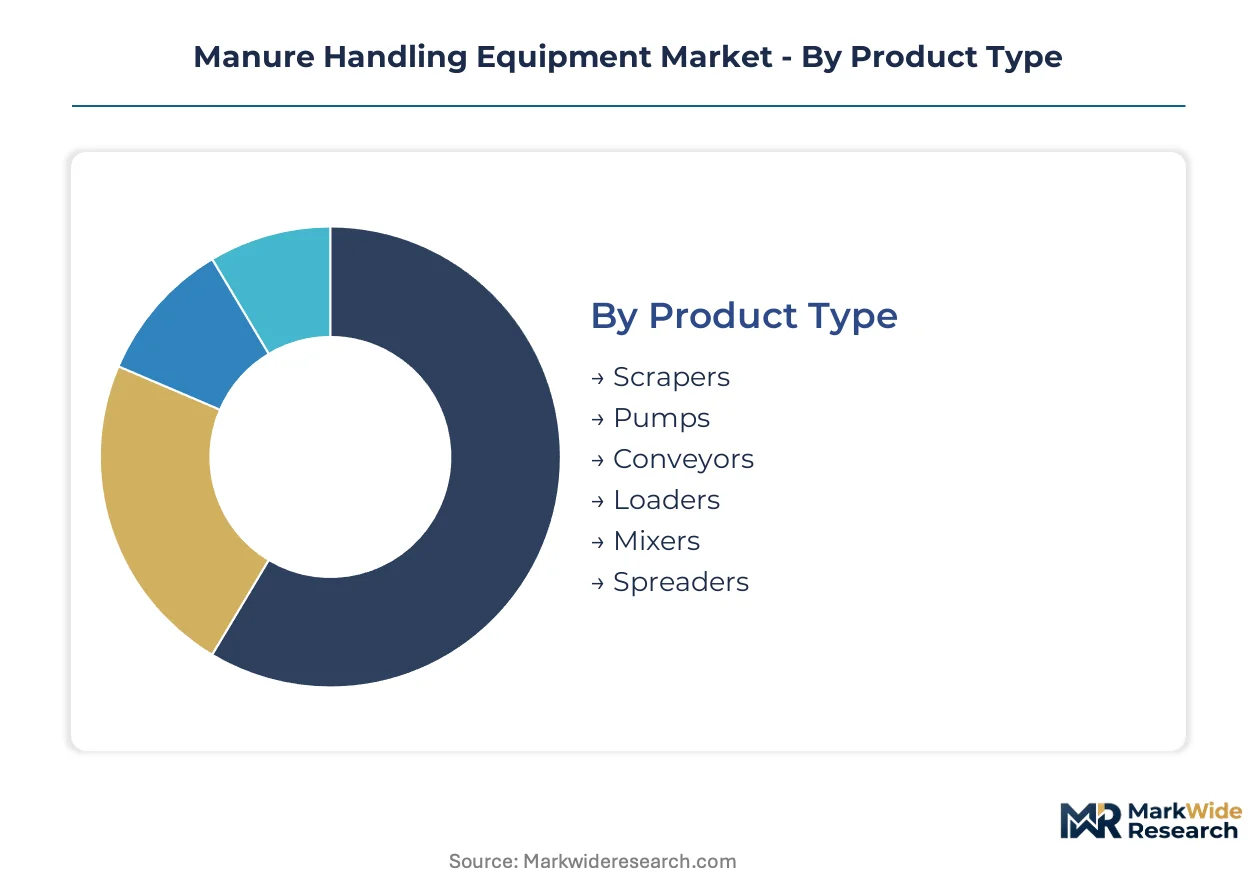
Equipment segmentation in manure handling reveals distinct replacement cycles and capital intensity patterns. Product type and technology choices directly determine maintenance burdens, energy costs, and compliance adaptability across livestock operations.
Product Type:
Replacement cycles vary dramatically across equipment categories, with high-wear components turning over every 3-5 years while structural systems persist for 15-20 years.
- Pumps:Rotary lobe and centrifugal designs handle slurry transport at 5-500 cubic meters per hour throughput rates. Dairy operations in Denmark and Germany concentrate demand for clog-resistant high-fiber variants as straw-bedded housing expands.
- Spreaders:Tractor-drawn tankers and trailing-shoe injectors dominate capital expenditure allocations in intensive livestock zones. Dutch arable contractors drive precision application upgrades as EU Green Deal nutrient caps tighten spreading windows and mandate injection depth standards.
- Scrapers:Automated alley-cleaning systems reduce labor exposure in confinement dairy barns.
- Conveyors:Auger and drag-chain systems move solid manure to storage or composting.
- Loaders:Front-end and specialized bucket configurations handle stacked solids.
- Mixers:Lagoon agitation equipment homogenizes slurry before pumping or spreading.
Spreaders anchor the volume base while pumps gain share at the steepest rate.
Technology:
Cost tiers separate premium sensor-integrated systems from basic mechanical alternatives, with electrification commanding 40-60% capital premiums over conventional drivetrains.
- Mechanical:Gearbox and chain-drive systems dominate installed base economics. German manufacturers maintain fabrication concentration for PTO-driven spreaders serving price-sensitive farm operators.
- Electric:Battery-powered agitation and pumping systems eliminate diesel cost exposure. Grid-connected dairies in Denmark adopt these for automated scraping systems where labor scarcity justifies capital intensity.
- Hydraulic:High-pressure circuits power heavy-duty loader and mixer functions.
- Pneumatic:Compressed-air systems serve specialized dry manure transport.
- Solar Powered:Off-grid photovoltaic arrays drive small-scale pumping where grid extension is uneconomical.
Mechanical systems retain the broadest installed base while electric configurations climb the fastest.
Application:
Customer maturity varies sharply, with dairy operations standardizing automated systems while aquaculture remains equipment-underserved.
- Dairy Farming:Predictable daily waste volumes justify capital-intensive automated scraping, separation, and digester-integrated handling. Milk production concentration in the Netherlands, Denmark, and Germany drives specification intensity for covered storage and precision injection.
- Swine Production:Slurry-dominant waste streams favor pump-and-store architectures. Slatted-floor confinement systems in intensive zones require specialized pit recharge and agitation equipment.
- Poultry Farming:Litter-based systems demand solid handling and composting infrastructure.
- Crop Farming:Manure importation for nutrient replacement uses contractor-operated spreading fleets.
- Aquaculture:Sediment and effluent handling remains technically distinct with limited equipment crossover.
Dairy farming anchors equipment revenue while swine production expands most quickly.
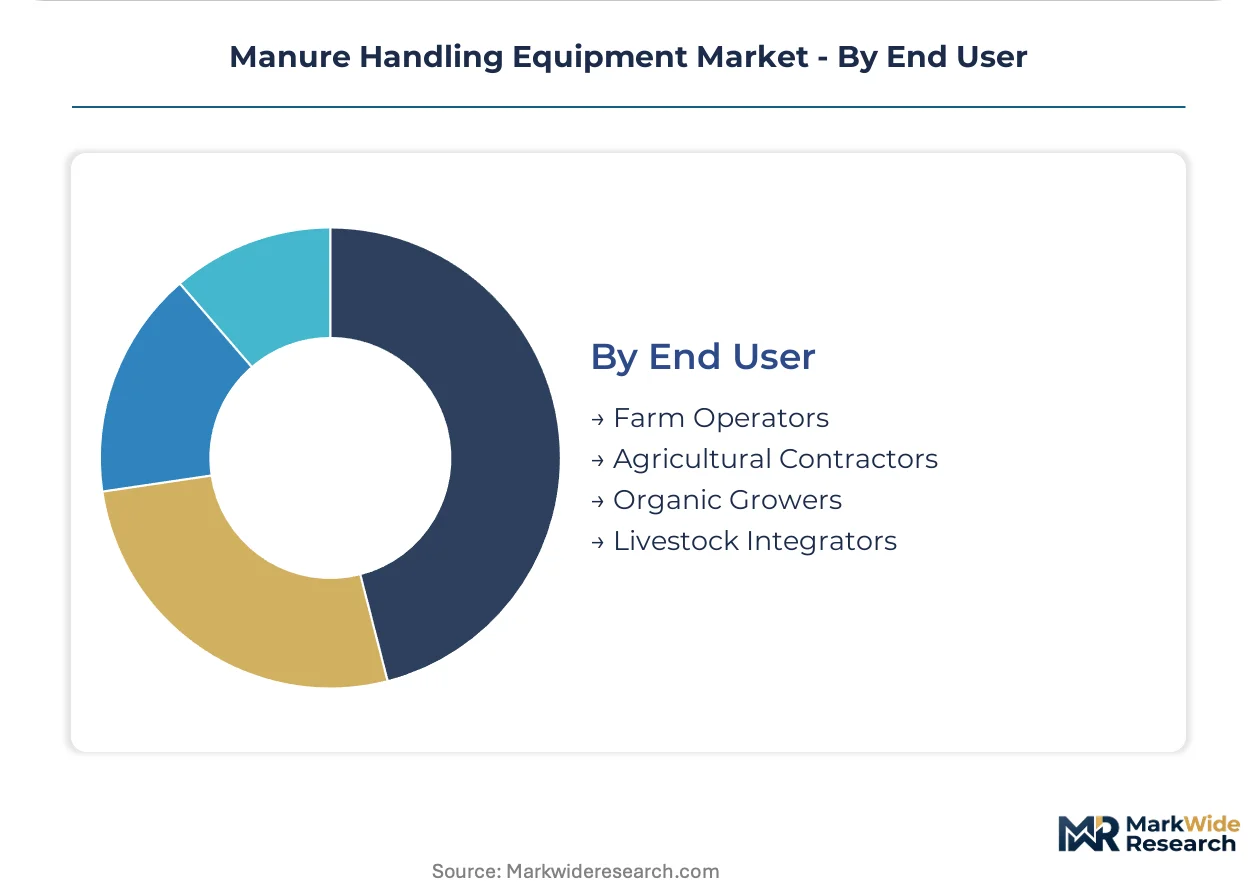
End User:
Procurement concentration is accelerating as cooperative buying groups displace individual farm decisions.
- Farm Operators:Owner-operated dairies and livestock farms make replacement decisions based on labor cost trade-offs. German family farms balance capital constraints against EU Nitrates Directive compliance deadlines.
- Agricultural Contractors:Fleet operators spread manure across multiple farms under service contracts. Dutch and Danish contractor consolidation drives standardization on high-capacity injection equipment with telemetry integration.
- Organic Growers:Certified operations prioritize composting and solid manure handling systems.
- Livestock Integrators:Corporate production systems centralize procurement for multiple facilities.
Farm operators retain the largest decision-making population while agricultural contractors capture the steepest share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision injection equipment to Dutch arable contractors facing EU Green Deal compliance deadlines. This trade corridor channels Northern European engineering into intensive livestock zones where nutrient caps are tightest.
Germany
Straw-bedded dairy housing expansion and biogas digester integration drive demand for clog-resistant high-fiber pump variants. The country's Federal Environment Agency enforces tightened spreading windows under the Nitrates Directive implementation. Bavaria's dairy belt concentrates specification intensity for covered storage and shallow-disc injector systems purpose-built for grassland regimes.
Netherlands
Arable contractor consolidation and cooperative procurement centralization accelerate fleet standardization on telemetry-integrated equipment. The Dutch government applies EU Green Deal Farm to Fork nutrient loss thresholds through national manure legislation. The Gelderland and Overijssel livestock corridors host dense contractor networks deploying variable-rate prescription mapping for precision application compliance.
Denmark
Grid-connected dairy automation and labor scarcity justify capital-intensive battery-powered agitation systems. The Danish Environmental Protection Agency administers strict ammonia emission ceilings aligned with EU Nitrates Directive caps. Jutland's cooperative-dominated dairy belt exhibits shared equipment pools that reduce individual farm capital exposure while standardizing on high-capacity injection fleets.
United States
Concentrated Animal Feeding Operation expansion and nutrient management plan mandates shape lagoon agitation and precision application specifications. The US Environmental Protection Agency enforces Clean Water Act rules requiring documented discharge controls. Wisconsin and California's Central Valley dairy clusters drive demand for automated scraping systems and covered storage infrastructure under state-level water quality enforcement.
China
Livestock zone consolidation and dual carbon goal implementation push anaerobic digester integration with handling systems. The Ministry of Ecology and Environment applies methane capture protocols to intensive production regions. Shandong and Sichuan provincial livestock belts concentrate state-backed equipment upgrading for pollution control and biogas precursor recovery.
Manure Handling Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a structure that concentrates premium-tier supply in Northern European engineering clusters while fragmenting mid-market mechanical fabrication. Consolidated dairy cooperatives and contractor buying groups displace independent dealer networks, compressing margin capture for non-integrated fabricators. Strategic archetypes separate backward-integrated dairy automation bundlers, proprietary pump technology specialists, and scale-driven tanker manufacturers. Dominant competitive moves include direct manufacturer relationships with cooperative procurement groups and geographic expansion through regional distributor acquisitions.
Among Scandinavian engineering-origin specialists, Samson Agro occupies a position exemplifying high-capacity spreader concentration across Northern European markets. German-based fabricators anchor the precision injection equipment segment serving Dutch and German compliance-driven replacement cycles. Within proprietary pump technology specialists, Vogelsang represents the rotary lobe architecture segment handling high-fiber slurry matrices without clogging failure modes.
| Leading Market Players |
|---|
| Samson Agro |
| GEA Group |
| Vogelsang |
| Joskin |
| Lely |
| Bauer Group |
| BouMatic |
| Valmetal |
| Patz Corporation |
| Others |
Pricing and Supply Chain Analysis
Stainless steel commodity volatility determines both capital equipment tier spreads and fabrication geography decisions for Northern European pump and tank manufacturers. Nickel and chromium price swings compress margin buffers on premium-grade stainless assemblies while pushing mid-market fabricators toward standardized carbon-steel alternatives with shorter replacement cycles.
Pricing Analysis
Current-generation electric drivetrain systems command 40-60% capital premiums over prior-generation mechanical PTO configurations, while next-generation solid-state battery architectures promise further cost compression. Three-tier pricing structure across premium sensor-integrated, standard hydraulic, and economy mechanical levels segments buyer pools by compliance urgency and labor substitution economics. Pricing pressure stems from cooperative procurement centralization in Denmark and the Netherlands, where buying groups extract volume discounts from manufacturers. Price-sensitive mid-scale dairy operators in Germany defer replacement cycles longest, while least-sensitive large arable contractors in the Netherlands prioritize telemetry integration regardless of capital cost.
Supply Chain Analysis
Export-control restrictions on precision sensor components limit telemetry system flows from US and Japanese suppliers to European equipment integrators. Manufacturing gravity centers on Germany, Denmark, and the Netherlands for high-specification injection equipment, while China anchors volume fabrication of standardized mechanical spreaders. Supply chains draw from stainless steel mills in Finland and Sweden, hydraulic component specialists in Italy, and sensor module producers in the USA. Single-source vulnerability concentrates in proprietary rotary lobe pump castings from specialized German foundries. Distribution runs through cooperative buying groups and independent dealer networks serving dairy belts in Jutland and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service revenue layers expand faster than hardware sales as Danish cooperatives unbundle capital purchase from maintenance contracts. Telemetry-enabled performance guarantees and predictive maintenance subscriptions capture recurring value from precision application compliance.
For Market Incumbents: Pre-empt disintermediation by cooperative buying groups through direct manufacturer relationships that bundle fleet standardization with captive service contracts. Backward integration into sensor calibration and data analytics capabilities defends margin position against emerging software-native competitors. Capacity addition in Poland and Romania addresses Eastern European dairy expansion while reducing exposure to German labor cost inflation. For New Entrants and Emerging Players: Pursue electric drivetrain white space in grid-connected Danish operations where diesel displacement mandates accelerate replacement demand. Battery-powered agitation systems for automated scraping applications represent the most penetrable segment given labor scarcity justification for capital intensity. Equipment-as-a-service go-to-market models bypass capital constraints among mid-scale German family farms facing EU Nitrates Directive deadlines. For Investors and Strategic Acquirers: EU Green Deal Farm to Fork implementation reshapes the acquisition landscape toward digester-integrated handling equipment with verified methane capture protocols. Long-term viability centers on platforms combining hardware throughput with nutrient management software and carbon credit verification services. Acquisition target archetype: mid-cap specialists with proprietary pump technology and established dealer relationships in Germany or the Netherlands. Watch ammonia emission ceiling tightening in Denmark as the signal for accelerated injection equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captures telemetry margin from Dutch cooperative procurement centralization. |
| Equipment-as-a-Service Launch | Opens capital-constrained German mid-scale dairy segments to automated systems. |
| Electric Drivetrain Platform Development | Addresses Danish grid-connected automation demand and diesel displacement mandates. |
| Digestor Integration Partnership | Attaches carbon credit revenue streams to handling equipment in biogas zones. |
| Regional Distributor Acquisition | Secures channel control in Jutland's cooperative-dominated dairy belt. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of equipment manufacturer filings, EU regulatory databases, and agricultural cooperative procurement records. Primary interviews engaged dairy farm operators, agricultural contractor fleet managers, OEM procurement specialists, and aftermarket service directors across Germany, Denmark, and the Netherlands. Secondary validation drew from Federal Environment Agency implementation guidance, Danish Environmental Protection Agency emission inventories, and machinery directive certification documentation. Bottom-up equipment shipment data triangulates against top-down nutrient management plan filings and biogas digester installation records.
Forecast inputs include equipment replacement cycle modeling by product category, technology adoption curves for electric drivetrains, and regulatory compliance deadline phasing across EU member states. Segmentation dimensions span product type, technology generation, livestock application, and end-user procurement concentration. CAGRs derive from installed base turnover rates, capital expenditure surveys, and cooperative buying group fleet standardization timelines. Industry-specific inputs incorporate EU Green Deal nutrient loss threshold tightening schedules and methane capture verification protocol development.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity prices, diesel cost trajectories, or agricultural credit availability would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement consistency and cooperative procurement centralization pace. Material shifts in EU Nitrates Directive implementation timelines or carbon credit mechanism design would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Destoner Machine Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Maize Milling Machine Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Rice Processing Machine Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Poultry Processing Equipment Market
Agricultural Processing Equipment
India Rice Milling Market