
 China Agricultural Shredder Machine Market | 2026-2036
China Agricultural Shredder Machine Market Size, Share, and Industry Trends Forecast 2026-2036
China Agricultural Shredder Machine Market Insights
China's tightened straw-burning prohibitions under environmental enforcement protocols is realigning the cost-of-entry calculus for agricultural shredder procurement across provincial farm bureaus. Changzhou Dongfeng Agricultural Machinery Group leverages its vertical integration into engine and chassis production to sustain price competitiveness in county-level tender markets. Weichai Lovol Intelligent Agricultural Technology anchors its position through R&D intensity in automated feeding mechanisms for high-moisture crop residue. Kubota China Holdings competes on brand strength and channel control, dominating premium segments in coastal province dealership networks.
Agricultural shredder machines are mechanical devices equipped with rotary blade assemblies, hammer mills, or flail systems powered by diesel engines or electric motors, designed to reduce crop residue, stalks, branches, and organic waste into uniform particulate matter for mulch, compost feedstock, or biomass fuel preparation. Operating capacities range from small-scale units processing under two tons per hour to industrial-scale systems exceeding fifteen tons per hour with hydraulic feed controls and reversible grates for contamination ejection. Diesel shredders occupy the dominant installed base across remote township operations where grid connectivity remains unreliable, while smart shredding systems integrating torque sensors and automatic feed rate adjustment represent the fastest-growing technology tier. Medium-scale capacity units command concentrated margin pools among agricultural cooperatives seeking fleet standardization between individual farm plots and centralized processing stations.
China's Ministry of Ecology and Environment enforces straw-burning bans through satellite monitoring and provincial penalty structures, while SAMR administers GB standards for agricultural machinery safety and electromagnetic compatibility, collectively elevating compliance costs for uncertified equipment entrants. The National Development and Reform Commission channels subsidies through provincial agricultural mechanization bureaus, conditioning equipment eligibility on energy-efficiency benchmarks and localized manufacturing content thresholds. Stakeholders must monitor evolving subsidy catalog revisions and carbon-accounting methodologies for biomass utilization to anticipate demand shifts between combustion feedstock and soil-amendment applications.
Market Dynamics
China's dual carbon goals and provincial straw-burning enforcement are restructuring capital allocation across agricultural mechanization fleets, forcing cooperatives to replace open-field combustion with compliant shredding infrastructure ahead of subsidy eligibility deadlines.
Growth Catalysts
- Henan Province mechanization mandates:Agricultural cooperatives in this wheat-corn rotation belt are expanding centralized processing stations under provincial fleet standardization programs.
- MEE satellite monitoring enforcement:Real-time detection of illegal straw burning triggers penalty structures that redirect farm investment toward certified shredding equipment.
- High-moisture rotary systems:Automated feeding mechanisms now handle fresh crop residue without pre-drying, cutting operational labor by half.
Market Restraints
- Diesel engine cost volatility:Fluctuations in refined fuel pricing squeeze operating margins for remote township operations lacking grid alternatives.
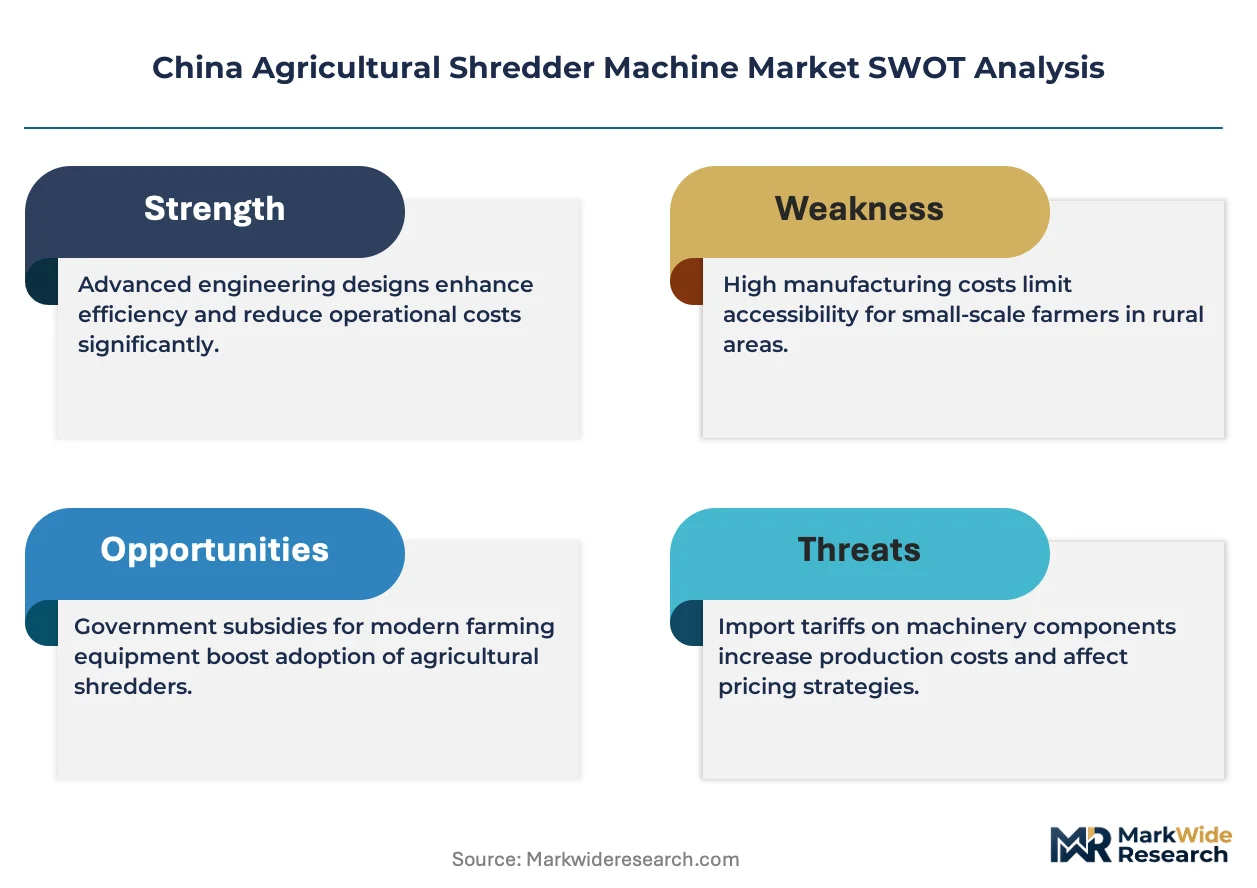
- Changzhou manufacturing cluster concentration:Component sourcing dependence on a single Jiangsu province hub creates supply vulnerability during peak procurement seasons.
- GB standard compliance friction:SAMR electromagnetic compatibility certification timelines extend equipment approval cycles by four to six months.
Strategic Opportunities
- Shandong biomass-to-energy corridor:Untapped demand exists for industrial-scale systems serving combined heat and power plants in this coastal province.
- Carbon-accounting methodology convergence:MEE protocols for soil-carbon sequestration credit verification will favor shredding over combustion feedstock applications.
- Smart torque-sensor integration:Machine learning feed-rate optimization is converging with hydraulic control systems to enable unmanned operation.
Industry Challenges
- Hydraulic systems technician scarcity:County-level service networks lack certified repair capacity for high-capacity shredder maintenance.
- Legacy diesel-to-electric retrofit complexity:Grid connectivity gaps in Hebei province townships block straightforward powertrain substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Agricultural Shredder Machine Market |
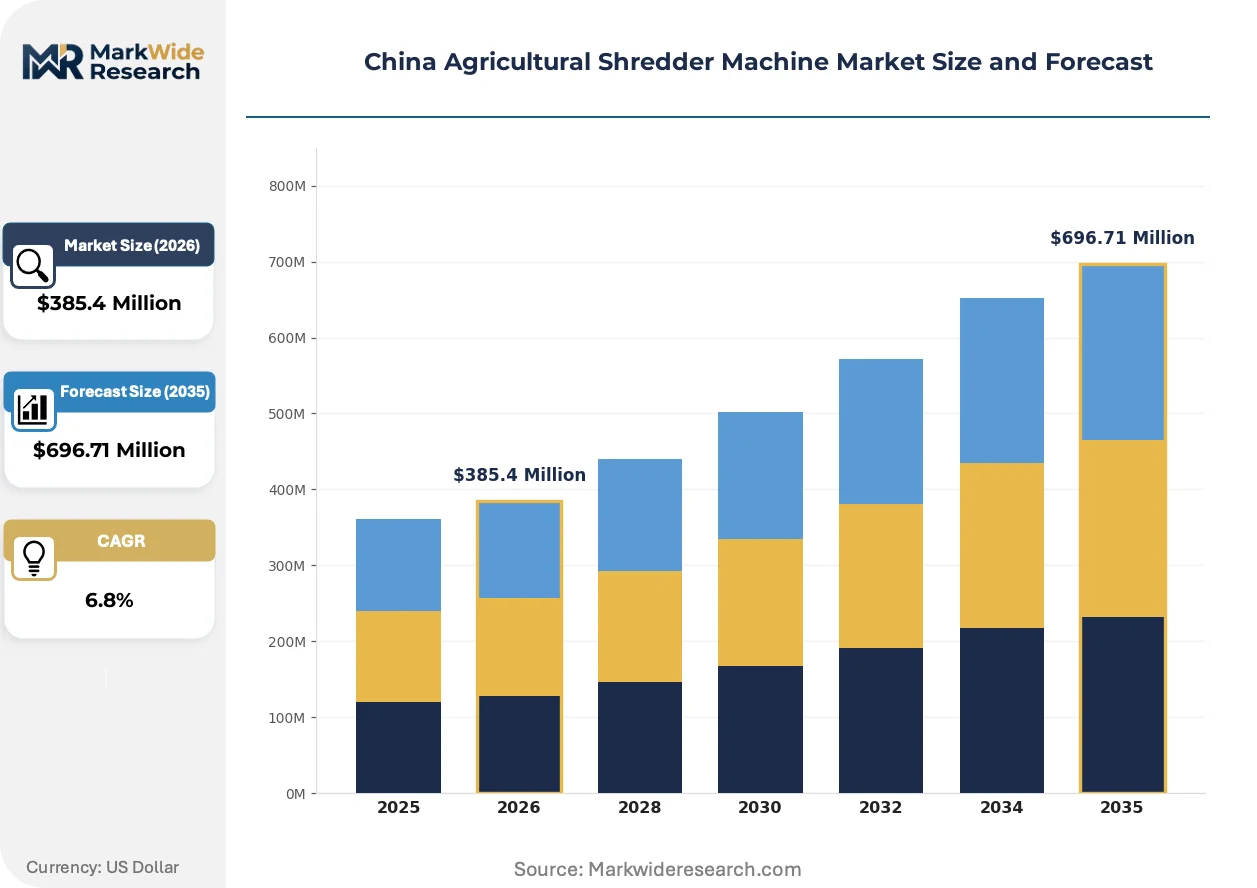
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Shredder, Diesel Shredder, Manual Shredder, Heavy-Duty Shredder End User: Farmers, Agricultural Cooperatives, Landscaping Services, Food Processing Companies Technology: Conventional, Advanced Automation, Hybrid, Smart Shredding Capacity: Small Scale, Medium Scale, Large Scale, Industrial Scale |
| Companies Covered | Changzhou Dongfeng Agricultural Machinery Group Co., Ltd, Weichai Lovol Intelligent Agricultural Technology Co., Ltd., Kubota China Holdings Co., Ltd., John Deere China (Investment) Co., Ltd., Jiangyin Unite Top Heavy Industry Co., Ltd., Zhengzhou Kowloon Machinery Equipment Co., Ltd., Tirox (Zhengzhou) Equipment Co., Ltd., Changzhou Qianyi Machinery Technology Co., Ltd., Yancheng Newbang Machinery Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Agricultural Shredder Machine Market Trends and Innovations
Smart shredding systems with automated feed control are compressing the performance gap between manual and autonomous operation, while regulatory pressure on residue management accelerates equipment replacement cycles beyond traditional depreciation schedules.
Intelligent torque-sensing rotary assemblies are overtaking conventional fixed-speed hammer mills in cooperative fleet procurement. These systems detect fiber density in real time and adjust blade speed to prevent jamming. Large-scale operators in Shandong and Hebei are specifying this technology in centralized tender documents. The shift is compressing margins for basic mechanical units while elevating service-contract revenue streams.
GB standards administered by SAMR now mandate electromagnetic compatibility testing for all agricultural machinery with electronic control modules. This elevates compliance costs for uncertified equipment and accelerates consolidation among smaller assemblers lacking in-house testing facilities. Shandong province agricultural mechanization bureaus are conditioning subsidy eligibility on full GB certification completion.
Cooperative procurement committees are consolidating purchasing authority previously dispersed across individual farm plots. County-level agricultural bureaus in Henan now negotiate fleet contracts covering fifty to one hundred units, replacing fragmented single-machine transactions. This concentration shifts bargaining power toward buyers and pressures distributors to unbundle after-sales service from equipment pricing.
China Agricultural Shredder Machine Market Segmentation
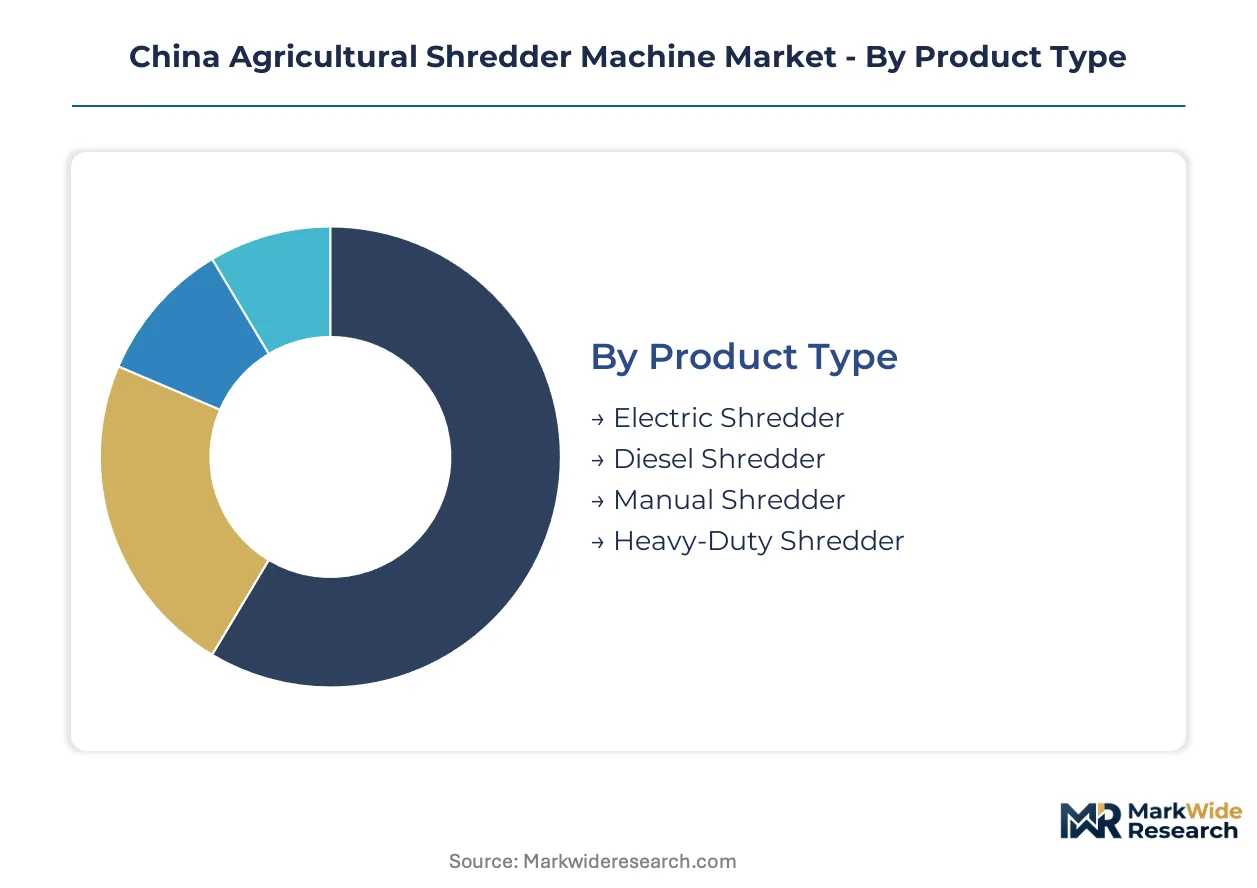
Segmentation in China's agricultural shredder market reveals divergent capital requirements and operational constraints across buyer types and technology tiers. Equipment procurement decisions hinge on grid connectivity, residue volume, and subsidy eligibility rather than price alone. Understanding these fault lines clarifies where manufacturers must concentrate R&D and distribution investments.
Product Type:
Capital intensity varies sharply across powertrain configurations, with diesel units demanding the highest upfront outlay for engine compliance and fuel storage infrastructure.
- Diesel Shredder:These units integrate water-cooled diesel engines rated 15-75 horsepower with hydraulic feed systems and reversible grates for contamination ejection. Demand concentrates in Hebei and Henan province townships where grid reliability remains sporadic; MEE enforcement of straw-burning bans accelerates fleet replacement cycles for these workhorse machines.
- Electric Shredder:Three-phase induction motors paired with variable-frequency drives deliver torque-controlled shredding without exhaust emissions. Shandong coastal counties with stable grid access favor these units for centralized processing stations; dual carbon goals channel subsidy preference toward electrified equipment in these zones.
- Manual Shredder:Hand-cranked rotary blade assemblies serve individual farm plots under two hectares with minimal capital outlay.
- Heavy-Duty Shredder:Reinforced chassis and dual-rotor configurations process woody biomass and mixed agricultural waste.
Most installed capacity flows through diesel shredders. Expansion is steepest in electric shredders.
End User:
Procurement scale and technical sophistication separate buyer segments, with cooperatives wielding concentrated purchasing power against fragmented individual farmers.
- Agricultural Cooperatives:Fleet buyers operating centralized processing stations across fifty to one hundred member farms negotiate volume contracts with hydraulic maintenance riders. Henan Province cooperatives drive standardization mandates; county-level agricultural bureaus consolidate tender authority previously dispersed across individual plots.
- Farmers:Individual operators of under ten hectares purchase small-scale units through township distributor networks. Hebei province townships show rising demand for compact diesel units; grid connectivity gaps block straightforward electrification for this segment.
- Landscaping Services:Municipal and commercial grounds maintenance contractors require portable, low-decibel equipment for urban green waste.
- Food Processing Companies:Agro-industrial facilities generate organic waste streams requiring continuous-duty shredding capacity.
Cooperative procurement now dominates volume transactions. Farmer-level demand is expanding most quickly as subsidy thresholds lower entry barriers.
Technology:
Automation depth determines pricing tiers and service revenue potential, with sensor-integrated systems commanding premium positioning.
- Smart Shredding:Machine learning algorithms optimize feed rates against real-time torque sensor data, enabling unmanned operation with jam prediction. Large-scale operators in Shandong specify this technology in centralized tenders; GB electromagnetic compatibility certification from SAMR conditions subsidy eligibility on these control modules.
- Advanced Automation:Programmable logic controllers manage hydraulic feed and reversible grate sequencing without full autonomy. Agricultural cooperatives in the North China Plain wheat-corn belt favor this mid-tier automation; automated feeding mechanisms cut operational labor by half for high-moisture residue.
- Hybrid:Dual-power configurations switch between diesel and electric operation based on grid availability.
- Conventional:Fixed-speed mechanical drives with manual feed control serve price-sensitive buyers in remote counties.
Conventional systems retain the largest installed base. Smart shredding is gaining share fastest as cooperative procurement committees specify intelligent torque-sensing assemblies.
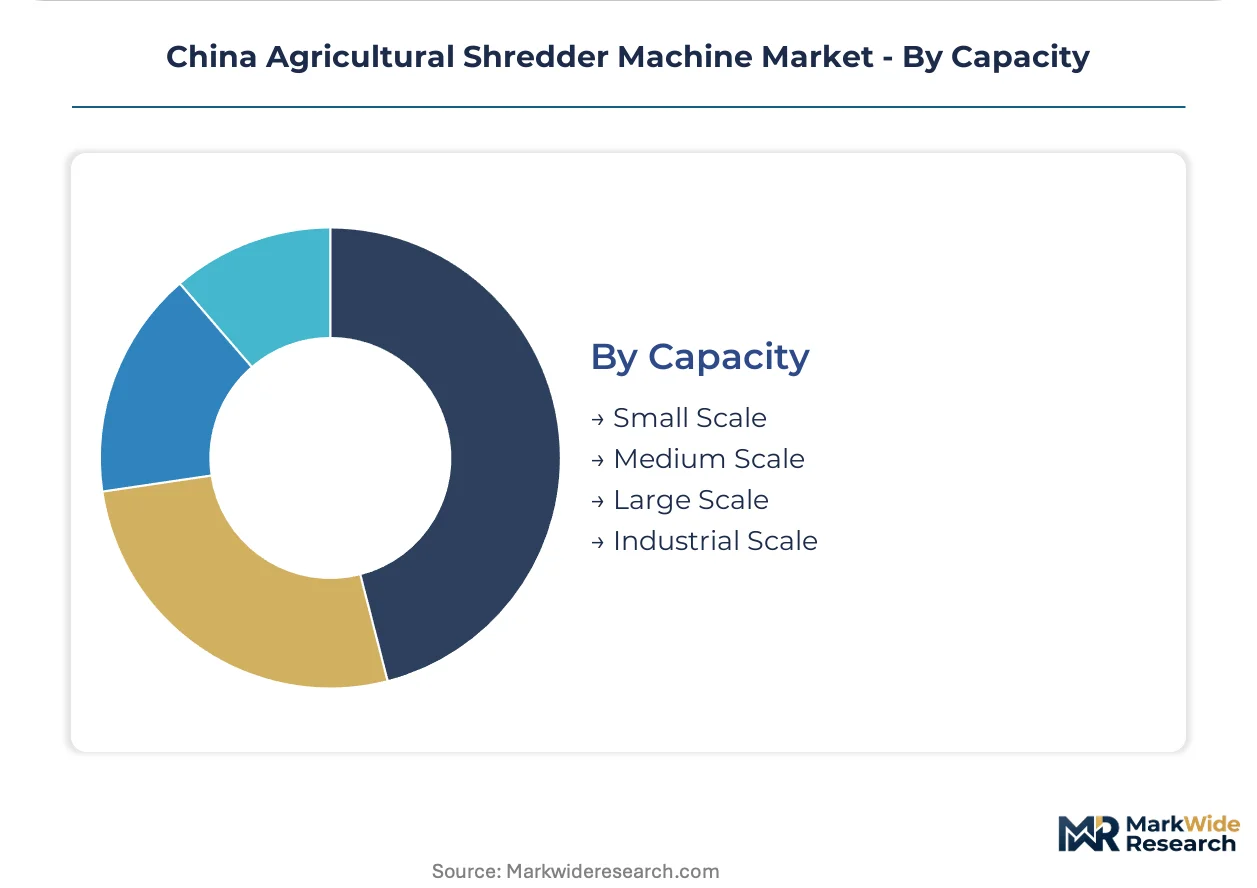
Capacity:
Throughput specification aligns with operational model scale, from plot-level residue management to industrial biomass feedstock supply.
- Medium Scale:Units processing two to eight tons per hour with hydraulic feed controls dominate cooperative fleet standardization programs. These systems balance mobility against throughput for centralized processing stations serving multiple member farms; margin pools concentrate here as buyers seek standardized maintenance protocols.
- Industrial Scale:Systems exceeding fifteen tons per hour with automated feed rate adjustment serve biomass-to-energy corridors. Shandong combined heat and power plants drive untapped demand; carbon-accounting methodology convergence for soil-carbon sequestration will favor shredding over combustion applications.
- Small Scale:Under two tons per hour capacity suits individual farm plots and landscaping contractors.
- Large Scale:Eight to fifteen tons per hour bridges cooperative and industrial applications with reversible grate contamination ejection.
Medium-scale units carry the heaviest procurement volume. Industrial-scale systems show the steepest expansion trajectory as provincial biomass energy targets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial agricultural mechanization bureaus anchor demand concentration across China's wheat-corn rotation belt. County-level procurement committees now consolidate tender authority previously dispersed across individual farm plots.
Henan Province
Agricultural cooperatives in this wheat-corn rotation belt are expanding centralized processing stations under provincial fleet standardization programs. The provincial agricultural mechanization bureau channels NDRC subsidies toward medium-capacity hydraulic shredders. Zhengzhou-based equipment distributors coordinate county-level tender negotiations covering fifty to one hundred units per contract.
Shandong Province
Coastal counties with stable grid access favor electric shredders for biomass-to-energy corridors serving combined heat and power plants. SAMR GB standards for electromagnetic compatibility condition subsidy eligibility on certified control modules. Qingdao and Yantai manufacturing clusters supply reinforced chassis systems to industrial-scale operators.
Hebei Province
Remote townships lacking reliable grid connectivity sustain diesel shredder demand despite fuel cost volatility. MEE satellite monitoring enforcement triggers penalty structures that redirect farm investment toward certified equipment. Baoding and Shijiazhuang county bureaus negotiate fleet contracts with hydraulic maintenance riders.
Jiangsu Province
The Changzhou manufacturing cluster concentrates component sourcing for rotary blade assemblies and hammer mill systems. Provincial dual carbon goals channel preference toward electrified equipment in grid-stable zones. Nanjing and Suzhou agricultural cooperatives specify smart torque-sensing technology in centralized tenders.
China Agricultural Shredder Machine Market Competitive Landscape
The competitive structure tilts toward domestic machinery conglomerates with captive engine production. State-affiliated agricultural equipment groups and foreign joint ventures occupy distinct tier positions. Three archetypes dominate: vertically integrated domestic champions, technology-licensing foreign entrants, and component-specialist assemblers. Capacity expansion and backward integration into powertrain manufacturing represent the dominant competitive moves.
Among domestic fabricators, Changzhou Dongfeng Agricultural Machinery Group Co., Ltd. and Weichai Lovol Intelligent Agricultural Technology Co., Ltd. exemplify the integrated champion archetype through in-house production of engines and chassis systems. Kubota China Holdings Co., Ltd. occupies a position within the premium-tier foreign joint venture segment. These three anchors illustrate how provincial tender markets reward manufacturing depth while coastal dealership networks reward brand strength.
| Leading Market Players |
|---|
| Changzhou Dongfeng Agricultural Machinery Group Co., Ltd |
| Weichai Lovol Intelligent Agricultural Technology Co., Ltd. |
| Kubota China Holdings Co., Ltd. |
| John Deere China (Investment) Co., Ltd. |
| Jiangyin Unite Top Heavy Industry Co., Ltd. |
| Zhengzhou Kowloon Machinery Equipment Co., Ltd. |
| Tirox (Zhengzhou) Equipment Co., Ltd. |
| Changzhou Qianyi Machinery Technology Co., Ltd. |
| Yancheng Newbang Machinery Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Steel price indices and diesel fuel benchmarks cascade through agricultural shredder manufacturing into three distinct pricing tiers shaped by powertrain configuration and after-sales bundling. Changzhou-based fabricators absorb raw material volatility through backward integration into rotary blade forging, while county-level distributors unbundle hydraulic maintenance contracts to preserve margin in competitive tender markets.
Pricing Analysis
The bundled-versus-unbundled service split separates premium positioning from economy-tier competition across China's provincial procurement committees. Three-tier pricing structure across premium, standard, and economy levels aligns with SAMR GB certification completion and smart torque-sensor integration depth. Price differentiation rests on electromagnetic compatibility certification status and hydraulic maintenance rider inclusion. Cost compression in economy diesel units is intensifying because of refined fuel price volatility and subsidy eligibility threshold tightening. Individual farmers in Hebei townships exhibit highest price sensitivity, while Henan agricultural cooperatives prioritize fleet standardization over unit cost.
Supply Chain Analysis
GB electromagnetic compatibility certification from SAMR gates component sourcing for electronic control modules, filtering uncertified assemblers from subsidy-eligible supplier pools. Manufacturing concentrates in China, with South Korea and Japan supplying precision torque sensors and variable-frequency drive systems. Raw material flows draw from Jiangsu province steel mills, Anhui casting foundries, and Shandong hydraulic component specialists. Single-source vulnerability concentrates in Changzhou rotary blade forging capacity during peak procurement seasons. Distribution runs through Zhengzhou and Jinan equipment distributors serving county-level agricultural mechanization bureaus.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's agricultural shredder market functions as a stable compounder anchored by irreversible environmental enforcement tightening straw-burning prohibitions across the North China Plain. Provincial subsidy catalog revisions and carbon-accounting methodology convergence generate predictable equipment replacement cycles.
For Market Incumbents: Acquire hydraulic systems service networks to lock in cooperative fleet contracts before technician scarcity worsens in Hebei and Henan counties. Integrate captive diesel engine production to buffer fuel cost volatility squeezing remote township operators. SAMR electromagnetic compatibility certification timelines threaten smaller assemblers lacking in-house testing facilities.
For New Entrants and Emerging Players: MEE satellite monitoring enforcement in China opens a window for smart shredding systems with automated feed control in Shandong biomass-to-energy corridors. Target industrial-scale capacity segments serving combined heat and power plants with unmanned operation specifications. Partner with Qingdao manufacturing clusters for reinforced chassis supply to bypass Changzhou component sourcing dependence.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier automation specialists bridging conventional mechanical drives and full smart shredding autonomy. Long-term viability over a five-to-ten-year window favors manufacturers with dual carbon goal alignment and provincial subsidy catalog positioning. Watch MEE soil-carbon sequestration credit verification protocols as the inflection signal shifting demand from combustion feedstock toward soil-amendment applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engine Production | Captive diesel powertrain supply buffers fuel cost volatility for remote township operators. |
| Smart Torque-Sensor Platform Development | Machine learning feed-rate optimization enables unmanned operation in cooperative fleet tenders. |
| Hydraulic Service Network Acquisition | County-level maintenance capacity scarcity threatens uptime guarantees for high-capacity shredders. |
| GB Electromagnetic Compatibility Certification | SAMR mandates condition NDRC subsidy eligibility on completed testing protocols. |
| Industrial-Scale Capacity Expansion | Shandong biomass-to-energy corridors drive untapped demand for fifteen-ton-per-hour systems. |
Research Methodology
Multiple input streams — provincial agricultural mechanization bureau procurement records, SAMR certification databases, and NDRC subsidy catalog revisions — were reconciled against primary interviews with equipment distributors, cooperative procurement committee heads, hydraulic systems technicians, and Changzhou manufacturing cluster managers. Secondary validation drew from customs trade data, agricultural machinery safety standards, and provincial environmental enforcement protocols. Bottom-up unit shipment tallies across Henan, Shandong, and Hebei counties were triangulated against top-down market sizing from powertrain configuration splits.
Historical shipment trajectories were cross-referenced against panel input from OEM procurement directors and county-level tender documentation to anchor projection assumptions across the analysis window. Segmentation modeling captured powertrain type, automation technology tier, capacity specification, and end-user archetype. CAGRs were derived from equipment replacement cycle compression under MEE enforcement tightening and subsidy eligibility deadline clustering. Forecast inputs incorporated diesel-electric powertrain substitution elasticity and smart shredding adoption curves in cooperative fleet standardization programs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt NDRC subsidy withdrawal or Changzhou supply disruption during peak procurement seasons. Model assumptions reflect documented provincial fleet standardization mandates and carbon-accounting methodology convergence timelines. A model refresh is warranted upon material change in MEE soil-carbon sequestration credit verification protocols or SAMR electromagnetic compatibility certification timeline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Rice Milling Machines Market
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Asia-Pacific Agricultural Shredder Machine Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Poultry Processing Equipment Market
Agricultural Processing Equipment
Combine Harvesters Market
Agricultural Processing Equipment
Meat Cutting Machine Market
Agricultural Processing Equipment
Rice Milling Machinery Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Global Square Straw Baler Market
Agricultural Processing Equipment
Meat Processing Equipment Market