
 Vegetable Dicing Machines Market | 2026-2036
Vegetable Dicing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Dicing Machines Market Analytics
Germany is tilting toward expanded production capacity for precision food processing equipment. KRONEN GmbH leverages its Swabian engineering base to dominate European supply of high-throughput dicing systems. Urschel Laboratories anchors North American demand with specialized cutting solutions for frozen vegetable processors. GEA Group AG extends its dairy and beverage machinery expertise into complementary vegetable processing lines.
Vegetable dicing machines are electromechanical food preparation systems employing rotating blade assemblies, grid cutting frames, or hydraulic push mechanisms to reduce raw produce into uniform cubes, strips, or slices at throughputs from fifty to several thousand kilograms per hour. Blade Technology configurations sustain the largest installed base across commercial and industrial settings due to proven reliability and lower maintenance intensity. Electric Dicers are capturing share from manual units in mid-scale catering operations where labor cost pressure intersects with volume requirements. Food Processing Plants represent the deepest margin pool, as these buyers prioritize total cost of ownership over capital expenditure and negotiate multi-year service contracts.
The US FDA's Food Safety Modernization Act mandates hygienic design standards that shape stainless steel construction and clean-in-place capabilities. Europe's CE marking and Machinery Directive enforce safety interlocks and noise emission controls that filter out lower-cost Asian competitors. China's GB standards and SAMR oversight impose additional conformity layers for equipment entering its domestic food processing sector. Stakeholders must weigh regulatory compliance investment against the volume opportunity in emerging automated kitchen segments.
Market Dynamics
Automated kitchen lines in North American hotel chains are compressing equipment replacement cycles from seven years to four, forcing manufacturers to prioritize modular upgrade paths over durable single-lifecycle designs. This demand compression is reshaping R&D allocation across the sector.
Growth Catalysts
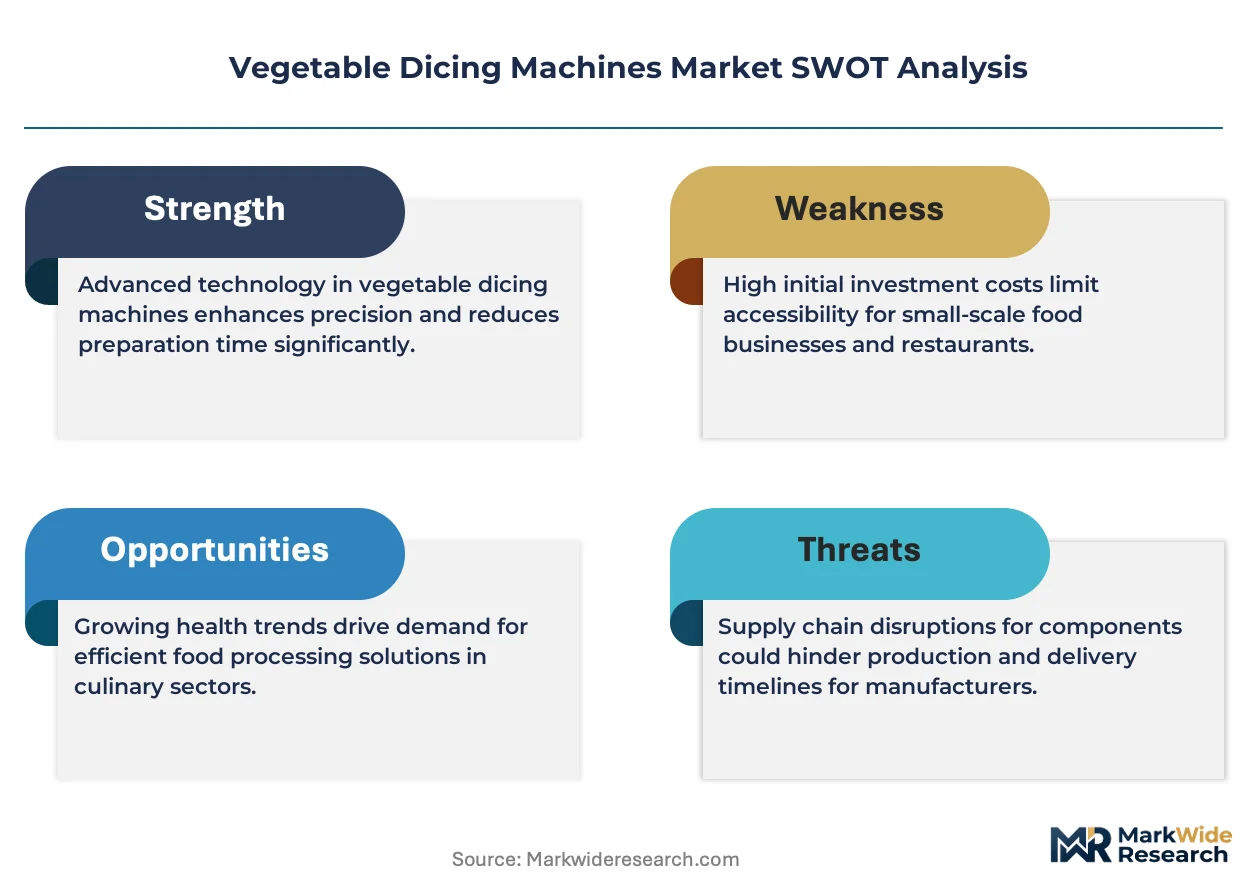
- CE marking and Machinery Directive:European safety mandates filter out low-cost competitors, creating protected margin pools for compliant manufacturers serving industrial food processors.
- Cloud kitchen proliferation:Delivery-optimized ghost kitchens in urban India require compact, high-throughput dicing systems that maximize output per square meter.
- Stainless steel hygienic design:FDA Food Safety Modernization Act requirements for clean-in-place capability drive replacement demand across US frozen vegetable processing plants.
Market Restraints
- Specialized blade alloy supply:German tool steel producers concentrate precision-grade supply, exposing equipment makers to input cost volatility and extended lead times.
- Technical limitation in frozen produce:Cryogenic brittleness in vegetables below minus eighteen degrees Celsius restricts cutting precision, capping throughput for frozen processors.
- Substitution by pre-cut supply chains:Contract farming arrangements delivering pre-diced vegetables directly to commercial kitchens reduce captive equipment demand.
Strategic Opportunities
- Underpenetrated Brazil:ANVISA regulatory alignment with Mercosur standards opens pathway for European-certified equipment to capture industrial food processing expansion.
- Regulatory tailwind from EU Green Deal:Energy-efficient motor system mandates accelerate replacement cycles for legacy dicing equipment across German and Italian processing corridors.
- Technology convergence of IoT sensors and predictive maintenance:Real-time blade-wear monitoring enables service contract unbundling, creating recurring revenue streams.
Industry Challenges
- Electromechanical technician scarcity:Food equipment service networks face acute shortages of specialists qualified to maintain integrated blade-drive-hydraulic systems.
- CE self-certification complexity:Documentation burden for Machinery Directive conformity assessment extends sales cycles by four to six months for mid-scale catering equipment buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Dicing Machines Market |
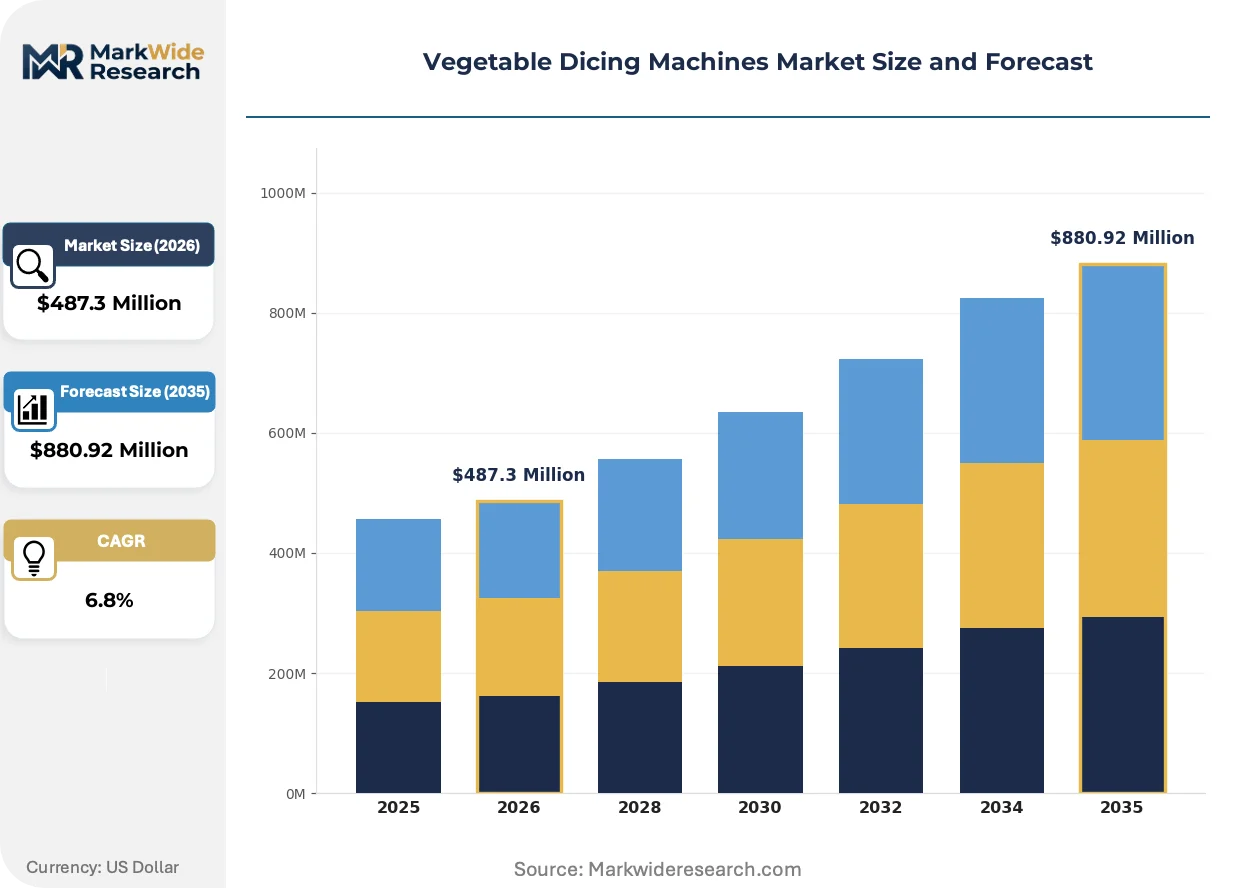
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Dicers, Electric Dicers, Multi-Function Dicers, Industrial Dicers End User: Restaurants, Food Processing Plants, Catering Services, Households Technology: Blade Technology, Laser Cutting, Hydraulic Systems, Smart Technology Capacity: Small Capacity, Medium Capacity, High Capacity, Custom Capacity |
| Companies Covered | KRONEN GmbH, Electrolux Professional, Urschel Laboratories, JBT Corporation, Sormac B.V., FAM, Hobart Corporation, Sammic, GEA Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Dicing Machines Market Evolving Landscape
Electromechanical precision is displacing pneumatic actuation across mid-scale commercial installations, while regulatory energy mandates accelerate motor system replacement. These shifts compress equipment lifecycles and elevate service contract value.
Pulse-width modulated variable frequency drives are rendering obsolete fixed-speed induction motors in vegetable dicing applications. Mid-scale catering operators in Germany and the Netherlands are adopting these systems at accelerating rates to satisfy Ecodesign for Sustainable Products Regulation thresholds. The technology is rendering obsolete the traditional premium placed on mechanical simplicity, as electrical complexity becomes compliance-mandatory.
REACH restrictions on chromium VI surface treatments are forcing migration to trivalent chrome and ceramic coating alternatives for blade assemblies. European manufacturers face reformulation costs that Asian competitors absorb less readily, tightening competitive access to the EU market. Frozen vegetable processors in Poland and Hungary are responding by consolidating procurement around suppliers with verified substitution documentation.
Equipment-as-a-service contracting is displacing outright purchase in North American hotel chain procurement. Third-party fleet managers now bundle dicing systems with maintenance, blade resupply, and throughput guarantees, capturing capital-constrained commercial kitchen operators. This model is most visible across Marriott and Hilton supply networks, where standardization incentives override brand-specific equipment preferences.
Vegetable Dicing Machines Market Segmentation
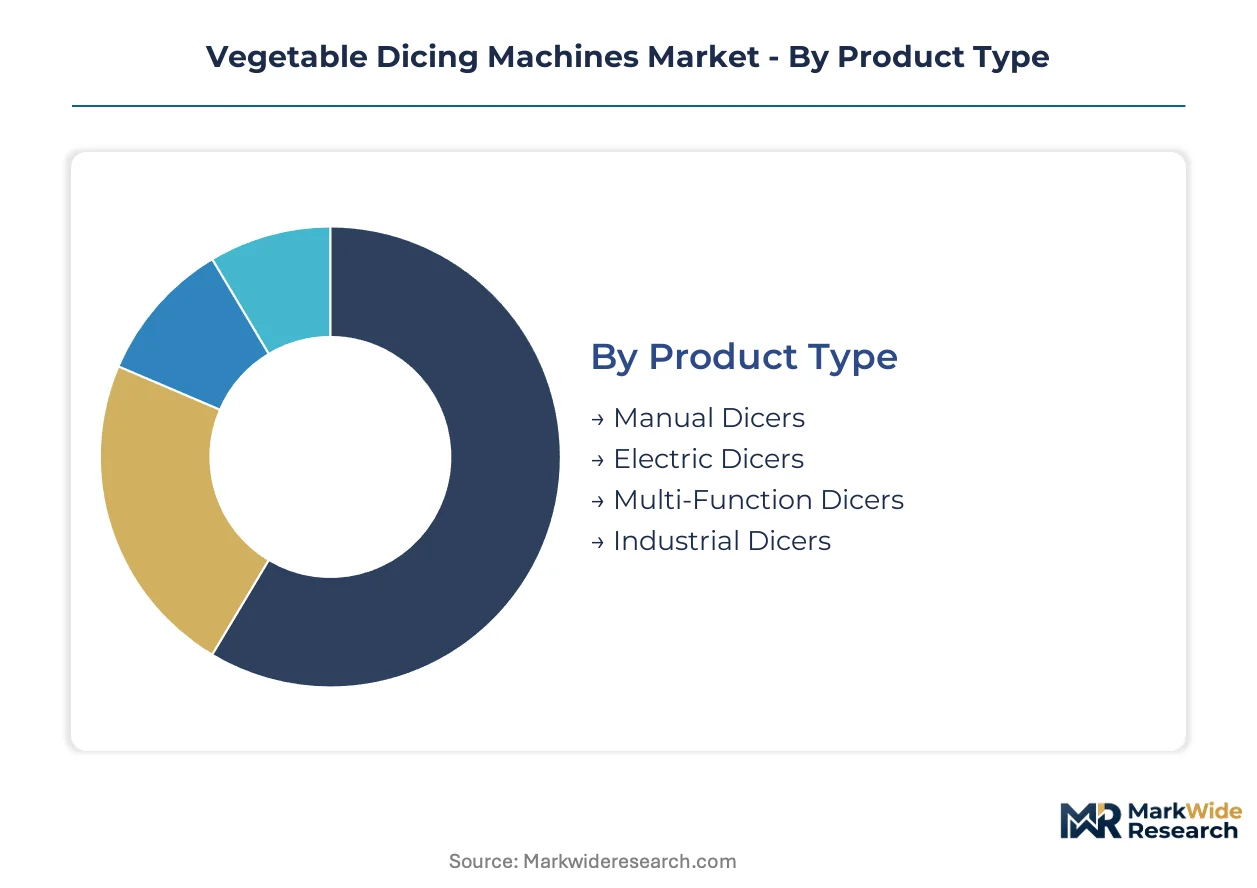
Equipment replacement cycles vary dramatically across buyer types in vegetable dicing machines, from four-year turnovers in automated hotel kitchens to decade-plus lifespans in household settings. Understanding where capital concentrates versus where volume expansion occurs shapes portfolio allocation for manufacturers and service providers.
Product Type:
Replacement velocity splits sharply between commercial and industrial tiers, with electric units in mid-scale catering turning over fastest while manual equipment in small restaurants persists longest.
- Manual Dicers:Hand-operated lever or crank mechanisms requiring no electrical connection, constructed from cast aluminum or food-grade polymer housings. Demand persists in emerging market street food vendors and institutional kitchens with unreliable power infrastructure where capital constraints override labor cost considerations.
- Electric Dicers:Motor-driven blade assemblies delivering fifty to five hundred kilograms hourly throughput via single-phase or three-phase power. North American hotel chains and European contract caterers are compressing replacement cycles to four years as modular upgrade paths displace durable single-lifecycle designs.
- Multi-Function Dicers:Interchangeable cutting heads enabling cubes, strips, slices, and julienne outputs from shared motor bases. Cloud kitchen operators in urban India prioritize these for space-constrained environments.
- Industrial Dicers:Heavy-duty systems with continuous feed mechanisms and clean-in-place architectures for frozen vegetable processors. German and Italian food equipment corridors concentrate procurement of these units.
Industrial dicers dominate installed base. Electric dicers are where expansion concentrates.
End User:
Margin structures diverge across buyer sophistication, with food processing plants negotiating multi-year service contracts while household purchasers prioritize acquisition cost over total cost of ownership.
- Restaurants:Full-service and quick-service operators with throughput requirements from fifty to three hundred kilograms daily. Independent restaurants in Brazil's expanding urban centers represent underpenetrated demand as ANVISA regulatory alignment opens equipment import pathways.
- Food Processing Plants:Industrial-scale frozen and fresh-cut vegetable operations with continuous production schedules. These buyers in Poland and Hungary are consolidating procurement around suppliers with verified REACH-compliant blade coating documentation.
- Catering Services:Contract foodservice operators serving institutional, corporate, and event markets. Equipment-as-a-service contracting is displacing outright purchase across North American hotel chain supply networks.
- Households:Residential consumers with intermittent, low-volume processing needs. This segment shows minimal technology adoption velocity compared to commercial tiers.
Food processing plants command deepest margin pools. Catering services are climbing the fastest as procurement models shift.
Technology:
Energy efficiency mandates are restructuring competitive access, with electrical complexity becoming compliance-mandatory and filtering out mechanically simple legacy designs.
- Blade Technology:Rotating or reciprocating blade assemblies employing stainless steel or specialized alloy cutting edges. This configuration sustains the largest installed base across commercial and industrial settings due to proven reliability and lower maintenance intensity.
- Laser Cutting:Directed energy systems for precision slicing applications requiring minimal mechanical contact. Adoption remains constrained by capital cost and technical complexity relative to mechanical alternatives.
- Hydraulic Systems:Fluid-power push mechanisms for high-force cutting of dense or frozen produce. Cryogenic brittleness below minus eighteen degrees Celsius restricts precision, capping throughput for frozen processors employing these systems.
- Smart Technology:IoT-enabled units with blade-wear sensors and predictive maintenance algorithms. Real-time monitoring enables service contract unbundling, creating recurring revenue streams for fleet managers.
Blade technology anchors current installed base. Smart technology represents the steepest expansion trajectory as predictive maintenance models mature.
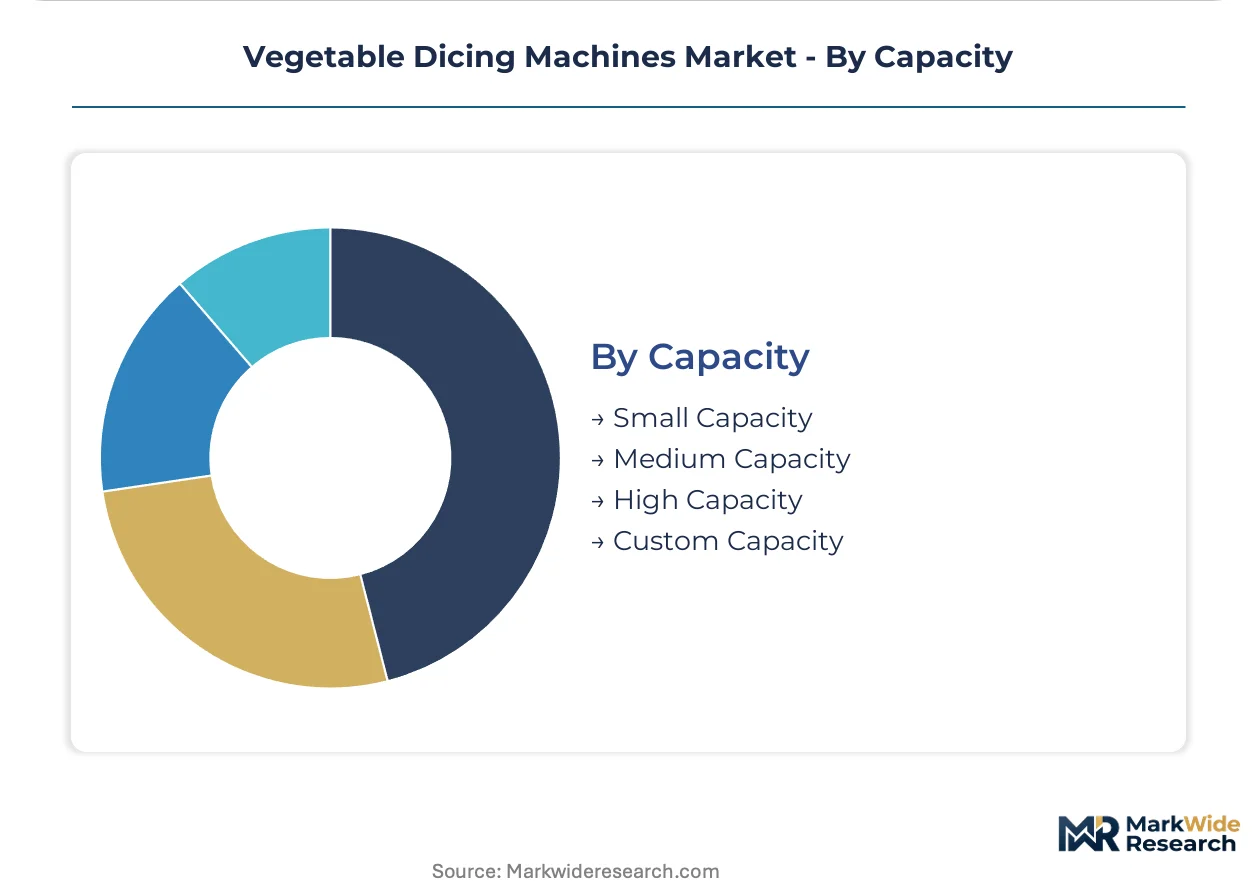
Capacity:
Throughput specifications align with operational scale, from intermittent household use through continuous industrial production with divergent equipment durability requirements.
- Small Capacity:Units processing under fifty kilograms hourly, typically single-phase electric or manual drive. Household and small restaurant demand concentrates here with extended replacement cycles.
- Medium Capacity:Systems delivering fifty to three hundred kilograms hourly, predominantly three-phase electric with modular blade configurations. Mid-scale catering operations in Germany and the Netherlands are adopting pulse-width modulated variable frequency drives to satisfy Ecodesign thresholds.
- High Capacity:Continuous-feed industrial systems exceeding five hundred kilograms hourly with integrated clean-in-place capability. FDA Food Safety Modernization Act requirements drive replacement demand across US frozen vegetable processing plants.
- Custom Capacity:Engineered-to-order systems for specialized produce types or facility constraints. These command premium pricing and extended lead times due to German tool steel supply concentration.
High capacity systems dominate revenue concentration. Medium capacity equipment is gaining share fastest as electrification mandates accelerate replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Food Safety Modernization Act mandates anchor United States demand, while Ecodesign for Sustainable Products Regulation thresholds reshape European procurement patterns. Equipment replacement cycles compress fastest where regulatory compliance intersects with automated kitchen expansion.
United States
Hotel chains and frozen vegetable processors drive equipment turnover. FDA hygienic design standards for clean-in-place capability eliminate legacy installations. Chicago's industrial food equipment corridor concentrates procurement decisions for North American contract catering networks.
Germany
Industrial food processors prioritize energy-efficient motor retrofits. Ecodesign for Sustainable Products Regulation mandates pulse-width modulated variable frequency drives. Stuttgart's precision manufacturing cluster anchors European supply chains for high-throughput dicing systems.
China
Domestic food processing sector expansion creates equipment demand at scale. SAMR oversight and GB standards impose conformity layers for imported machinery. Yangtze River Delta manufacturing bases localize production for mid-capacity catering equipment.
India
Cloud kitchen proliferation in urban centers demands compact, high-throughput systems. FSSAI food safety standards shape stainless steel construction requirements. Mumbai and Bangalore concentrate procurement for delivery-optimized ghost kitchen operators.
Brazil
Industrial food processing expansion opens equipment import pathways. ANVISA regulatory alignment with Mercosur standards reduces certification barriers. São Paulo's expanding urban centers represent underpenetrated demand for mid-scale commercial installations.
Vegetable Dicing Machines Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. German engineering specialists dominate precision blade technology, while diversified industrial conglomerates leverage cross-sector manufacturing scale. Three archetypes define competitive positioning: Swabian precision engineering houses, North American frozen food specialists, and diversified European industrial equipment platforms. Capacity expansion and strategic technology licensing constitute the dominant competitive moves across the sector.
Within the precision engineering tier, KRONEN GmbH and Urschel Laboratories exemplify divergent geographic anchoring strategies. KRONEN leverages its Baden-Württemberg base to serve European industrial food processors, while Urschel Laboratories occupies a position calibrated to North American frozen vegetable demand. GEA Group AG represents the diversified industrial platform archetype, extending machinery expertise across adjacent food processing categories. These three entities collectively illustrate how regulatory compliance capability and geographic proximity to demand clusters determine competitive access.
| Leading Market Players |
|---|
| KRONEN GmbH |
| Electrolux Professional |
| Urschel Laboratories |
| JBT Corporation |
| Sormac B.V. |
| FAM |
| Hobart Corporation |
| Sammic |
| GEA Group AG |
| Others |
Value Network & Pricing Analysis
German tool steel producers concentrate precision-grade blade alloy supply, anchoring margin pools downstream with industrial food processors who negotiate multi-year service contracts rather than competing on capital expenditure. Equipment makers face input cost volatility and extended lead times that cascade into pricing power concentration among certified European manufacturers.
Pricing Analysis
European-manufactured industrial dicers command substantial premiums over Asian alternatives due to CE marking and Machinery Directive compliance costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Price erosion runs through mid-scale catering tiers as cloud kitchen operators prioritize acquisition cost over total cost of ownership. Food processing plants show least price sensitivity, prioritizing clean-in-place capability and predictive maintenance contracts.
Supply Chain Analysis
Specialized blade alloys draw from German, Swedish, and Austrian metallurgical corridors where precision-grade tool steel production concentrates. Component dependencies span electric motor systems from Italian and German manufacturers, hydraulic assemblies from Dutch suppliers, and stainless steel housings from Spanish and Polish fabricators. Single-source vulnerability in cryogenic-grade blade treatments exposes frozen vegetable processor equipment lines to supply interruption. Distribution runs through OEM-direct channels for industrial tiers and foodservice equipment distributors for commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from compressed replacement cycles driven by regulatory energy mandates that force premature obsolescence of legacy motor systems. The cyclical driver is Ecodesign for Sustainable Products Regulation compliance deadlines accelerating equipment turnover across European processing corridors.
For Market Incumbents: Entrench modular upgrade architectures that extend customer lifetime value beyond traditional seven-year replacement horizons. Defend against equipment-as-a-service fleet managers by captive blade resupply contracts and predictive maintenance platform integration. Priority levers include backward integration into German tool steel sourcing and CE self-certification capability investments that compress sales cycles. For New Entrants and Emerging Players: Establish a beachhead in Brazil's industrial food processing expansion where ANVISA regulatory alignment with Mercosur standards reduces European certification barriers. White-space targets include mid-capacity electric dicers for urban Indian cloud kitchens and REACH-compliant blade coating services for Polish and Hungarian frozen vegetable processors. Go-to-market angle emphasizes compact footprint per square meter maximization for space-constrained ghost kitchen operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision engineering houses in Baden-Württemberg holding Swabian manufacturing clusters but lacking predictive maintenance software capabilities. Long-term viability over the next decade hinges on technology convergence plays bridging electromechanical heritage with IoT-enabled service contract unbundling. Watch for blade-wear sensor patent filings as inflection indicator for recurring revenue model maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Real-time blade-wear monitoring enables service contract unbundling for Marriott and Hilton supply networks. |
| REACH-Compliant Blade Coating Migration | Trivalent chrome and ceramic alternatives secure European market access against Asian competitors. |
| Variable Frequency Drive Integration | Pulse-width modulated systems satisfy Ecodesign thresholds for German and Dutch catering operators. |
| Equipment-as-a-Service Fleet Management | Third-party bundling captures capital-constrained hotel chain procurement shifting from outright purchase. |
| Brazilian Regulatory Certification Investment | ANVISA alignment opens industrial food processing corridors in São Paulo's expanding urban centers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with food processing plant engineers, commercial kitchen maintenance directors, OEM procurement teams, and aftermarket service heads; and secondary validation through FDA Food Safety Modernization Act filings, Ecodesign for Sustainable Products Regulation documentation, customs equipment import records, and SEC filings from diversified industrial equipment platforms. Bottom-up equipment shipment tallies by capacity tier and top-down processor capital expenditure surveys were triangulated against regulatory compliance cost estimates.
Forecast inputs span product type segmentation across manual, electric, multi-function, and industrial dicer categories; end-user segmentation across restaurants, food processing plants, catering services, and households; technology segmentation across blade, laser, hydraulic, and smart systems; and capacity segmentation from small through custom engineered-to-order systems. CAGRs were derived from replacement cycle compression analysis and regulatory mandate timing across the projection horizon. Industry-specific inputs include Ecodesign compliance deadlines and cloud kitchen square footage constraints in urban India.
Sensitivities concentrate around German tool steel supply disruption, REACH restriction enforcement intensity, and frozen vegetable processor throughput caps from cryogenic brittleness limitations. Forecasts reflect assumptions regarding regulatory alignment timelines and electromechanical technician availability for service network expansion. Cross-checking against equipment-as-a-service contract disclosure patterns from North American hotel chain supply networks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
North America Feed Pelletizing Agent Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
Rice Milling Machinery Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Dal Mill Machine Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Destoner Machine Market
Agricultural Processing Equipment
Feed Screw Barrel Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Solar Herbs Dryer Market