
 Maize Milling Machine Market | 2026-2036
Maize Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Maize Milling Machine Market Foresight
Equipment leasing and pay-as-you-mill service contracts are fragmenting capital barriers across Africa and South Asia, enabling smaller processors to access industrial-grade capacity without full ownership burdens. Bühler Group leverages its Swiss engineering heritage to anchor premium roller mill installations across large-scale commercial operations in East Africa. ABC Machinery competes aggressively on diesel-powered small-scale units designed for off-grid agricultural cooperatives. Alapala sustains its position through integrated plant engineering that extends from grain cleaning through finished packaging.
A maize milling machine processes dried maize kernels into grits, flour, or meal through mechanical grinding, sifting, and separation stages, with roller mills achieving extraction rates of 72-78% for refined maize flour through differential roller speed and corrugation profiles. Hammer mills dominate small-scale and household segments due to lower capital outlay and simpler maintenance, though roller mills command the industrial end-user category where throughput exceeds 50 tonnes per day. Electric technology leads the technology dimension in grid-connected regions, while diesel configurations occupy rural agricultural cooperative installations where grid reliability remains intermittent.
ISO 22000 food safety management systems and national food regulator standards in major maize-consuming countries shape equipment specifications, particularly for contact-surface materials and dust containment. The EPA and equivalent environmental agencies in processing jurisdictions enforce emissions controls on diesel-powered units, nudging technology migration toward electric or hybrid drive systems. Stakeholders must monitor how carbon-border adjustment mechanisms and green equipment financing criteria reshape capital allocation between established diesel infrastructure and electrified alternatives.
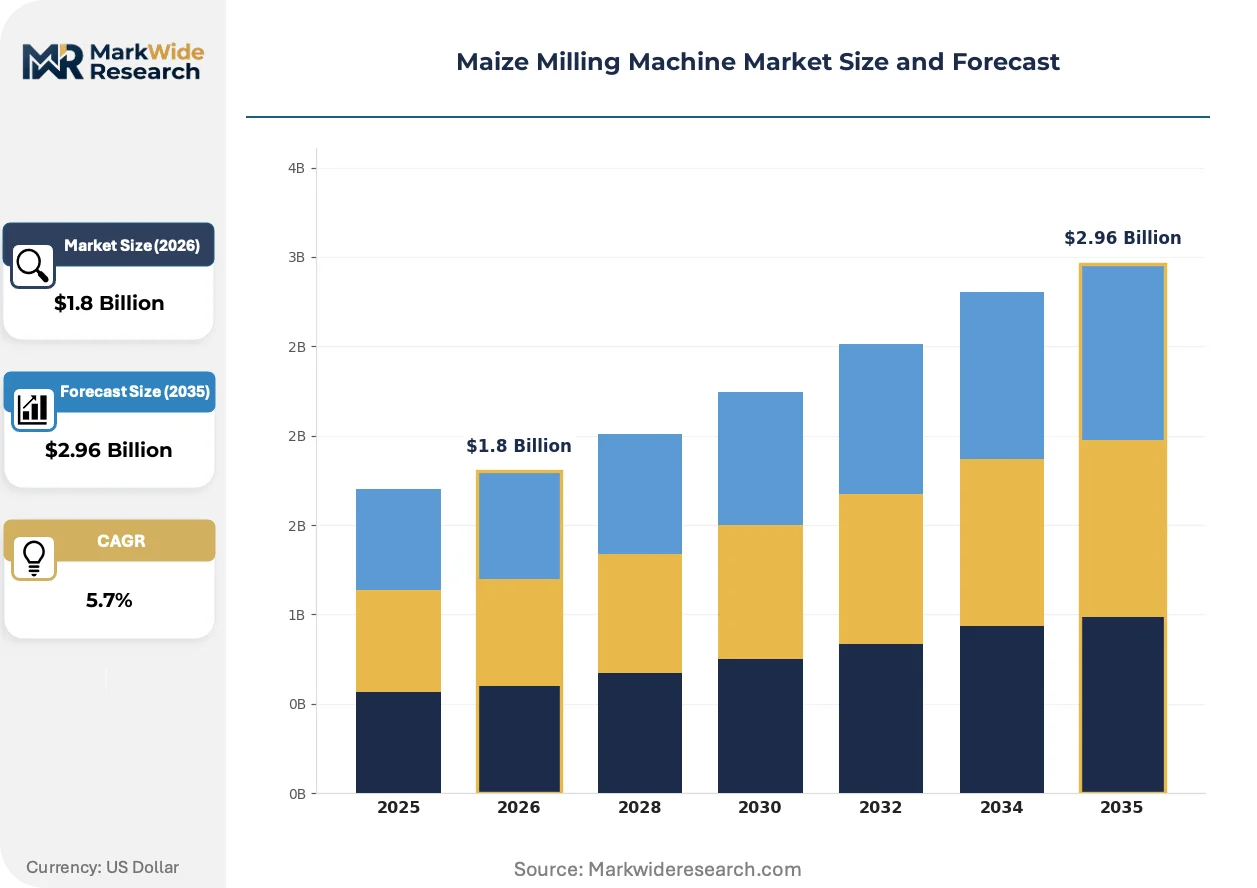
Market Dynamics
Import substitution mandates across African maize-consuming nations are forcing rapid domestic milling infrastructure deployment, while FAO Codex Alimentarius mycotoxin standards push capital toward automated sorting and climate-controlled processing systems.
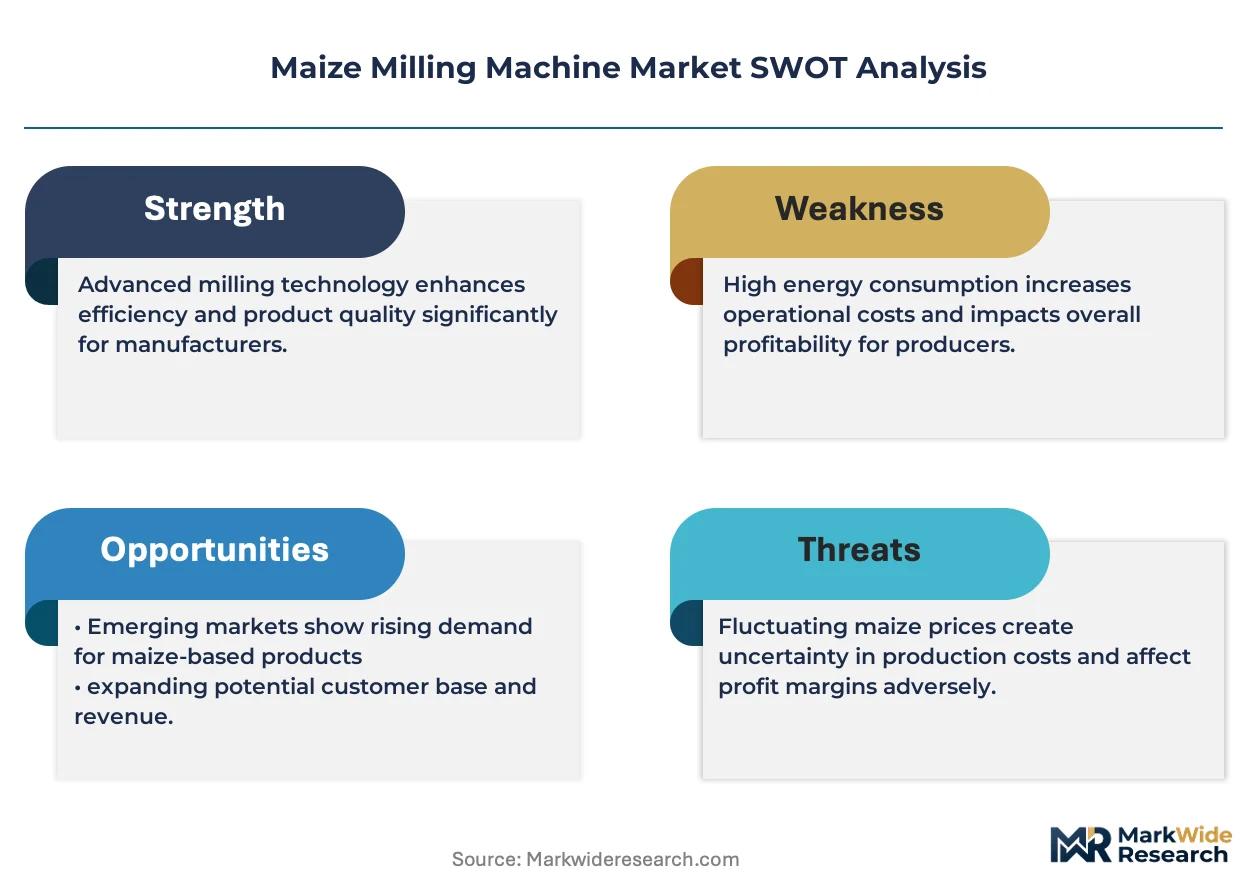
Growth Catalysts
- Federal import substitution policies:Nigeria's restrictions on maize product imports compel domestic millers to install industrial-grade capacity, creating equipment demand across roller mill and cleaning system categories.
- Post-harvest loss reduction mandates:Agricultural cooperatives in Sub-Saharan Africa are mechanizing milling operations to cut spoilage, with diesel-powered units penetrating off-grid rural installations.
- Fortification requirements:National food regulator standards mandating vitamin and mineral enrichment in maize flour drive upgrades to precision dosing and homogeneous mixing equipment.
Market Restraints
- Steel and bearing input volatility:Roller mill corrugation profiles and precision drive components depend on alloy steel supply chains concentrated in East Asian manufacturing hubs, exposing African and South Asian buyers to currency and freight cost swings.
- Grid reliability deficits:Rural agricultural cooperatives in Nigeria, Tanzania, and Zambia face diesel-electric technology lock-in due to intermittent grid access, limiting migration to lower-operating-cost electric systems despite EPA and national emissions enforcement tightening.
- Skilled maintenance scarcity:Differential roller speed calibration and automated sorter programming require technicians rarely available outside Nairobi, Lagos, and Johannesburg service corridors, extending downtime and warranty claim cycles.
Strategic Opportunities
- Pay-as-you-mill service contracts:Equipment-as-a-service models are penetrating Kenyan and Ugandan agricultural cooperatives, converting capital expenditure into operational expenditure and expanding addressable market to sub-50-tonne-per-day processors.
- Carbon-border adjustment alignment:Green equipment financing criteria from development finance institutions are creating first-mover advantage for hybrid diesel-electric mill configurations in export-oriented maize processing zones.
- Integrated plant engineering:Turnkey solutions spanning grain intake through finished packaging capture margin from buyers seeking single-vendor accountability for ISO 22000 compliance and dust containment certification.
Industry Challenges
- Certification timeline compression:National food regulator approvals for contact-surface materials and mycotoxin detection integration are extending commissioning schedules by four to eight months in multiple African jurisdictions.
- Legacy hammer mill retrofit complexity:Small-scale processors seeking extraction rate improvements face incompatible infrastructure when upgrading to roller mill systems, requiring complete electrical and building envelope reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maize Milling Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hammer Mill, Roller Mill, Stone Mill, Turbo Mill Technology: Electric, Diesel, Gasoline, Manual End User: Commercial, Agricultural Cooperatives, Household, Industrial Capacity: Small-Scale, Medium-Scale, Large-Scale, Custom-Built |
| Companies Covered | Tehold International, ABC Machinery, GrainTech Engineering, AgroMill Solutions, Precision Milling Systems, Bühler Group, Satake Corporation, Alapala, Voson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maize Milling Machine Market Shifts & Advancements
Automation and digital process control are penetrating maize milling operations previously dependent on manual intervention, while regulatory pressure on mycotoxin management accelerates sensor integration and data logging adoption.
Near-infrared spectroscopy and AI-driven optical sorting is hybridizing quality control workflows in large-scale commercial installations. Nigerian and Kenyan millers exceeding 100 tonnes per day are deploying real-time moisture and aflatoxin detection to preempt batch rejection. The technology is hybridizing traditional laboratory testing with inline monitoring, compressing quality assurance staffing requirements and enabling continuous rather than batch-based release decisions.
REACH chemical compliance and EU Green Deal carbon accounting rules are reshaping equipment export requirements for European-built mills destined for African markets. Contact-surface material declarations and end-of-life recycling protocols now accompany CE marking in tender documentation. East African buyers sourcing from European vendors are absorbing documentation burdens previously absent in South Asian or Chinese supply relationships.
After-sales service unbundling is fragmenting traditional vendor-customer relationships across West African markets. Mill operators in Ghana and Côte d'Ivoire are procuring spare parts through independent distributors and third-party maintenance contracts rather than original equipment manufacturer service agreements. This pattern concentrates in diesel-powered hammer mill segments where technical complexity permits non-specialized technician intervention.
Maize Milling Machine Market Segmentation
Segmentation in maize milling equipment reveals distinct technology-capacity pairings that align with infrastructure availability and capital access. Nigerian commercial millers and Tanzanian agricultural cooperatives face divergent equipment selection constraints based on grid reliability and throughput requirements.
Product Type:
Mature industrial designs coexist with emerging precision grinding systems across the maturity spectrum.
- Roller Mill:Differential-speed corrugated rollers achieve extraction rates of 72-78% for refined maize flour through precision gap adjustment and controlled temperature milling. Nigerian industrial installations exceeding 50 tonnes per day deploy these systems to meet federal fortification mandates and FAO Codex Alimentarius mycotoxin standards.
- Hammer Mill:Rotating hammers pulverize kernels through impact grinding, offering lower capital outlay and simpler maintenance protocols. Demand concentrates among agricultural cooperatives in off-grid Sub-Saharan regions where diesel configurations dominate and technician scarcity limits complex equipment servicing.
- Stone Mill:Traditional abrasive grinding preserves whole-grain nutritional profiles for specialty food applications.
- Turbo Mill:High-velocity air classification enables ultra-fine particle size reduction for pharmaceutical and industrial starch extraction.
Roller mill installations handle the majority of throughput; turbo mill systems are gaining share fastest in specialized industrial applications.
Technology:
Cost tier stratification separates grid-dependent electric systems from fuel-powered alternatives suited to intermittent infrastructure.
- Electric:Grid-connected three-phase motors drive precision roller mills and automated sorting systems in Nigerian urban milling clusters and Kenyan commercial zones. ISO 22000-compliant installations favor electric drives for consistent torque control and integration with inline mycotoxin detection sensors.
- Diesel:Compression-ignition engines power hammer mills and small-scale roller installations across rural Zambia, Tanzania, and northern Nigeria where grid reliability remains sporadic. EPA emissions enforcement and national environmental agency standards are nudging operators toward hybrid configurations despite higher upfront capital requirements.
- Gasoline:Portable single-cylinder units serve household and micro-enterprise segments with sub-one-tonne-per-day processing needs.
- Manual:Hand-cranked stone mills persist in remote household segments beyond fuel supply chains.
Electric technology commands the highest throughput volumes; diesel-electric hybrid configurations are expanding most quickly as development finance institutions impose green equipment financing criteria.
End User:
Application-driven segmentation maps equipment specifications to operational scale and regulatory exposure.
- Industrial:Integrated plants exceeding 100 tonnes per day deploy automated cleaning, milling, fortification, and packaging lines under single-vendor engineering contracts. Nigerian millers serving urban fortified flour markets invest in these configurations to satisfy national food regulator standards and secure retail distribution contracts.
- Agricultural Cooperatives:Member-owned processing facilities in Kenya and Uganda adopt pay-as-you-mill service contracts and equipment leasing to convert capital expenditure into operational expenditure. Diesel-powered hammer mills and small-scale roller units dominate this segment where grid access is unreliable and maintenance technician availability is limited to major service corridors.
- Commercial:Independent millers serving regional wholesale markets operate mid-scale electric or diesel systems.
- Household:Single-family or village-level processing employs manual or small gasoline units for immediate consumption.
Industrial end users process the greatest volume; agricultural cooperatives are climbing the fastest on participation as mechanization spreads through equipment-as-a-service models.
Capacity:
Volume-based segmentation determines automation level, labor intensity, and regulatory compliance scope.
- Large-Scale:Systems processing above 50 tonnes per day incorporate real-time moisture monitoring, AI-driven optical sorting, and automated packaging to achieve continuous rather than batch-based release decisions. Nigerian installations in this tier absorb extended commissioning timelines of four to eight months due to national food regulator certification requirements for contact-surface materials and mycotoxin detection integration.
- Small-Scale:Sub-10-tonne-per-day hammer mill and basic roller mill configurations serve rural agricultural cooperatives and village-level commercial operations. These units face technology lock-in when upgrading to roller mill systems, often requiring complete electrical and building envelope reconstruction.
- Medium-Scale:10-50 tonne-per-day systems bridge commercial and industrial segments with semi-automated controls.
- Custom-Built:Engineered-to-order plants address specific grain intake configurations, fortification dosing requirements, or packaging line integrations.
Large-scale capacity handles the majority of throughput; custom-built installations are expanding most quickly as turnkey engineering contracts capture margin from buyers seeking single-vendor accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal import substitution policies across African maize-consuming nations are accelerating domestic milling infrastructure deployment, while FAO Codex Alimentarius standards on mycotoxin limits reshape equipment specifications toward automated sorting and climate-controlled processing systems.
Nigeria
Restrictions on maize product imports compel domestic millers to install industrial-grade roller mill capacity, creating sustained equipment demand across cleaning system and fortification dosing categories. The country's national food regulator mandates vitamin and mineral enrichment in maize flour, driving upgrades to precision mixing infrastructure. Lagos and Kano industrial clusters absorb extended commissioning timelines of four to eight months due to certification requirements for contact-surface materials.
Kenya
Agricultural cooperatives are adopting pay-as-you-mill service contracts to convert capital expenditure into operational expenditure, expanding mechanized capacity without full ownership burdens. Development finance institutions impose green equipment financing criteria that favor hybrid diesel-electric configurations in export-oriented processing zones. Nairobi anchors the primary service corridor where differential roller speed calibration technicians concentrate, while rural installations face maintenance scarcity extending downtime cycles.
Tanzania
Off-grid agricultural cooperatives in northern and central regions deploy diesel-powered hammer mills due to intermittent grid access, limiting migration to lower-operating-cost electric systems. EPA emissions enforcement and national environmental agency standards are nudging operators toward hybrid configurations despite higher upfront capital requirements. Dar es Salaam serves as the import hub for alloy steel components and precision drive systems sourced from East Asian manufacturing centers.
Uganda
Equipment leasing models penetrate member-owned processing facilities, enabling sub-50-tonne-per-day processors to access industrial-grade capacity. The country's national food regulator aligns fortification requirements with FAO standards, pushing capital toward automated dosing and homogeneous mixing equipment. Kampala-based distributors are fragmenting traditional vendor relationships as mill operators procure spare parts through independent channels rather than original equipment manufacturer service agreements.
Zambia
Rural milling operations face diesel-electric technology lock-in due to grid reliability deficits, constraining technology migration despite tightening emissions standards. Agricultural cooperatives mechanize operations to cut post-harvest losses, with small-scale roller units penetrating peri-urban installations. Lusaka and the Copperbelt region concentrate service technician availability, while remote cooperatives endure extended warranty claim cycles due to skilled maintenance scarcity.
Maize Milling Machine Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers: Swiss and European engineering houses anchor premium integrated plant installations, Chinese and South Asian fabricators dominate mid-scale diesel and electric configurations, and regional assemblers serve price-sensitive cooperative segments. Strategic archetypes include turnkey engineering specialists, component-focused fabricators, and equipment-as-a-service platform operators. Competitive moves concentrate on geographic expansion through local assembly partnerships and portfolio diversification into complementary grain processing equipment.
Among established engineering houses, Bühler Group and Satake Corporation exemplify the premium-tier archetype through integrated plant engineering extending from grain intake through finished packaging. ABC Machinery occupies a position within the mid-scale diesel-powered segment designed for off-grid agricultural cooperatives. Alapala represents the turnkey specialist archetype, capturing margin from buyers seeking single-vendor accountability for ISO 22000 compliance and dust containment certification.
| Leading Market Players |
|---|
| Tehold International |
| ABC Machinery |
| GrainTech Engineering |
| AgroMill Solutions |
| Precision Milling Systems |
| Bühler Group |
| Satake Corporation |
| Alapala |
| Voson |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese mid-scale fabricators is compressing margins for roller mill and hammer mill producers, forcing tier-1 European engineering houses to bundle after-sales service contracts and remote diagnostics as margin protection while African cooperatives exploit buyer leverage on diesel-powered units.
Pricing Analysis
Certification level creates the primary spread between premium Swiss-engineered installations and mid-tier Asian alternatives, with ISO 22000-compliant contact-surface materials commanding substantial premiums over basic CE-marked configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation depth and mycotoxin detection integration, with Nigerian industrial millers least price-sensitive due to federal fortification mandates while Kenyan agricultural cooperatives drive hardest bargain on pay-as-you-mill contracts. Cost compression in standard-tier electric systems is intensifying because alloy steel input volatility and freight cost swings from East Asian manufacturing hubs are squeezing fabricator margins.
Supply Chain Analysis
Extended payment terms from development finance institutions are easing working capital constraints for East African buyers sourcing precision drive components and roller corrugation profiles. Manufacturing concentrates in China, India, and Switzerland, with alloy steel supply chains drawing from East Asian hubs and precision bearings sourcing from German and Japanese specialty producers. Single-source vulnerability runs through roller mill corrugation grinding equipment concentrated in Swiss and German machine tool builders. Distribution runs through Nairobi, Lagos, and Johannesburg service corridors where spare parts unbundling is fragmenting traditional vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent equipment manufacturers face substitution pressure from equipment-as-a-service platform operators converting capital expenditure into operational expenditure across Kenyan and Ugandan agricultural cooperatives.
For Market Incumbents: Build switching-cost moats through integrated remote diagnostics and predictive maintenance subscriptions that lock in roller mill calibration dependencies. Anchor premium positioning by deepening backward integration into precision corrugation grinding capabilities, insulating margin from alloy steel volatility. Defend against pay-as-you-mill disintermediation by embedding ISO 22000 compliance documentation into long-term service contracts.
For New Entrants and Emerging Players: Mid-scale commercial millers in Tanzania and Zambia represent the most penetrable entry point, where diesel-electric hybrid configurations face limited incumbent coverage and development finance green criteria create first-mover advantage. Target peri-urban Nigerian processors seeking extraction rate upgrades from legacy hammer mills but lacking capital for full roller mill reconstruction. Lead with equipment leasing bundled with technician training to overcome skilled maintenance scarcity outside major service corridors.
For Investors and Strategic Acquirers: Long-term, this sits as a food-security infrastructure play because federal import substitution mandates across African maize-consuming nations guarantee sustained equipment demand regardless of commodity price cycles. Prioritize turnkey engineering specialists with demonstrated ISO 22000 certification timelines and established spare parts distribution in West African markets. Watch carbon-border adjustment mechanism implementation in EU-destined maize product flows as signal for hybrid diesel-electric configuration demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Pay-as-you-mill Platform Launch | Converts capital expenditure into operational expenditure for Kenyan and Ugandan agricultural cooperatives. |
| Hybrid Diesel-Electric Configuration | Aligns with development finance green criteria and EPA emissions tightening in Nigerian and Tanzanian markets. |
| Remote Diagnostics Integration | Compresses downtime cycles where differential roller speed calibration technicians concentrate in Nairobi and Lagos. |
| Backward Integration into Corrugation Grinding | Insulates margin from alloy steel supply chain volatility concentrated in East Asian manufacturing hubs. |
| Turnkey ISO 22000 Certification Bundling | Captures extended commissioning timeline value as Nigerian national food regulator requirements tighten. |
Research Methodology
A spread of perspectives from plant engineers at Nigerian industrial millers, procurement leads at Kenyan agricultural cooperatives, aftermarket service heads at European engineering houses, and development finance institution officers converged on the working assumptions. Primary interviews combined with secondary validation from FAO Codex Alimentarius documentation, national food regulator filings in Nigeria and Uganda, customs data on alloy steel component imports, and equipment manufacturer SEC disclosures. Bottom-up capacity installation tracking across Lagos, Kano, Nairobi, and Dar es Salaam industrial clusters triangulated against top-down maize consumption and fortification mandate projections.
Demand-supply balance modeling anchored volume forecasts, with segmentation across roller mill and hammer mill product types, electric and diesel technology configurations, industrial and agricultural cooperative end users, and large-scale versus small-scale capacity tiers. CAGRs derived from installed base depreciation schedules, replacement cycle analysis, and greenfield project pipelines across the projection horizon. Industry-specific inputs included FAO mycotoxin standard enforcement timelines, federal import substitution policy implementation rates, and grid reliability improvement trajectories in rural Nigerian and Tanzanian zones.
Practitioners should monitor alloy steel price volatility, carbon-border adjustment mechanism announcements, and national food regulator certification timeline compression for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Oil Mill Machine Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Sugarcane Harvesters Market
Agricultural Processing Equipment
Global Egg Processing Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Cashew Processing Machine Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Hemp Processing Equipment Market
Agricultural Processing Equipment
Poultry Processing Equipment Market