
 Harvesting Equipment Market | 2026-2036
Harvesting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Harvesting Equipment Market Insights
Skilled combine technician availability is collapsing across the US Corn Belt and Canadian Prairies, forcing operators toward autonomous GPS-Enabled platforms. Deere & Company leverages its precision agriculture ecosystem to anchor premium positioning in North America. CNH Industrial N.V. competes through dual-brand distribution across European wheat zones and Latin American soybean regions. AGCO Corporation specializes in mid-range mechanical harvesters for emerging cooperative buyers in Eastern Europe.
Harvesting equipment comprises self-propelled and trailed machines engineered to cut, thresh, clean, and bag grain or forage crops in a single field pass, with cutting widths spanning 20 to 45 feet and engine outputs from 300 to 700 horsepower for Class 9 combines. Its primary commercial purpose is reducing crop loss below 2% while compressing harvest windows vulnerable to weather damage. Combine Harvesters dominate installed base value and aftermarket parts revenue across all major grain-producing regions. Autonomous technology represents the fastest-expanding segment as labor economics deteriorate, though mechanical systems still occupy the majority unit volume in price-sensitive South Asian and African markets. GPS-Enabled platforms concentrate margin pools in subscription-based fleet management and yield-mapping software.
EPA Tier 4 Final and EU Stage V emission frameworks are forcing engine redesigns and raising upfront equipment costs, while ISO 12100 machinery safety standards govern access to European and Australian import markets. The US FAA regulates aerial spraying coordination with autonomous ground fleets, and Brazil's national environmental regulator enforces deforestation-linked equipment financing restrictions in the Amazon biome. Stakeholders must monitor regulatory divergence between emission jurisdictions and autonomous operation liability frameworks as these determine which technology investments will retain market access.
Market Dynamics
Farm labor shortages across North American grain belts are accelerating autonomous machinery adoption faster than OEMs can scale production capacity, compressing equipment replacement cycles and reshaping dealer service revenue models.
Growth Catalysts
- EPA Tier 4 Final emission standards:These regulations are forcing fleet turnover in the US Corn Belt as older mechanical-hydraulic combines face operating restrictions, pulling forward demand for compliant powertrains.
- Brazil's Mato Grosso soybean frontier:Operators in this high-productivity belt are replacing aging Class 7 and Class 8 fleets with GPS-Enabled platforms to maximize narrow harvest windows.
- Autonomous GPS-Enabled technology:Labor economics deterioration across the Canadian Prairies is pushing cooperative buyers toward subscription-based fleet management and yield-mapping software bundles.
Market Restraints
- Engine redesign costs:EPA Tier 4 Final and EU Stage V frameworks are raising upfront equipment costs by 15-25% for mechanical harvesters, squeezing price-sensitive South Asian buyers.
- Technician availability collapse:Skilled combine technician pools are shrinking across the US Corn Belt, limiting aftermarket service capacity and extending downtime for mechanical systems.
- Deforestation-linked financing restrictions:Brazil's national environmental regulator is blocking equipment credit in Amazon biome regions, constraining fleet expansion in northern agricultural frontiers.
Strategic Opportunities
- Eastern European cooperative buyers:Mid-range mechanical harvester demand is concentrating in Poland, Romania, and Ukraine as EU Common Agricultural Policy subsidies support fleet modernization.
- Aerial-ground fleet coordination:The US FAA is developing regulatory frameworks for autonomous ground harvesters operating alongside spraying drones, creating integrated crop management service bundles.
- Yield-mapping software convergence:GPS-Enabled platforms are merging with soil sensor networks and variable-rate input systems, enabling outcome-based agronomic advisory subscriptions.
Industry Challenges
- Autonomous operation liability frameworks:Jurisdictional divergence between US state tort law, EU machinery directives, and Brazilian civil code is creating legal uncertainty for cross-border OEM deployments.
- ISO 12100 safety certification timelines:European and Australian import market access requires extensive third-party validation of autonomous emergency-stop systems, delaying product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Harvesting Equipment Market |
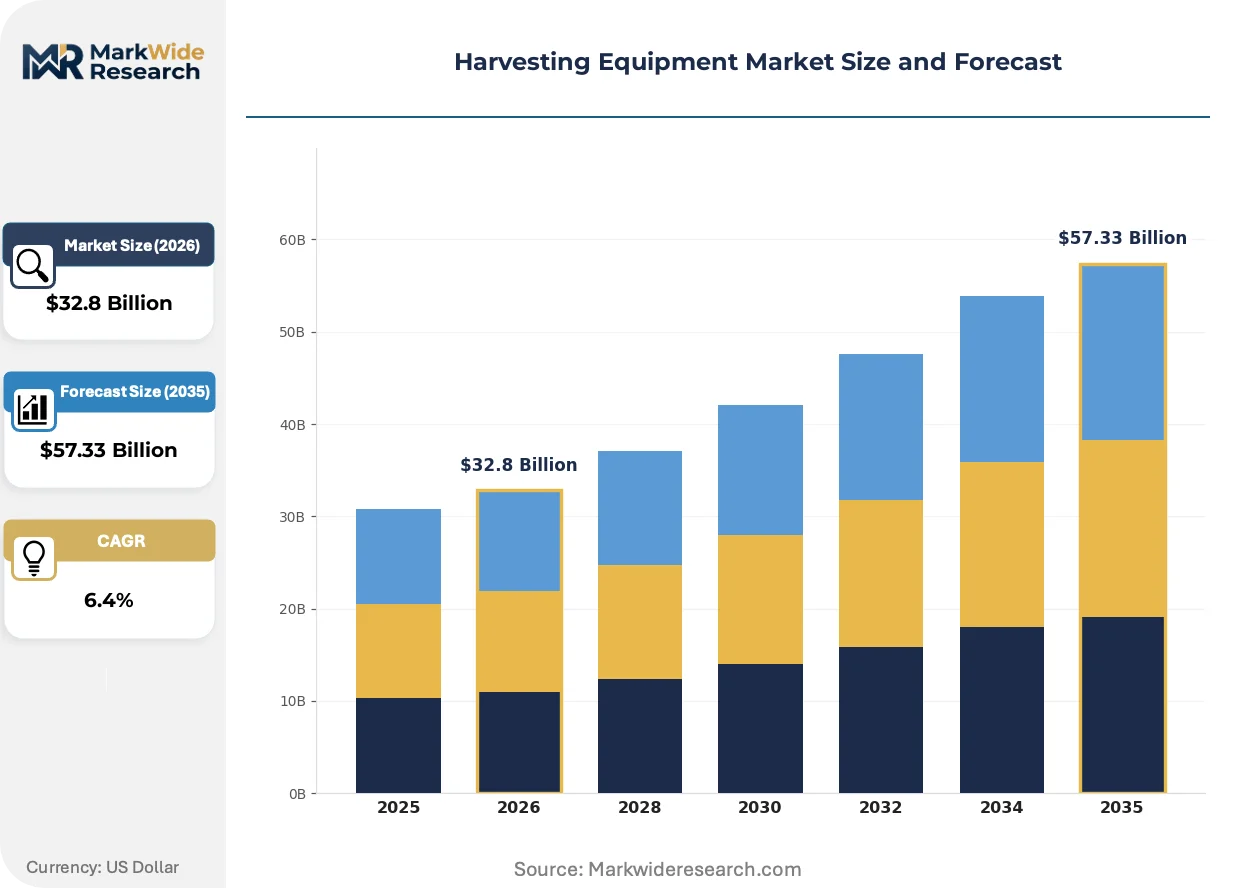
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Combine Harvesters, Forage Harvesters, Potato Harvesters, Cotton Pickers, Sugarcane Harvesters Technology: Mechanical, Hydraulic, Pneumatic, Autonomous, GPS-Enabled Application: Crop Harvesting, Fruit Picking, Root Crop Extraction, Fiber Collection, Biomass Gathering End User: Large-Scale Farmers, Agricultural Cooperatives, Food Processing Units, Equipment Rental Services |
| Companies Covered | Deere & Company, CNH Industrial N.V., AGCO Corporation, CLAAS KGaA mbH, KUBOTA Corporation, Mahindra & Mahindra Ltd., YANMAR HOLDINGS Co., Ltd., Maschinenfabrik Bernard KRONE GmbH & Co. KG, Sampo-Rosenlew Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Harvesting Equipment Market Trends and Innovations
Powertrain electrification and digital agriculture convergence are fragmenting traditional equipment categories while regulatory emission deadlines compress technology roadmaps across all major grain-producing regions.
Autonomous navigation stacks are fragmenting the competitive landscape as specialized software vendors bypass incumbent OEM control over precision agriculture ecosystems. Deere and CNH Industrial are racing to integrate LiDAR-based obstacle detection and swarm-coordination algorithms into Class 9 combines. This technology is fragmenting aftermarket revenue pools away from mechanical parts toward software subscriptions and telematics service contracts.
EU Stage V emission frameworks are mandating diesel particulate filter and selective catalytic reduction systems on all engines above 56 kW, adding weight and cooling complexity to combine designs. Manufacturers are responding with hybrid-electric auxiliary systems to maintain power density. European wheat zone operators are absorbing these costs faster than South American buyers, shifting production allocation toward EU-compliant configurations.
Cooperative buyers in Eastern Europe are consolidating procurement through shared-equipment platforms and seasonal leasing pools rather than individual ownership. This behavior is compressing dealer sales cycles and forcing manufacturers to develop fleet-management software for multi-operator credentialing and usage-based billing. Poland and Romania are exhibiting the fastest adoption of these shared-access models among EU member states.
Harvesting Equipment Market Segmentation
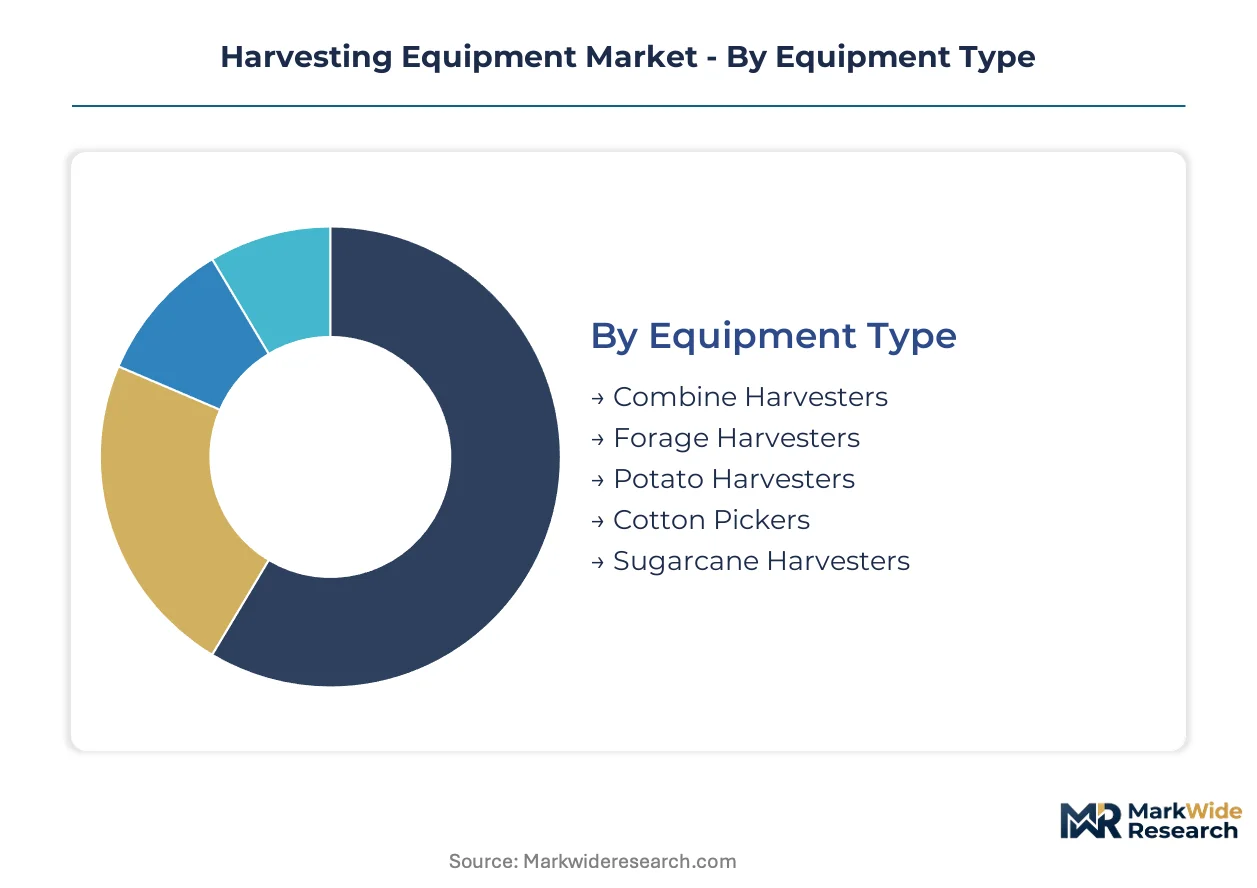
Harvesting equipment segmentation reflects divergent technology maturity curves and regulatory compliance tiers across grain-producing regions. Equipment type and technology categories capture the bulk of procurement decisions as operators balance EPA Tier 4 Final mandates against labor economics.
Equipment Type:
EPA Tier 4 Final and EU Stage V emission standards have forced divergent design investments across equipment categories, with larger self-propelled platforms absorbing compliance costs more readily than specialized trailed units.
- Combine Harvesters:Self-propelled platforms with cutting widths from 20 to 45 feet and engine outputs spanning 300 to 700 horsepower dominate installed base value. US Corn Belt operators are replacing aging Class 7 and Class 8 fleets with Class 9 models to compress harvest windows vulnerable to weather damage.
- Forage Harvesters:These machines cut, chop, and collect silage crops in a single pass using cutterhead drums or flail systems. Dairy cooperative demand in Wisconsin and Bavaria is concentrating procurement toward GPS-Enabled platforms with yield-mapping integration.
- Potato Harvesters:Specialized digging and sorting systems for root crop extraction.
- Cotton Pickers:Spindle or stripper mechanisms for fiber collection in high-density planting configurations.
- Sugarcane Harvesters:Whole-stalk or chopper systems engineered for tropical biomass gathering.
Combine Harvesters handle the majority of throughput; Forage Harvesters are the fastest mover on share as dairy operations automate feed logistics.
Technology:
Cost tier stratification separates premium autonomous platforms from mechanical systems still serving price-sensitive cooperative buyers in Eastern Europe and South Asia.
- GPS-Enabled:Satellite-guided steering and yield-mapping software bundles command subscription-based revenue pools. Canadian Prairie cooperatives are adopting these platforms fastest as skilled technician availability collapses.
- Autonomous:LiDAR-based obstacle detection and swarm-coordination algorithms eliminate operator dependency. Brazil's Mato Grosso soybean frontier is absorbing these units despite 15-25% upfront cost premiums over mechanical alternatives.
- Mechanical:Conventional gear-and-chain drive systems without electronic control modules.
- Hydraulic:Fluid-power actuation for header lift and reel positioning functions.
- Pneumatic:Compressed-air systems for lightweight crop handling and cleaning operations.
Mechanical systems still move the most unit volume; Autonomous platforms are climbing the fastest as labor shortages accelerate replacement cycles.
Application:
Customer type fragmentation separates large-scale estate operators from seasonal rental services with divergent utilization intensity and financing capacity.
- Crop Harvesting:Grain and oilseed collection using threshing and cleaning mechanisms. Large-scale farmers in Iowa and Illinois are consolidating procurement toward 12-month utilization models to amortize EPA Tier 4 Final compliance premiums.
- Biomass Gathering:Residue collection for biofuel feedstock and soil amendment markets. Agricultural cooperatives in Poland and Romania are deploying shared-equipment platforms for seasonal straw and stover aggregation.
- Fruit Picking:Orchard-specific platforms with gentle handling for tree crops.
- Root Crop Extraction:Deep-lifting systems for tuber and bulb harvesting.
- Fiber Collection:Specialized units for cotton and bast crop recovery.
Crop Harvesting absorbs the dominant share of capital deployment; Biomass Gathering is gaining share fastest as biofuel mandates expand feedstock demand.
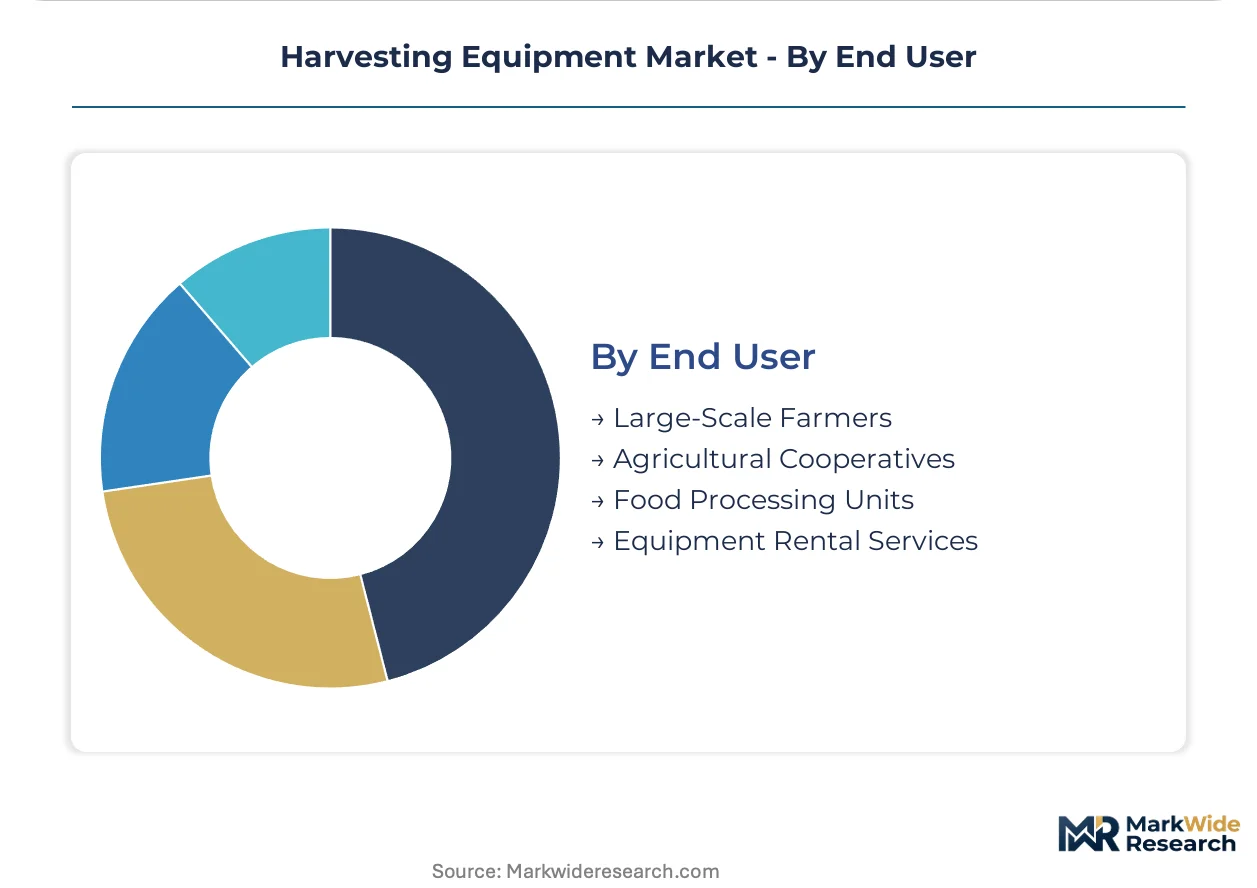
End User:
Supply concentration among OEMs with precision agriculture ecosystems shapes procurement access for different buyer scale tiers.
- Large-Scale Farmers:Individual estates with 5,000+ acre operations and in-house maintenance capabilities. These buyers in Australia's wheat belt are absorbing EU Stage V compliant configurations despite weight and cooling complexity additions.
- Agricultural Cooperatives:Shared-equipment pools with multi-operator credentialing requirements. Eastern European cooperatives in Ukraine and Romania are consolidating procurement through seasonal leasing platforms rather than individual ownership.
- Food Processing Units:Vertically integrated operators with captive harvesting requirements.
- Equipment Rental Services:Third-party fleet operators with usage-based billing models.
Large-Scale Farmers commit the majority of capital expenditure; Agricultural Cooperatives are expanding most quickly as shared-access models compress individual ownership economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and US manufacturing clusters while Brazilian and Indian producers absorb cost compression from emission compliance and import tariff structures.
United States
EPA Tier 4 Final standards are forcing fleet turnover across Iowa and Illinois grain belts as operators retire pre-2015 mechanical-hydraulic combines. The FAA is developing coordination protocols for autonomous ground harvesters operating alongside aerial spraying drones. Deere & Company anchors precision agriculture ecosystems from its Illinois and Iowa manufacturing footprint.
Germany
EU Stage V emission frameworks mandate diesel particulate filters and selective catalytic reduction systems on engines above 56 kW, adding weight and cooling complexity to combine designs. CLAAS KGaA mbH leverages its Harsewinkel engineering base to serve European wheat zones with compliant configurations. Bavarian dairy cooperatives are consolidating procurement toward GPS-enabled forage harvesters with yield-mapping integration.
Brazil
IBAMA, the national environmental regulator, enforces deforestation-linked equipment financing restrictions in the Amazon biome, constraining fleet expansion in northern agricultural frontiers. Mato Grosso soybean operators are replacing aging Class 7 and Class 8 fleets with autonomous platforms despite upfront cost premiums. Sampo-Rosenlew Oy and other specialized manufacturers are penetrating the Cerrado mechanization belt through regional distribution partnerships.
India
Maharashtra and Punjab wheat belts are absorbing mid-range mechanical harvesters as price-sensitive cooperative buyers delay GPS-enabled adoption. The Bureau of Indian Standards governs machinery safety certification for import market access, while the Production-Linked Incentive scheme supports domestic component manufacturing. Haryana's rice-wheat rotation districts are exhibiting fastest uptake of trailed harvesting equipment among South Asian markets.
Canada
Skilled combine technician availability is collapsing across Saskatchewan and Manitoba, pushing Prairie cooperatives toward subscription-based fleet management and autonomous GPS-enabled platforms. Health Canada and PMRA regulate aerial spraying coordination with ground-based autonomous systems. Alberta's large-scale estate operators are consolidating procurement toward 12-month utilization models to amortize Tier 4 Final compliance premiums.
Harvesting Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision agriculture ecosystems commanding premium positioning while mechanical specialists serve price-sensitive emerging markets. The vendor base clusters around three strategic archetypes: integrated precision agriculture platforms, dual-brand distribution networks, and mid-range mechanical specialists. Dominant competitive moves include backward integration into sensor and software stacks and geographic expansion through regional assembly partnerships.
Among North American integrated platform providers, Deere & Company exemplifies the precision agriculture ecosystem archetype, while CNH Industrial N.V. occupies a position spanning dual-brand distribution across European wheat zones and Latin American soybean regions. AGCO Corporation represents the mid-range mechanical specialist tier, anchoring cooperative buyer relationships in Eastern Europe. These three players collectively illustrate the competitive tension between subscription-based software revenue models and traditional equipment sales cycles.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial N.V. |
| AGCO Corporation |
| CLAAS KGaA mbH |
| KUBOTA Corporation |
| Mahindra & Mahindra Ltd. |
| YANMAR HOLDINGS Co., Ltd. |
| Maschinenfabrik Bernard KRONE GmbH & Co. KG |
| Sampo-Rosenlew Oy |
| Others |
Pricing and Supply Chain Analysis
Ninety-day engine procurement lead times for Tier 4 Final compliant powertrains concentrate pricing power with German and US manufacturing clusters while compressing margins for South Asian mechanical harvester assemblers dependent on imported diesel engine blocks.
Pricing Analysis
Configured-to-order premiums for GPS-enabled autonomous platforms run 15-25 points above standard mechanical configurations. Three-tier pricing structure across premium autonomous, standard GPS-enabled, and economy mechanical levels anchors procurement decisions. Cost compression in the mechanical tier intensifies because EPA Tier 4 Final redesigns raise baseline engine costs without commensurate feature differentiation. Agricultural cooperatives in Eastern Europe exhibit highest price sensitivity; large-scale estate operators in Australia's wheat belt absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Port congestion on Hamburg-Rotterdam feeder routes and container availability constraints on Asia-Europe trade lanes fragment component delivery schedules for precision agriculture sensor modules. Manufacturing gravity centers on Germany, the United States, and Brazil for final assembly, with China and Japan feeding critical LiDAR and GPS subsystems. Supply chains rest on high-grade steel forgings, semiconductor control modules, and selective catalytic reduction aftertreatment hardware. Single-source vulnerability concentrates in LiDAR sensor arrays from specialized vendors. Distribution runs through OEM-captive dealer networks with regional parts depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service subscription models threaten traditional unit-sales economics, forcing incumbents to defend installed base relationships against autonomous fleet operators offering outcome-based harvesting contracts.
For Market Incumbents: Consolidate precision agriculture software stacks through backward integration into sensor hardware and yield-mapping algorithms. Lock dealer service revenue through multi-year telemetry subscription bundles that extend beyond equipment warranty periods. Autonomous navigation vendors bypassing OEM control over precision ecosystems represent the primary substitution threat.
For New Entrants and Emerging Players: Aftermarket technician availability collapse across the Canadian Prairies and US Corn Belt opens white-space for mobile service platforms and predictive maintenance analytics. Target cooperative buyers in Poland and Romania with seasonal leasing software that multi-operator credentialing demands. Pursue fleet-management SaaS partnerships with existing mechanical harvester distributors rather than competing on hardware.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription-based yield-mapping and autonomous coordination software will capture margin pools that mechanical parts once dominated. Acquisition candidates include LiDAR navigation specialists and regional leasing platform operators. Monitor EPA enforcement variance across US states as inflection signal for autonomous liability framework maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Hardware | CLAAS and Deere captive LiDAR production reduces dependency on automotive-tier suppliers. |
| Autonomous Fleet Coordination Platform | Swarm algorithms for multiple combines optimize harvest windows in Mato Grosso soybean belts. |
| Seasonal Leasing Software Launch | Multi-operator credentialing systems capture Eastern European cooperative procurement consolidation. |
| Telematics Service Contract Expansion | Usage-based billing extends dealer revenue beyond equipment sale into 10-year service horizons. |
| Regional Assembly Partnership | Brazilian Cerrado manufacturing avoids IBAMA financing restrictions on imported equipment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of OEM technical documentation, EPA enforcement records, and EU Stage V certification databases. Interviews with combine fleet managers, precision agriculture software engineers, dealer service directors, and cooperative procurement officers informed demand-side dynamics. Secondary validation drew from USDA equipment sales reports, ANFAVEA Brazilian machinery statistics, and ISO 12100 safety certification registries. Bottom-up unit demand estimates triangulated against top-down OEM revenue disclosures.
Segmentation dimensions modeled span equipment type, technology tier, application intensity, and end-user scale across the projection horizon. Analytical framework derives CAGRs from replacement cycle compression, emission compliance deadlines, and labor economics deterioration. Forecast inputs incorporate EPA Tier 4 Final enforcement trajectories and autonomous navigation stack maturation curves.
Material uncertainties — regulatory divergence on autonomous operation liability, commodity price volatility affecting farm capital budgets, and technician availability collapse severity — sit outside the modeled envelope. Forecasts reflect assumptions about emission standard adherence and software subscription adoption velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Corn Milling Machine Market
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Destoner Machine Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Global Nut Processing Equipment Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Rice Milling Machines Market
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Manure Handling Equipment Market