
 Destemmer Machine Market | 2026-2036
Destemmer Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Destemmer Machine Market Outlook
Contract winemaking services is bifurcating demand between estate vineyards and third-party crush facilities. Zambelli Enotech leverages its Italian manufacturing base to dominate European supply chains for pneumatic destemmers. Bucher Vaslin sustains technology leadership through electromechanical R&D programs in France's Champagne region. Della Toffola Group anchors its position with integrated crushing and sorting lines that compete on throughput efficiency for large-scale juice manufacturers.
A destemmer machine separates grape berries from their stems through rotating perforated cylinders, beaters, or centrifugal mechanisms, with throughput rates ranging from 500 kilograms to over 30 tonnes per hour depending on configuration. The equipment serves primarily to reduce tannin extraction from stems during red wine fermentation and to prepare clean fruit for juice concentration processes. Automatic electromechanical systems command premium positioning among high-volume vineyards, while manual and semi-automatic variants retain durable demand from small-lot producers and restaurants where capital constraints limit technology uptake. Pneumatic destemming technology leads in gentleness metrics for premium wine applications, though hydraulic systems persist in established European installations where replacement cycles lag.
FDA food-contact material standards govern stainless steel specifications and sanitary design requirements for destemmers entering US juice manufacturing facilities, while EU Machinery Directive 2006/42/EC mandates CE marking for automated systems sold across member states. REACH compliance pressures European manufacturers to document substance safety for polymer components in roller and cage assemblies. Stakeholders must weigh electromechanical migration timelines against installed-base service revenue as regulatory phasedowns on pneumatic refrigerants accelerate equipment replacement decisions.
Market Dynamics
The EU's F-Gas Regulation is compressing replacement cycles across European wine processing corridors, forcing electromechanical migration while service revenue from pneumatic installed bases erodes. Boutique wineries in Oregon and Sonoma County are simultaneously expanding automated destemming capacity to capture premium wine demand, creating divergent regional equipment strategies.
Growth Catalysts
- EU F-Gas phasedown:The regulation mandates refrigerant-dependent cooling system retirement, accelerating electromechanical destemmer procurement across Champagne, Prosecco, and Franciacorta corridors.
- Premium wine demand concentration:Boutique wineries in Oregon and Sonoma County are automating crush facilities to meet rising estate-bottled red wine requirements.
- Vineyard consolidation in Northern Italy:Large-scale juice manufacturers are replacing legacy equipment with high-throughput integrated crushing and sorting lines.
Market Restraints
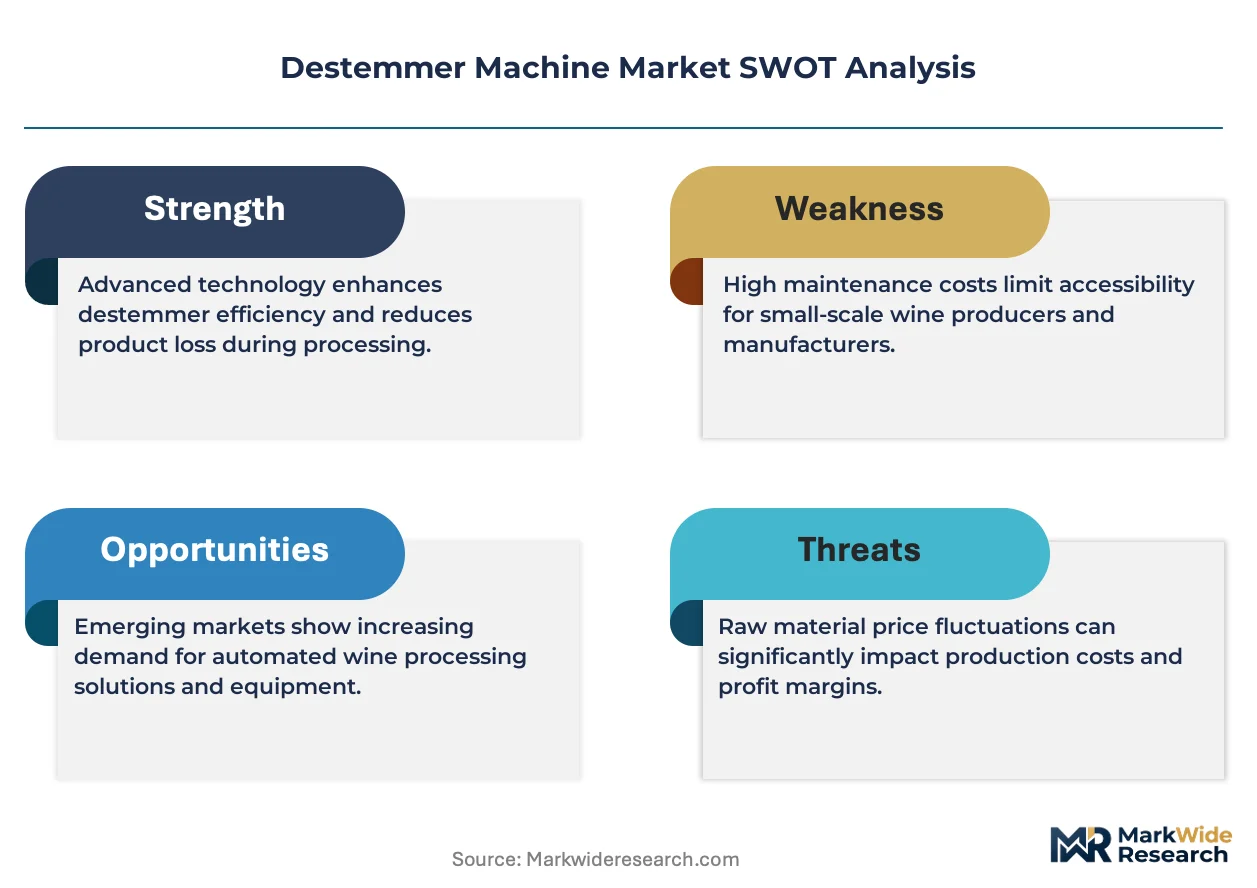
- Stainless steel input volatility:FDA food-contact material specifications for 304 and 316L grades expose manufacturers to nickel and chromium price swings.
- European supply concentration:Pneumatic destemmer component sourcing clusters in Northern Italy, creating vulnerability to regional logistics disruptions.
- Hydraulic system lock-in:Established European installations face technical limitations in retrofitting legacy hydraulic destemmers for electromechanical operation.
Strategic Opportunities
- Contract winemaking expansion:Third-party crush facilities in California's Central Valley represent underpenetrated demand for mid-capacity automated systems.
- Electromechanical-pneumatic hybrid convergence:Combining gentle berry handling with refrigerant-free cooling creates premium positioning for Franciacorta sparkling wine producers.
- Indian wine sector emergence:Nascent vineyard development in Maharashtra and Karnataka creates first-mover positioning for semi-automatic destemmer suppliers.
Industry Challenges
- CE marking certification timelines:EU Machinery Directive 2006/42/EC compliance documentation delays electromechanical system launches by 8-14 months.
- Legacy system integration complexity:Automated destemmers must synchronize with existing crusher-stemmer sequences and sorting tables without production line shutdown.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Destemmer Machine Market |
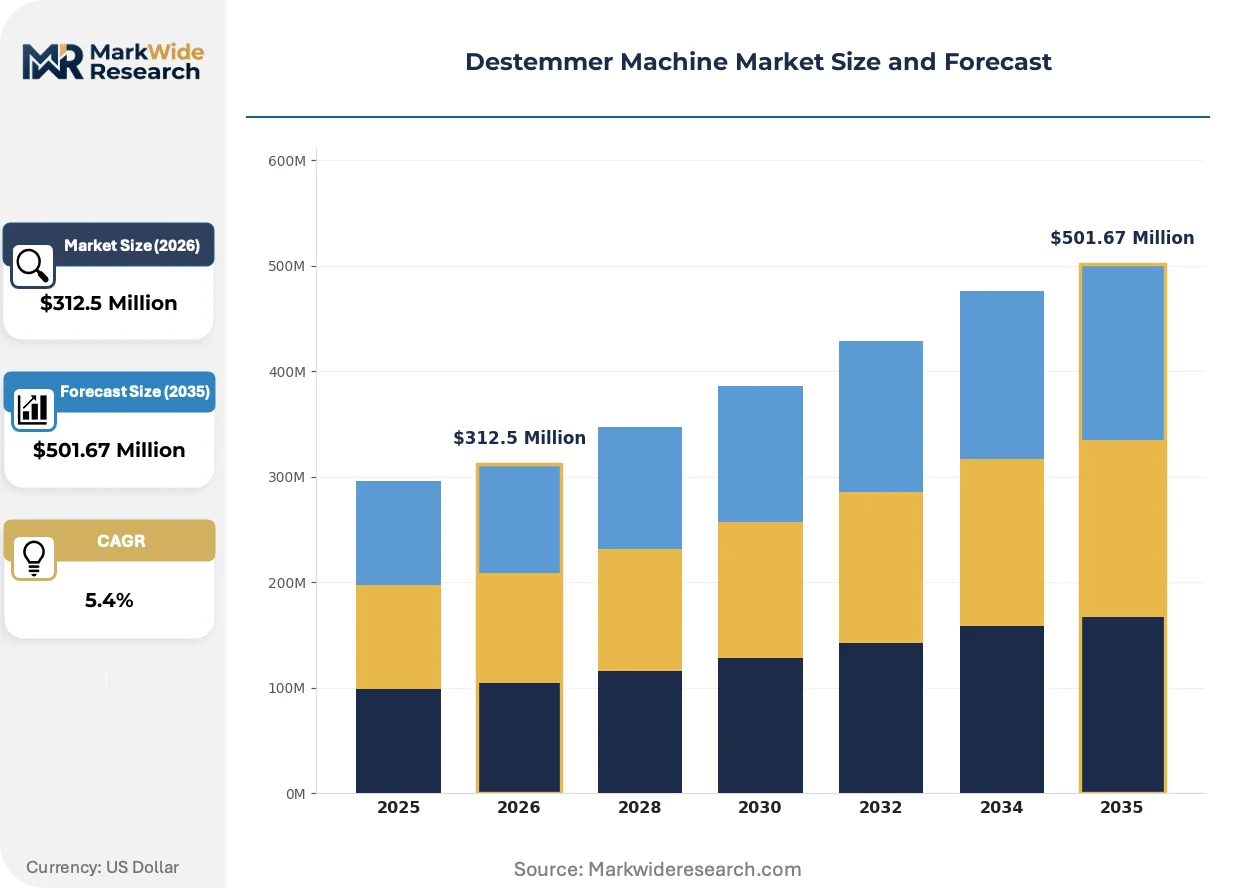
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, Electric Application: Wine Production, Juice Extraction, Fruit Processing, Culinary Use End User: Vineyards, Juice Manufacturers, Restaurants, Home Users Technology: Mechanical, Pneumatic, Hydraulic, Electromechanical |
| Companies Covered | Zambelli Enotech, Bucher Vaslin, Della Toffola Group, Enoitalia, Scharfenberger GmbH & Co. KG, Enoveneta, Pera-Pellenc S.A., Criveller Group, Scott Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Destemmer Machine Market Strategic Shifts
Processing technology is bifurcating between gentle-handling premium systems and brute-force juice extraction equipment, with regulatory pressure accelerating the split. Electromechanical innovation, compliance-driven material substitution, and service model restructuring are the three forces reshaping competitive positioning.
Centrifugal destemming technology is fragmenting the premium wine equipment segment. Rotating perforated cylinder designs with variable frequency drives enable berry separation at sub-2% stem fragment rates. Estate vineyards in Burgundy and Willamette Valley are adopting these systems for pinot noir lots. The technology is fragmenting supplier hierarchies by enabling Italian electromechanical specialists to challenge established pneumatic incumbents.
REACH compliance is forcing polymer component documentation across roller and cage assemblies. ECHA substance safety registrations now govern polyurethane and nylon formulations in contact surfaces. European manufacturers face reformulation costs or supply base switches. The regulation most affects mid-cap equipment producers lacking in-house polymer chemistry capabilities.
After-sales service unbundling is disrupting traditional equipment procurement in high-volume juice manufacturing. Large-scale processors now separate destemmer acquisition from maintenance contracts, soliciting third-party technical service bids. This compresses OEM service margins while opening independent technician networks. The pattern is most visible in California's Central Valley bulk wine and concentrate facilities.
Destemmer Machine Market Segmentation
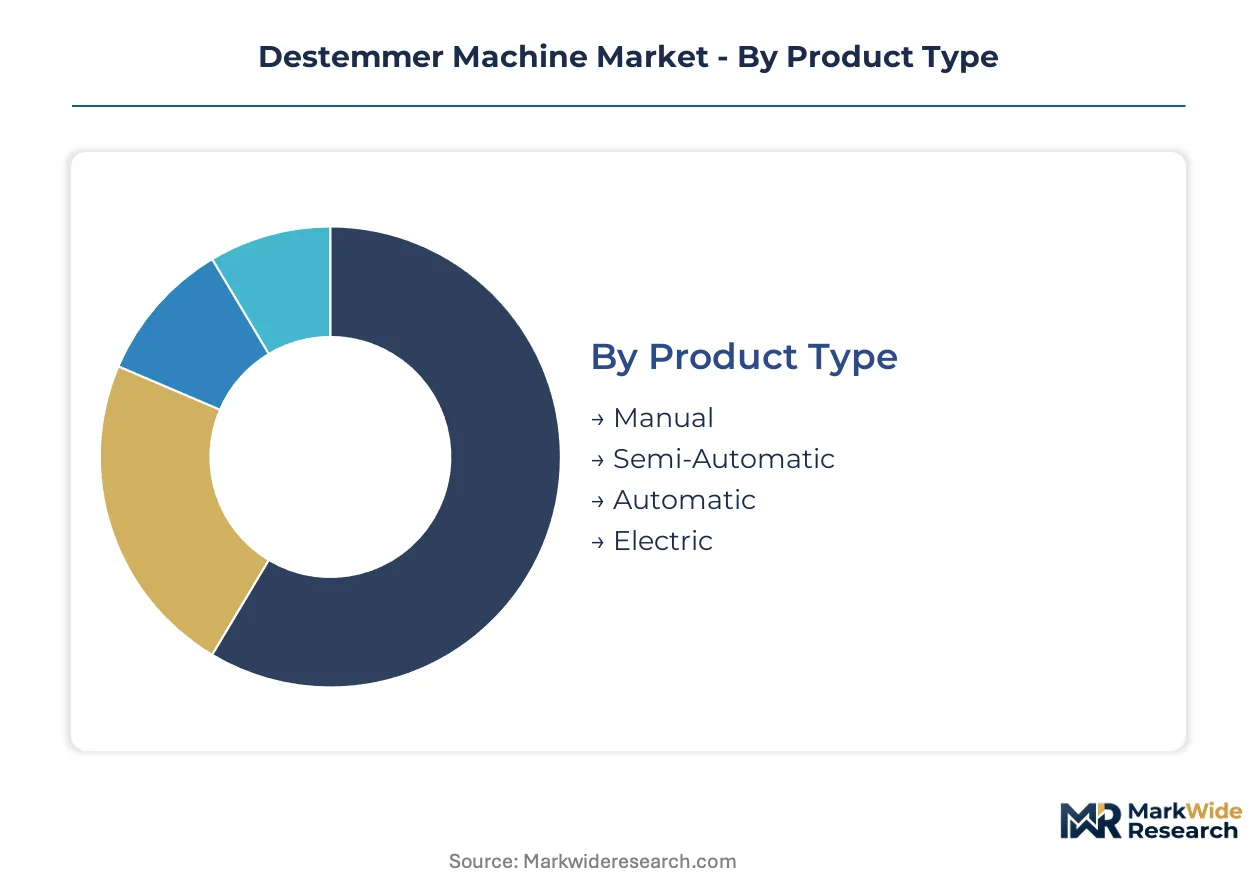
Destemmer machine procurement patterns diverge sharply between premium wine estates prioritizing berry integrity and bulk juice operators optimizing throughput per labor hour. Equipment specification cascades through four interlocking dimensions that determine technology selection, compliance burden, and service lifecycle economics.
Product Type:
Margin pools concentrate in automatic systems where electromechanical innovation commands pricing premiums, while manual variants sustain durable aftermarket parts revenue from estate vineyards with limited capital refresh cycles.
- Automatic:Variable frequency drive systems with rotating perforated cylinders achieve sub-2% stem fragment rates. Demand clusters in Burgundy and Willamette Valley pinot noir operations where gentle handling preserves phenolic precision. The EU F-Gas Regulation accelerates replacement of refrigerant-dependent cooling modules in these configurations.
- Semi-Automatic:Hybrid loading mechanisms with operator-controlled destemming intensity bridge capital constraints and quality requirements. Third-party crush facilities in California's Central Valley are standardizing on these units to handle multiple varietal contracts without dedicated lines.
- Manual:Hand-cranked perforated drums serve restaurant wine programs and home producers in emerging markets where electricity reliability limits automation.
- Electric:Fixed-speed motor drives without programmable controls occupy the entry tier for small-lot producers in India's Maharashtra corridor.
Automatic systems hold installed capacity across European premium corridors. Semi-Automatic is rotating up the share rankings in contract winemaking facilities.
Application:
Volume concentration follows divergent processing economics, with wine production prioritizing stem exclusion precision and juice extraction maximizing tons-per-hour throughput.
- Wine Production:Tannin management requirements drive specification toward pneumatic and electromechanical systems with adjustable cage apertures. Northern Italy's Prosecco and Franciacorta corridors are replacing legacy hydraulic equipment to meet sparkling wine pressure-sensitivity standards.
- Juice Extraction:Brute-force mechanical destemming with integrated crushing serves concentrate manufacturers in California's Central Valley. FDA food-contact material specifications for 304 and 316L stainless steel govern equipment qualification.
- Fruit Processing:Cross-berry adaptability for blueberries and cranberries extends equipment utilization beyond grape harvest windows. Pacific Northwest cooperatives deploy these configurations.
- Culinary Use:Compact tabletop units serve restaurant fermentation programs and culinary education institutions with sub-500 kilogram hourly throughput requirements.
Wine Production dominates replacement spending. Juice Extraction is expanding most quickly as vineyard consolidation concentrates processing volume.
End User:
Procurement authority splits between estate vineyards with quality-driven specification and third-party facilities where equipment utilization rates determine ROI thresholds.
- Vineyards:Estate-bottled producers in Oregon and Sonoma County automate crush facilities to capture premium red wine price realization. Electromechanical systems with berry sorting integration command specification priority.
- Juice Manufacturers:Large-scale concentrate processors unbundle equipment acquisition from maintenance contracts, compressing OEM service margins. After-sales service unbundling is most visible in California's Central Valley bulk facilities.
- Restaurants:Urban wine programs in metropolitan markets source compact semi-automatic units for on-site fermentation differentiation.
- Home Users:Entry-level manual and electric configurations serve amateur winemakers in emerging markets with nascent vineyard development.
Vineyards anchor replacement demand. Juice Manufacturers are climbing the fastest as contract winemaking expands processing outsourcing.
Technology:
Regulatory phasedown on pneumatic refrigerants is compressing technology migration timelines while service revenue from installed hydraulic bases erodes.
- Electromechanical:Motor-driven rotating cages with programmable speed profiles eliminate refrigerant-dependent cooling. The EU F-Gas Regulation mandates this migration across Champagne, Prosecco, and Franciacorta corridors.
- Pneumatic:Compressed air systems retain gentleness leadership for premium berry handling but face component sourcing concentration in Northern Italy. REACH compliance pressures polymer formulation documentation for roller assemblies.
- Hydraulic:Established European installations face technical limitations in retrofitting legacy equipment for electromechanical operation. Replacement cycles lag in older Champagne houses.
- Mechanical:Fixed-speed drum systems persist in entry-tier and developing market applications where capital constraints dominate specification.
Pneumatic technology holds legacy installed base. Electromechanical is gaining share fastest as regulatory deadlines compress procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters in Northern Italy, France's Champagne corridor, and Germany's industrial belt supply the majority of destemmer systems worldwide. Regional procurement patterns diverge sharply between European regulatory-driven replacement cycles and New World capacity expansion.
United States
Oregon's Willamette Valley and Sonoma County estates are automating crush facilities to capture premium pinot noir and cabernet price realization. FDA food-contact material standards govern 304 and 316L stainless steel specifications for equipment entering juice manufacturing facilities. California's Central Valley bulk wine processors are unbundling equipment acquisition from maintenance contracts.
Italy
Prosecco and Franciacorta vineyard consolidation is driving replacement cycles for high-throughput integrated crushing and sorting lines. The EU F-Gas Regulation is compressing electromechanical migration timelines across pneumatic installed bases. Northern Italy's component sourcing concentration for pneumatic destemmer assemblies creates logistics vulnerability.
France
Champagne houses face technical limitations in retrofitting legacy hydraulic destemmers for electromechanical operation. EU Machinery Directive 2006/42/EC mandates CE marking compliance documentation that delays system launches. The Champagne region's established equipment base sustains technology leadership through dedicated R&D programs.
Germany
REACH compliance pressures polymer formulation documentation for roller and cage assemblies in mid-cap equipment production. ECHA substance safety registrations now govern polyurethane and nylon formulations in contact surfaces. German fabricators face reformulation costs or supply base switches for polymer components.
India
Nascent vineyard development in Maharashtra and Karnataka is creating first-mover positioning opportunities for semi-automatic destemmer suppliers. The country's national food safety regulator is developing alignment with international sanitary design standards. Capital constraints in emerging wine regions favor entry-tier electric configurations over full automation.
Destemmer Machine Market Competitive Environment
Concentration sits with Italian electromechanical specialists and French pneumatic incumbents who anchor supply chains across European premium wine corridors. The vendor base stratifies across three tiers: integrated line manufacturers competing on throughput efficiency, component specialists dominating regional service networks, and emerging Asian fabricators targeting price-sensitive developing markets. Two dominant competitive moves are reshaping positioning: technology licensing agreements that accelerate electromechanical migration timelines, and backward integration into stainless steel component fabrication to hedge nickel and chromium input volatility.
Within the European specialist tier, Zambelli Enotech and Bucher Vaslin exemplify divergent technology strategies—Italian electromechanical innovation against French pneumatic heritage. Della Toffola Group occupies a position as an integrated line manufacturer competing on throughput efficiency for large-scale juice processors. Scharfenberger GmbH & Co. KG represents the German mid-cap segment facing REACH compliance pressures on polymer formulations.
| Leading Market Players |
|---|
| Zambelli Enotech |
| Bucher Vaslin |
| Della Toffola Group |
| Enoitalia |
| Scharfenberger GmbH & Co. KG |
| Enoveneta |
| Pera-Pellenc S.A. |
| Criveller Group |
| Scott Laboratories Inc. |
| Others |
Value Chain & Pricing Dynamics
Fourteen-week lead times for electromechanical drive assemblies from Northern Italian fabricators concentrate pricing power with established European suppliers while compressing margins for mid-cap competitors lacking captive component sourcing. This inventory-to-delivery gap shapes procurement decisions across premium wine corridors and bulk juice facilities alike.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European destemmer procurement, separating refrigerant-compliant electromechanical systems at premium positioning from legacy pneumatic and hydraulic equipment facing accelerated depreciation. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling, with CE-marked automatic systems commanding the highest tier. Cost compression in mid-cap semi-automatic configurations is intensifying because stainless steel input volatility exposes manufacturers to nickel and chromium price swings. Third-party crush facilities in California's Central Valley exhibit the highest price sensitivity, while estate vineyards in Burgundy and Willamette Valley prioritize berry integrity over unit economics.
Supply Chain Analysis
Italy, France, and Germany anchor destemmer equipment fabrication, with Northern Italian specialists dominating pneumatic component production and Champagne-region houses sustaining hydraulic system legacy bases. Stainless steel 304 and 316L grades, polymer formulations for roller assemblies, and variable frequency drive modules constitute critical input dependencies. Single-source vulnerability clusters in Northern Italy's pneumatic component corridor, where regional logistics disruptions ripple through European supply chains. Distribution runs through OEM-direct sales for large-scale juice manufacturers and regional equipment dealers serving estate vineyards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract winemaking expansion fragments demand between quality-driven estate specifications and utilization-optimized third-party facilities, creating distinct competitive arenas for technology positioning and service model innovation.
For Market Incumbents: Compound technology leadership in electromechanical systems by accelerating R&D programs in France's Champagne region while backward integrating into stainless steel component fabrication to hedge nickel and chromium input volatility. Defend installed-base service revenue against unbundling pressures by embedding predictive maintenance modules in automatic system architectures. The threat of emerging Asian fabricators targeting price-sensitive developing markets demands proactive certification investment in India's Maharashtra corridor. For New Entrants and Emerging Players: Anchor in India's nascent vineyard development across Maharashtra and Karnataka, where capital constraints favor entry-tier electric configurations and first-mover positioning remains available. Target semi-automatic destemmer demand from third-party crush facilities in California's Central Valley, where equipment utilization rates determine ROI thresholds and mid-cap competitors lack dedicated service networks. A go-to-market angle emphasizing cross-berry adaptability for blueberries and cranberries extends equipment utilization beyond grape harvest windows. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-driven replacement cycle play because EU F-Gas phasedown mandates compress electromechanical migration timelines across pneumatic installed bases. Acquisition targets should exhibit in-house polymer chemistry capabilities to manage REACH compliance pressures on roller and cage assemblies, or captive stainless steel fabrication to offset input volatility. The signal to watch is after-sales service unbundling penetration in California's Central Valley bulk facilities, which indicates margin compression velocity for OEM service revenue.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Technology Licensing | Accelerates refrigerant-free migration timelines across Champagne and Prosecco corridors. |
| Stainless Steel Backward Integration | Hedges nickel and chromium price volatility for FDA food-contact material compliance. |
| Polymer Formulation Reformulation | Addresses ECHA substance safety registration requirements under REACH compliance. |
| Contract Winemaking Service Unbundling | Opens independent technician networks as California bulk processors separate acquisition from maintenance. |
| Indian Market First-Mover Positioning | Captures nascent vineyard development in Maharashtra before standardization locks in supplier relationships. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with winemaking facility managers, equipment procurement leads at juice manufacturers, aftermarket service technicians, and regulatory compliance officers across European and North American wine corridors. Secondary validation drew from EU Machinery Directive implementation guidance, ECHA substance safety databases, FDA food-contact material standards, customs trade data for stainless steel equipment imports, and SEC filings from publicly traded agricultural equipment manufacturers. Bottom-up equipment shipment estimates were triangulated against top-down vineyard acreage and processing capacity projections.
Across the analysis window, the analytical framework modeled volume and value outputs through segmentation across product type, application, end user, and technology dimensions, with additional granularity for regulatory compliance tier and regional replacement cycle timing. CAGRs were derived from installed base depreciation curves and electromechanical migration velocity assumptions. Industry-specific forecast inputs included EU F-Gas Regulation phasedown deadlines and vineyard consolidation patterns in Northern Italy's Prosecco corridor.
Material uncertainties — stainless steel commodity price volatility, CE marking certification delays, and logistics disruptions in Northern Italian component sourcing — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and replacement cycle acceleration that could shift with macroeconomic conditions or policy amendments. Recalibration cycles align with material shifts in F-Gas Regulation implementation timelines and vineyard consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Asia-Pacific Agricultural Shredder Machine Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
India Rice Milling Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Dal Mill Machine Market
Agricultural Processing Equipment
Corn Thresher Market
Agricultural Processing Equipment
North America Feed Pelletizing Agent Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market