
 Solar Herbs Dryer Market | 2026-2036
Solar Herbs Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Herbs Dryer Market Insights
ISO 9001 quality management certification is redrawing competitive boundaries in solar herbs drying equipment, forcing smaller fabricators toward third-party auditing or exit. Ecozen Solutions leverages its Indian engineering base to dominate active dryer deployments across turmeric and cardamom belts. Suncue Company Ltd. sustains technology leadership in heat exchanger configurations for humid subtropical conditions. Agro Solar Europe GmbH anchors premium positioning through CE-marked passive dryer lines sold to organic herb cooperatives.
Solar herbs dryers harness photovoltaic or thermal solar collection to reduce crop moisture content from sixty to twelve percent without fossil fuel combustion, preserving volatile oil profiles critical to pharmaceutical and culinary grades. The equipment typically integrates polycarbonate glazing, aluminum absorber plates, and forced-air or natural convection channels sized to batch capacities between fifty and five hundred kilograms. Active dryers lead installed capacity due to their reliability during monsoon seasons, while hybrid dryers represent the fastest-expanding category as processors seek backup biomass or electric heating for continuous operation. Direct solar technology occupies the largest share of farmer-level purchases, though indirect solar systems command higher margins among certified organic exporters requiring HACCP-aligned temperature control.
India's BIS mandates structural safety testing for solar thermal equipment, while the EU F-Gas Regulation indirectly pressures European manufacturers to eliminate synthetic refrigerant dependencies in hybrid designs. The US FDA's Foreign Supplier Verification Program shapes export-oriented dryer specifications, particularly moisture uniformity documentation for imported dried botanicals. Stakeholders must monitor how evolving energy subsidy regimes and phytosanitary certification requirements alter equipment procurement criteria across origin and destination markets.
Market Dynamics
India's PLI scheme for clean energy equipment is compressing equipment procurement timelines as turmeric and ginger processors in Maharashtra and Karnataka replace fuel-powered dehydration with solar thermal systems ahead of FDA moisture compliance deadlines.
Growth Catalysts
- FDA Foreign Supplier Verification Program:US import scrutiny of herb moisture content is forcing certified organic exporters to document temperature uniformity, pulling demand toward HACCP-aligned indirect solar dryers.
- Volatile oil preservation:Pharmaceutical-grade botanical buyers now specify solar dehydration to protect active compounds, displacing fossil-fuel ovens in cardamom and ashwagandha processing clusters.
- EU F-Gas Regulation:Synthetic refrigerant phase-down in hybrid dryer designs is accelerating thermal storage innovation among European organic herb cooperatives seeking CE-marked equipment.
Market Restraints
- Aluminum absorber plate cost volatility:Input price swings for thermal collection materials squeeze fabricator margins, particularly for passive dryer lines targeting smallholder budgets.
- Monsoon reliability gap:Natural convection systems face capacity utilization collapse during India's four-month wet season, constraining farmer-level adoption in Kerala and Tamil Nadu.
- BIS structural safety testing:Mandatory certification timelines for solar thermal equipment delay commercialization for smaller Indian fabricators lacking third-party laboratory relationships.
Strategic Opportunities
- Biomass-electric hybrid architectures:Continuous operation backup systems are capturing premium positioning among Southeast Asian spice exporters facing grid intermittency.
- ISO 9001 certification gap:Quality management auditing scarcity among regional fabricators creates white space for compliant equipment vendors to consolidate turmeric belt procurement.
- Polycarbonate glazing advances:UV-stabilized panel convergence with forced-air channel design is opening pharmaceutical contract manufacturing specifications previously closed to solar thermal.
Industry Challenges
- Thermal engineer scarcity:Heat exchanger configuration expertise for humid subtropical conditions concentrates among a handful of equipment designers, constraining deployment velocity.
- CE marking timeline compression:European organic cooperatives demand faster certification cycles than passive dryer lines can deliver, creating order backlogs.
- Legacy fuel oven integration:Ginger processors face operational friction retrofitting batch workflows designed around LPG combustion to solar thermal batch capacities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Herbs Dryer Market |
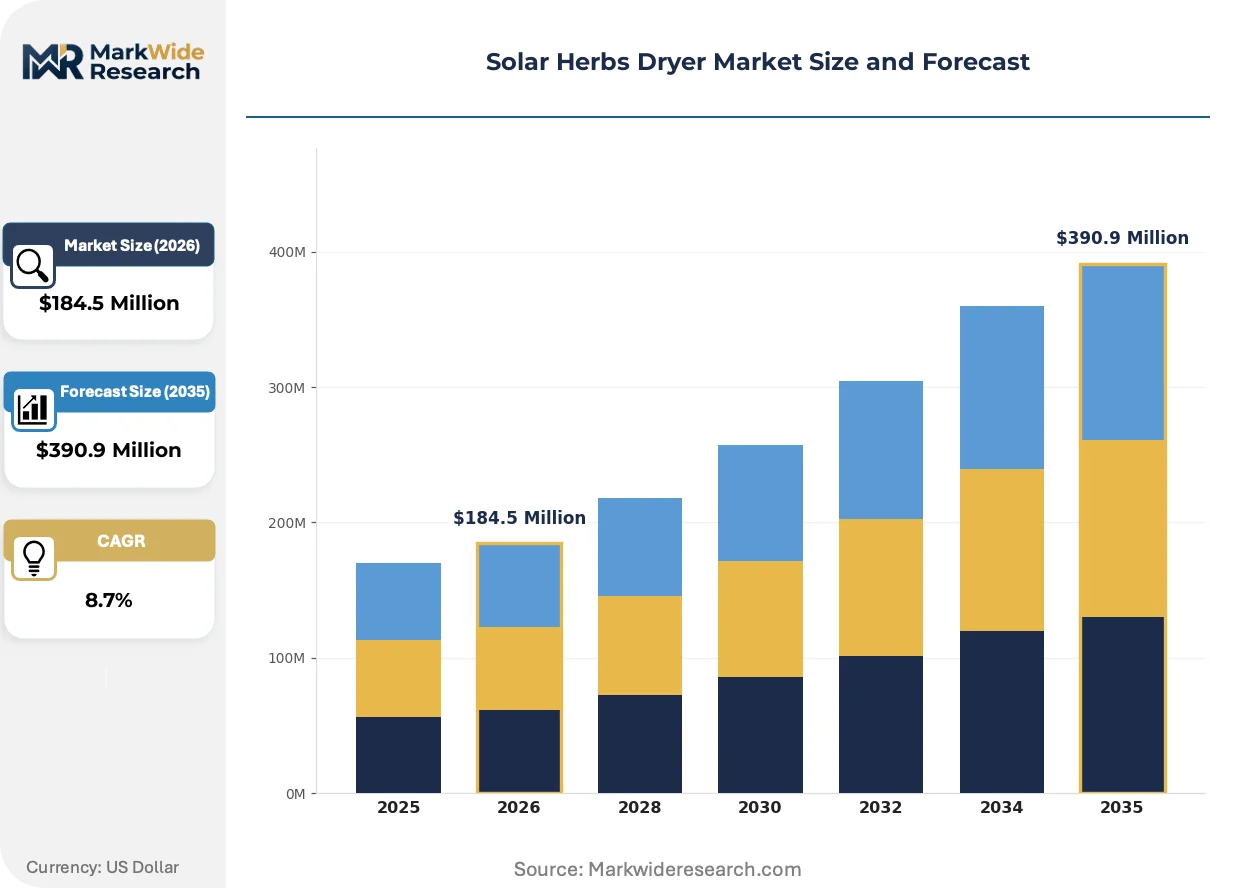
| Market Size in 2026 | $184.5 Million |
| Market Size in 2035 | $390.9 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Dryers, Active Dryers, Hybrid Dryers, Vacuum Dryers Technology: Direct Solar, Indirect Solar, Thermoelectric, Heat Exchanger End User: Farmers, Herb Processors, Food Manufacturers, Exporters Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Ecozen Solutions, Suncue Company Ltd., Agro Solar Europe GmbH, Solar Dryers Australia, Solar Conduction Dryer Pvt. Ltd., Sun Best, Ecosolaris, SolarTech Solutions, SolarFlex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Herbs Dryer Market Trends and Innovations
Equipment architecture is pivoting toward hybrid thermal storage as processors reject single-source energy dependency. Regulatory documentation requirements now shape R&D roadmaps more than raw efficiency metrics.
Forced-air solar dryers with photovoltaic-powered circulation fans are displacing natural convection systems in India's turmeric belt. Medium-scale processors operating fifty to two hundred kilogram batches are adopting active ventilation to maintain throughput during monsoon humidity spikes. This shift is compressing the addressable market for passive polycarbonate designs while elevating margin capture for thermal storage-integrated equipment.
The EU F-Gas Regulation's synthetic refrigerant phase-down is reshaping hybrid dryer engineering priorities. Equipment manufacturers must eliminate compressor-dependent backup heating without sacrificing temperature precision, driving investment in phase-change material thermal batteries. CE-marked lines for organic herb cooperatives now emphasize refrigerant-free biomass integration, with Germany and Italy representing the strictest compliance testing environments.
Certification-driven procurement is fragmenting buyer-seller relationships in Southeast Asian spice export corridors. Organic certifiers now audit dehydration equipment alongside agricultural practices, compelling processors to unbundle dryer purchases from general farm machinery suppliers. Vietnam and Indonesia display the sharpest channel disruption, with exporters establishing direct engineering relationships to secure HACCP-aligned documentation chains.
Solar Herbs Dryer Market Segmentation
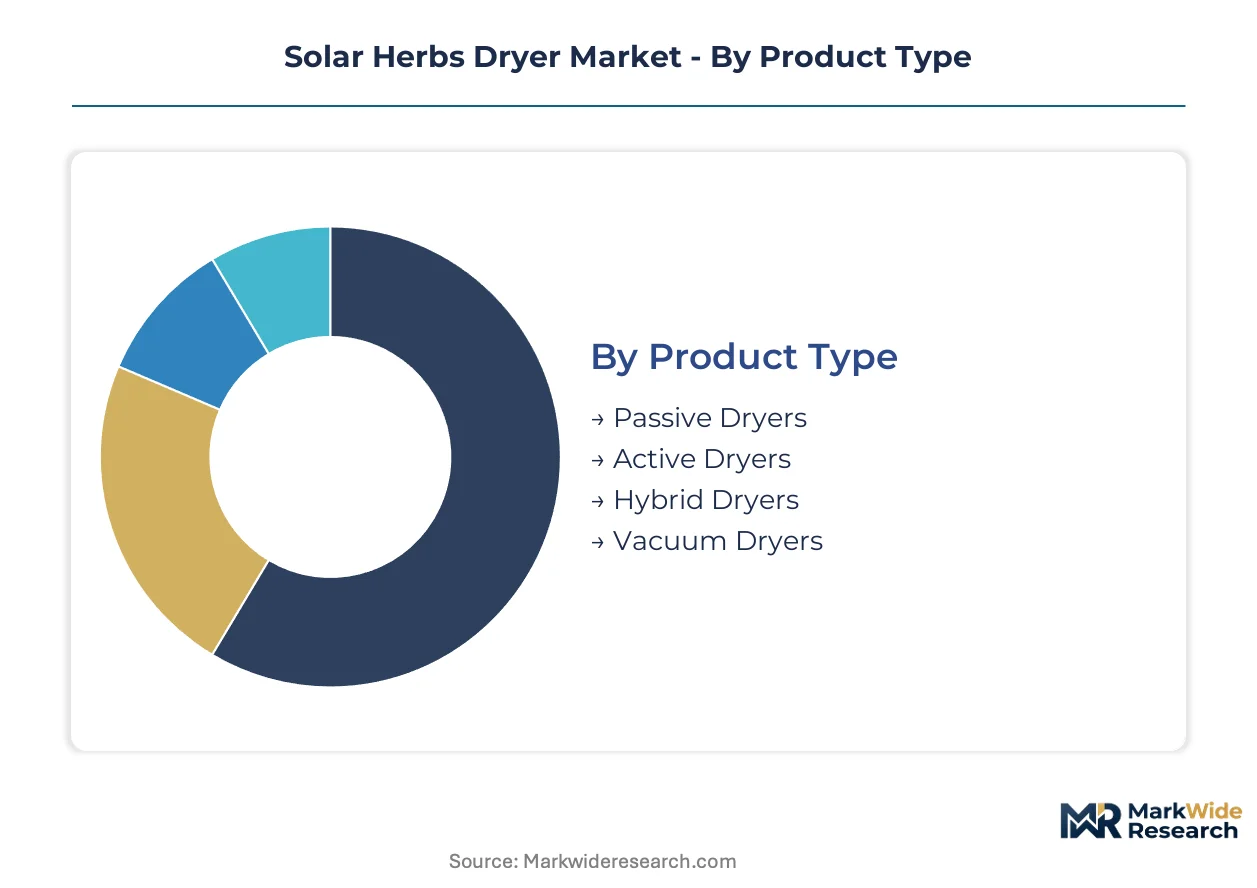
Equipment segmentation in solar herbs drying reflects divergent procurement patterns between domestic smallholders and export-oriented processors. Understanding these splits clarifies where margin capture concentrates versus where volume scales.
Product Type:
Domestic procurement in India and Southeast Asia favors passive designs for turmeric belt smallholders, while FDA-aligned exporters pull toward active and hybrid configurations with documented temperature uniformity.
- Passive Dryers:Natural convection systems with polycarbonate glazing and aluminum absorber plates require no electrical input. Demand concentrates among Maharashtra and Karnataka smallholders seeking sub-fifty kilogram batch capacity for turmeric and ginger; BIS structural safety testing delays constrain smaller fabricators from serving this tier.
- Active Dryers:Photovoltaic-powered forced-air circulation maintains throughput during monsoon humidity spikes. Export processors in Vietnam and Indonesia specify these for HACCP documentation chains; forced-air configurations now displace natural convection in India's turmeric belt.
- Hybrid Dryers:Biomass-electric backup architectures capture premium positioning among Southeast Asian spice exporters facing grid intermittency.
- Vacuum Dryers:Low-temperature dehydration preserves volatile oil profiles for pharmaceutical-grade botanical specifications.
Active dryers hold the largest share; momentum sits with hybrid configurations.
Technology:
Cost tier separation runs sharp between farmer-level direct solar purchases and certified organic exporter investment in precision-controlled indirect systems.
- Direct Solar:Sunlight strikes crop surfaces directly through transparent glazing. Farmer-level purchases across Kerala and Tamil Nadu dominate this tier; monsoon reliability gaps constrain utilization during four-month wet seasons.
- Indirect Solar:Thermal transfer via heat exchanger separates heating fluid from drying air. Organic exporters in Germany and Italy specify these for CE-marked, refrigerant-free compliance; EU F-Gas Regulation phase-down accelerates thermal storage innovation here.
- Thermoelectric:Solid-state heat pumping enables precise temperature control for high-value ashwagandha and cardamom processing.
- Heat Exchanger:Configurations optimized for humid subtropical conditions concentrate expertise among specialized equipment designers.
Direct solar dominates farmer-level volume; indirect systems command the steepest expansion trajectory among certified organic exporters.
End User:
Customer type determines specification intensity, from basic structural safety to full HACCP-aligned documentation chains.
- Farmers:Individual smallholders in India's spice belts operate sub-hundred kilogram batches; aluminum absorber plate cost volatility squeezes accessible price points.
- Herb Processors:Medium-scale operations in Vietnam and Indonesia now unbundle dryer purchases from general farm machinery suppliers to secure organic certifier audit trails.
- Food Manufacturers:Commercial kitchens and ingredient suppliers specify UV-stabilized polycarbonate glazing with forced-air channels.
- Exporters:FDA Foreign Supplier Verification Program compliance drives procurement toward ISO 9001-certified fabricators with third-party laboratory relationships.
Herb processors represent the largest installed base; exporters are climbing the fastest as certification requirements tighten.
Distribution Channel:
Channel selection tracks customer scale and documentation requirements, with direct engineering relationships displacing traditional agricultural machinery networks.
- Online Retail:E-commerce platforms serve smallholder inquiries for passive dryer specifications and spare polycarbonate panels.
- Direct Sales:Engineering relationships dominate Southeast Asian spice export corridors where organic certifiers audit equipment alongside agricultural practices.
- Distributors:Regional agricultural machinery networks retain relevance for standard passive dryer lines in India's turmeric belt.
- Wholesale:Bulk procurement cooperatives in Maharashtra and Karnataka aggregate demand for active dryer deployments.
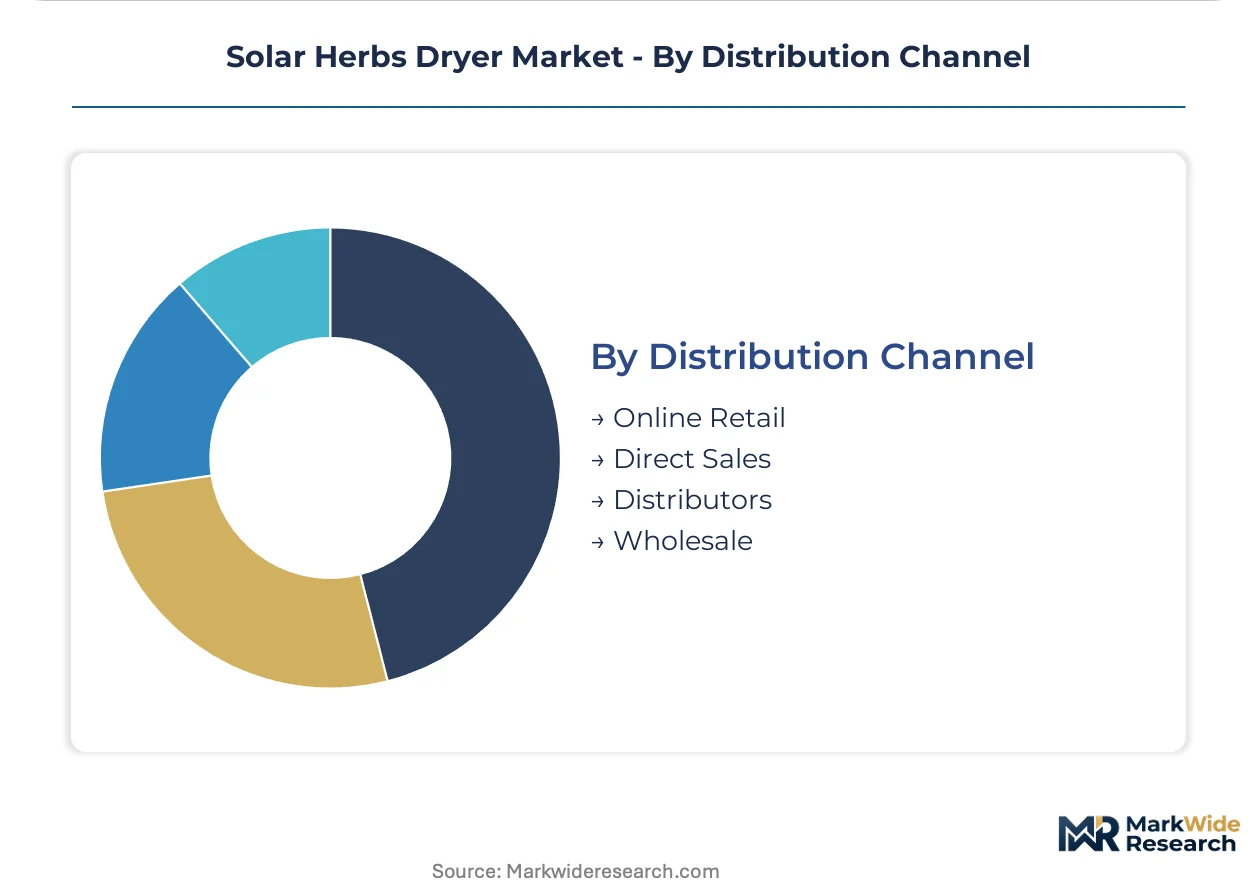
Direct sales capture the largest share; online retail is gaining share fastest among entry-level smallholders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for clean energy equipment accelerates procurement timelines across turmeric and ginger processing belts, while FDA moisture compliance deadlines compress investment cycles for export-oriented processors in Maharashtra and Karnataka.
India
Turmeric and ginger processors in Maharashtra and Karnataka states replace fuel-powered dehydration with solar thermal systems ahead of FDA Foreign Supplier Verification Program deadlines. BIS mandates structural safety testing for solar thermal equipment, delaying commercialization for smaller fabricators lacking third-party laboratory relationships. The turmeric belt clusters around Sangli, Nizamabad, and Erode drive active dryer deployments with photovoltaic-powered forced-air circulation.
Vietnam
Organic spice exporters unbundle dryer purchases from general farm machinery suppliers to secure HACCP-aligned documentation chains for EU and US markets. The country's national food safety authority tightens phytosanitary certification requirements for dehydrated botanical exports. Processing cooperatives in the Central Highlands and Mekong Delta regions establish direct engineering relationships with equipment fabricators to satisfy organic certifier audit trails.
Germany
Organic herb cooperatives demand CE-marked passive dryer lines with refrigerant-free biomass integration to satisfy EU F-Gas Regulation phase-down requirements. The country's federal environmental agency enforces strict compliance testing environments for thermal storage innovation. Equipment procurement concentrates in Bavaria and Baden-Württemberg, where pharmaceutical-grade botanical processors specify indirect solar systems with documented temperature uniformity.
Indonesia
Cardamom and clove exporters scale solar dryer procurement to replace diesel-powered dehydration amid rising EU import scrutiny of carbon intensity in spice supply chains. The national standards body implements quality management certification requirements for agricultural equipment exports. Processing clusters in North Sumatra and Sulawesi adopt biomass-electric hybrid architectures to maintain continuous operation during grid intermittency.
Italy
Organic herb cooperatives in Tuscany and Emilia-Romagna specify CE-marked equipment with phase-change material thermal batteries to eliminate synthetic refrigerant dependencies. The national environmental ministry enforces EU F-Gas Regulation compliance timelines that outpace passive dryer certification cycles. Rosemary and oregano processors in the Apennine foothills drive demand for HACCP-aligned indirect solar systems with precision temperature control.
Solar Herbs Dryer Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage, producing a bifurcated structure where ISO 9001-compliant fabricators capture export-processor premiums while regional specialists serve smallholder volume. Three archetypes dominate: engineering-intensive active dryer specialists, CE-marked premium passive line providers, and hybrid system integrators targeting biomass backup. Consolidation pressures concentrate among smaller Indian fabricators facing BIS testing delays, while European players prioritize faster CE marking cycles.
Within the engineering-intensive tier, Ecozen Solutions and Suncue Company Ltd. exemplify divergent geographic anchoring strategies. Ecozen Solutions leverages its Indian engineering base to dominate deployments across turmeric and cardamom belts, while Suncue Company Ltd. sustains technology positioning in heat exchanger configurations. Agro Solar Europe GmbH occupies a position among CE-marked premium providers serving organic herb cooperatives.
| Leading Market Players |
|---|
| Ecozen Solutions |
| Suncue Company Ltd. |
| Agro Solar Europe GmbH |
| Solar Dryers Australia |
| Solar Conduction Dryer Pvt. Ltd. |
| Sun Best |
| Ecosolaris |
| SolarTech Solutions |
| SolarFlex |
| Others |
Pricing and Supply Chain Analysis
Polycarbonate glazing substitution for tempered glass in collector assemblies simultaneously concentrates absorber plate fabrication in Indian engineering clusters and compresses accessible price points for Maharashtra smallholders. This material pivot redraws procurement geography while amplifying margin pressure on passive dryer lines targeting sub-fifty kilogram batch capacities.
Pricing Analysis
Certification level creates the primary spread across equipment tiers, with ISO 9001-compliant fabricators capturing premiums from FDA-aligned exporters while untested regional suppliers compete on first-cost for domestic turmeric processors. Three-tier pricing structure separates CE-marked European lines from BIS-certified Indian systems from uncertified local fabricators. Cost compression in polycarbonate glazing and aluminum absorber plates intensifies as commodity volatility squeezes fabricator margins. Domestic smallholders in Karnataka exhibit acute price sensitivity, whereas Vietnamese exporters prioritize documentation reliability over unit economics.
Supply Chain Analysis
Strategic stockpiling of aluminum absorber plates and UV-stabilized polycarbonate panels dominates procurement strategy among Indian fabricators facing raw material lead time variability. Manufacturing concentrates in India, China, and Germany, with thermal storage component engineering anchored in European specialist workshops. Supply chains draw from aluminum smelting corridors and petrochemical glazing production, exposing fabricators to commodity price swings. Single-source vulnerability in heat exchanger configuration expertise constrains deployment velocity. Distribution runs through direct engineering relationships for export processors and regional agricultural machinery networks for domestic smallholders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as India's PLI scheme for clean energy equipment compresses procurement timelines and FDA moisture compliance deadlines force replacement investment. Equipment replacement cycles and subsidy regime shifts drive the cyclical pattern.
For Market Incumbents: Shield certification moats by accelerating BIS laboratory partnerships ahead of smaller fabricators exiting due to testing delays. Deepen captive supply of aluminum absorber plates to buffer commodity volatility threatening passive dryer margins. Vertical integration into polycarbonate glazing distribution secures input cost stability against petrochemical price swings.
For New Entrants and Emerging Players: Aftermarket thermal storage retrofit services represent underserved white space where incumbent OEMs neglect installed base monetization. Target India's Kerala and Tamil Nadu smallholders facing monsoon reliability gaps with forced-air conversion kits for existing passive systems. Deploy direct-to-processor digital channels bypassing fragmented agricultural machinery distributors.
For Investors and Strategic Acquirers: Capital is best deployed toward CE-marked hybrid system specialists with refrigerant-free biomass integration capabilities aligned to EU F-Gas Regulation phase-down timelines. Long-term viability rests on regulatory compliance durability rather than raw efficiency metrics. Watch FDA Foreign Supplier Verification Program enforcement intensity as the inflection signal for export-processor equipment upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 9001 Certification Investment | Third-party quality auditing unlocks FDA-aligned exporter procurement previously closed to regional fabricators. |
| Biomass-Electric Hybrid Development | Refrigerant-free backup architectures capture premium positioning among Southeast Asian spice exporters facing grid intermittency. |
| Direct Engineering Relationship Buildout | Bypassing agricultural machinery distributors satisfies organic certifier audit trail requirements in Vietnam and Indonesia. |
| Thermal Storage Innovation | Phase-change material batteries eliminate synthetic refrigerant dependencies for EU F-Gas Regulation compliance. |
| Polycarbonate Glazing Backward Integration | Captive supply of UV-stabilized panels buffers commodity volatility squeezing passive dryer margins. |
Research Methodology
Cross-validation between equipment fabricator technical specifications and export-processor procurement documentation anchors the qualitative findings in this study. Primary interviews with thermal engineers at dryer manufacturers, organic certifier audit specialists, turmeric cooperative procurement managers, and FDA regulatory consultants combined with secondary validation from BIS certification records, EU F-Gas Regulation compliance filings, and Indian customs equipment import data. Bottom-up deployment counts across Maharashtra and Karnataka processing clusters triangulate against top-down market sizing from clean energy subsidy disbursement records.
Sensitivity analysis across aluminum price scenarios and monsoon seasonality assumptions shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product type (passive, active, hybrid, vacuum), technology tier (direct solar, indirect solar, thermoelectric), end-user scale (smallholder, processor, exporter), and regional regulatory cluster (BIS-mandated India, CE-marked Europe, FDA-aligned US export corridors). CAGRs derive from equipment replacement cycle analysis and subsidy regime elasticity estimates, with phytosanitary certification requirement evolution and thermal storage cost curves as key forecast inputs.
Forecasts assume regulatory continuity in India's PLI scheme and FDA Foreign Supplier Verification Program enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as EU F-Gas Regulation phase-down timelines and BIS structural safety testing capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Feed Screw Barrel Market
Agricultural Processing Equipment
Rice Milling Machines Market
Agricultural Processing Equipment
Global Nut Processing Equipment Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Seed Processing Equipment Market
Agricultural Processing Equipment
Rice Processing Machine Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Sugarcane Harvesters Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market
Agricultural Processing Equipment
Global Egg Processing Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Rotary Drum Dryers Market