
 Rice Processing Machine Market | 2026-2036
Rice Processing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Processing Machine Market Analytics
OEM-direct distribution in South Asia is reconfiguring as mill operators bypass traditional dealer networks for factory-engineered solutions. Bühler Group leverages its Swiss engineering heritage to anchor premium automatic milling lines across Indian large-mill installations. Satake Corporation competes through specialized optical sorting integration that sustains its dominance in Japanese-standard export facilities. Milltec Machinery Pvt Ltd differentiates via localized after-sales density that controls service access in South Indian cooperative networks.
Rice processing machines encompass mechanical and electro-mechanical systems designed to transform paddy into polished, graded, and packaged rice through sequential dehusking, separation, whitening, and sorting operations, with modern units achieving throughput rates exceeding 10 tonnes per hour at milling yields above 68 percent head rice recovery. These systems serve commercial millers, food processors, and export houses requiring consistent grain quality and minimal broken-rice fractions. Automatic operation type commands the widest installed base among large mills due to labor cost arbitrage and throughput reliability, while hybrid configurations are gaining traction among mid-scale enterprises seeking partial automation without full capital commitment. Direct sales channels capture the dominant transaction volume for automatic and semi-automatic units, as technical commissioning requirements and spare-part lifecycle contracts discourage arm's-length purchasing.
India's BIS mandates equipment certification for milling machinery deployed in government procurement programs, while the EU's CE marking governs export-bound machine safety and electromagnetic compatibility standards for European-bound rice processing lines. China's GB standards and NMPA-aligned food contact material rules shape component sourcing for manufacturers serving the domestic market. Stakeholders must monitor how diverging national certification regimes fragment equipment design standards and determine which compliance investments unlock priority market access.
Market Dynamics
Automated optical sorting and AI-driven quality control systems are compressing traditional milling workflows as Southeast Asian export houses face tightening EU and Japanese import standards for broken-rice tolerances.
Growth Catalysts
- India's BIS certification mandate:Government procurement programs now require certified milling equipment, forcing mid-scale mills toward standardized automated lines that guarantee head rice recovery rates above 68 percent.
- Labor cost arbitrage:Vietnamese Mekong Delta mills are replacing manual husking crews with continuous-flow automated systems to maintain export competitiveness against Thai and Cambodian suppliers.
- Photonic sorting integration:Near-infrared and RGB camera arrays now detect chalky grains and foreign matter at throughput rates exceeding 10 tonnes per hour, reducing downstream quality penalties.
Market Restraints
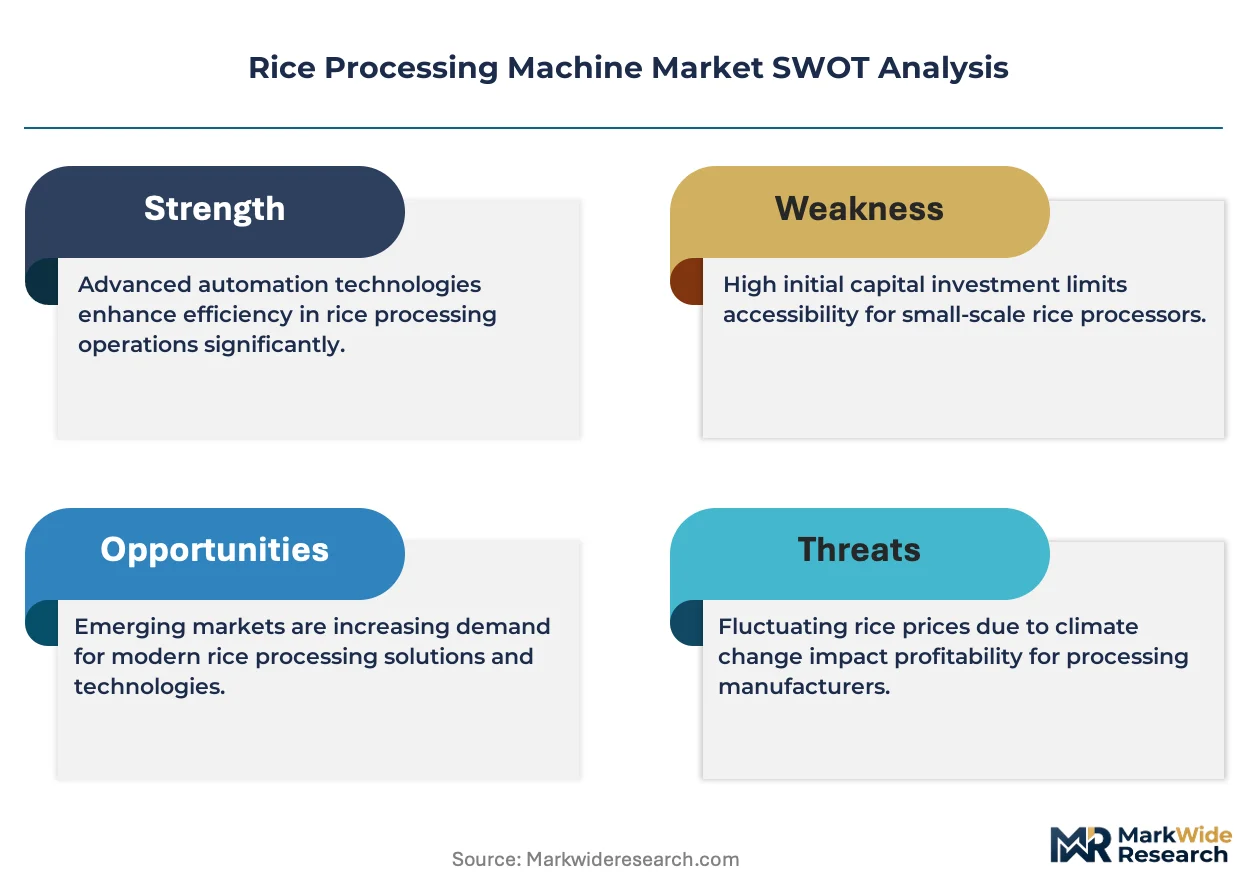
- Capital intensity barrier:Fully automated polishing and sorting lines require seven-figure USD investments that exclude cooperative mills with annual paddy throughput below 15,000 tonnes.
- Specialized component concentration:Precision optical sensors and servo-controlled pressure whiteners depend on Japanese and German component suppliers, exposing buyers to extended lead times and currency volatility.
- Steel and aluminum input costs:Milling equipment frames and rotary components face commodity price swings that erode fixed-price contract margins for domestic fabricators.
Strategic Opportunities
- Myanmar's underpenetrated mill base:Post-sanction modernization of Yangon and Mandalay processing facilities creates first-mover positioning for automated line integrators.
- EU Green Deal alignment:Carbon footprint disclosure requirements for imported rice are incentivizing European-bound exporters to install energy-efficient variable-frequency drive systems and heat-recovery dryers.
- Direct-to-mill engineering contracts:OEMs are bypassing dealer networks to offer factory-commissioned turnkey installations with lifecycle spare-part agreements, capturing margin from technical commissioning services.
Industry Challenges
- Mechatronics talent scarcity:Servo calibration, PLC programming, and optical sensor alignment require technicians with cross-disciplinary training that vocational programs in rural mill regions fail to produce.
- Legacy equipment integration:Brownfield installations must synchronize new automated whitening lines with existing dehuskers and separators, creating downtime risks and yield inconsistencies during commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Processing Machine Market |
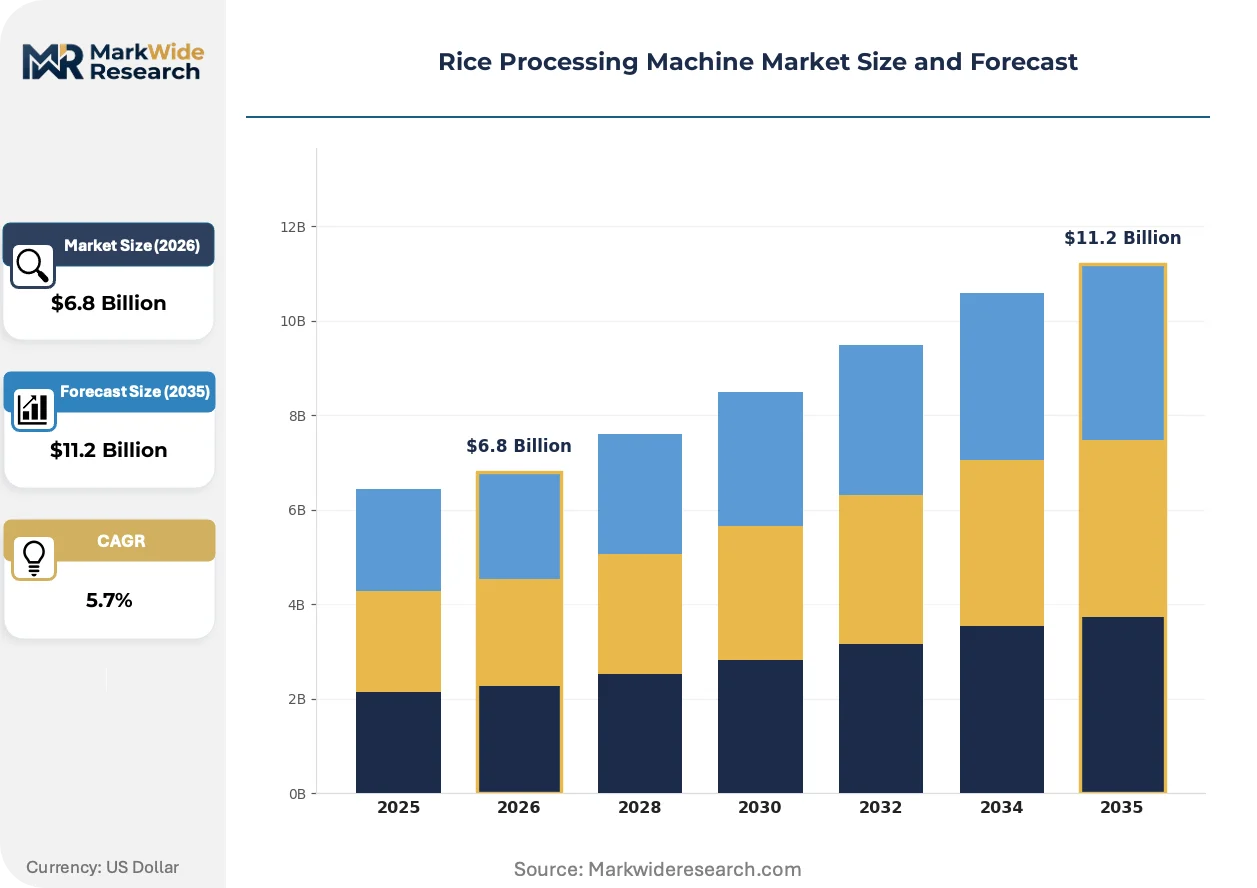
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Huskers, Paddy Separators, Rice Graders, Polishing Machines End User: Small Enterprises, Large Mills, Cooperative Societies, Exporters Operation Type: Automatic, Semi-Automatic, Manual, Hybrid Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Satake Corporation, Bühler Group, Milltec Machinery Pvt Ltd, G.G. Dandekar Machine Works Ltd, Zhejiang QiLi Machinery Co. Ltd., Hunan Chenzhou Grain & Oil Machinery, Fowler Westrup India Pvt. Ltd., Zaccaria, AG Growth International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Processing Machine Market Evolving Landscape
Digital twin simulation and predictive maintenance platforms are compressing equipment commissioning cycles while remote diagnostics reduce field service dependency for geographically dispersed mill installations.
Sensor fusion arrays combining hyperspectral imaging, laser scattering, and acoustic grain-impact analysis are virtualizing traditional manual inspection roles. Vietnamese export-oriented mills are adopting these systems at the fastest clip in Southeast Asia. This convergence is virtualizing the boundary between milling and laboratory-grade quality assurance, forcing equipment vendors to bundle analytical software with mechanical hardware.
India's BIS certification framework for rice milling machinery is tightening electromagnetic compatibility and food-contact material standards for equipment deployed in government procurement channels. Domestic manufacturers must now submit to third-party testing protocols that previously applied only to European-bound exports. Mid-scale mill operators in Tamil Nadu and Andhra Pradesh are responding by consolidating purchases toward pre-certified OEM platforms rather than custom-fabricated solutions.
Buyer preference is gravitating toward outcome-based equipment performance contracts that guarantee head rice recovery percentages and broken-rice limits rather than capital purchase arrangements. Dealer networks in South India are losing ground to OEM-direct commissioning teams that embed process engineers during installation. This pattern is most pronounced in Kerala's cooperative mill federations, where treasurer-governed boards favor fixed operational cost structures over balance-sheet asset accumulation.
Rice Processing Machine Market Segmentation
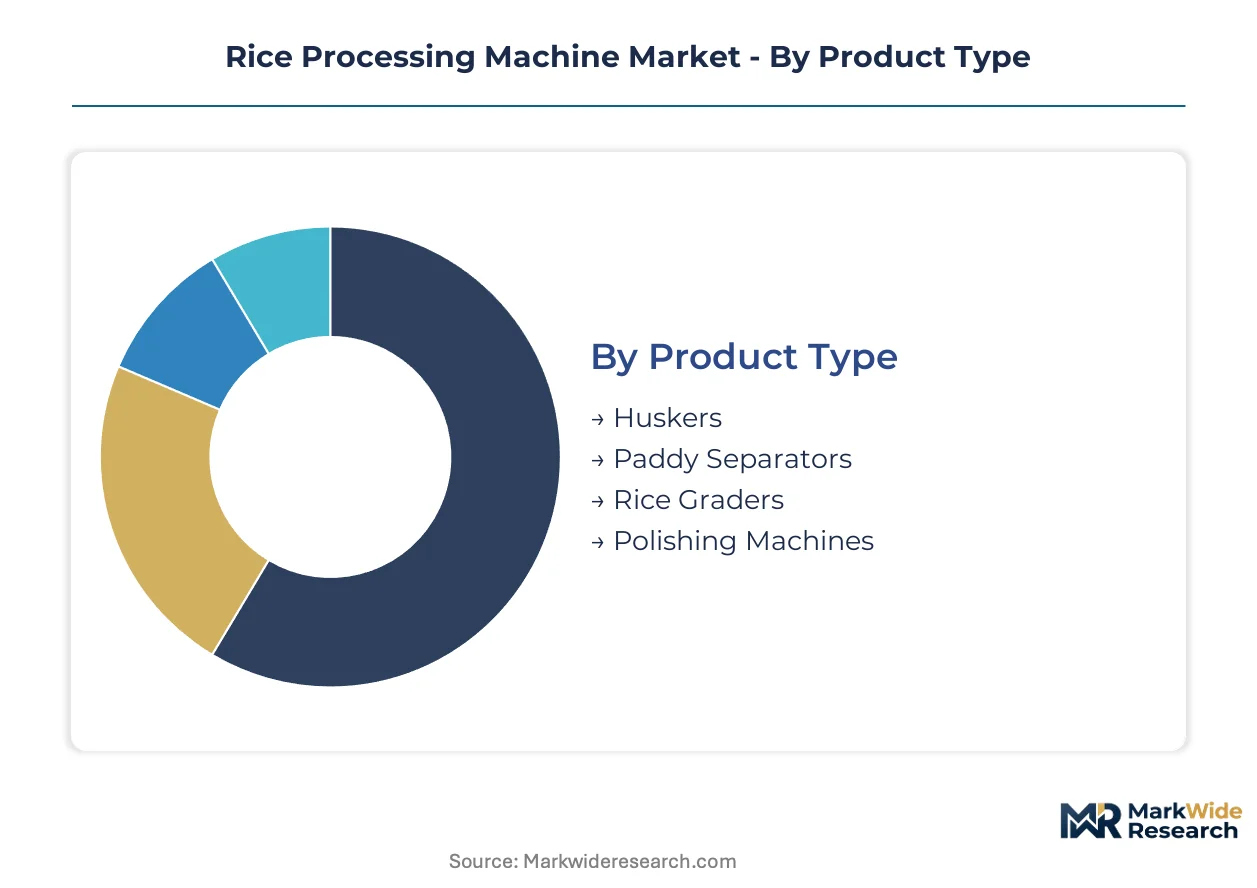
Rice processing equipment segmentation reflects divergent capital capacities, labor cost structures, and quality compliance requirements across milling operations. Equipment specification and procurement channel selection directly determine head rice recovery rates, throughput scalability, and access to export certification standards.
Product Type:
Equipment selection spans the complete paddy-to-rice transformation sequence, with each machine type addressing distinct yield optimization and quality control functions.
- Huskers:Rubber-roll and abrasive-type dehusking systems remove the outer husk layer while preserving grain integrity, with pneumatic separation circuits now standard in Mekong Delta export facilities facing EU broken-rice tolerance limits.
- Polishing Machines:Friction-based whitening and water-polishing units achieve the surface finish and translucency demanded by Japanese and Middle Eastern import standards, with multi-pass configurations dominating high-value aromatic rice processing.
- Paddy Separators:Gravity tables and tray-type separators isolate unhusked grains from brown rice streams, enabling closed-loop return to dehusking lines.
- Rice Graders:Length- and thickness-based sorting equipment classifies milled rice into head rice, large broken, small broken, and brewers' fractions for differentiated pricing.
By volume, Huskers lead installed capacity across all mill scales. By growth pace, Polishing Machines are expanding most quickly as export houses upgrade to meet premium-market appearance standards.
End User:
Customer scale determines automation level, financing structure, and technical service requirements, with procurement authority varying from individual mill owners to federated cooperative boards.
- Large Mills:Integrated processing complexes with annual paddy throughput exceeding 50,000 tonnes deploy continuous-flow automated lines with centralized process control, prioritizing BIS-certified equipment to secure government procurement contracts and export eligibility.
- Exporters:Quality-focused operations serving EU, Japanese, and Gulf markets invest in optical sorting and laboratory-grade grading infrastructure, accepting capital intensity to minimize downstream quality penalties and rejection risk.
- Small Enterprises:Family-operated mills with localized catchment areas favor semi-automatic configurations and equipment retrofitting to preserve working capital.
- Cooperative Societies:Member-governed federations in Kerala and Tamil Nadu prioritize fixed operational cost structures and OEM-direct service agreements over asset ownership models.
Large Mills command the dominant share of automatic line revenue. Exporters demonstrate the steepest equipment upgrade trajectory as phytosanitary and aesthetic standards tighten.
Operation Type:
Automation configuration reflects labor cost arbitrage, power reliability, and technician availability, with hybrid architectures emerging as a risk-mitigation strategy.
- Automatic:PLC-controlled continuous-flow systems with automated feed regulation, pressure whitening, and integrated sorting achieve throughput rates above 10 tonnes per hour with minimal operator intervention, displacing manual crews in Vietnamese Mekong Delta export facilities.
- Hybrid:Partially automated configurations retain manual paddy intake and packaging while automating core milling processes, appealing to mid-scale Indian mills seeking yield improvement without full capital commitment.
- Semi-Automatic:Operator-supervised batch systems with mechanized material handling suit cooperative mills with intermittent power supply and limited maintenance capability.
- Manual:Traditional huller and single-pass whitening equipment persists in remote rural installations with minimal capital access and localized consumption markets.
Automatic systems lead capital deployment value. Hybrid configurations are gaining share fastest among mid-scale enterprises navigating technician scarcity and power volatility.
Distribution Channel:
Channel structure is fragmenting as technical commissioning requirements and lifecycle spare-part contracts reshape buyer-supplier relationships.
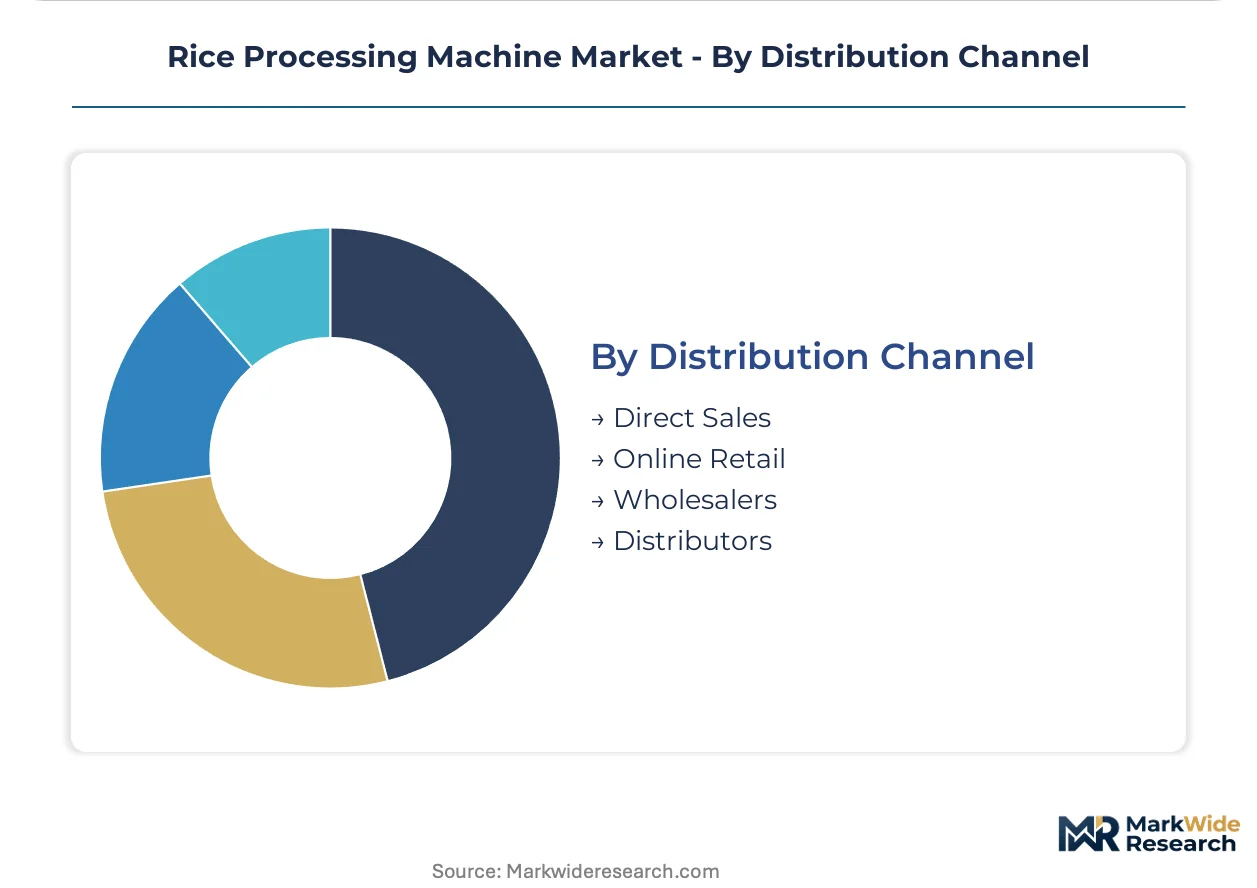
- Direct Sales:OEM-commissioned turnkey installations with embedded process engineers and multi-year spare-part agreements now dominate automatic and semi-automatic unit transactions, capturing margin from technical services that dealer networks cannot replicate.
- Distributors:Traditional dealer networks retain relevance for replacement components and standard equipment in rural cooperative segments where relationship-based credit terms outweigh technical sophistication.
- Wholesalers:Inventory-holding intermediaries serve small enterprise segments with standardized, non-customized equipment and limited after-sales obligation.
- Online Retail:Digital procurement channels facilitate spare-part sourcing and secondary equipment transactions, though capital equipment sales remain negligible due to commissioning complexity.
Direct Sales channels transact the majority of automatic line value. Online Retail is expanding most quickly for consumables and replacement component sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mekong River Delta's dense network of navigable waterways and proximity to Ho Chi Minh City's Cai Mep-Thi Vai deepwater port complex underwrites Vietnam's dominance in rice export logistics. Automated milling clusters concentrate along these transport arteries to minimize paddy spoilage and maximize containerized throughput.
Vietnam
Export-oriented mills in An Giang and Dong Thap provinces are retrofitting dehusking lines with pneumatic separation circuits to meet EU broken-rice tolerance limits. The Ministry of Agriculture and Rural Development enforces Decree 107 on rice export business conditions, mandating traceability systems that drive optical sorting adoption. Can Tho City's integrated milling complex serves as the primary consolidation point for Mekong Delta paddy flows.
India
Tamil Nadu and Andhra Pradesh cooperative federations are consolidating purchases toward BIS-certified OEM platforms to secure Food Corporation of India procurement contracts. The Bureau of Indian Standards mandates electromagnetic compatibility and food-contact material testing for equipment deployed in government channels. Kolkata's Haldia port corridor anchors eastern India's parboiled rice export infrastructure.
Thailand
Central Plains mills around Suphan Buri and Nakhon Sawan are upgrading whitening lines to sustain premium jasmine rice positioning against Vietnamese competition. The Thai Industrial Standards Institute enforces TISI certification for milling machinery used in export-grade processing. Bangkok's Laem Chabang port facilities handle the majority of aromatic rice container movements.
China
Heilongjiang and Jilin province state-owned enterprises are expanding integrated processing capacity for high-volume japonica rice distribution. The National Medical Products Administration aligns food contact material rules with GB standards that shape domestic component sourcing. Harbin's Songnen Plain processing belt represents the largest concentration of northeastern Chinese milling automation.
Myanmar
Yangon and Mandalay mill operators are modernizing legacy equipment as post-sanction trade normalization resumes. The national food safety regulator enforces emerging equipment standards for export-bound processing lines. The Ayeyarwady Delta's Pathein corridor is attracting turnkey installation contracts from regional OEM commissioning teams.
Rice Processing Machine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision optical sensors and servo-controlled pressure modules. The vendor base organizes around three strategic archetypes: Swiss and Japanese engineering houses anchoring premium automatic lines, Indian fabricators dominating mid-scale cooperative segments through localized service density, and Chinese manufacturers capturing cost-sensitive replacement equipment demand. Competitive dynamics center on direct-to-mill engineering contracts displacing dealer networks, and outcome-based performance guarantees replacing capital purchase arrangements.
Within the premium engineering tier, Bühler Group and Satake Corporation exemplify platform integrators leveraging heritage technical credentials to anchor large-mill installations. Milltec Machinery Pvt Ltd occupies a position among Indian fabricators emphasizing aftermarket service proximity in South Indian cooperative networks. Zhejiang QiLi Machinery Co. Ltd. represents Chinese manufacturers serving cost-optimized equipment replacement cycles in domestic and Southeast Asian markets.
| Leading Market Players |
|---|
| Satake Corporation |
| Bühler Group |
| Milltec Machinery Pvt Ltd |
| G.G. Dandekar Machine Works Ltd |
| Zhejiang QiLi Machinery Co. Ltd. |
| Hunan Chenzhou Grain & Oil Machinery |
| Fowler Westrup India Pvt. Ltd. |
| Zaccaria |
| AG Growth International Inc. |
| Others |
Value Network & Pricing Analysis
The Cai Mep-Thi Vai deepwater port corridor's container handling cost dynamics compress margin structures for Vietnamese export-oriented mills while amplifying price differentiation between BIS-certified premium lines and uncertified economy equipment across South Asian procurement channels.
Pricing Analysis
Volume-discount tiering structures separate large-mill turnkey contracts from cooperative society equipment purchases, with pricing stratifying across premium Swiss-engineered automatic lines, mid-tier Indian-fabricated hybrid systems, and Chinese-sourced replacement components. Certification grade and after-sales service bundling drive price differentiation, while steel and aluminum commodity volatility erodes fixed-price contract margins for domestic fabricators. Cooperative mills in Kerala and Tamil Nadu demonstrate highest price sensitivity due to treasurer-governed capital constraints, whereas Mekong Delta export houses prioritize yield guarantees over upfront equipment cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Japanese and German precision component suppliers dominating optical sensor and servo-controlled pressure module production. Steel frames and aluminum rotary components draw from Chinese and Indian metalworking centers, while rubber-roll husker consumables feed from Southeast Asian polymer processors. Single-source vulnerability in photonic sorting arrays exposes buyers to extended lead times. Distribution runs through OEM-direct commissioning teams embedding process engineers during installation, displacing traditional dealer networks for automatic line transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Kerala and Tamil Nadu cooperative federations consolidate purchases toward pre-certified OEM platforms, shifting procurement leverage from fragmented individual mill owners toward federated boards with standardized technical specifications.
For Market Incumbents: Insulate premium positioning by deepening captive supply of precision optical components from Japanese sensor manufacturers, countering emerging Chinese cost-optimized entrants. Anchor BIS certification investment to secure Food Corporation of India procurement channel access against mid-scale fabricators lacking third-party testing capabilities. For New Entrants and Emerging Players: Establish a beachhead in Myanmar's Yangon and Mandalay modernization wave, where post-sanction equipment replacement cycles lack established service infrastructure. Target cooperative society segments with fixed operational cost contracting models that transfer yield risk from treasurer-governed boards to equipment vendors, replicating Kerala's outcome-based performance guarantee structure. For Investors and Strategic Acquirers: India's BIS certification mandate reshapes the acquisition landscape by elevating compliance-capable fabricators above custom-equipment competitors. Five-to-ten-year viability favors platform integrators with embedded process engineering capabilities over pure manufacturing plays. Monitor Food Corporation of India procurement contract award patterns as inflection signal for certified equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Mill Engineering Contracts | OEM commissioning teams capture margin from technical services that dealer networks cannot replicate across Mekong Delta installations. |
| BIS Certification Investment | Third-party testing protocols unlock Food Corporation of India procurement channels previously restricted to European-bound exports. |
| Optical Sorting Integration | Near-infrared and RGB camera arrays reduce downstream quality penalties for Vietnamese export houses facing EU broken-rice tolerance limits. |
| Outcome-Based Performance Contracting | Fixed operational cost structures transfer yield risk from Kerala cooperative boards to equipment vendors, displacing capital purchase arrangements. |
| Myanmar Market Entry | Post-sanction modernization of Yangon and Mandalay facilities creates first-mover positioning for automated line integrators with localized service capability. |
Research Methodology
Initial hypotheses were tested against primary input from commercial mill operators, OEM technical commissioning engineers, cooperative federation procurement officers, and aftermarket service heads, and refined through secondary validation against BIS certification filings, Bureau of Indian Standards electromagnetic compatibility protocols, Vietnam Ministry of Agriculture and Rural Development Decree 107 traceability requirements, and customs data on milling equipment import flows. Bottom-up equipment installation tracking and top-down export volume analysis were triangulated to anchor market sizing.
Demand-supply-balance framing modeled paddy throughput expansion against installed capacity utilization across large-mill, exporter, and cooperative society segments throughout the forecast period. Operation type, distribution channel, and regional regulatory cluster dimensions shaped segmentation analytics. CAGRs were derived from equipment replacement cycle analysis and export certification adoption curves, with head rice recovery rate thresholds and broken-rice tolerance standards informing yield-driven demand projections.
Stress conditions across steel and aluminum commodity price volatility, Japanese-German component lead time extension, and BIS certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on cooperative federation consolidation pace and Myanmar trade normalization trajectory. Quarterly review of Food Corporation of India procurement contract awards and EU Green Deal carbon footprint disclosure implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Manure Handling Equipment Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Global Egg Processing Market
Agricultural Processing Equipment
Tobacco Drying Machines Market