
 Global Threshers Market | 2026-2036
Global Threshers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Threshers Market Outlook
Leasing and pay-per-use harvest service models is narrowing the capital barrier for smallholder farmers across South Asia and sub-Saharan Africa. John Deere leverages its captive finance arm to anchor machine-as-a-service contracts in emerging markets. CLAAS Group competes through specialized high-throughput systems for European cooperatives. Mahindra & Mahindra dominates tractor-integrated threshing platforms across India's fragmented landholding structure.
A thresher separates grain from straw and chaff through mechanical beating, rubbing, or centrifugal action, typically processing 500-2,000 kg of crop per hour depending on drum speed and concave clearance. The equipment reduces post-harvest losses from 15-20% under manual methods to under 2% in mechanized systems. Tractor-mounted units lead volume due to compatibility with existing two-wheel and four-wheel tractor fleets across smallholder economies. Self-propelled combines command premium positioning in large-scale North American and Australian operations where labor costs justify capital intensity. Walk-behind configurations sustain fastest growth in African markets where miniaturization meets emerging cooperative demand.
India's BIS certification mandates safety guards and noise thresholds for power-operated threshers sold through subsidized channels. The EU Machinery Directive and CE marking requirements shape export feasibility for Asian manufacturers targeting European cooperatives. EPA tiered emission standards in the United States constrain engine specifications for self-propelled units. Stakeholders must monitor how carbon-accounting frameworks and biofuel-linked grain purity standards redefine threshing performance benchmarks.
Market Dynamics
Precision threshing technology and India's PLI scheme for farm machinery are compressing replacement cycles across South Asian smallholder cooperatives, fundamentally restructuring capital deployment patterns in mechanized post-harvest processing.
Growth Catalysts
- India's PLI scheme for farm machinery:Production-linked incentives accelerate domestic manufacturing scale and subsidized channel penetration across Bihar, Punjab, and Haryana grain belts.
- Mechanization cooperatives:Smallholder aggregation models in Bangladesh and Nepal expand addressable demand for tractor-integrated threshing platforms previously inaccessible to fragmented landholdings.
- Precision threshing drum designs:Variable-speed concave systems reduce grain damage rates below 2%, justifying premium positioning among quality-sensitive export-oriented operations.
Market Restraints
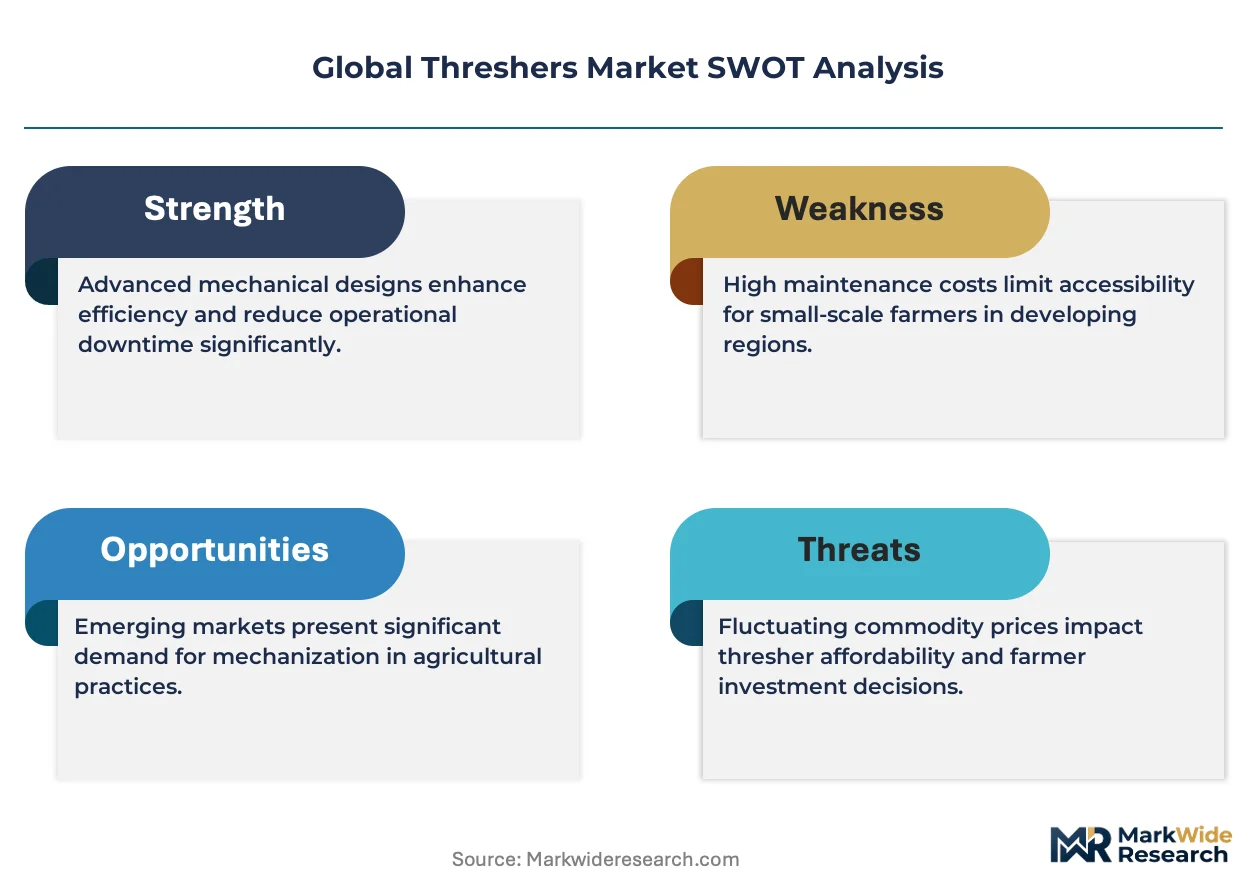
- Steel and engine component volatility:Input cost swings in cast iron drums and diesel power units compress OEM margins during subsidy-dependent procurement cycles.
- Spare parts supply concentration:Critical gearbox and bearing sourcing clusters in China's Shandong province expose aftermarket service networks to geopolitical friction.
- Manual threshing persistence:Labor-surplus rural economies in sub-Saharan Africa sustain non-mechanized alternatives despite demonstrable post-harvest loss differentials.
Strategic Opportunities
- Kenya and Tanzania cooperative formation:Emerging farmer aggregation structures create first-mover positioning for pay-per-use harvest service deployment.
- EU Green Deal carbon-accounting frameworks:Biofuel-linked grain purity standards reward threshing systems with traceable low-damage processing credentials.
- Telematics-converged maintenance:IoT-enabled drum wear monitoring and predictive service scheduling unlock subscription revenue streams alongside equipment sales.
Industry Challenges
- Skilled technician scarcity:Mechatronics competency gaps in rural service networks delay precision system repairs and erode uptime guarantees.
- BIS certification timeline compression:Safety guard and noise threshold compliance documentation bottlenecks slow subsidized channel product launches.
- Legacy fleet integration friction:Two-wheel tractor compatibility requirements constrain self-propelled platform design flexibility for Asian manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Threshers Market |
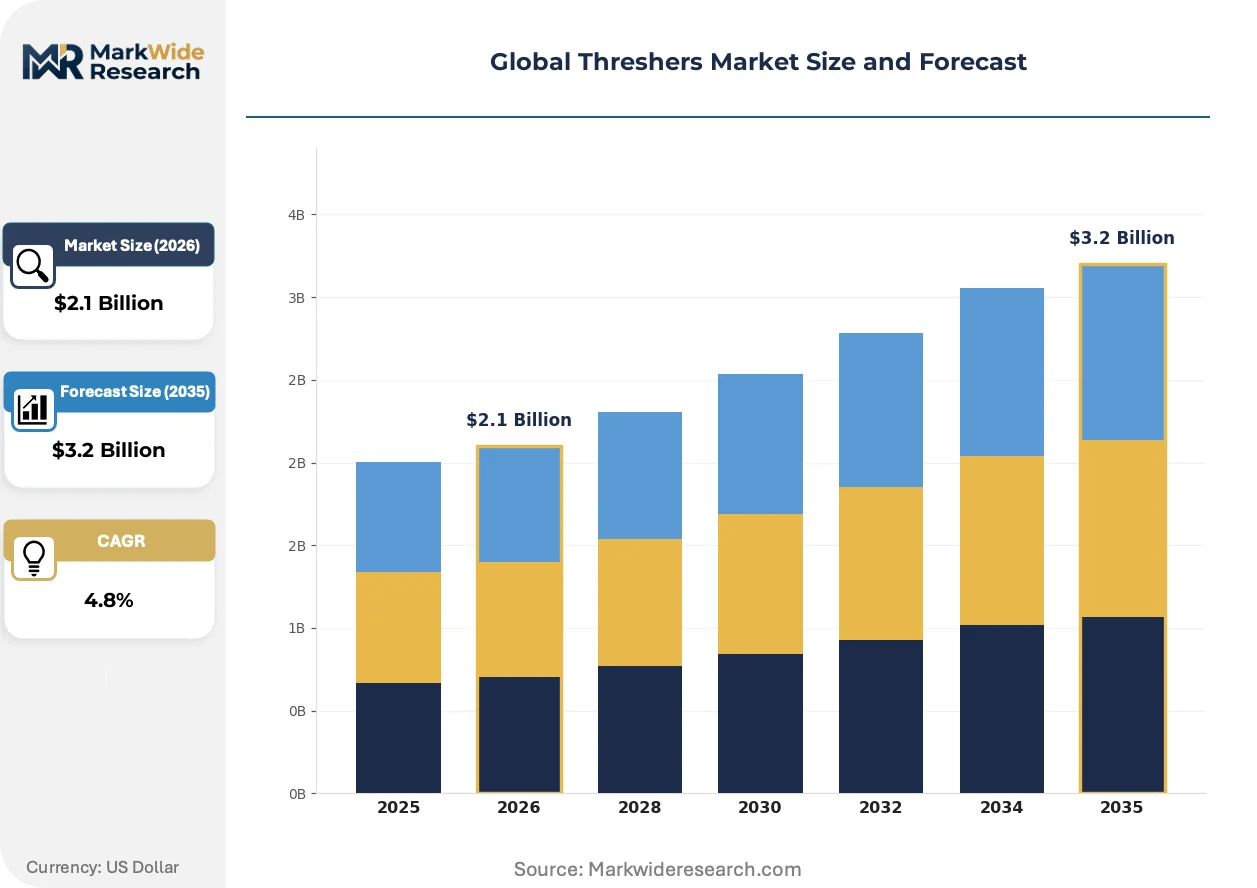
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Propelled, Tractor-Mounted, Walk-Behind, Hand-Held Application: Cereals, Pulses, Oilseeds, Others End User: Farmers, Cooperatives, Agribusinesses, Research Institutions Distribution Channel: Retail, Online, Wholesalers, Direct Sales |
| Companies Covered | Mahindra & Mahindra, Kubota, John Deere, AGCO, CNH Industrial, CLAAS Group, Iseki & Co, Deluxe Agro Industries, ALMACO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Threshers Market Strategic Shifts
Active sensor integration and regulatory carbon-accounting are redefining performance benchmarks beyond throughput metrics, embedding traceability and damage minimization as core purchasing criteria.
Axial-flow threshing technology replaces conventional tangential drum designs through gentler crop handling and reduced straw fragmentation. Large-scale Australian wheat operations and Brazilian soybean cooperatives in Mato Grosso are standardizing these configurations for export-grade purity requirements. The technology is rendering obsolete fixed-concave systems that cannot adapt clearance settings to moisture-variable harvest conditions.
EPA tiered emission standards for off-road diesel engines constrain self-propelled combine specifications in the United States, forcing engine downsizing or after-treatment adoption. Manufacturers respond with power-dense alternatives and electrified auxiliary systems to preserve throughput while meeting NOx thresholds. Premium North American operations absorb compliance costs; price-sensitive segments delay fleet renewal.
Cooperative procurement committees now bundle threshing services with storage and logistics through single-contract harvest management platforms. Equipment financiers and regional agricultural banks in India displace traditional dealer credit arrangements. Maharashtra and Gujarat farmer producer organizations demonstrate this consolidation most visibly, compressing vendor negotiation cycles and unbundling after-sales service pricing.
Global Threshers Market Segmentation
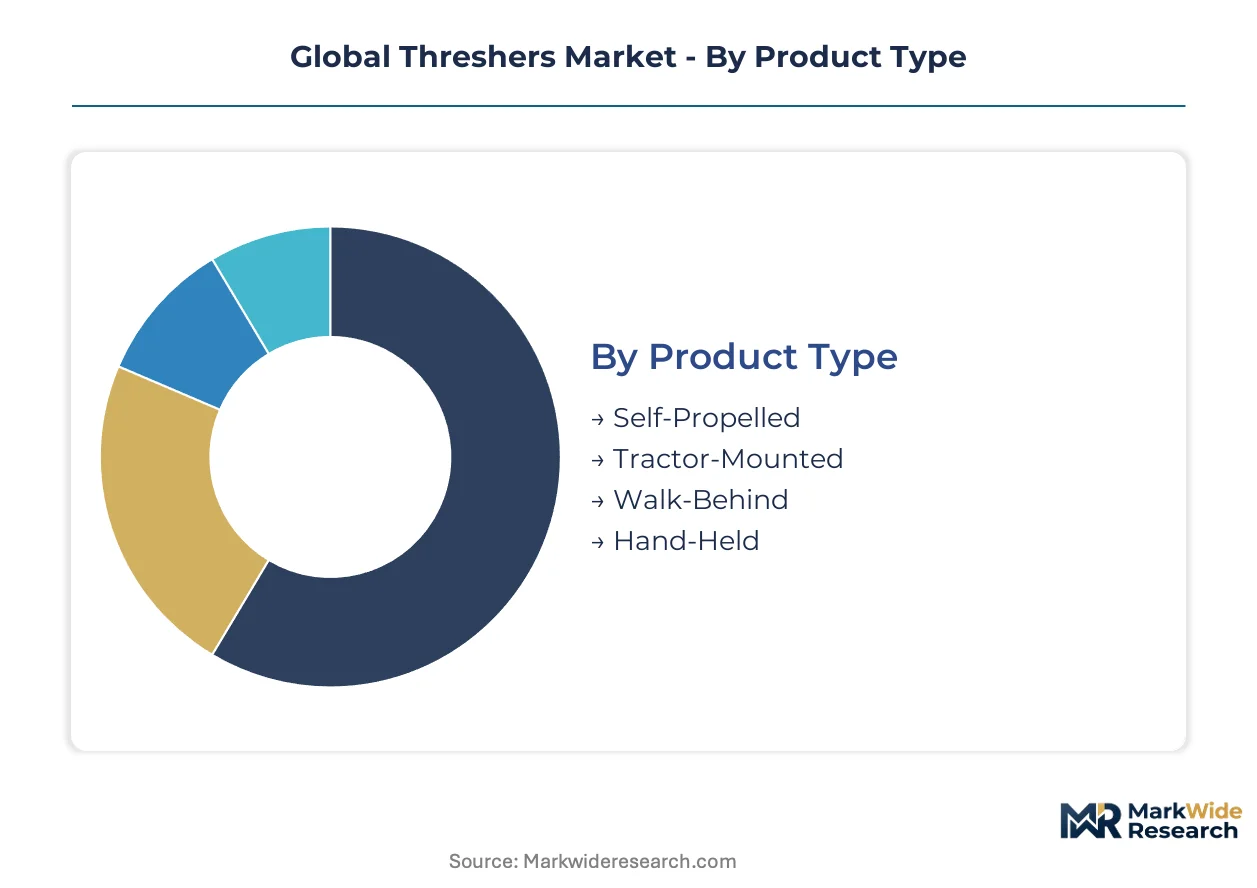
Thresher segmentation reveals divergent equipment lifecycles across product architectures, with capital-intensive platforms cycling slower than portable units. Procurement patterns vary sharply by crop type and end-user aggregation level, reshaping vendor go-to-market priorities.
Product Type:
Replacement cycles stretch from 3-5 years for hand-held units to 12-15 years for self-propelled systems, creating distinct aftermarket revenue profiles.
- Self-Propelled:Integrated engine-harvester platforms process 8-15 tonnes per hour through axial-flow threshing drums. Large-scale Australian wheat operations and Brazilian soybean cooperatives in Mato Grosso absorb premium pricing for autonomous guidance compatibility.
- Tractor-Mounted:Power-take-off driven units attach to existing two-wheel and four-wheel tractor fleets across South Asian smallholder economies. India's Bihar and Punjab grain belts concentrate demand through subsidized procurement channels under the PLI scheme.
- Walk-Behind:Miniaturized diesel or electric configurations serve emerging cooperatives in Kenya and Tanzania where capital constraints preclude tractor ownership.
- Hand-Held:Manual or battery-powered units address subsistence plots below two hectares; lowest replacement thresholds sustain spare parts dependency.
Tractor-Mounted anchors the volume base while Walk-Behind gains share at the steepest rate.
Application:
Grain fragility and moisture tolerance requirements stratify equipment specifications across crop categories.
- Cereals:Wheat, rice, and maize processing dominates throughput metrics; axial-flow designs minimize cracked kernels for EU export-grade purity standards.
- Pulses:Lentil and chickpea threshing demands gentler concave clearance settings to preserve seed coat integrity for food-grade certification.
- Oilseeds:Soybean and rapeseed processing in Brazil's Mato Grosso region requires specialized rasp-bar configurations to handle high-oil-content biomass.
- Others:Specialty crops including sorghum and millet occupy niche retrofit markets with limited OEM standardization.
Cereals commands installed base dominance while Oilseeds climbs fastest on biofuel-linked grain purity incentives.
End User:
Procurement scale and financing sophistication fragment sharply across user archetypes.
- Farmers:Individual smallholders below five hectares rely on dealer credit and government subsidy windows; replacement decisions hinge on harvest timing.
- Cooperatives:Aggregated farmer producer organizations in Maharashtra and Gujarat bundle threshing with storage logistics, compressing vendor negotiation leverage.
- Agribusinesses:Integrated grain traders and processors specify telematics-enabled uptime guarantees for supply chain traceability.
- Research Institutions:Agricultural universities and breeding stations drive limited volume for experimental variety development.
Farmers retain volume concentration while Cooperatives expand most quickly through service-model consolidation.
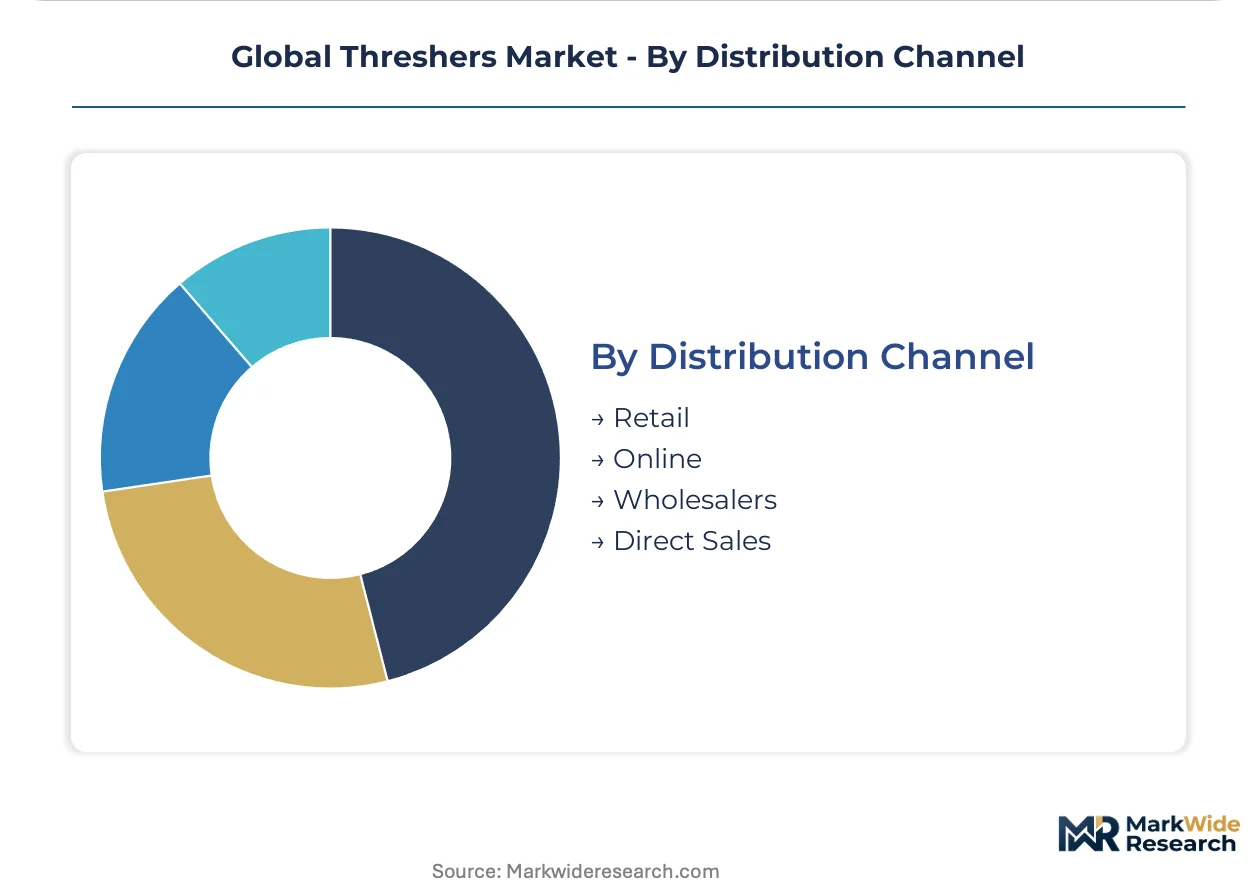
Distribution Channel:
Channel economics reflect subsidy documentation burdens and spare parts proximity requirements.
- Retail:Authorized dealer networks handle BIS certification documentation and installation for subsidized sales in India's grain belt states.
- Online:E-commerce penetration remains constrained by after-sales service dependency; spare parts ordering gains traction for standardized components.
- Wholesalers:Regional distributors aggregate demand across fragmented geographies in sub-Saharan Africa where direct OEM presence is thin.
- Direct Sales:Large agribusinesses and cooperatives negotiate enterprise contracts with captive financing arrangements.
Retail secures volume leadership while Direct Sales scales fastest among cooperative procurement committees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium axial-flow systems in Australia command pricing multiples against basic tractor-mounted units in Bangladesh, creating a structural arbitrage that OEMs exploit through tiered product architectures. This asymmetry shapes capital deployment patterns across mechanization gradients. Regional performance diverges sharply between subsidy-dependent procurement channels and export-grade purity markets.
India
Bihar, Punjab, and Haryana grain belts concentrate demand through subsidized tractor-integrated platforms under the PLI scheme for farm machinery. BIS certification mandates safety guards and noise thresholds that slow product launches but anchor quality baselines. Maharashtra and Gujarat farmer producer organizations bundle threshing with storage logistics, compressing vendor negotiation leverage.
Brazil
Mato Grosso soybean cooperatives standardize axial-flow configurations for export-grade purity requirements, absorbing premium pricing for autonomous guidance compatibility. ANVISA and environmental licensing shape equipment specifications for large-scale operations. Regional agricultural banks displace dealer credit through single-contract harvest management platforms.
United States
Large-scale wheat operations in the Great Plains drive self-propelled combine specifications with telematics-enabled uptime guarantees. EPA tiered emission standards constrain engine configurations, forcing power-dense alternatives or after-treatment adoption. Premium operations absorb compliance costs; price-sensitive segments delay fleet renewal cycles.
Germany
EU Machinery Directive and CE marking requirements shape export feasibility for manufacturers targeting European cooperatives. EU Green Deal carbon-accounting frameworks reward threshing systems with traceable low-damage processing credentials. Specialized high-throughput systems serve precision-oriented farmer associations in Bavaria and Lower Saxony.
Kenya
Emerging farmer aggregation structures in Kenya and Tanzania create first-mover positioning for pay-per-use harvest service deployment. Walk-behind miniaturized configurations sustain fastest growth where capital constraints preclude tractor ownership. Regional distributors aggregate demand across fragmented geographies where direct OEM presence remains thin.
Global Threshers Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying drums, concaves, and power transmission assemblies to branded assemblers. The vendor base organizes around three archetypes: diversified agricultural equipment conglomerates with captive finance arms, regional machinery specialists with deep distribution in single geographies, and component fabricators serving the aftermarket. Consolidation pressure concentrates among mid-scale specialists lacking telematics integration capabilities. Strategic moves center on M&A for precision threshing IP and captive financing arrangements to anchor machine-as-a-service contracts.
Within the diversified equipment tier, John Deere leverages its captive finance infrastructure to anchor service contracts in emerging markets, while Mahindra & Mahindra dominates tractor-integrated platforms across India's fragmented landholding structure. CLAAS Group occupies a position among European specialists targeting cooperative procurement committees with high-throughput axial-flow systems. These three anchors exemplify divergent geographic and product-architecture strategies without direct segment overlap.
| Leading Market Players |
|---|
| Mahindra & Mahindra |
| Kubota |
| John Deere |
| AGCO |
| CNH Industrial |
| CLAAS Group |
| Iseki & Co |
| Deluxe Agro Industries |
| ALMACO |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Mumbai maritime corridor's freight volatility feeds directly into landed cost spreads for Indian OEMs sourcing precision-machined drums from China's Shandong province, compressing margins on economy-tier tractor-mounted units while amplifying price premiums for configured-to-order axial-flow systems.
Pricing Analysis
Configured-to-order spreads against standard catalogue pricing widen substantially across the Global Threshers Market, with axial-flow autonomous-guidance configurations commanding substantial premiums over fixed-concave tractor-mounted alternatives. Price differentiation rests on certification grade—BIS-compliant safety-guard systems for India's subsidized channels versus CE-marked precision units for EU cooperatives—and after-sales service bundling through captive finance arms. Pricing pressure stems from steel and cast iron input volatility, particularly for OEMs serving subsidy-dependent procurement cycles in South Asia. Individual smallholders below five hectares exhibit acute price sensitivity, while Brazilian soybean cooperatives in Mato Grosso absorb premium positioning for export-grade purity compliance.
Supply Chain Analysis
Contract manufacturing capacity for precision threshing drums and variable-speed concave systems concentrates in China's Shandong province, with secondary clusters in India's Punjab and Haryana industrial belts. Raw material dependencies center on high-grade cast iron for drum fabrication, specialty steel alloys for rasp-bar configurations, and EPA-compliant diesel power units for self-propelled platforms. Supply chain risk manifests through single-source vulnerability in precision gearbox and bearing sourcing from Shandong, exposing aftermarket service networks to geopolitical friction. Distribution runs through authorized dealer networks handling BIS documentation in India's grain belt states, supplemented by regional wholesalers aggregating fragmented demand across sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Threshers Market is navigating a cyclical recovery anchored to India's PLI scheme for farm machinery, which is compressing replacement cycles and restructuring capital deployment patterns across South Asian smallholder cooperatives.
For Market Incumbents: Insulate service revenue streams from margin erosion in equipment sales by deepening captive finance penetration and predictive maintenance subscriptions. John Deere's machine-as-a-service contracts in emerging markets exemplify this defensive posture. Threats from telematics-native entrants necessitate accelerated IoT integration in drum wear monitoring systems. Vertical integration into precision concave manufacturing in India's PLI-subsidized zones offers cost control leverage.
For New Entrants and Emerging Players: Establish a beachhead in Kenya and Tanzania's emerging cooperative structures through pay-per-use harvest service deployment, where capital constraints preclude tractor ownership and incumbent presence remains thin. Walk-behind miniaturized configurations represent the most penetrable product tier. A go-to-market angle bundling threshing with storage logistics through regional agricultural bank partnerships bypasses traditional dealer credit barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized agricultural equipment divisions lacking telematics integration capabilities. Long-term viability hinges on subscription revenue attachment rates and precision threshing IP ownership. The signal to watch is cooperative procurement committee consolidation in Maharashtra and Gujarat, where vendor negotiation compression indicates market maturation and acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Threshing IP Acquisition | Variable-speed concave technology secures premium positioning in EU export-grade purity markets. |
| Captive Finance Infrastructure Expansion | Machine-as-a-service contracts anchor recurring revenue in India's subsidy-dependent procurement channels. |
| Telematics Platform Integration | IoT-enabled drum wear monitoring unlocks predictive maintenance subscriptions alongside equipment sales. |
| Regional Manufacturing Footprint | PLI-subsidized production in India's grain belt states reduces landed cost exposure to freight volatility. |
| Cooperative Service Bundling | Single-contract harvest management platforms compress vendor negotiation cycles in Maharashtra and Gujarat. |
Study Parameters
A spread of perspectives from agricultural equipment procurement managers at Indian farmer producer organizations, maintenance directors at Brazilian soybean cooperatives, aftermarket service heads at regional distributors in sub-Saharan Africa, and plant engineers at Chinese precision-machining facilities converged on the working assumptions. These primary insights combined with secondary validation from BIS certification databases, ANVISA environmental licensing records, EU Machinery Directive compliance filings, and customs trade data for cast iron and specialty steel inputs. Bottom-up unit economics across product tiers triangulated against top-down macroeconomic indicators for agricultural mechanization rates.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeling across product architecture, crop application, end-user aggregation level, and distribution channel. CAGRs derived from replacement cycle analysis—3-5 years for hand-held units stretching to 12-15 years for self-propelled systems—and penetration rate assumptions for emerging cooperative structures in Kenya and Tanzania. Industry-specific forecast inputs incorporated India's PLI scheme disbursement trajectories and EPA tiered emission standard compliance cost absorption patterns in North American premium operations.
Sensitivities concentrate around India's BIS certification timeline compression, geopolitical friction in Shandong gearbox sourcing, and carbon-accounting framework adoption timelines under the EU Green Deal. Forecasts reflect documented assumptions on subsidy continuity and cooperative formation rates. Cross-checking against agricultural machinery trade association shipment data and regional agricultural bank lending disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Maize Milling Machine Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Color Sorter Market
Agricultural Processing Equipment
Global Egg Processing Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Sugarcane Harvesters Market
Agricultural Processing Equipment
Global Square Straw Baler Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Meat Processing Equipment Market