
 Non-GMO Yogurt Market | 2026-2036
Non-GMO Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Non-GMO Yogurt Market Analytics
France is narrowing its non-GMO dairy processing capacity gap through expanded Brittany-based fermentation facilities. Chobani leverages its integrated milk supply network to secure Non-GMO Project verification across mainstream retail channels. Stonyfield Farm anchors its competitive stance through deep organic supplier relationships and cooperative dairy partnerships. Danone differentiates via specialized strain development for reduced-sugar formulations that retain live culture counts.
Non-GMO yogurt denotes fermented milk products derived from livestock feed and ingredients certified free of genetically modified organisms, typically maintaining live and active cultures above 10^6 CFU per gram at manufacture. The production relies on controlled supply chain segregation, from verified non-GMO feed through dedicated processing lines, to prevent cross-contamination with conventional dairy streams. Greek yogurt occupies the premium tier within product type segmentation, commanding higher margins through straining processes that concentrate protein content. Drinking yogurt represents the fastest-expanding format, particularly in convenience-oriented channels where portability drives repeat purchase behavior. Plain flavor SKUs sustain the largest volume base, though fruit-infused variants capture incremental growth in children's and snacking occasions.
The Non-GMO Project standard and USDA National Organic Program collectively shape ingredient sourcing mandates and third-party audit frequencies across North American supply chains. FDA food labeling requirements for bioengineered disclosures under the National Bioengineered Food Disclosure Standard add compliance complexity for imported yogurt bases and additive formulations. Stakeholders must monitor evolving state-level GMO labeling precedents and retailer-specific certification demands that could fragment market access requirements beyond federal baselines.
Market Dynamics
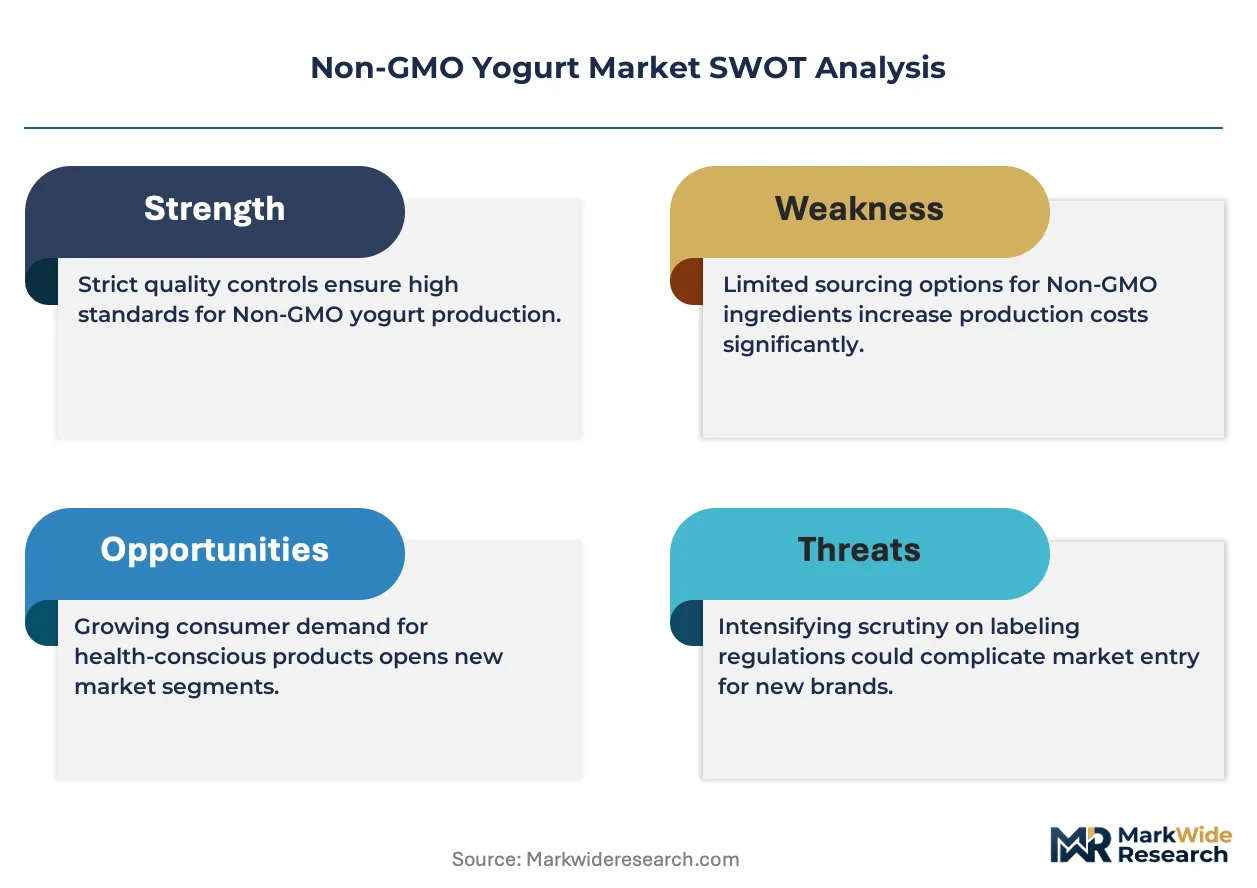
Supply chain segregation costs are compressing margin structures for mid-tier processors unable to achieve scale in Non-GMO Project verification, while integrated dairy cooperatives capture disproportionate shelf space through backward control of feed sourcing.
Growth Catalysts
- USDA Organic Program alignment:Dual certification pathways reduce audit redundancy for processors serving natural grocery channels, accelerating supplier onboarding timelines.
- Corporate wellness cafeteria procurement:Hospital and technology campus foodservice directors are mandating clean-label dairy SKUs in refreshment contracts.
- Pacific Northwest consumer clustering:Regional co-op density in Oregon and Washington sustains price premiums that subsidize national certification investments.
Market Restraints
- Non-GMO feed cost volatility:Corn and soybean price spreads against conventional grain narrow processor margins during harvest disruptions.
- Processing line segregation requirements:Dedicated fermentation and filling equipment demands capital commitments that freeze out contract manufacturers.
- FDA bioengineered disclosure friction:Imported yogurt base formulations trigger compliance reviews that extend clearance timelines at port.
Strategic Opportunities
- Drinking yogurt format expansion:Convenience-store channel penetration offers volume growth outside refrigerated perimeter competition.
- Reduced-sugar strain development:Specialized culture combinations enable clean-label sweetness without added sugars.
- IRA agricultural conservation incentives:Feed crop transition subsidies lower non-GMO sourcing costs for qualifying dairy operations.
Industry Challenges
- Live culture stability expertise:Maintaining 10^6 CFU per gram through shelf life requires fermentation scientists in short supply.
- Cross-contamination prevention protocols:Segregated logistics networks demand coordination with third-party cold chain providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-GMO Yogurt Market |
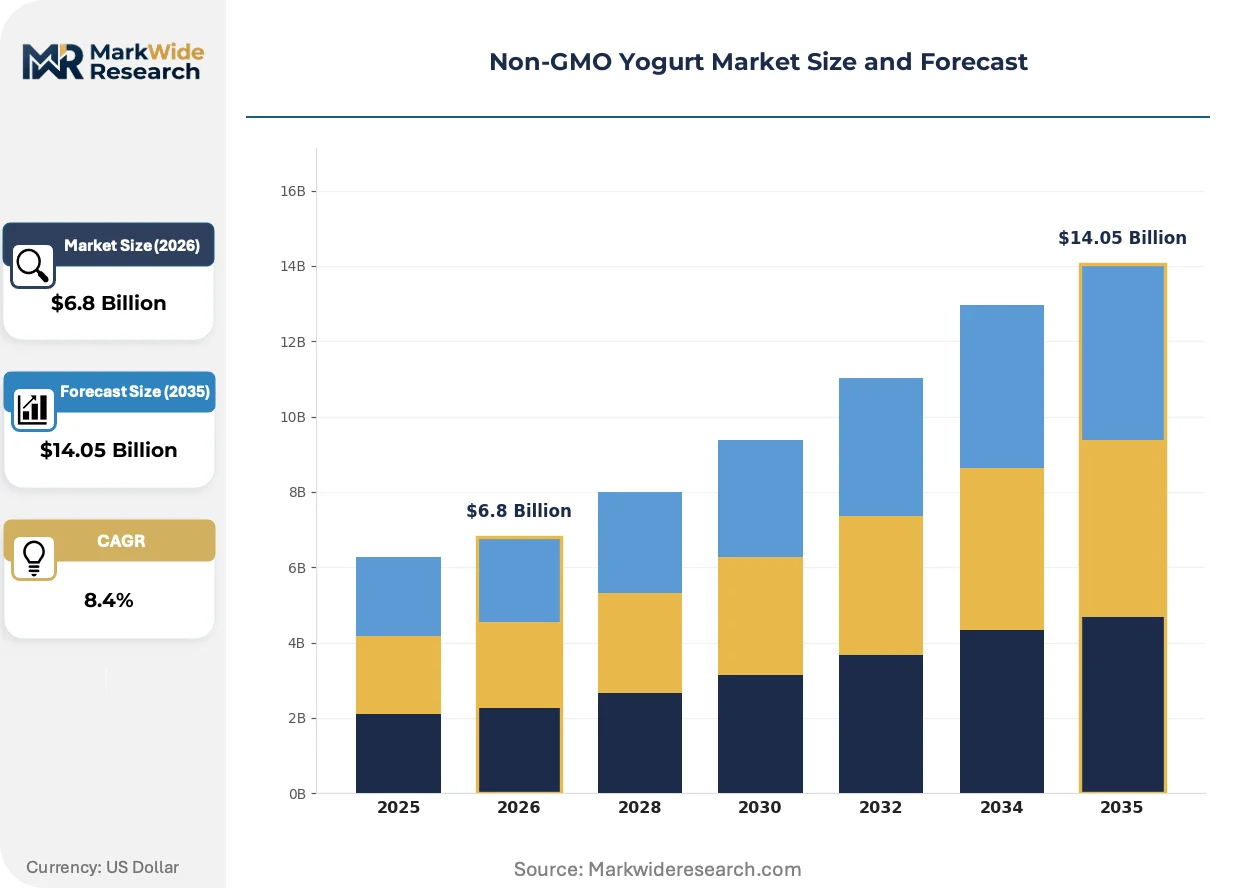
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Set Yogurt, Drinking Yogurt, Greek Yogurt, Lactose-Free Yogurt Flavor: Plain, Strawberry, Blueberry, Vanilla Packaging Type: Plastic Cups, Glass Jars, Tetra Pak, Pouches Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores |
| Companies Covered | Chobani, Stonyfield Farm, Danone, FAGE International, Nestlé, Mengniu Dairy, Siggi's, Wallaby Organic, Nancy's Yogurt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-GMO Yogurt Market Evolving Landscape
Digital traceability infrastructure is rewiring how verification data flows between farm and retail, replacing paper-based audit trails with immutable records that compress dispute resolution timelines.
Blockchain-enabled supply chain documentation is virtualizing the verification workflow for Non-GMO Project compliance. Mid-sized dairy processors are adopting these platforms fastest to reduce third-party audit costs. The technology is virtualizing the documentation burden that previously required dedicated compliance staff.
EU Green Deal farm-to-fork targets are tightening residue monitoring for imported dairy cultures. EFSA guidance on novel fermentation inputs is forcing reformulation reviews for reduced-sugar variants. European processors are responding by accelerating in-house strain development programs.
Direct-to-subscription models are capturing repeat purchase volume previously held by conventional grocery. Natural grocery chains are responding with private-label non-GMO lines that match subscription pricing. The Pacific Northwest remains the geography where this channel shift is most advanced.
Non-GMO Yogurt Market Segmentation
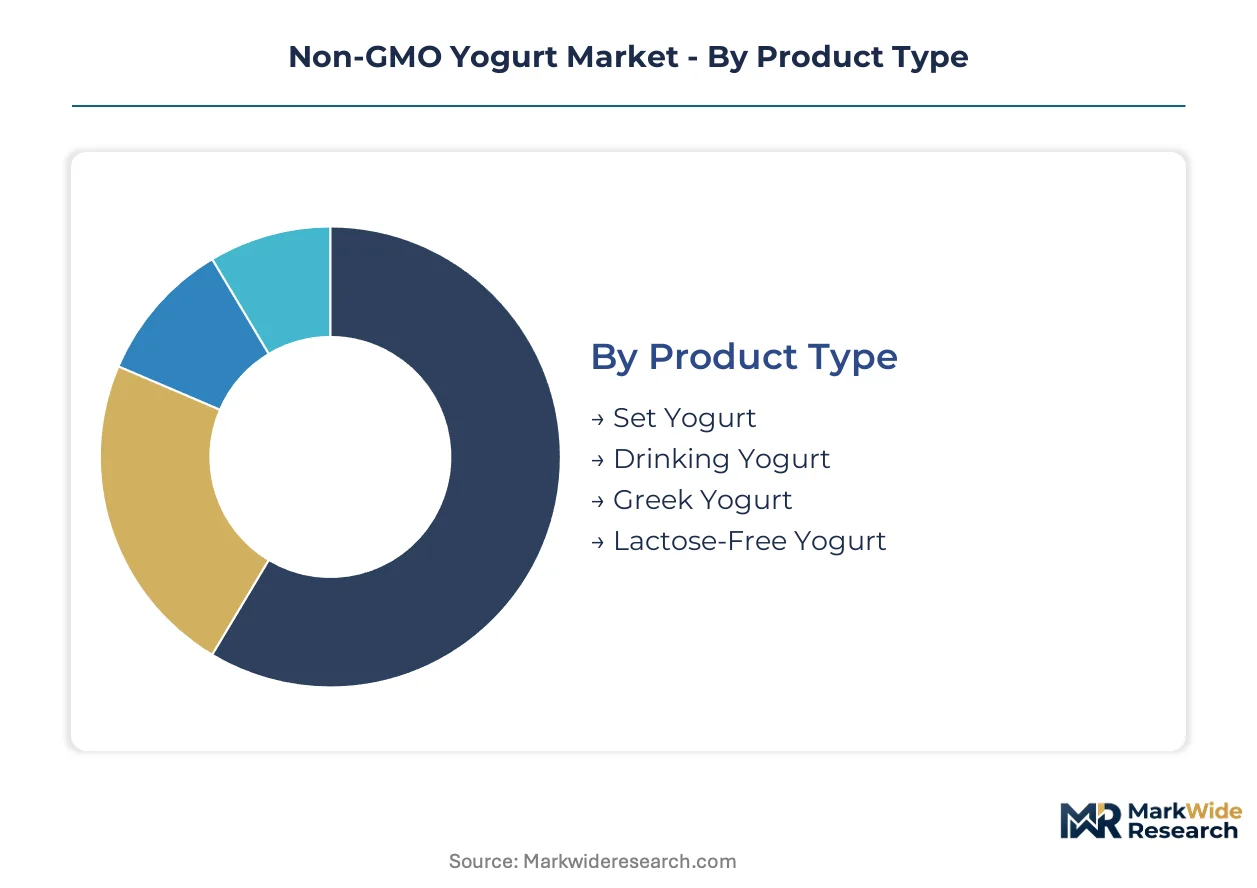
Non-GMO yogurt segmentation reflects divergent consumer priorities across convenience, health positioning, and certification credibility. Each dimension carries distinct supply chain implications for segregation protocols and channel access requirements.
Product Type:
Use-case spectrum spans spoonable breakfast occasions to portable nutrition formats, with protein concentration and digestive tolerance driving technical differentiation.
- Greek Yogurt:Strained fermentation removes whey to concentrate protein above 10g per serving, commanding shelf space in premium perimeter dairy cases. Pacific Northwest co-ops sustain price premiums that subsidize Non-GMO Project verification costs for this tier.
- Drinking Yogurt:Fluid viscosity enables on-the-go consumption through single-serve bottles, expanding fastest in convenience-store channels where portability drives repeat purchase velocity.
- Set Yogurt:Firm gel structure from direct vat inoculation serves traditional breakfast and cooking applications with minimal processing.
- Lactose-Free Yogurt:Beta-galactosidase enzyme treatment hydrolyzes lactose pre-fermentation, addressing digestive intolerance in aging demographics.
Established volume favors set yogurt; emerging adoption favors drinking yogurt.
Flavor:
Cost tier stratification separates commodity base formulations from value-added fruit preparations requiring additional supply chain segregation.
- Plain:Unsweetened base maintains largest volume foundation, serving as ingredient for cooking and smoothie customization while minimizing added-sugar disclosure complexity under FDA guidelines.
- Strawberry:Fruit preparation demands verified non-GMO cane sugar and pectin stabilizers, tightening supplier documentation requirements for dual-certified organic processors.
- Blueberry:Anthocyanin-rich fruit purees target antioxidant positioning in children's snacking occasions.
- Vanilla:Natural flavor extraction from vanilla planifolia orchids requires geographic traceability to Madagascar or Tahiti supply basins.
Plain sustains procurement scale; fruit-infused variants capture incremental margin expansion.
Packaging Type:
Application requirements dictate material selection across retail perimeter placement, e-commerce shipping durability, and sustainability credentialing.
- Plastic Cups:Polypropylene tubs dominate refrigerated dairy case placement, with thin-wall designs reducing per-unit resin costs for high-velocity SKUs.
- Tetra Pak:Aseptic carton formats enable ambient distribution for drinking yogurt, extending shelf life without cold chain dependency.
- Glass Jars:Premium positioning in natural grocery channels supports circular packaging claims through deposit-return systems.
- Pouches:Flexible film formats reduce shipping cube for direct-to-subscription fulfillment models.
Plastic cups anchor mainstream volume; pouches are gaining share fastest in digital-native channels.
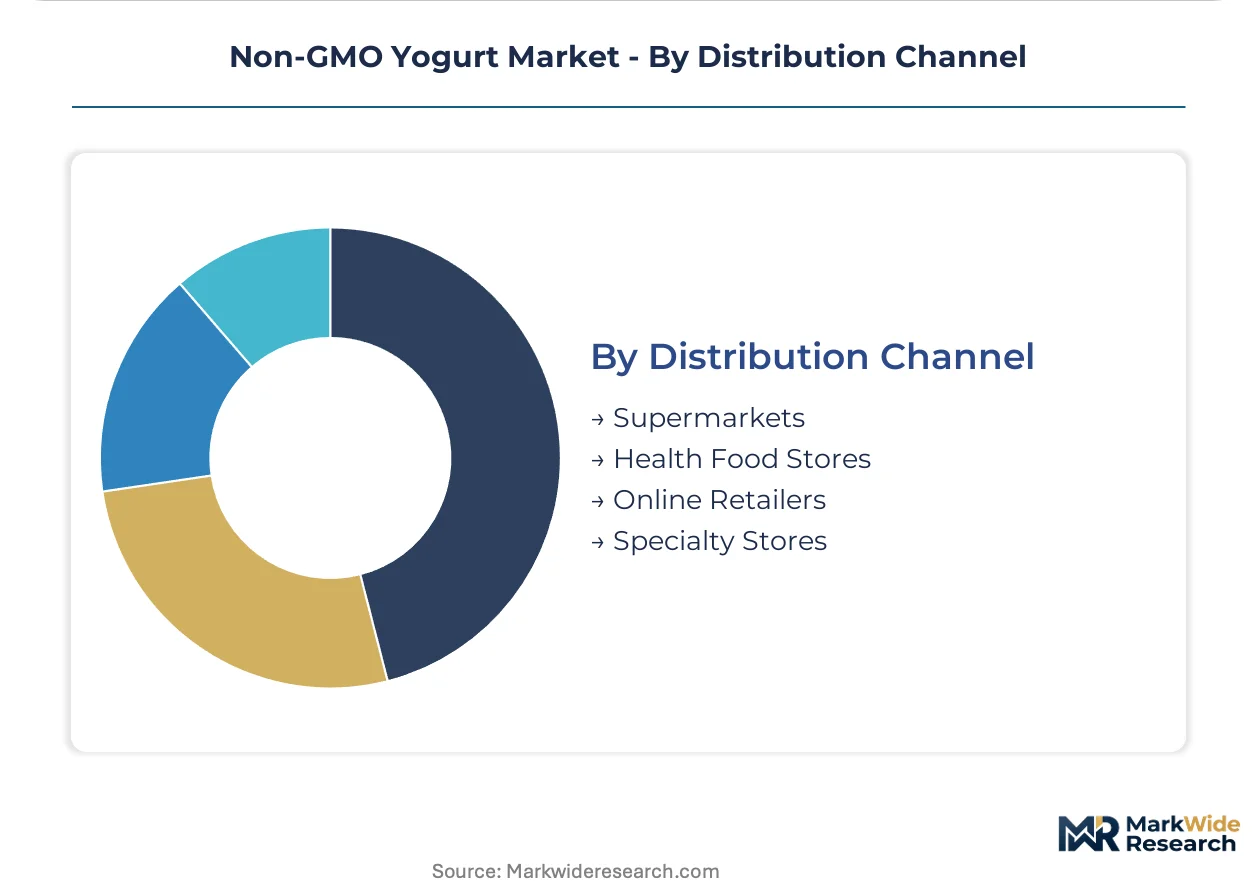
Distribution Channel:
Customer type concentration determines certification depth, with institutional procurement mandating stricter documentation than conventional retail.
- Supermarkets:Mainstream retail chains require Non-GMO Project verification for shelf placement in natural product sets, with slotting fees favoring integrated processors.
- Health Food Stores:Regional co-op networks in Oregon and Washington sustain dual-certified organic and non-GMO SKU density through consumer education investments.
- Online Retailers:Subscription platforms capture repeat purchase volume through auto-replenishment algorithms.
- Specialty Stores:Hospital and corporate wellness cafeterias mandate clean-label dairy through refreshment contract specifications.
Supermarkets consolidate procurement scale; specialty channels show steepest expansion trajectory for certified placement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Non-GMO yogurt production clusters where verified feed sourcing and fermentation infrastructure overlap. Integrated dairy cooperatives in specific geographies capture disproportionate shelf space through backward control of grain procurement.
United States
Hospital and corporate wellness cafeterias in Seattle and Portland mandate clean-label dairy through refreshment contracts. The USDA National Organic Program and FDA bioengineered disclosure standards shape ingredient documentation requirements. Oregon and Washington co-ops sustain price premiums that subsidize Non-GMO Project verification investments.
France
Specialized strain development for reduced-sugar formulations drives processor R&D spending in Brittany-based facilities. EFSA guidance on novel fermentation inputs forces reformulation reviews for clean-label variants. The Brittany fermentation cluster is narrowing national non-GMO dairy processing capacity gaps.
Germany
Natural grocery chains in Bavaria and Baden-Württemberg maintain strong consumer loyalty for certified clean-label products. EU Green Deal farm-to-fork targets tighten residue monitoring for imported dairy cultures. Munich and Stuttgart retail networks anchor premium-tier SKU placement.
Canada
Digital traceability infrastructure adoption accelerates among mid-sized Ontario processors seeking audit cost reductions. Health Canada and PMRA residue standards influence cross-border ingredient sourcing decisions. The Toronto-Ottawa corridor concentrates private-label non-GMO development activity.
Australia
Direct-to-subscription models capture repeat purchase volume in Sydney and Melbourne metro areas. TGA oversight of novel food ingredients affects probiotic strain registration timelines. Victorian dairy operations are expanding aseptic processing capacity for drinking yogurt exports.
Non-GMO Yogurt Market Competitive Landscape
Integrated cooperatives and multinational dairy conglomerates split the market between premium certification depth and mainstream retail scale. Three archetypes dominate: backward-integrated cooperatives controlling feed sourcing, multinational processors leveraging strain development capabilities, and specialist organic brands anchoring natural channel loyalty. Competitive moves concentrate on capacity expansion in fermentation facilities and strategic partnerships for digital traceability infrastructure.
Within the cooperative archetype, Chobani exemplifies scale-driven verification across mainstream retail channels. Stonyfield Farm and Danone occupy positions spanning integrated organic supply networks and specialized culture development. These three anchors represent divergent strategic paths: captive feed control, deep supplier relationships, and technical formulation differentiation.
| Leading Market Players |
|---|
| Chobani |
| Stonyfield Farm |
| Danone |
| FAGE International |
| Nestlé |
| Mengniu Dairy |
| Siggi's |
| Wallaby Organic |
| Nancy's Yogurt |
| Others |
Value Network & Pricing Analysis
Brittany's expanding fermentation cluster concentrates European non-GMO dairy processing capacity, translating upstream feed verification costs into tiered shelf-price premiums that Pacific Northwest co-ops subsidize through regional consumer loyalty.
Pricing Analysis
The Non-GMO Project standard dictates the pricing tier structure across retail channels, separating dual-certified organic SKUs from single-verified conventional lines. Three-tier pricing stratifies across premium Greek yogurt, standard spoonable formats, and economy private-label offerings. Pricing pressure stems from corn and soybean spread volatility narrowing processor margins. Hospital and corporate wellness cafeterias show least price sensitivity, while convenience-store drinking yogurt buyers demand volume discounts.
Supply Chain Analysis
Extended payment terms from integrated cooperatives to verified grain suppliers anchor working capital flows across the network. Feed sourcing concentrates in the United States, France, and Australia, with fermentation infrastructure clustered in Brittany and the Pacific Northwest. The chain draws from non-GMO corn, soybean meal, and dairy cultures as critical inputs. Single-source vulnerability in live culture suppliers poses structural risk. Distribution runs through refrigerated perimeter placement in supermarkets and direct-to-subscription fulfillment for digital-native channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-GMO yogurt sits in early-cycle expansion as corporate wellness procurement mandates accelerate certified SKU adoption ahead of mainstream retail saturation.
For Market Incumbents: Build captive feed sourcing moats through backward integration into verified grain procurement. Chobani's integrated milk supply network demonstrates how controlled sourcing secures Non-GMO Project verification at scale. Stonyfield Farm's deep organic supplier relationships offer a cooperative alternative to vertical ownership. Both approaches defend against emerging contract manufacturers with blockchain-enabled traceability platforms.
For New Entrants and Emerging Players: Mid-tier drinking yogurt in convenience-store channels represents the most penetrable entry point, with portability-driven repeat purchase velocity outpacing refrigerated perimeter competition. Reduced-sugar strain development offers technical differentiation without massive fermentation infrastructure. Target corporate wellness refreshment contracts through clean-label certification depth rather than price undercutting.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-anchored consumer staples play because dual-verified supply chains create durable switching costs for retail buyers. Acquisition candidates include mid-sized processors with blockchain traceability adoption and established Non-GMO Project relationships. Watch for IRA agricultural conservation incentive expansion as a demand inflection signal for qualifying dairy operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Non-GMO Feed Supply Integration | Captive grain sourcing locks in verification compliance and compresses third-party audit costs for processors. |
| Drinking Yogurt Format Expansion | Ambient-stable Tetra Pak distribution opens convenience-store channels outside traditional refrigerated perimeter competition. |
| Blockchain Traceability Deployment | Immutable documentation reduces Non-GMO Project compliance staffing and accelerates dispute resolution timelines. |
| Reduced-Sugar Strain Development | Specialized culture combinations enable clean-label sweetness without added sugars under FDA disclosure rules. |
| Corporate Wellness Contract Capture | Hospital and technology campus refreshment mandates create institutional volume with premium pricing tolerance. |
Research Methodology
A standing panel of fermentation scientists, retail category buyers, dairy cooperative procurement managers, and foodservice contract directors provided ongoing calibration across the study. Primary interviews with these stakeholders combined with secondary validation from USDA organic certification databases, FDA bioengineered disclosure filings, Non-GMO Project verification records, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Scenario-bracketing around feed cost volatility and certification adoption rates shaped projections across the analysis window. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel, with regional regulatory cluster as an added industry-specific layer. CAGRs derived from historical trajectory analysis and penetration curve modeling, incorporating live culture stability expertise scarcity and cold chain infrastructure expansion as forecast inputs.
Practitioners should monitor feed crop price spreads, state-level GMO labeling precedents, and digital traceability platform adoption for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Cheese Color Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Blue Cheese Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
Dairy Carton Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Ultra High Temperature Sterilized Milk Market
Dairy Products
Organic Milk Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Fluid Milk Market
Dairy Products
Lactose and Derivative Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
GCC Camel Dairy Market