
 Printed Tissue Paper Market | 2026-2036
Printed Tissue Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Tissue Paper Market Intelligence
Asset-light leasing arrangements for digital printing presses is fragmenting competitive dynamics among mid-tier tissue converters. Kimberly-Clark Corporation leverages captive pulp sourcing to sustain margin stability across North American printed towel lines. Essity AB anchors European food service napkin supply through centralized flexography hubs in Sweden and Germany. Sofidel Group competes in Southern Europe by controlling specialized short-run serviette contracts for boutique hospitality chains.
Printed tissue paper denotes wood-pulp or recycled-fiber substrates surface-decorated with food-safe or cosmetic-grade inks, typically weighing 14–22 grams per square meter and engineered for single-use absorption or decorative presentation. Flexography dominates high-volume facial tissue and toilet tissue runs where solvent-free water-based formulations meet FDA indirect food contact rules; digital printing captures fastest growth in event management and custom hospitality branding where run lengths fall below ten thousand units. Margin pools concentrate in gravure-printed premium gift wrap tissues and lithography-enhanced institutional towel lines where registration precision justifies higher unit economics.
FDA indirect food contact substance notifications and EPA volatile organic compound emission limits govern ink chemistry and drying system design across United States manufacturing. EU REACH chemical restrictions and F-Gas Regulation phase-downs on solvent-based processes are redirecting European converters toward water-based flexography and UV-cured digital platforms. Stakeholders must monitor how China's SAMR national standard revisions on recycled fiber content and India's BIS packaging material safety certifications reshape export qualification requirements and regional sourcing decisions.
Market Dynamics
Water-based ink compliance mandates across the European Union and accelerated flexography automation in East Asian mills are redirecting procurement patterns and fragmenting competitive dynamics among mid-tier tissue converters.
Growth Catalysts
- EU REACH chemical restrictions:These regulations phase down solvent-based processes and redirect European converters toward water-based flexography platforms, expanding compliant supplier pools.
- Quick-service restaurant chains:Expansion in India's tier-one cities is driving printed napkin and serviette volumes for branded hospitality consumables.
- Digital printing press leasing:Asset-light arrangements are lowering entry barriers for mid-tier converters and fragmenting competitive dynamics in custom short-run segments.
Market Restraints
- Pulp input cost volatility:Fluctuations in virgin wood-pulp and recycled fiber pricing compress margins for converters lacking captive sourcing arrangements.
- Flexography equipment concentration:High-volume press manufacturing concentrates in Germany and Japan, creating supply risk for mills in emerging markets.
- Technical registration precision limits:Gravure and lithography methods face throughput ceilings below ten thousand units, constraining premium gift wrap scaling.
Strategic Opportunities
- India's tier-one city penetration:Luxury hotel construction and quick-service restaurant expansion create white space for branded hospitality consumables.
- UV-cured digital platform convergence:Combination with water-based flexography enables hybrid production lines serving both high-volume and custom short-run demand.
- China SAMR recycled fiber standards:Upcoming national standard revisions on recycled fiber content create qualification advantages for early-compliant exporters.
Industry Challenges
- Flexography operator skill scarcity:Specialized knowledge of solvent-free water-based formulation tuning and drying system calibration remains concentrated in legacy European and Japanese workforces.
- FDA indirect food contact certification timelines:Notification review periods for ink chemistry changes delay product launches for food service napkin lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Tissue Paper Market |
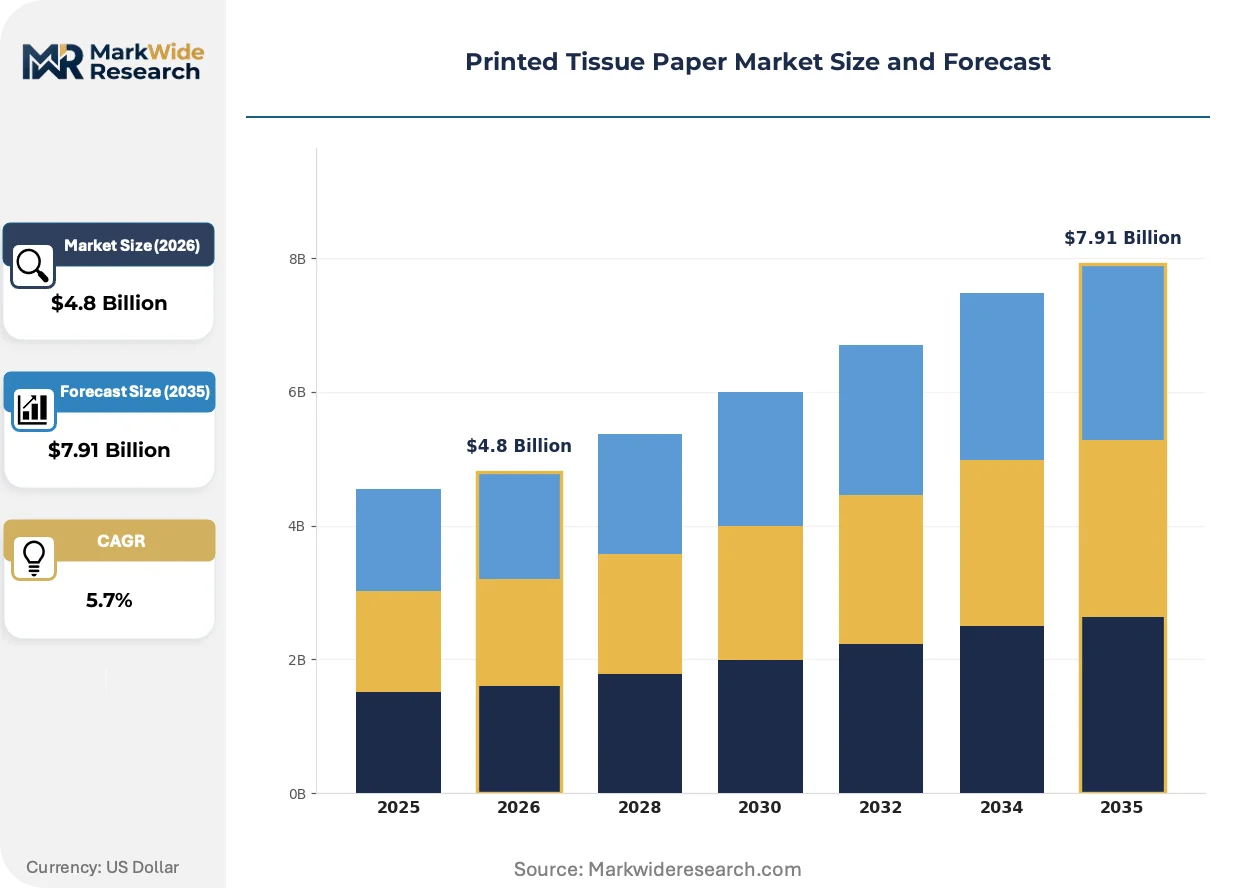
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Tissue, Toilet Tissue, Napkins, Paper Towels, Serviettes Printing Technology: Flexography, Lithography, Gravure, Digital Printing, Screen Printing Application: Hospitality, Personal Care, Food Service, Institutional Facilities, Event Management Distribution Channel: Supermarkets, Mass Merchandisers, E-Commerce, Wholesale Distributors, Specialty Stores |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Georgia-Pacific LLC, Asia Pulp & Paper, Essity AB, Cascades Inc., Sofidel Group, Hengan International Group, CMPC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Tissue Paper Market Strategic Shifts & Innovations
Digital printing technologies are collapsing minimum order thresholds and compressing production cycles, while regulatory chemistry mandates and buyer procurement model evolution reshape competitive positioning across premium and standard tiers.
Digital inkjet systems with UV-cured water-based formulations are collapsing the economic floor for short-run printed tissue production. Boutique hospitality chains and event management agencies are adopting these platforms for runs below ten thousand units. This technology is collapsing the volume advantage previously held by gravure-dominated premium gift wrap segments.
EU F-Gas Regulation phase-downs on solvent-based drying systems are forcing European converters toward water-based flexography and UV-cured digital platforms. Industrial consequence includes accelerated capital replacement cycles and stranded asset risk for legacy solvent infrastructure. Food service napkin supply chains in Sweden and Germany are responding fastest through centralized hub reconfiguration.
Buyer aggregation through hospitality procurement consortia is compressing supplier negotiation cycles and unbundling after-sales service from equipment leases. Mid-tier converters face margin pressure as purchasing power concentrates in boutique hotel chains and quick-service restaurant groups. This pattern is most visible in India's tier-one cities where luxury hotel construction is expanding printed serviette volumes.
Printed Tissue Paper Market Segmentation
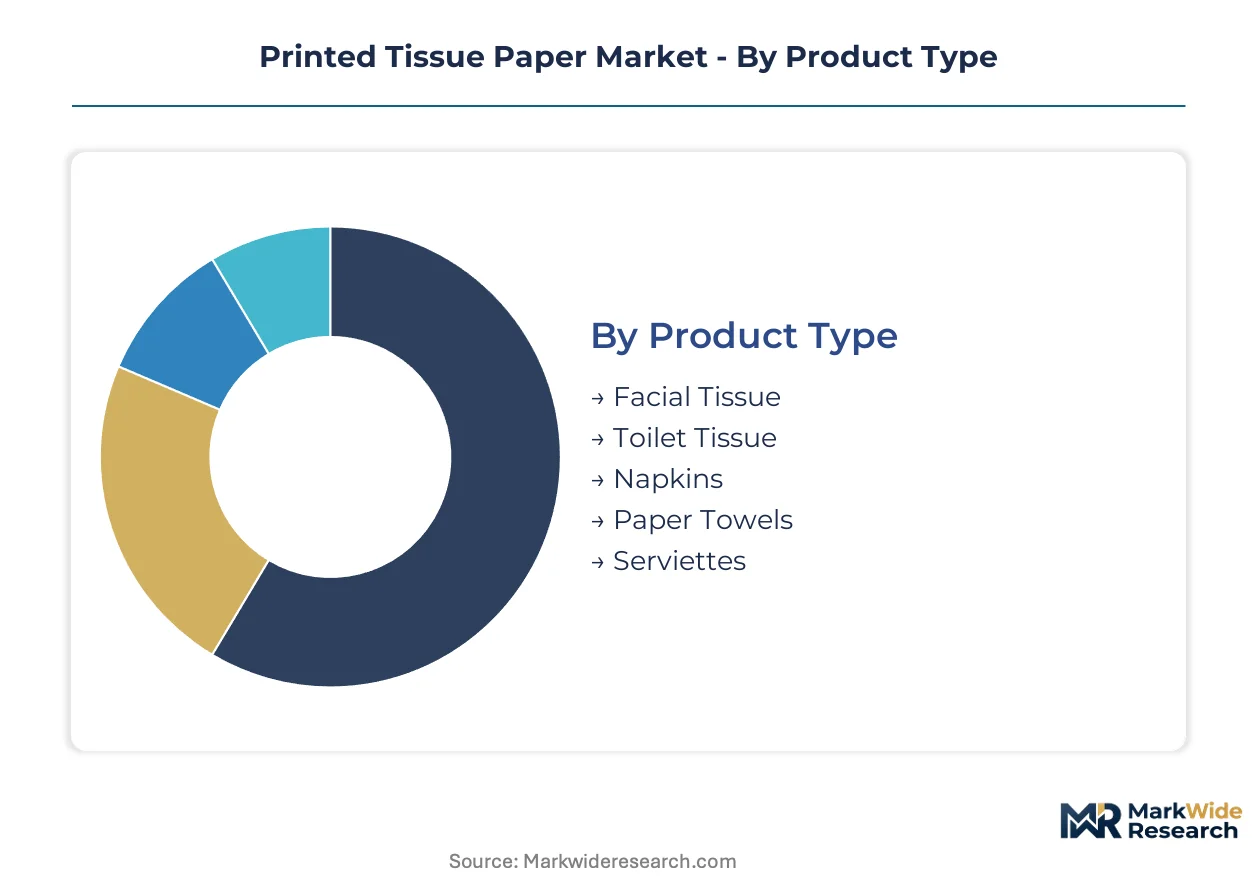
Segmentation in printed tissue paper separates volume-driven commodity grades from precision-decorated premium lines. Each dimension—product format, decoration method, end-use, and channel—carries distinct margin profiles and compliance requirements that reshape procurement priorities.
Product Type:
Cost tier separates single-use absorbency products from decorative presentation formats, with material basis weight and surface finish driving pricing architecture.
- Napkins:Food-grade substrates surface-printed with FDA-compliant water-based inks for table service applications. Quick-service restaurant chains in India's tier-one cities are expanding volumes for branded hospitality consumables, though BIS packaging safety certifications complicate import qualification timelines.
- Serviettes:Higher basis weight decorative tissues engineered for boutique hospitality presentation, typically gravure-printed with registration precision below 0.1mm. Luxury hotel construction in Mumbai and Delhi is rotating up demand for short-run custom branding where digital platforms capture contract flow.
- Facial Tissue:Softwood-pulp substrates with cosmetic-grade ink formulations for personal care packaging.
- Toilet Tissue:Recycled-fiber or virgin-pulp rolls with surface decoration for retail shelf differentiation.
- Paper Towels:High-absorbency institutional grades with limited print coverage for kitchen and washroom applications.
Napkins hold installed capacity. Serviettes is rotating up the share rankings.
Printing Technology:
Application requirements dictate method selection, with food contact compliance and run length economics fragmenting technology adoption across converter tiers.
- Flexography:Solvent-free water-based formulations on anilox roller systems for high-volume facial and toilet tissue runs. EU REACH chemical restrictions are redirecting European converters toward compliant water-based platforms, expanding supplier pools for food service napkin lines.
- Digital Printing:UV-cured inkjet systems collapsing minimum order thresholds below ten thousand units. Event management agencies and boutique hospitality chains are adopting these platforms for custom short-run production, compressing the volume advantage previously held by gravure-dominated segments.
- Gravure:Cylinder-based precision decoration for premium gift wrap tissues requiring registration accuracy.
- Lithography:Offset methods for institutional towel lines with moderate print complexity and mid-scale volumes.
- Screen Printing:Specialty applications with heavy ink deposition for decorative serviette borders and logo treatments.
Flexography holds installed capacity. Digital Printing is climbing the fastest.
Application:
Customer type segments volume buyers from specification-driven purchasers, with regulatory exposure and brand equity requirements shaping converter relationships.
- Food Service:Napkins and serviettes for restaurant, catering, and institutional dining with FDA indirect food contact substance notifications governing ink chemistry. Quick-service restaurant procurement consortia are compressing supplier negotiation cycles and unbundling after-sales service from equipment leases.
- Hospitality:Branded consumables for hotels, resorts, and cruise lines where presentation quality supports property positioning. India's tier-one city penetration creates white space as luxury hotel construction expands printed serviette volumes.
- Personal Care:Facial tissue and toilet tissue for retail consumer markets with cosmetic-grade formulation requirements.
- Institutional Facilities:Healthcare, education, and corporate washroom supplies with standardized procurement specifications.
- Event Management:Custom-printed tissues for weddings, corporate functions, and promotional campaigns with sub-thousand-unit run lengths.
Food Service holds installed capacity. Hospitality is gaining share fastest.
Distribution Channel:
Geography and buyer scale determine channel selection, with procurement model evolution reshaping margin capture across retail and contract routes.
- E-Commerce:Direct-to-customer platforms for custom short-run orders and event management procurement. Asset-light digital printing press leasing is fragmenting competitive dynamics among mid-tier converters serving this channel.
- Wholesale Distributors:Consolidated supply to food service operators and hospitality groups with centralized inventory management. Buyer aggregation through procurement consortia is concentrating purchasing power and pressuring mid-tier converter margins.
- Supermarkets:Mass retail placement for branded facial and toilet tissue with high-velocity replenishment requirements.
- Mass Merchandisers:Big-box retail contracts for multi-pack tissue products with promotional pricing cycles.
- Specialty Stores:Premium gift wrap tissues and decorative serviettes for boutique retail positioning.
Wholesale Distributors holds installed capacity. E-Commerce is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European flexography hubs where REACH compliance creates supplier scarcity, while East Asian mills compete on automation-driven cost compression. This asymmetry redirects procurement patterns toward compliant exporters and fragments competitive dynamics among mid-tier converters lacking captive pulp sourcing.
United States
Food service napkin demand from quick-service restaurant chains and institutional dining drives volume, though FDA indirect food contact notification timelines delay product launches. EPA volatile organic compound emission limits govern ink chemistry and drying system design across manufacturing. The Southeast pulp-tissue corridor spanning Georgia and Alabama hosts concentrated flexography capacity serving North American retail and hospitality channels.
Germany
Centralized flexography hubs supply European food service napkin lines with water-based formulation compliance. EU F-Gas Regulation phase-downs on solvent-based processes force accelerated capital replacement cycles and stranded asset risk for legacy infrastructure. The Baden-Württemberg industrial cluster anchors high-volume press manufacturing and specialized drying system calibration expertise.
Sweden
Boutique hospitality procurement consortia compress supplier negotiation cycles for branded serviette contracts. REACH chemical restrictions expand compliant supplier pools while redirecting converter investment toward UV-cured digital platforms. Stockholm-Uppsala logistics corridors enable centralized hub reconfiguration serving Nordic and Baltic food service supply chains.
India
Luxury hotel construction in Mumbai and Delhi rotates up demand for short-run custom serviette branding where digital platforms capture contract flow. BIS packaging material safety certifications complicate import qualification timelines for foreign converters. Quick-service restaurant expansion across tier-one cities expands printed napkin volumes for branded hospitality consumables.
China
Accelerated flexography automation in East Asian mills redirects procurement patterns through cost-competitive high-volume output. SAMR national standard revisions on recycled fiber content reshape export qualification requirements and regional sourcing decisions. The Yangtze River Delta manufacturing belt concentrates digital printing press assembly and water-based ink formulation capacity.
Printed Tissue Paper Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in ink formulation and anilox roller supply. The market structure consolidates around three to five vertically integrated pulp-to-tissue conglomerates with captive sourcing, while mid-tier converters fragment across asset-light digital leasing arrangements. Strategic archetypes span captive pulp owners, flexography automation leaders, and short-run digital specialists. Dominant competitive moves include backward integration into pulp supply and hybrid production line convergence combining water-based flexography with UV-cured digital platforms.
Among North American pulp-integrated conglomerates, Kimberly-Clark Corporation and Georgia-Pacific LLC exemplify scale-driven platform control through captive fiber sourcing and centralized manufacturing footprints. Within the European compliance-specialist tier, Essity AB and Sofidel Group occupy positions anchored by REACH-aligned water-based flexography hubs and boutique hospitality contract concentration. These named entities represent strategic archetypes rather than exhaustive market coverage, with competitive dynamics further fragmenting as digital press leasing lowers entry barriers for mid-tier converters in custom short-run segments.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Georgia-Pacific LLC |
| Asia Pulp & Paper |
| Essity AB |
| Cascades Inc. |
| Sofidel Group |
| Hengan International Group |
| CMPC |
| Others |
Cost & Logistics Intelligence
Captive pulp sourcing in North American integrated mills concentrates margin stability downstream in branded towel and napkin lines, while converters without upstream fiber control face compressed economics during virgin wood-pulp price spikes. This asymmetry between integrated conglomerates and asset-light mid-tier operators fragments competitive positioning across premium gift wrap and standard food service tiers.
Pricing Analysis
The customization-premium spread separates gravure-printed serviettes with sub-0.1mm registration precision from flexography commodity napkin runs. Three-tier pricing structure across premium, standard, and economy levels stratifies by basis weight, ink formulation grade, and FDA indirect food contact certification status. Pricing pressure stems from buyer aggregation through hospitality procurement consortia unbundling after-sales service from equipment leases. Quick-service restaurant chains exhibit highest price sensitivity due to volume procurement cycles, while boutique hotel chains absorb premiums for short-run digital customization.
Supply Chain Analysis
Supplier-financing arrangements including extended payment terms and supply-chain finance facilities have become standard for digital press acquisition among mid-tier converters. Raw material flows draw from German and Japanese flexography equipment manufacturers, Swedish pulp-integrated hubs, and Chinese water-based ink formulation clusters. Single-source vulnerability concentrates in anilox roller and high-volume press manufacturing. Distribution runs through wholesale distributors consolidating inventory for food service operators and hospitality procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospitality procurement consortia and quick-service restaurant group purchasing organizations, fragmenting supplier margins and compressing negotiation cycles for mid-tier converters.
For Market Incumbents: Pre-empt digital platform leasing fragmentation by consolidating short-run serviette contract flow through hybrid production lines combining water-based flexography with UV-cured digital capacity. Anchor margin stability through captive pulp sourcing or long-term fiber offtake agreements with Swedish or Finnish suppliers. Counter asset-light entrant pressure by unbundling equipment service from consumables supply in negotiated contracts. For New Entrants and Emerging Players: Pursue India's tier-one city hospitality construction wave through digital printing press leasing arrangements targeting luxury hotel serviette customization below ten thousand units. Capture contract flow from event management agencies requiring sub-thousand-unit runs with compressed production cycles. Establish go-to-market positioning through e-commerce direct procurement platforms bypassing wholesale distributor consolidation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier converters holding stranded solvent-based flexography infrastructure facing EU F-Gas Regulation compliance deadlines. Five-to-ten-year viability hinges on successful hybrid line reconfiguration and REACH-aligned water-based formulation transitions. Monitor SAMR recycled fiber standard revision timing as inflection indicator for Chinese export qualification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Production Line Convergence | Combines water-based flexography with UV-cured digital platforms serving both high-volume and custom short-run demand. |
| Captive Pulp Sourcing Arrangements | Backward integration into virgin fiber supply stabilizes margin exposure during wood-pulp price volatility cycles. |
| REACH Compliance Infrastructure | Water-based formulation hubs in Germany and Sweden expand compliant supplier pools for European food service napkin lines. |
| Digital Press Leasing Programs | Asset-light arrangements lower entry barriers for mid-tier converters targeting event management and boutique hospitality segments. |
| India Tier-One City Penetration | Luxury hotel construction in Mumbai and Delhi rotates up demand for short-run custom serviette branding contracts. |
Research Approach
A standing panel of tissue converters, flexography press operators, hospitality procurement managers, and food service supply chain directors provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA indirect food contact substance notification databases, EU REACH chemical restriction filings, SAMR standard revision drafts, and trade customs records for pulp and tissue machinery imports. Bottom-up capacity assessments triangulated against top-down demand modeling across product format, printing technology, and end-use application dimensions.
Scenario-bracketing framed low, base, and high cases reflecting regulatory acceleration variance and pulp input cost volatility bands across the projection horizon. Segmentation modeling incorporated product type, printing technology, application, and distribution channel dimensions with regional regulatory cluster overlays. CAGRs derived from volume trajectory analysis calibrated against installed capacity utilization rates and buyer procurement model evolution patterns. Forecast inputs included flexography automation adoption curves and digital press leasing penetration rates.
Sensitivities concentrate around EU F-Gas Regulation enforcement timing, SAMR recycled fiber content standard finalization, and pulp price volatility amplitude. Forecasts reflect documented assumptions regarding buyer aggregation pace and technology substitution thresholds. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Malaysia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Felt Bobs Market
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Ring Spinning Frame Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
E-Glass Fiber Yarn and Roving Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Sewing Thread Market
Yarn and Fabric Manufacturing
Flat Knitting Machine Market
Yarn and Fabric Manufacturing
Italy Textile Manufacturing Market
Yarn and Fabric Manufacturing
Sailcloth Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Europe Textile Market