
 Asia Pacific Touch Screen Controllers Market | 2026-2036
Asia Pacific Touch Screen Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Touch Screen Controllers Market Outlook
South Korea's display semiconductor corridor is rewriting procurement patterns for capacitive touch controllers across the Asia Pacific. Texas Instruments sustains analog front-end leadership through dense channel partner networks in Shenzhen and Taipei. STMicroelectronics leverages integrated MCU-controller combinations to anchor industrial automation design wins across Japan and Australia. Synaptics differentiates through fingerprint-sensor fusion controllers that dominate premium smartphone sockets in China and India.
Asia Pacific touch screen controllers are mixed-signal integrated circuits that convert analog capacitive or resistive panel signals into digital touch coordinates, typically operating at supply voltages between 1.8V and 3.3V with sampling rates exceeding 100Hz for multi-touch tracking. These devices serve as the critical interface layer between human input and embedded systems in smartphones, vehicle infotainment panels, and factory HMI terminals. Capacitive controllers command the largest value share due to smartphone and tablet penetration, while infrared controllers represent a faster-growing niche in outdoor kiosks and medical environments where glove compatibility matters. Multi-touch technology captures the dominant volume position, though gesture recognition controllers are gaining traction in automotive interfaces where driver distraction regulations favor hands-free interaction paradigms.
China's SAMR enforces GB 9254 electromagnetic compatibility standards that dictate radiated emission limits for touch controllers deployed in consumer electronics. Japan's METI coordinates JIS standards for industrial equipment interfaces, while South Korea's MFDS oversees medical device touch panel certifications that constrain controller supplier eligibility. India's BIS mandatory registration scheme for electronic components is extending compliance timelines for non-domestic semiconductor vendors. Stakeholders must monitor how divergent national certification timelines affect inventory positioning and regional manufacturing commitments.
Market Dynamics
South Korea's display semiconductor corridor is consolidating touch controller specification authority, with Seoul-based panel makers dictating multi-touch sampling rates and electromagnetic compatibility thresholds that cascade through Shenzhen assembly lines and Taipei design houses.
Growth Catalysts
- Smartphone OEM Expansion:Indian and Southeast Asian handset manufacturers are scaling mid-tier device production, creating sustained demand for cost-optimized capacitive controllers with integrated gesture recognition.
- GB 9254 Compliance Upgrades:China's SAMR is tightening radiated emission limits for consumer electronics, forcing controller redesigns that favor domestic suppliers with established certification pathways.
- Automotive HMI Modernization:Japanese and Australian vehicle manufacturers are specifying touch controllers with haptic feedback integration for infotainment clusters, opening adjacent revenue streams beyond mobile devices.
Market Restraints
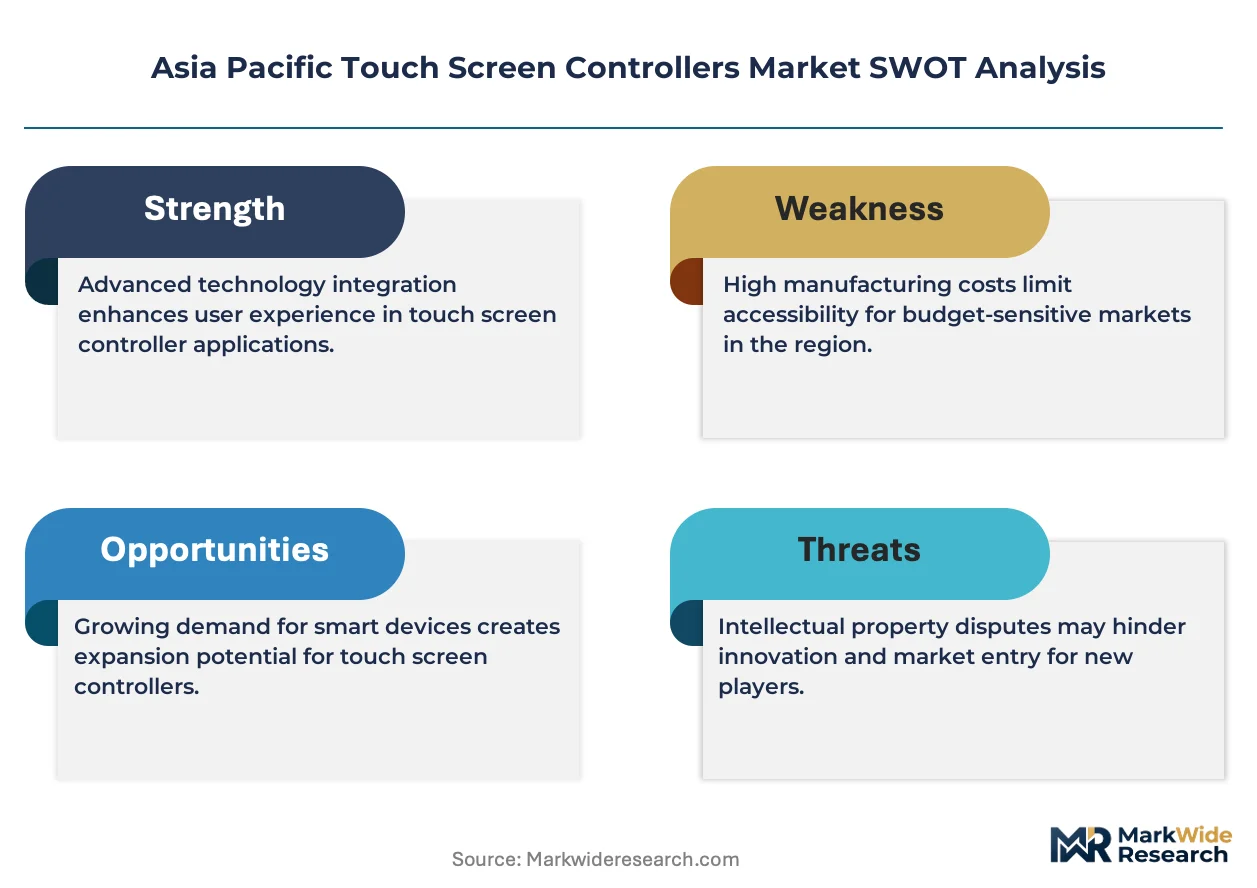
- Silicon Wafer Cost Volatility:Foundry capacity constraints in Taiwan and South Korea are inflating analog front-end die costs, compressing gross margins for fabless controller vendors.
- Supply Concentration Risk:Advanced multi-touch DSP cores depend on a narrow base of Seoul and Tokyo-based intellectual property licensors, creating licensing bottleneck exposure.
- Electromagnetic Interference Limitations:Dense channel configurations in high-resolution panels face signal-to-noise degradation near 5G antenna modules, constraining design flexibility.
Strategic Opportunities
- Vietnam Manufacturing Migration:Assembly line relocation from coastal China to northern Vietnam is creating demand for controllers with simplified logistics certification and shorter customs clearance protocols.
- Medical Device Integration:Australia's TGA and South Korea's MFDS are expanding touch panel approval pathways for surgical navigation systems, enabling premium pricing for sterilization-resistant controller variants.
- MCU-Controller Convergence:Industrial automation buyers across Japan are specifying single-chip solutions combining touch processing with motor control, rewarding vendors with integrated portfolio breadth.
Industry Challenges
- Mixed-Signal Design Talent Scarcity:Analog-digital interface expertise concentrates in Seoul and Hsinchu, forcing non-cluster vendors into expensive relocation packages or remote team fragmentation.
- Multi-Jurisdiction Certification Overlap:India's BIS mandatory registration scheme runs parallel to China's GB standards and Japan's JIS frameworks, extending product launch timelines by 8-14 months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Touch Screen Controllers Market |
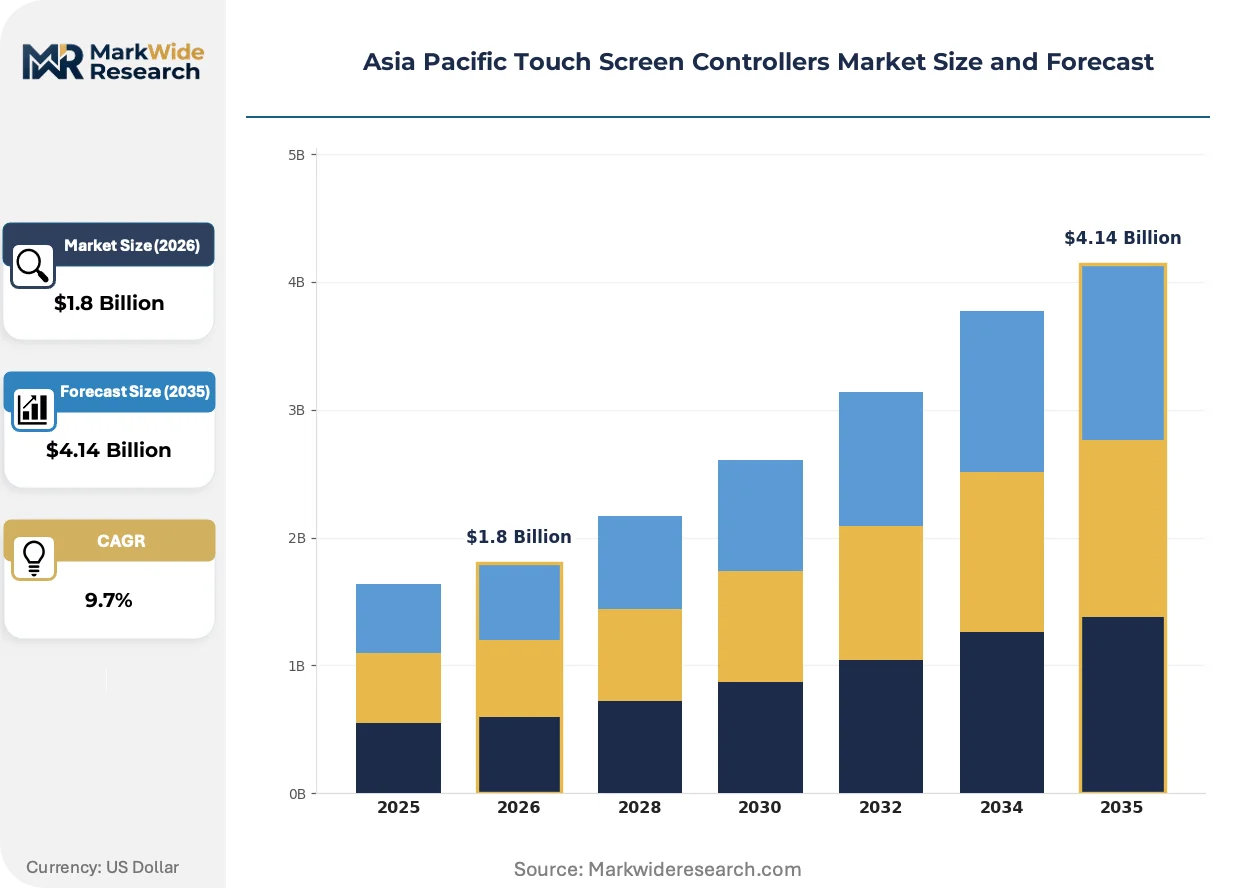
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resistive, Capacitive, Infrared, Optical Application: Consumer Electronics, Automotive Interface, Industrial Automation, Retail Kiosks Technology: Multi-Touch, Single Touch, Gesture Recognition, Pressure Sensing End User: OEMs, Manufacturers, Retailers, Distributors |
| Companies Covered | STMicroelectronics N.V., Texas Instruments Inc., Cypress Semiconductor Corporation, Microchip Technology Inc., Analog Devices Inc., Infineon Technologies AG, Synaptics Incorporated, NXP Semiconductors, Renesas Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Touch Screen Controllers Market Strategic Shifts
Controller architectures are virtualizing signal processing functions that previously demanded dedicated hardware, compressing bill-of-materials costs while enabling firmware-upgradable feature sets that extend product lifecycles in fast-refresh mobile markets.
Sensor fusion is virtualizing discrete fingerprint and touch functions into unified controller silicon, eliminating separate biometric modules in premium smartphones. Chinese and Indian OEMs are adopting these integrated solutions fastest, with flagship design cycles now mandating single-chip implementations. This consolidation is virtualizing secondary supplier tiers and concentrating procurement authority among vendors with biometric algorithm portfolios.
Japan's METI is coordinating updated JIS standards for industrial equipment electromagnetic resilience, mandating expanded temperature operating ranges and vibration tolerance for factory floor touch interfaces. Controller vendors serving automation OEMs must now qualify products through revised METI-administered test protocols before accessing public infrastructure project supplier lists. Heavy machinery and process control segments are responding by pre-qualifying dual-source controller configurations to mitigate certification delay risks.
Panel maker direct contracting is displacing traditional component distributor channels across South Korea and Taiwan. Seoul-based display manufacturers now specify controllers through dedicated semiconductor procurement divisions that negotiate volume commitments directly with analog front-end designers, bypassing Taipei and Hong Kong-based intermediaries. This channel compression is most visible in tablet and notebook segments where annual contract values justify dedicated supplier relationship management overhead.
Asia Pacific Touch Screen Controllers Market Segmentation
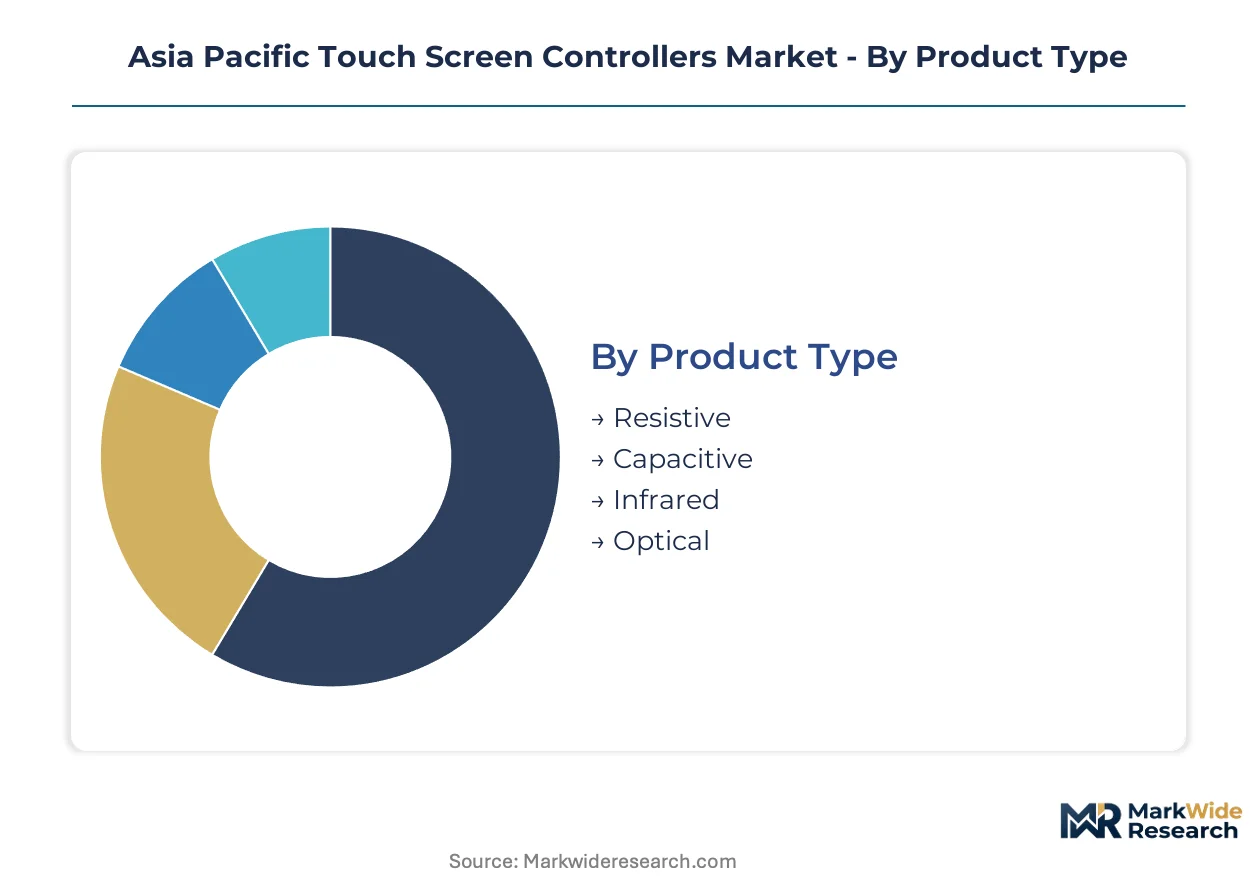
Touch controller segmentation in Asia Pacific reflects divergent technical requirements across smartphone assembly lines in Shenzhen, automotive clusters in Nagoya, and industrial automation corridors in Seoul. Procurement patterns fragment sharply between cost-optimized capacitive solutions for mid-tier handsets and precision-engineered variants for medical device OEMs in Osaka and Singapore.
Product Type:
After-sales service intensity varies dramatically across controller architectures, with resistive panels demanding frequent calibration support in factory environments while capacitive solutions require minimal field intervention.
- Capacitive:These controllers detect touch through electrical field disruption at the glass surface, enabling multi-point tracking essential for smartphone and tablet interfaces. Demand concentrates in South Korea's display corridor where Seoul-based panel makers specify sampling rates above 120Hz for flagship handsets, with electromagnetic compatibility certification under China's GB 9254 standards creating supplier qualification bottlenecks.
- Resistive:Pressure-activated layers complete electrical circuits through physical deformation, functioning reliably with gloved hands or stylus input. Industrial automation buyers across Japan's METI-regulated factory equipment segments favor these controllers for HMI terminals where vibration tolerance and expanded temperature ranges outweigh precision requirements.
- Infrared:Grid-based photodetector arrays enable touch detection without surface overlays, supporting outdoor kiosk deployments in Australia's retail infrastructure.
- Optical:Camera-based imaging systems track touch coordinates through visual pattern recognition, serving large-format interactive displays in India's educational technology procurement.
Capacitive holds the largest share; momentum sits with infrared as outdoor and medical applications expand.
Application:
Cost tier stratification separates premium automotive specifications from economy-grade consumer electronics, with certification overhead creating pricing cliffs between segments.
- Consumer Electronics:Smartphones, tablets, and wearable devices drive volume procurement with aggressive cost targets. Indian and Southeast Asian OEMs are scaling mid-tier production, sourcing controllers through Shenzhen channel partners with integrated gesture recognition firmware.
- Automotive Interface:Vehicle infotainment clusters and dashboard controls demand haptic feedback integration and extended temperature operation. Japanese manufacturers specify these controllers through direct procurement relationships with analog front-end designers, bypassing traditional distribution.
- Industrial Automation:Factory floor HMI terminals require vibration tolerance and electromagnetic resilience under Japan's updated JIS standards. Seoul and Tokyo-based intellectual property licensors control advanced multi-touch DSP cores for this segment.
- Retail Kiosks:Self-service terminals and point-of-sale interfaces prioritize durability and glove compatibility, with Australia's TGA expanding touch panel approval pathways for adjacent medical applications.
Consumer electronics commands dominant volume; automotive interface is climbing the fastest as haptic integration becomes standard.
Technology:
Customer type differentiation separates high-volume smartphone OEMs seeking firmware-upgradable feature sets from industrial buyers prioritizing long-term supply stability.
- Multi-Touch:Simultaneous tracking of multiple contact points enables pinch, zoom, and rotation gestures through dedicated DSP architectures. South Korean display makers dictate specification roadmaps that cascade through Taipei design houses, with controller virtualization compressing bill-of-materials costs while extending product lifecycles.
- Gesture Recognition:Algorithmic interpretation of motion patterns enables hands-free interaction paradigms critical for driver distraction regulations. Chinese and Indian OEMs are adopting these solutions fastest, with flagship design cycles now mandating single-chip implementations combining biometric and touch functions.
- Single Touch:Basic coordinate detection serves cost-sensitive applications where multi-point tracking adds unnecessary complexity.
- Pressure Sensing:Force-sensitive layers enable variable input response, supporting stylus and drawing applications in creative professional segments.
Multi-touch captures the dominant position; gesture recognition is gaining share fastest through automotive safety mandates.
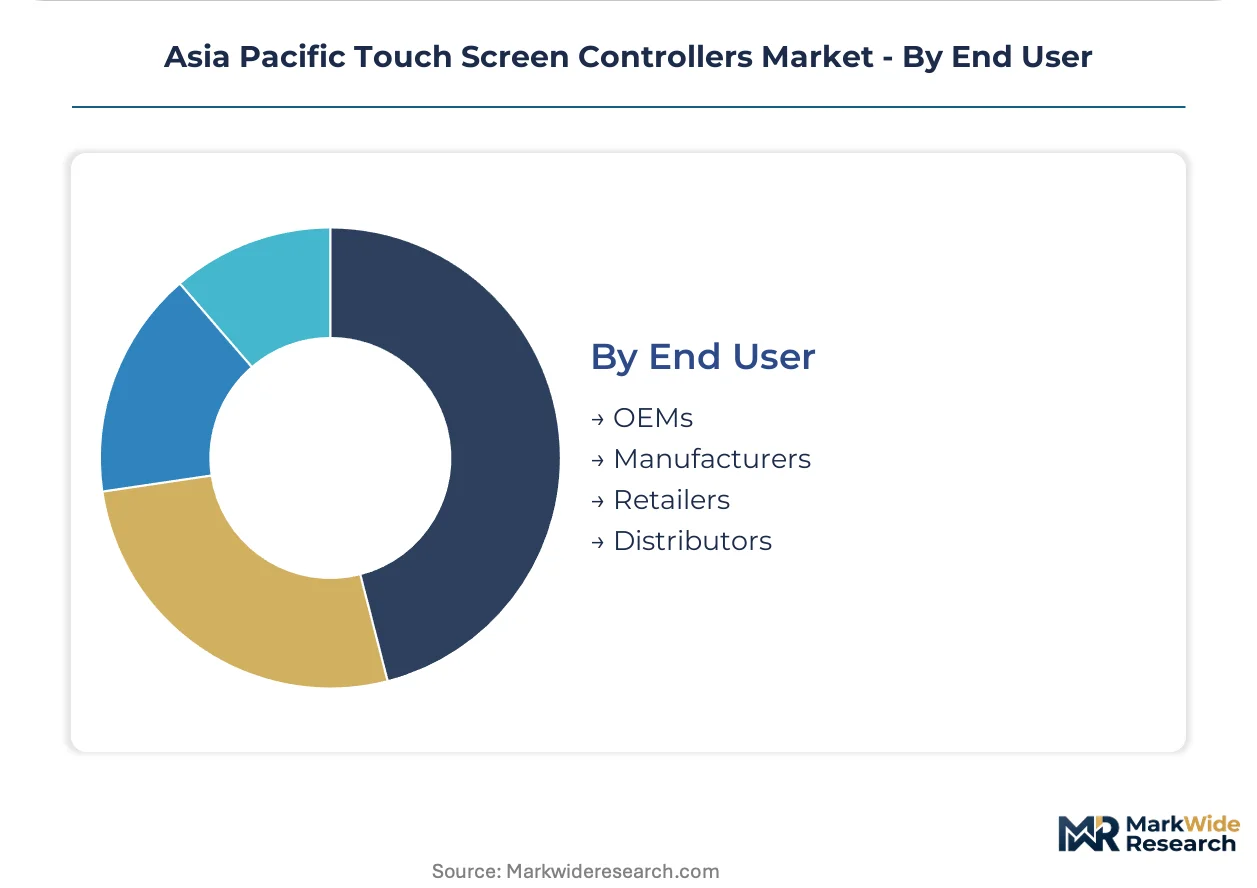
End User:
Supply concentration shapes procurement leverage, with OEMs extracting volume commitments directly from controller designers while distributors serve fragmented retailer demand.
- OEMs:Original equipment manufacturers in smartphones and automotive systems negotiate annual contracts through dedicated semiconductor procurement divisions. Panel maker direct contracting is displacing traditional channels across South Korea and Taiwan, with Seoul-based display manufacturers bypassing Taipei and Hong Kong intermediaries.
- Manufacturers:Contract electronics assemblers in Vietnam and northern China source controllers with simplified logistics certification as assembly lines relocate from coastal provinces.
- Retailers:Consumer electronics chains and corporate IT resellers face inventory positioning challenges from divergent national certification timelines across India's BIS, China's GB standards, and Japan's JIS frameworks.
- Distributors:Component wholesalers maintain regional stocking positions for aftermarket replacement and repair segments, though channel compression is eroding traditional margins.
OEMs hold the largest share; momentum sits with manufacturers as Vietnam production migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul-based panel makers concentrate touch controller specification authority, with procurement decisions cascading through Shenzhen assembly corridors and Taipei design houses. Display semiconductor clusters in South Korea and Taiwan dictate multi-touch sampling rates and electromagnetic compatibility thresholds that reshape supplier qualification protocols across the region.
China
Mid-tier smartphone OEMs in Shenzhen and Dongguan are scaling capacitive controller procurement for domestic and export handset production. SAMR enforces GB 9254 electromagnetic compatibility standards that tighten radiated emission limits for consumer electronics, favoring domestic suppliers with established certification pathways. Yangtze River Delta assembly hubs are absorbing controller inventory ahead of compliance deadline migrations.
South Korea
Seoul-based display manufacturers negotiate annual controller contracts through dedicated semiconductor procurement divisions, bypassing traditional distribution channels. MFDS oversees medical device touch panel certifications that constrain supplier eligibility for surgical navigation systems. Busan-Ulsan industrial corridors are qualifying sterilization-resistant controller variants for premium medical equipment exports.
Japan
Automotive OEMs in Nagoya and Tokyo specify touch controllers with haptic feedback integration for infotainment clusters and dashboard controls. METI coordinates updated JIS standards for industrial equipment electromagnetic resilience, mandating expanded temperature ranges for factory floor HMI terminals. Osaka medical device clusters are expanding touch panel approval pathways for adjacent surgical applications.
India
Handset manufacturers in Noida and Chennai are scaling mid-tier device production, creating sustained demand for cost-optimized capacitive controllers with integrated gesture recognition. BIS mandatory registration scheme for electronic components extends compliance timelines for non-domestic semiconductor vendors. Karnataka's electronics manufacturing zones are absorbing relocated assembly capacity from coastal China.
Vietnam
Contract electronics assemblers in Bac Ninh and Hai Phong are sourcing controllers with simplified logistics certification as production migrates from northern China provinces. Shorter customs clearance protocols favor suppliers with regional stocking positions in Hanoi and Ho Chi Minh City. Northern Vietnam manufacturing corridors are qualifying dual-source controller configurations to mitigate certification delay risks.
Asia Pacific Touch Screen Controllers Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in analog front-end and mixed-signal domains. The vendor base arranges into three tiers: diversified semiconductor conglomerates with broad analog portfolios, fabless controller specialists focused on touch-specific IP, and integrated device manufacturers serving captive display maker demand. Competitive moves center on direct panel maker contracting and MCU-controller convergence for industrial automation sockets.
Among European-domiciled diversified suppliers, STMicroelectronics N.V. and Infineon Technologies AG occupy positions emphasizing integrated MCU-controller combinations for automotive and industrial segments. Texas Instruments Inc. exemplifies the analog front-end specialist archetype through channel partner density in Shenzhen and Taipei. Synaptics Incorporated represents the fingerprint-sensor fusion controller tier dominating premium smartphone sockets in China and India.
| Leading Market Players |
|---|
| STMicroelectronics N.V. |
| Texas Instruments Inc. |
| Cypress Semiconductor Corporation |
| Microchip Technology Inc. |
| Analog Devices Inc. |
| Infineon Technologies AG |
| Synaptics Incorporated |
| NXP Semiconductors |
| Renesas Electronics |
| Others |
Value Chain & Pricing Dynamics
Foundry undercapacity across Taiwan and South Korea is compressing analog front-end die availability, forcing controller vendors into allocation-driven pricing postures that favor annual contract commitments over spot procurement.
Pricing Analysis
China's GB 9254 electromagnetic compatibility standards dictate the pricing tier structure across the Asia Pacific touch controller market, separating premium-certified domestic suppliers from import-dependent vendors facing extended compliance timelines. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with automotive haptic-integrated controllers commanding the highest tier and mid-tier smartphone capacitive solutions facing the steepest cost compression. Pricing pressure stems from silicon wafer cost volatility and foundry margin expansion, with Indian and Southeast Asian handset OEMs exhibiting the greatest price sensitivity while South Korean display makers demonstrate inelastic demand for specification-compliant controllers.
Supply Chain Analysis
Tariff exposure between China and Vietnam dominates supply chain risk calculus as assembly lines migrate to northern Vietnam manufacturing corridors. Controller production draws from Taiwan's foundry base, South Korea's display semiconductor cluster, and Shenzhen's channel partner networks, with advanced multi-touch DSP cores resting on intellectual property licensors in Seoul and Tokyo. Raw material dependencies include 8-inch silicon wafers, copper-clad laminate substrates, and gold bonding wire. Distribution runs through direct panel maker contracting that displaces traditional Taipei and Hong Kong-based intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Touch controller architectures are approaching a platform-economics inflection as sensor fusion virtualizes discrete biometric and touch functions into unified silicon, with interoperability between fingerprint algorithms and multi-touch DSP cores determining ecosystem lock-in.
For Market Incumbents: Entrench specification authority through deeper integration with Seoul-based display makers, anchoring multi-touch sampling rate roadmaps that cascade through regional design houses. Prioritize MCU-controller convergence for Japanese industrial automation sockets to defend against STMicroelectronics' integrated portfolio breadth. Secure captive foundry capacity in Taiwan through long-term wafer supply agreements that constrain fabless competitor access. For New Entrants and Emerging Players: Pursue sterilization-resistant controller variants for South Korean and Australian medical device approvals, where MFDS and TGA certification pathways create qualification moats against established smartphone-focused vendors. Target Vietnam-based contract manufacturers with simplified logistics certification and shorter customs clearance protocols as production migration accelerates from coastal China. Lead with firmware-upgradable architectures that extend product lifecycles in fast-refresh mobile markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with biometric algorithm portfolios that lock premium smartphone OEMs into single-chip sensor fusion implementations. Over the medium-term horizon, prioritize acquisition targets with established GB 9254 certification pathways and direct relationships with Shenzhen channel partners. Watch for inflection in automotive haptic feedback integration mandates across Japanese and Australian vehicle platforms.| Strategic Initiative | Industry Significance |
|---|---|
| MCU-Controller Convergence | STMicroelectronics anchors industrial automation design wins through integrated motor control combinations across Japan and Australia. |
| Direct Panel Maker Contracting | Seoul-based display manufacturers bypass Taipei intermediaries, compressing channel margins and concentrating procurement authority. |
| GB 9254 Compliance Investment | Domestic Chinese suppliers with established SAMR certification pathways capture mid-tier smartphone controller share from import-dependent vendors. |
| Sensor Fusion Integration | Synaptics dominates premium smartphone sockets through unified fingerprint-touch silicon that eliminates separate biometric modules. |
| Vietnam Manufacturing Qualification | Controllers with simplified logistics certification capture assembly line relocation demand in Bac Ninh and Hai Phong corridors. |
Study Parameters
Operator-level perspectives from touch controller procurement directors at Seoul-based panel makers, analog front-end designers in Hsinchu, and industrial automation OEMs in Nagoya anchored the qualitative base. Primary fieldwork combined structured interviews with semiconductor procurement divisions, channel partner managers in Shenzhen and Taipei, and regulatory affairs leads navigating China's SAMR and India's BIS frameworks. Secondary validation drew from SEC semiconductor filings, customs trade data for controller IC imports, and METI-administered JIS standard updates. Bottom-up segment sizing triangulated against top-down display panel production forecasts.
Scenario bracketing around foundry capacity utilization and certification timeline divergence shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included controller architecture, application vertical, technology tier, and end-user procurement structure, with additional granularity on electromagnetic compatibility grade. CAGRs derived from shipment volume trajectories by segment, weighted by average selling price evolution across premium and economy tiers. Forecast inputs incorporated display panel area forecasts and smartphone production data by regional manufacturing cluster.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, China-Vietnam tariff schedules, or analog-digital interface talent migration patterns would shift the trajectory. Forecasts reflect documented assumptions on technology substitution rates and regulatory implementation schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Global Capacitive Sensor Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Aspiration Control Systems Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Digital Humidity Sensor Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Wireless IoT Sensors Market