
 Fluid Dispensing Equipment Market | 2026-2036
Fluid Dispensing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Dispensing Equipment Market Analysis
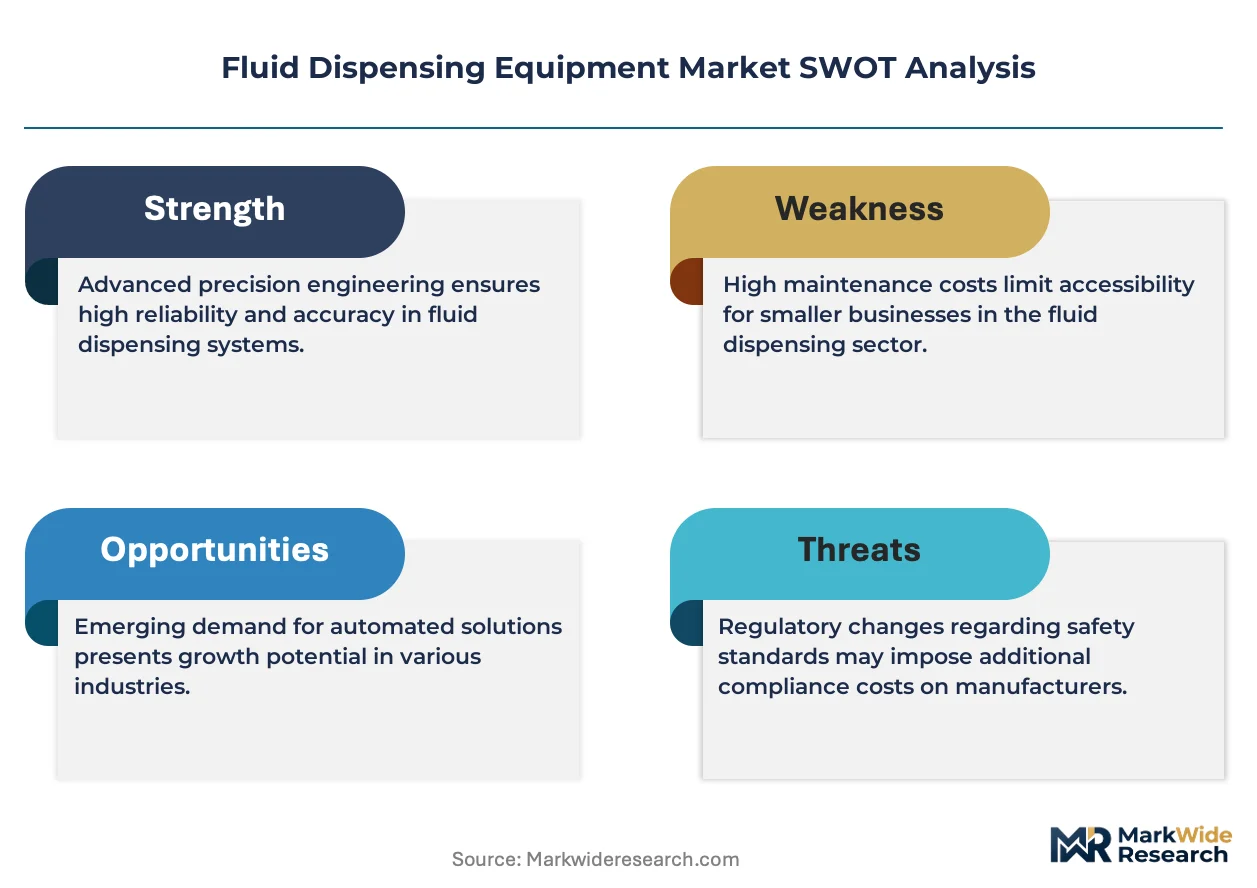
REACH compliance is realigning the cost-of-entry calculus for fluid dispensing equipment suppliers serving European automotive and electronics clients. Nordson Corporation leverages its precision valve technology to sustain premium positioning in automated assembly lines. Graco Inc. anchors its competitive stance through broad manufacturing scale across industrial coatings and sealant applications.
Fluid dispensing equipment encompasses electromechanical, pneumatic, handheld, and automated systems engineered to meter and deposit adhesives, sealants, lubricants, and other fluids with volumetric accuracy typically within one percent. These systems serve critical bonding, coating, and encapsulation functions across automotive powertrain assembly, semiconductor packaging, and pharmaceutical sterile filling operations. Pneumatic technology retains dominant installed base share in high-volume automotive plants where air-driven reliability offsets precision limitations. Automated systems represent the fastest-expanding technology segment as electronics manufacturers adopt vision-guided dispensing for micro-component placement. Dispensing pumps concentrate margin pools in cleanroom pharmaceutical applications where contamination control justifies premium pricing.
The EPA regulates volatile organic compound emissions from solvent-based dispensing processes in US manufacturing facilities, while OSHA sets exposure limits for isocyanate-containing adhesives common in polyurethane dispensing. The EU Green Deal accelerates demand for water-based and UV-curable fluid formulations that require compatible equipment retrofits. Stakeholders must monitor how dual carbon goals in China and carbon border adjustments in Europe reshape equipment specification standards and supplier qualification timelines.
Market Dynamics
Semiconductor packaging miniaturization is compressing dispensing tolerance requirements from microns to sub-micron precision, forcing equipment suppliers to rebuild motion control architectures around linear motor stages and vision feedback loops.
Growth Catalysts
- Automotive electrification:Battery module assembly lines in Germany and the US require thermal interface material dispensing for cell-to-cell bonding, pulling high-volume automated systems into EV manufacturing corridors.
- REACH substance restrictions:ECHA's tightening controls on hexavalent chromium and certain isocyanates in adhesive formulations are accelerating equipment replacement cycles as European manufacturers retool for compliant chemistries.
- AI-driven vision systems:Machine learning-based defect detection integrated into dispensing heads is reducing rework rates in semiconductor backend facilities across Taiwan and South Korea.
Market Restraints
- Precision component supply concentration:Linear encoders and ceramic dispensing nozzles rely heavily on Japanese and German specialty suppliers, creating vulnerability to single-source disruptions.
- Fluoropolymer feedstock volatility:PTFE-based seals and coatings face price instability tied to fluorspar mining concentration in China and Mexico, squeezing margin on high-purity pharmaceutical dispensing pumps.
- Pneumatic precision ceiling:Compressed air-driven systems cannot achieve the repeatability required for 01005 component underfill, capping their addressable market in advanced electronics packaging.
Strategic Opportunities
- Biologics sterile filling:Single-use fluid path technologies are opening demand from contract manufacturing organizations producing mRNA therapies and cell therapies in controlled environments.
- Water-based adhesive transition:The EU Green Deal's push for solvent reduction is creating retrofit demand for equipment compatible with higher-viscosity, waterborne formulations in automotive interiors.
- India electronics manufacturing:PLI scheme incentives for semiconductor and mobile device assembly are attracting dispensing equipment deployment into Gujarat and Tamil Nadu production zones.
Industry Challenges
- Mechatronics engineering scarcity:The intersection of precision fluid mechanics, motion control, and cleanroom protocols requires talent pools concentrated in southern Germany and coastal China, limiting expansion velocity.
- ISO 14644 cleanroom certification timelines:Pharmaceutical equipment qualification protocols now extend 18-24 months, delaying revenue recognition and tying up working capital in validation documentation.
- Legacy SCADA integration friction:Brownfield automotive plants running proprietary Allen-Bradley or Siemens architectures resist retrofitting modern dispensing cells without middleware layers that degrade real-time performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Dispensing Equipment Market |
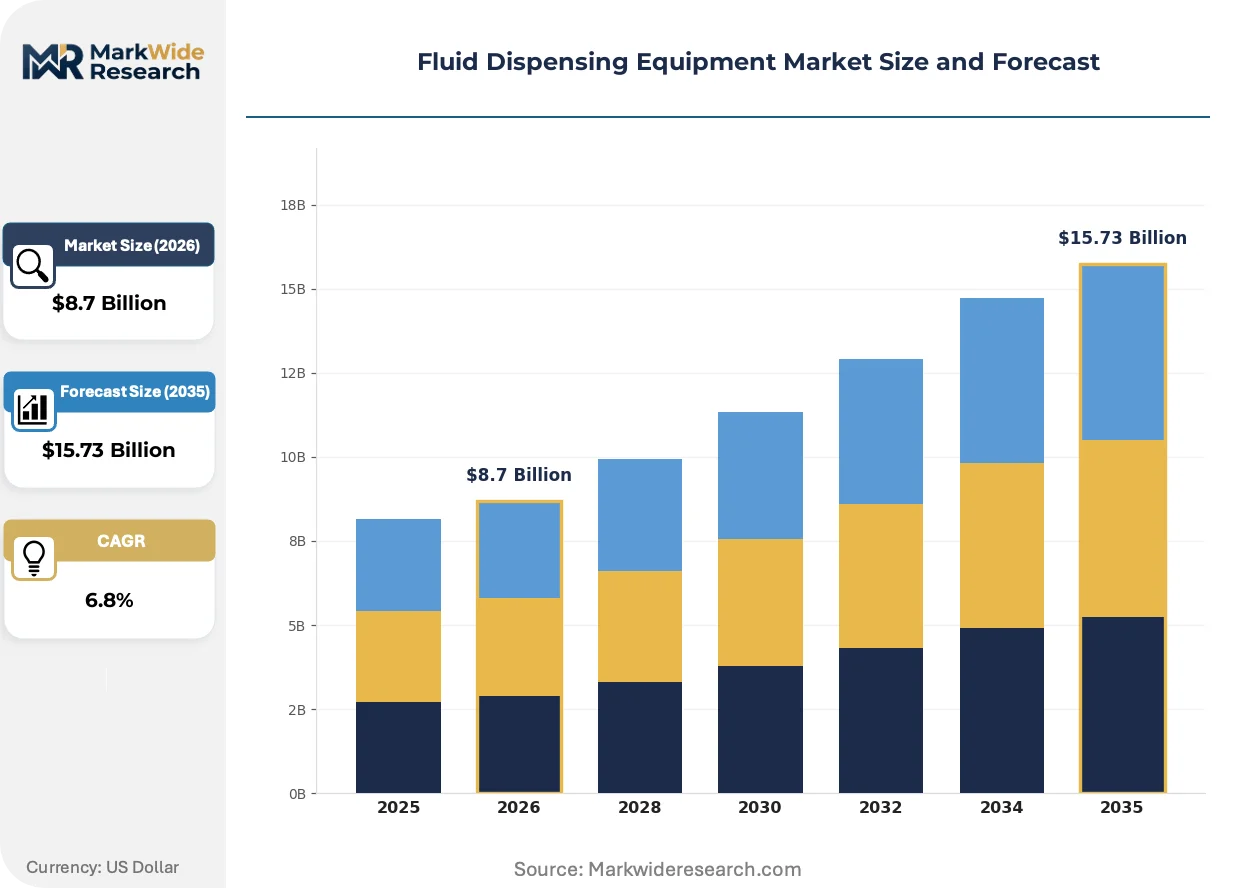
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispensing Pumps, Applicators, Syringes, Sprayers Technology: Electromechanical, Pneumatic, Handheld, Automated End User: Manufacturers, Retailers, Service Providers, Laboratories Application: Food & Beverage, Automotive, Pharmaceuticals, Cleanroom |
| Companies Covered | Nordson Corporation, Graco Inc., Henkel AG & Co. KGaA, Speedline Technologies, Musashi Engineering Inc., ITW Dynatec, GPD Global, Fisnar Inc., Dymax Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Dispensing Equipment Market Emerging Trajectories
Equipment architectures are converging around closed-loop process control, with sensor fusion and edge computing displacing open-loop pneumatic sequencing across precision manufacturing verticals.
Jet dispensing technology is absorbing the most demanding micro-electronics applications through piezoelectric actuation that ejects picoliter droplets without substrate contact. Korean memory manufacturers and Taiwanese OSATs are adopting these systems for stacked die underfill and copper pillar bumping. This precision tier is absorbing volume that previously required time-pressure or auger methods, compressing the viable specification range for legacy equipment.
REACH authorization requirements for SVHC substances are forcing adhesive formulators to eliminate bisphenol A and certain epoxy hardeners from electronics-grade products. Equipment suppliers must validate new material rheologies against existing pump and valve designs, often requiring hardware modifications to handle elevated viscosities or shortened pot lives. German automotive suppliers face the tightest compliance deadlines, accelerating their equipment refresh cycles relative to North American counterparts operating under less restrictive EPA frameworks.
Buyer consolidation among tier-one electronics contract manufacturers is concentrating procurement leverage and compressing approved vendor lists. Foxconn, Jabil, and similar scaled assemblers now mandate equipment-as-a-service arrangements with guaranteed uptime clauses, displacing traditional capital purchase models. This shift is most pronounced in Mexico and Vietnam, where greenfield facilities lack legacy equipment baggage and negotiate subscription-based deployment from inception.
Fluid Dispensing Equipment Market Segmentation
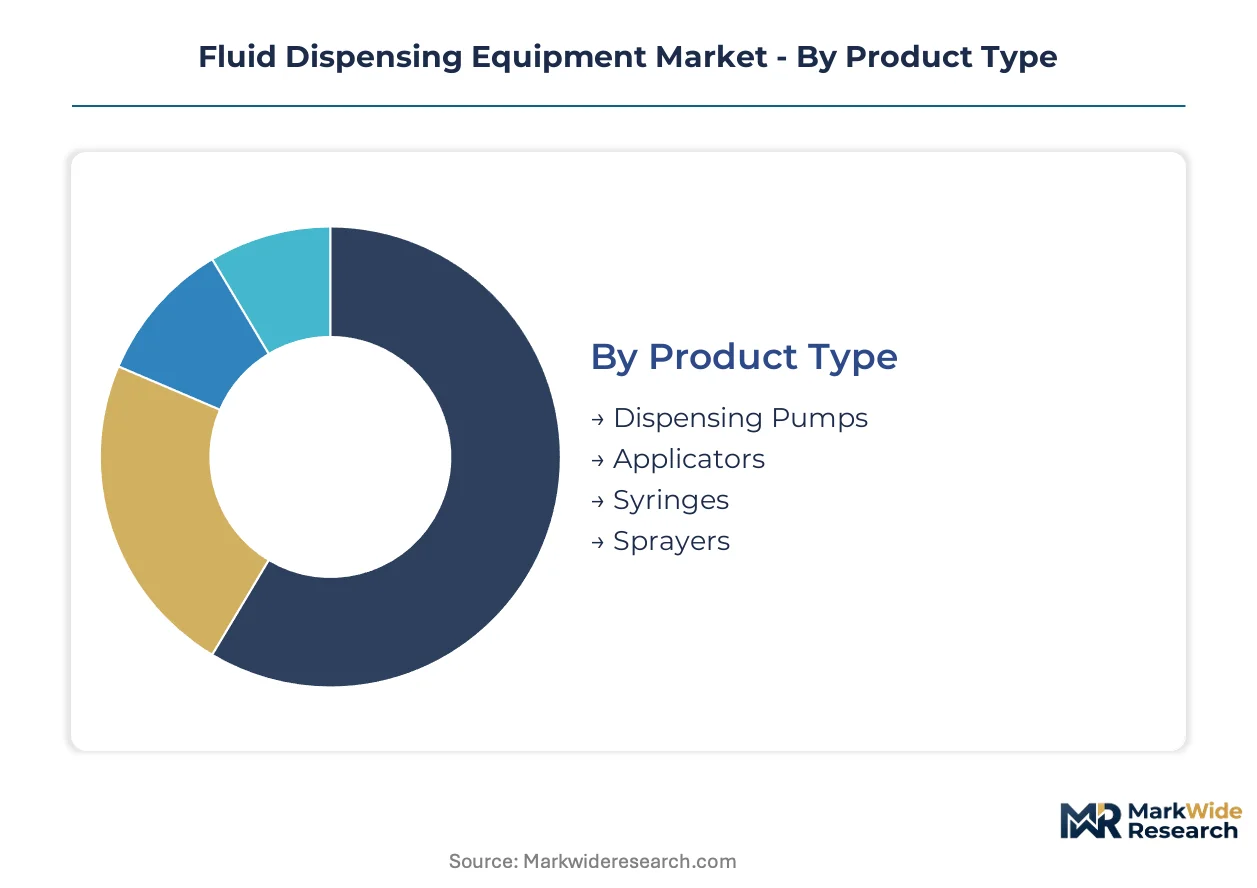
Segmentation in fluid dispensing equipment reveals how precision requirements, regulatory exposure, and automation intensity fragment procurement decisions across end-use verticals. Buyers prioritize different performance thresholds—volumetric accuracy, contamination control, or throughput speed—based on their production environment and compliance obligations.
Product Type:
Purchase decisions here hinge on fluid viscosity range and batch volume, with high-value applications demanding specialized architectures over general-purpose tools.
- Dispensing Pumps:Positive-displacement and peristaltic architectures dominate pharmaceutical sterile filling and semiconductor encapsulation where volumetric repeatability within one percent is mandatory. Cleanroom-validated pump systems command premium positioning in mRNA therapy manufacturing corridors across Germany and the United States.
- Applicators:Handheld and bench-mounted dispensing guns serve automotive seam sealing and electronics conformal coating with adjustable flow control for variable bead profiles. Mexican and Vietnamese electronics assembly plants favor pneumatic applicators for their capital efficiency in high-mix, medium-volume production.
- Syringes:Disposable barrel-and-plunger systems enable precise micro-deposition in medical device assembly and laboratory research settings.
- Sprayers:Atomizing nozzles distribute coatings and lubricants across large surface areas in industrial maintenance and food processing equipment.
Volume sits with dispensing pumps; growth tilts toward applicators as contract manufacturers in emerging electronics corridors prioritize flexible automation.
Technology:
Capital intensity and precision ceilings differentiate technology selection, with motion control sophistication determining addressable market tier.
- Automated:Vision-guided robotic cells with linear motor stages and real-time feedback loops execute sub-micron dispensing for advanced semiconductor packaging. Taiwanese OSATs and Korean memory manufacturers absorb these systems for stacked die underfill and copper pillar bumping applications.
- Electromechanical:Servo-driven screw pumps and jet valves deliver repeatable deposition without compressed air dependency, suiting cleanroom pharmaceutical operations where oil contamination risks are prohibitive.
- Pneumatic:Air-driven time-pressure systems retain cost advantage in high-volume automotive powertrain assembly where precision tolerances remain within pneumatic capability.
- Handheld:Manual dispensing tools serve prototyping, repair, and low-volume specialty manufacturing with minimal capital outlay.
Installed base concentrates in pneumatic systems; expansion concentrates in automated platforms as miniaturization demands outstrip legacy precision limits.
End User:
Procurement scale and technical specification authority separate end-user categories, with direct manufacturers wielding greatest customization leverage.
- Manufacturers:Tier-one automotive and electronics producers specify integrated dispensing cells with guaranteed uptime clauses and predictive maintenance integration. Foxconn and similar scaled assemblers increasingly mandate equipment-as-a-service arrangements over capital purchase.
- Service Providers:Contract manufacturing organizations demand rapid changeover capability and multi-material compatibility to serve diverse client portfolios.
- Retailers:Distributors and aftermarket suppliers stock consumables and replacement components for maintenance and repair operations.
- Laboratories:Research and quality control facilities prioritize precision over throughput for analytical and developmental applications.
Revenue gravity centers on manufacturers; fastest expansion emerges among service providers as biologics contract manufacturing scales.
Application:
Regulatory stringency and contamination risk stratify application segments, with pharmaceutical and cleanroom environments imposing the most demanding qualification protocols.
- Pharmaceuticals:Sterile filling of vials, syringes, and cartridges for biologics and vaccines requires ISO 14644-compliant equipment with single-use fluid path technologies. Extended validation timelines of 18-24 months delay revenue recognition but sustain premium pricing.
- Cleanroom:Semiconductor and electronics packaging operations demand particulate control and electrostatic discharge protection throughout dispensing processes.
- Automotive:Battery module assembly for electric vehicles pulls thermal interface material dispensing systems into German and US manufacturing corridors.
- Food & Beverage:Sanitary design standards govern equipment specification for edible oil, flavor, and additive dispensing with CIP/SIP compatibility.
Margin pools concentrate in pharmaceuticals; retrofit demand accelerates in automotive as electrification reshapes assembly processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor packaging corridors in East Asia absorb the highest equipment density, while automotive electrification pulls automated dispensing systems into German and US manufacturing zones. Regulatory divergence between REACH-compliant Europe and EPA-governed North America is fragmenting supplier qualification protocols.
China
MIIT's dual carbon goals are accelerating solvent-free adhesive transitions in Yangtze River Delta electronics plants. GB standards for cleanroom equipment are tightening validation requirements for pharmaceutical dispensing pump imports. Shenzhen and Suzhou semiconductor packaging clusters are scaling jet dispensing lines for advanced memory die stacking.
United States
OSHA isocyanate exposure limits are forcing polyurethane adhesive equipment retrofits across Michigan and Ohio automotive assembly plants. EPA volatile organic compound regulations are constraining solvent-based dispensing process expansions. Texas and Arizona battery gigafactories are pulling thermal interface material dispensing systems into EV supply chains.
Germany
ECHA REACH authorization deadlines for hexavalent chromium are compressing equipment replacement cycles in Baden-Württemberg automotive supplier networks. EU Green Deal solvent reduction targets are creating retrofit demand for water-based adhesive compatible systems. Bavarian pharmaceutical equipment manufacturers face 18-24 month ISO 14644 qualification timelines for biologics sterile filling exports.
South Korea
MFDS pharmaceutical manufacturing standards are elevating cleanroom equipment specifications for mRNA therapy production in Songdo and Osong bioclusters. METI-aligned precision motion control requirements are shaping semiconductor backend equipment procurement. Suwon and Pyeongtaek memory manufacturing zones are absorbing piezoelectric jet dispensing systems for copper pillar bumping.
India
PLI scheme incentives for semiconductor and mobile device assembly are attracting dispensing equipment deployment into Gujarat and Tamil Nadu production corridors. CDSCO pharmaceutical equipment validation protocols are extending supplier qualification timelines for sterile filling applications. BIS standards for industrial automation are harmonizing with ISO frameworks for contract manufacturing organization equipment sourcing.
Fluid Dispensing Equipment Market Vendor Landscape
German and Japanese producers anchor one tier; US specialists hold premium positioning in precision valve architectures. The vendor base stratifies across three tiers: diversified industrial conglomerates with broad coating and adhesive portfolios, precision automation specialists focused on semiconductor and pharmaceutical verticals, and regional fabricators serving automotive maintenance and repair channels. Competitive moves concentrate on equipment-as-a-service subscription models and AI-driven vision system integration partnerships.
Within the precision automation tier, Nordson Corporation and Graco Inc. exemplify divergent strategic positioning. Nordson occupies a position anchored in precision valve technology for automated assembly lines, while Graco represents scale-driven manufacturing breadth across industrial coatings and sealant applications. Musashi Engineering Inc. sits within the East Asian specialist archetype serving semiconductor backend facilities. These three entities collectively illustrate how geographic origin and portfolio focus fragment competitive positioning across automotive, electronics, and pharmaceutical end-use verticals.
| Leading Market Players |
|---|
| Nordson Corporation |
| Graco Inc. |
| Henkel AG & Co. KGaA |
| Speedline Technologies |
| Musashi Engineering Inc. |
| ITW Dynatec |
| GPD Global |
| Fisnar Inc. |
| Dymax Corporation |
| Others |
Supply Flow & Price Mechanics
EU Green Deal solvent reduction mandates gate qualified supply access and premium-tier pricing power for fluid dispensing equipment serving European automotive and electronics clients. Equipment suppliers must validate water-based adhesive compatibility through extended qualification protocols, compressing margin for non-compliant architectures while rewarding certified system providers with pricing leverage in German and French manufacturing corridors.
Pricing Analysis
Short lead-time premiums distinguish fluid dispensing equipment procurement, with German automotive suppliers paying substantial markups for ISO 14644-validated systems delivered within compressed validation windows. Three-tier pricing structure across premium, standard, and economy levels separates vision-guided automated cells from pneumatic applicators and handheld tools. Pricing pressure stems from Foxconn-led buyer consolidation mandating equipment-as-a-service subscriptions with uptime guarantees. Contract manufacturers exhibit highest price sensitivity; pharmaceutical sterile filling operations show least sensitivity due to contamination control imperatives.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific semiconductor corridors shapes total landed cost calculations for precision dispensing components. Manufacturing concentrates in Germany, Japan, and China, with linear encoders and ceramic nozzles drawing from Japanese and German specialty suppliers. Fluorspar feedstock volatility from Chinese and Mexican mining operations threatens PTFE seal pricing stability. Single-source vulnerability concentrates in ceramic dispensing nozzle fabrication. Distribution runs through tier-one electronics contract manufacturers and pharmaceutical OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluid dispensing equipment is becoming a vertical-integration race as suppliers pursue captive production of precision motion control components to escape Japanese and German encoder dependency. Control over linear motor stage manufacturing represents the decisive upstream lever.
For Market Incumbents: Cement dominance in semiconductor packaging corridors through backward integration into ceramic nozzle production, eliminating single-source vulnerability to Japanese suppliers. Acquire vision system software capabilities to defend against AI-native entrants threatening precision dispensing automation. ISO 14644 certification investment in Bavarian and Suzhou facilities locks out mid-tier competitors from pharmaceutical sterile filling procurement. For New Entrants and Emerging Players: REACH authorization deadlines in Germany open a window for compliant water-based adhesive equipment specialists to capture automotive interior retrofit demand. Target Gujarat and Tamil Nadu electronics manufacturing zones where PLI scheme incentives reduce incumbent brand stickiness. Lead with rapid deployment capability and subscription pricing to bypass capital purchase barriers among Vietnamese contract manufacturers. For Investors and Strategic Acquirers: Equipment-as-a-service contract signings at Foxconn and Jabil facilities are the leading indicator that recurring revenue models are achieving scale validation in electronics assembly. Five-to-ten year viability favors precision automation specialists with pharmaceutical cleanroom credentials over generalist industrial coating players. Monitor ECHA SVHC substance list expansion as the signal for accelerated European equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Motion Control | Captive linear encoder production reduces dependency on Japanese suppliers for semiconductor packaging equipment. |
| Equipment-as-a-Service Subscription Launch | Foxconn uptime guarantee contracts validate recurring revenue models in Mexican and Vietnamese greenfield facilities. |
| AI-Driven Vision System Partnership | Machine learning defect detection integration addresses sub-micron tolerance requirements in Korean memory manufacturing. |
| Water-Based Adhesive Compatibility Certification | EU Green Deal compliance unlocks automotive interior retrofit demand in Baden-Württemberg supplier networks. |
| Single-Use Fluid Path Technology Expansion | mRNA therapy manufacturing demand in German and US bioclusters sustains premium pricing for pharmaceutical pumps. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this fluid dispensing equipment analysis. Primary interviews with plant engineers at automotive powertrain facilities, procurement leads at semiconductor OSATs, regulatory affairs directors at pharmaceutical equipment manufacturers, and aftermarket service heads at industrial distributors combined with secondary validation. FDA 510(k) submissions, ECHA REACH authorization databases, MIIT equipment standards filings, and SEC 10-K disclosures provided bottom-up and top-down triangulation.
Segment-level granularity modeled technology adoption across automated, electromechanical, pneumatic, and handheld platforms; product type differentiation between dispensing pumps, applicators, syringes, and sprayers; and end-user procurement patterns among manufacturers, service providers, retailers, and laboratories. CAGRs derived from equipment shipment volumes cross-referenced against semiconductor packaging capacity expansion and automotive electrification capex disclosures. Jet dispensing adoption curves in Taiwanese and Korean memory facilities informed precision tier growth assumptions.
The model assumes a particular technology adoption path; alternative pathways for piezoelectric jet dispensing would alter the outlook if pneumatic systems achieve unexpected precision breakthroughs. Forecasts reflect assumptions regarding REACH substance restriction timelines, PLI scheme incentive durability, and fluorspar supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Global Vacuum Furnaces Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
South America Fans and Blowers Market
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
Actuators Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Industrial Refrigeration Systems Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Machine Mounts Market
Industrial Equipment
Global Integrated Drive Systems Market