
 Industrial Joysticks Market | 2026-2036
Industrial Joysticks Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Joysticks Market Analysis
Construction equipment is hardening as the dominant end-use vertical for industrial joysticks, displacing legacy manual lever systems in excavators and crane cabins. Bosch Rexroth leverages its hydraulic-electronic integration expertise to anchor premium positioning in European heavy machinery. CTI Electronics specializes in sealed, high-cycle joystick designs for marine and offshore environments. APEM competes through broad catalog breadth across analog and digital product lines.
An industrial joystick is a human-machine interface device that translates mechanical hand motion into electrical signals controlling machinery movement, typically rated for operational lifetimes exceeding five million cycles and sealed to IP65 or higher ingress protection standards. Its primary purpose is enabling precise, proportional control of heavy equipment in environments where direct mechanical linkage is impractical or unsafe. Hall Effect sensor technology leads the technology dimension due to contactless operation and immunity to dust contamination, while wireless joysticks represent the fastest-growing product type as OEMs eliminate cable maintenance in mobile equipment. The application dimension shows material handling maturing with standardized cabin layouts, whereas robotics applications concentrate margin pools through custom force-feedback specifications.
ISO 13849 machinery safety standards and IEC 61000 electromagnetic compatibility frameworks shape product design requirements, compelling manufacturers to validate redundant signal paths and shielding architectures. OSHA workplace safety regulations in the United States and CE marking obligations under EU machinery directives further condition market access and liability exposure. Stakeholders must monitor evolving functional safety integrity levels and wireless protocol certifications as determinants of competitive viability in next-generation equipment platforms.
Market Dynamics
Construction equipment OEMs are hardening joystick integration as the primary control interface, with ISO 13849 functional safety mandates and IEC 61000 electromagnetic compatibility standards tightening certification thresholds that filter supplier viability.
Growth Catalysts
- Electrification of mobile equipment:Battery-powered excavators and material handlers require electronic control architectures that replace mechanical linkages, pulling demand for sealed proportional joysticks rated to IP67.
- OSHA workplace safety enforcement:United States regulatory pressure on crane and lifting equipment operators is mandating redundant control systems with dual-channel signal paths, expanding specification requirements for safety-rated joysticks.
- Stuttgart-Munich automation cluster:German industrial machinery manufacturers are upgrading cabin ergonomics to attract skilled operators, specifying force-feedback joysticks with haptic response for precision earthmoving.
Market Restraints
- Rare earth magnet supply concentration:Hall Effect sensors depend on neodymium and dysprosium sourcing concentrated in Chinese processing facilities, creating input cost volatility and geopolitical exposure for joystick manufacturers.
- Functional safety certification timelines:ISO 13849 PLd validation requires 18-24 month third-party verification cycles that compress product launch windows and strain engineering budgets.
- Pneumatic control substitution:Compressed-air lever systems retain cost advantage in static industrial settings where environmental sealing is not required, limiting joystick penetration in legacy manufacturing lines.
Strategic Opportunities
- Indian infrastructure buildout:The country's PLI scheme for construction equipment manufacturing is attracting OEM assembly plants that will specify localized joystick supply chains to avoid import duties.
- Wireless protocol convergence:Integration of Bluetooth Low Energy with ISA100.11a industrial wireless standards is eliminating cable maintenance in mobile cranes and port handling equipment.
- EU Green Deal machinery retrofit mandates:Incentives for diesel-to-electric equipment conversion are creating aftermarket demand for electronic control retrofits in existing European construction fleets.
Industry Challenges
- Embedded firmware talent scarcity:Functional safety programming to IEC 61508 standards requires specialized engineers that joystick manufacturers compete to hire from automotive and aerospace sectors.
- Legacy hydraulic system integration:Proportional valve mapping between electronic joystick outputs and existing hydraulic architectures demands custom calibration protocols that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Joysticks Market |
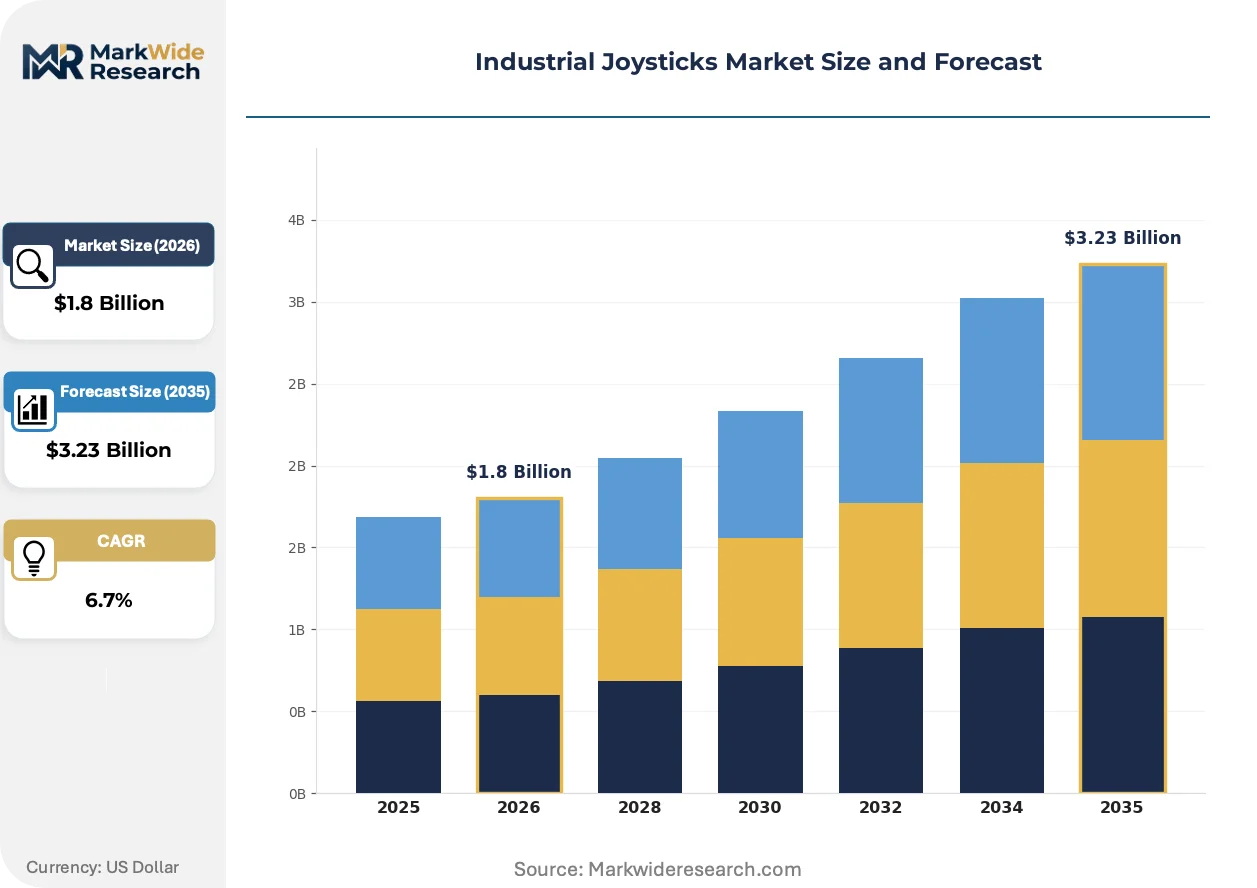
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Joysticks, Digital Joysticks, Wireless Joysticks, Touchscreen Joysticks Application: Robotics, Material Handling, Construction Equipment, Remote Control Vehicles End User: Manufacturing, Aerospace, Automotive, Defense Technology: Hall Effect Sensors, Potentiometer Technology, Capacitive Sensors, MEMS |
| Companies Covered | J.R. Merritt Controls, Spohn, APEM, Schneider Electric, Eaton, Bosch Rexroth, CTI Electronics, Danfoss, Curtiss-Wright, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Joysticks Market Emerging Trajectories
Sensor fusion and wireless connectivity are compressing the traditional divide between operator interface and machine control systems, enabling new architectures that reduce cabin wiring complexity while tightening response precision.
Hall Effect sensing with redundant magnetic arrays is automating fault detection in real-time operator inputs. Mining truck OEMs in Western Australia are specifying these contactless designs for 10-million-cycle durability in dust-choked environments. The technology is automating the elimination of mechanical wear points that previously drove scheduled maintenance intervals.
EU machinery directives under the CE marking framework now mandate documented risk assessments for control system failures. Manufacturers must validate single-fault tolerance in joystick signal paths to access European construction equipment supply chains. German component suppliers are responding by pre-certifying modular joystick platforms that OEMs can configure without repeating full validation cycles.
After-sales service unbundling is fragmenting traditional distribution relationships. Rental fleet operators in the United States are contracting directly with joystick specialists for field replacement programs, bypassing equipment dealers. This pattern concentrates in the material handling vertical where standardized cabin layouts enable plug-and-play component swaps without OEM technician involvement.
Industrial Joysticks Market Segmentation
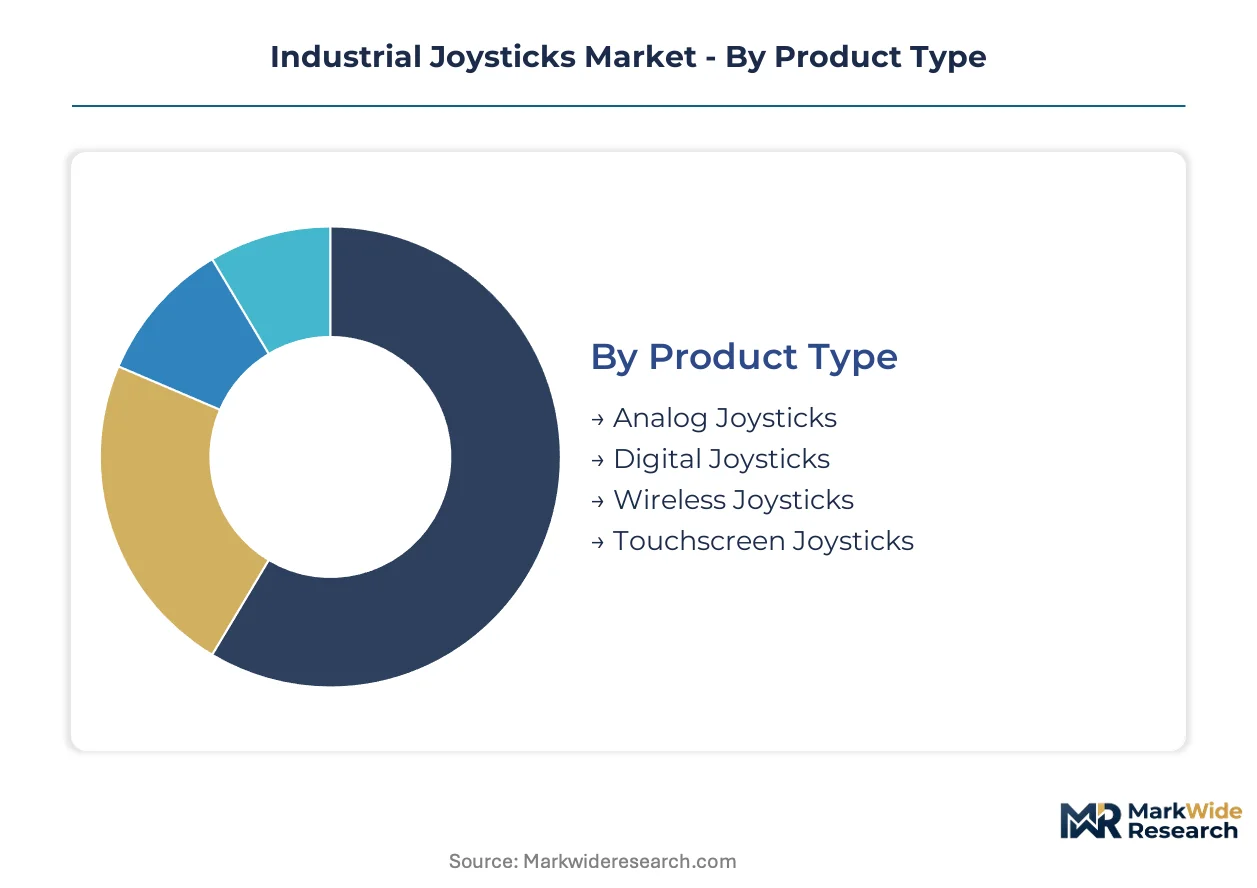
Equipment replacement cycles and cabin retrofit programs are reshaping demand patterns across industrial joystick categories. OEM specification upgrades and aftermarket service unbundling are concentrating procurement decisions around performance tier and wireless capability rather than legacy analog compatibility.
Product Type:
Retrofit-driven upgrades are accelerating as rental fleets and construction operators replace mechanical lever systems with electronic interfaces during scheduled equipment overhauls.
- Analog Joysticks:Resistive potentiometer-based signal generation dominates legacy equipment maintenance contracts. German earthmoving OEMs in the Stuttgart-Munich corridor specify these for backward compatibility with existing hydraulic valve amplifiers during phased fleet modernization.
- Digital Joysticks:CAN bus and SAE J1939 protocol integration enable direct machine controller communication without analog-to-digital conversion stages. Demand concentrates in material handling verticals where standardized cabin layouts support plug-and-play component swaps.
- Wireless Joysticks:Bluetooth Low Energy and ISA100.11a industrial wireless protocols eliminate cable maintenance in port cranes and mobile elevating work platforms.
- Touchscreen Joysticks:Haptic force-feedback integration targets robotics applications requiring programmable resistance curves for delicate manipulation tasks.
Analog joysticks sit at the top of the volume ranking, with wireless joysticks climbing the fastest as port handling and mining equipment OEMs eliminate cable fatigue failures.
Application:
Margin pools concentrate where custom force-feedback specifications and extended operational lifecycles justify premium component sourcing over catalog-standard alternatives.
- Robotics:Six-axis force-torque sensing and programmable impedance control enable collaborative robot programming by demonstration. Automotive assembly lines in Germany and Japan specify these for ergonomic workstation retrofit programs.
- Material Handling:Standardized cabin layouts across forklift and reach truck platforms enable aftermarket service unbundling. Rental fleet operators in the United States contract directly with joystick specialists for field replacement programs bypassing equipment dealers.
- Construction Equipment:ISO 13849 PLd functional safety mandates require redundant signal paths in excavator and crane control systems.
- Remote Control Vehicles:Mining truck OEMs in Western Australia specify sealed designs rated for 10-million-cycle durability in dust-choked environments.
Construction equipment commands the largest installed base, with robotics gaining share fastest through collaborative automation deployments in automotive and electronics manufacturing.
End User:
Defense and aerospace procurement patterns favor dual-source qualification requirements that extend supplier validation timelines but lock in multi-year production commitments.
- Manufacturing:Factory automation retrofits and new line installations drive standardized proportional control specifications across metalworking and plastics processing machinery.
- Aerospace:DO-160G environmental qualification and MIL-STD-810 shock resistance requirements filter supplier viability for ground support equipment and flightline tow vehicles.
- Automotive:Assembly line collaborative robot deployments concentrate demand for force-feedback programmable interfaces.
- Defense:Single-fault-tolerant architectures and TEMPEST electromagnetic shielding specifications apply to battlefield construction and materials handling equipment.
Manufacturing absorbs the highest unit volumes, with aerospace expanding most quickly through ground support equipment modernization programs at major international hub airports.
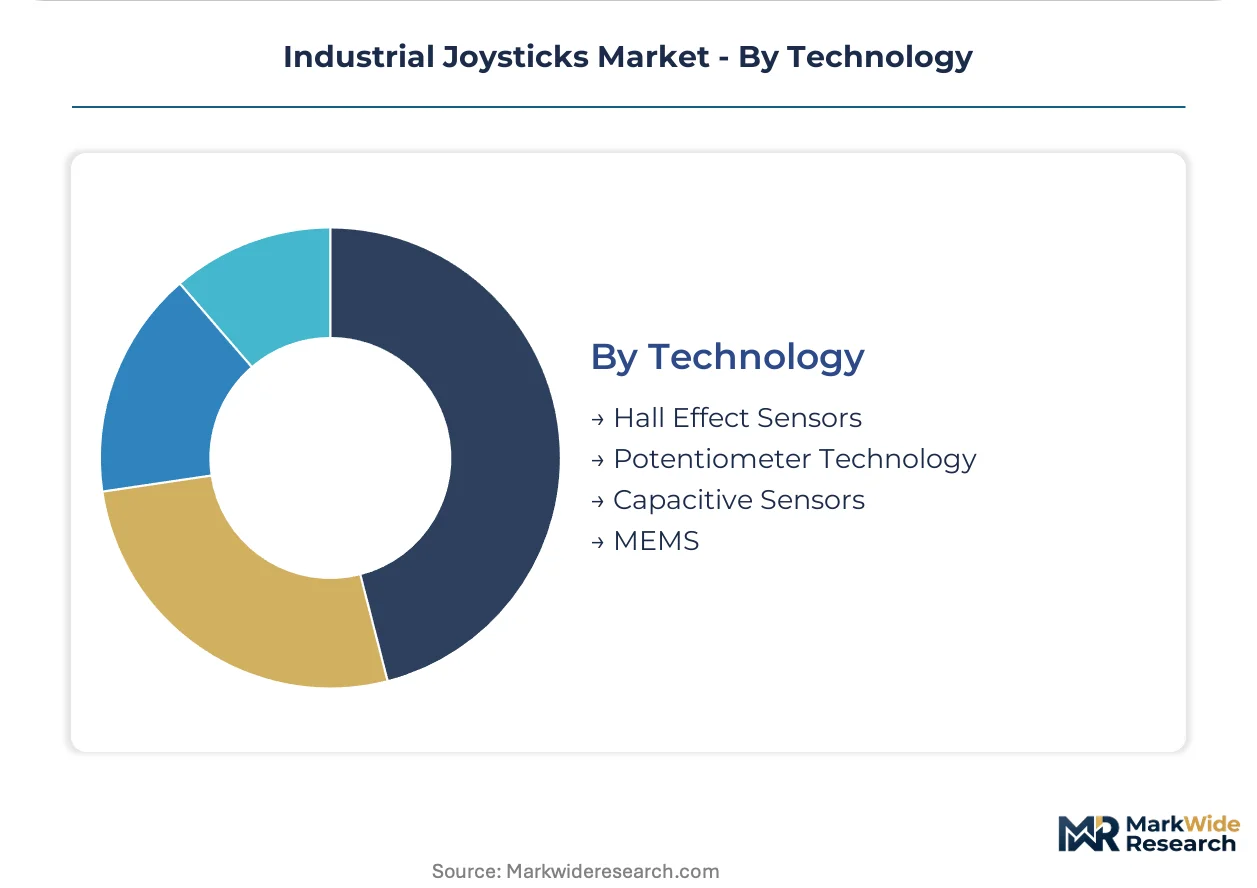
Technology:
Supply concentration in Chinese rare earth processing facilities creates input cost volatility for contactless magnetic sensing technologies dependent on neodymium and dysprosium.
- Hall Effect Sensors:Contactless magnetic field detection eliminates mechanical wear points and provides immunity to dust contamination. Mining and construction OEMs specify redundant magnetic arrays for 10-million-cycle durability in unsealed environments.
- Potentiometer Technology:Carbon film and conductive plastic resistance elements dominate cost-sensitive replacement part markets where operational lifecycle is shorter than mean-time-between-failure requirements.
- Capacitive Sensors:Non-contact position detection enables sealed designs for marine and offshore environments without dynamic seal wear.
- MEMS:Microelectromechanical accelerometer and gyroscope integration enables inertial reference for stabilized platform control in aerial work platforms and marine cranes.
Hall Effect sensors lead the technology ranking by revenue, with MEMS gaining share fastest through stabilization and active damping applications in elevating work platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling joystick manufacturing toward jurisdictions where ISO 13849 certification costs compress against EU machinery directive enforcement. German and US specification requirements filter supplier viability while Indian and Southeast Asian assembly plants absorb volume production under localized content rules.
Germany
Stuttgart and Munich automation clusters drive specification upgrades for force-feedback joysticks in precision earthmoving equipment. CE marking obligations under EU machinery directives mandate documented risk assessments for control system failures. Baden-Württemberg OEMs are pre-certifying modular joystick platforms to compress third-party validation cycles.
United States
OSHA workplace safety enforcement on crane and lifting equipment mandates redundant control systems with dual-channel signal paths. Rental fleet operators in the Midwest and Southeast contract directly with joystick specialists for field replacement programs. Texas and Illinois construction equipment distributors bypass traditional dealer networks for aftermarket component sourcing.
China
Rare earth magnet processing concentration in Jiangxi and Inner Mongolia creates input cost leverage for Hall Effect sensor manufacturers. GB standards alignment with IEC 61000 electromagnetic compatibility frameworks conditions export market access. Yangtze River Delta industrial zones are consolidating joystick assembly for domestic construction equipment OEMs.
India
The PLI scheme for construction equipment manufacturing attracts OEM assembly plants specifying localized joystick supply chains. DGFT import duty structures favor domestic component sourcing over European and East Asian imports. Gujarat and Maharashtra industrial corridors are developing sealed proportional joystick production for excavator and material handler integration.
Japan
METI industrial automation roadmaps prioritize collaborative robot deployments requiring programmable force-feedback interfaces. JIS standards alignment with ISO 13849 functional safety requirements conditions supplier qualification timelines. Kansai region automotive assembly lines specify haptic response joysticks for ergonomic workstation retrofit programs.
Industrial Joysticks Market Vendor Landscape
Pre-certification of modular joystick platforms dominates the current landscape as German suppliers compress OEM validation cycles. The vendor base stratifies across hydraulic-electronic integration specialists, sealed-environment fabricators, and broad-catalog component houses. Three archetypes anchor competitive positioning: precision earthmoving integrators, marine/offshore sealing specialists, and digital protocol standardizers. Technology licensing and backward integration into sensor manufacturing represent the dominant competitive moves.
Among European-based precision integrators, Bosch Rexroth occupies a position exemplifying hydraulic-electronic convergence for heavy machinery applications. CTI Electronics represents the sealed-environment archetype with high-cycle durability specifications for marine and offshore deployments. APEM anchors the broad-catalog tier across analog and digital product lines, serving standardized cabin layouts in material handling verticals.
| Leading Market Players |
|---|
| J.R. Merritt Controls |
| Spohn |
| APEM |
| Schneider Electric |
| Eaton |
| Bosch Rexroth |
| CTI Electronics |
| Danfoss |
| Curtiss-Wright |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between ISO 13849 PLd-validated platforms and commodity analog replacements splits pricing power across German precision integrators and Asian volume assemblers. This tier divergence channels procurement decisions through Stuttgart-Munich automation clusters for force-feedback specifications while compressing margins on standard potentiometer units sourced under India's PLI localization mandates.
Pricing Analysis
Distributor markup layers of 18-25% separate OEM direct contracts from aftermarket channel sales in construction equipment verticals. Three-tier pricing structure across premium Hall Effect arrays, mid-grade digital CAN bus interfaces, and economy analog potentiometer replacements reflects certification burden and cycle-life guarantees. Cost compression in standard-grade units intensifies as Chinese rare earth processors leverage neodymium supply control. Rental fleet operators exhibit highest price sensitivity, while mining OEMs in Western Australia absorb premium positioning for 10-million-cycle durability ratings.
Supply Chain Analysis
India's PLI scheme for construction equipment manufacturing and China's GB standards alignment mandates are pulling assembly capacity toward domestic-content-compliant jurisdictions. Neodymium and dysprosium sourcing concentrates in Jiangxi and Inner Mongolia processing facilities, while potentiometer carbon film production anchors in Japan and Germany. Single-source vulnerability in rare earth magnet supply creates input cost volatility for contactless sensor manufacturers. Distribution runs through equipment OEM procurement teams for new-build specifications and direct specialist contracts for aftermarket replacement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratcheting, with ISO 13849 functional safety mandates and IEC 61000 electromagnetic compatibility frameworks expanding addressable specification requirements across European and North American equipment platforms.
For Market Incumbents: Cement pre-certification advantages by modularizing joystick platforms that OEMs configure without repeating full PLd validation cycles. Deepen backward integration into Hall Effect sensor manufacturing to offset rare earth cost volatility from Chinese processors. Lock in multi-year supply agreements with Stuttgart-Munich automation clusters before Indian PLI localization matures.
For New Entrants and Emerging Players: Launch via direct aftermarket service contracts with US rental fleet operators bypassing established dealer networks. Target wireless joystick retrofit programs in port handling and mobile elevating work platforms where cable fatigue failures drive replacement demand. Penetrate through ISA100.11a industrial wireless protocol specialization as OEMs eliminate cabin wiring complexity.
For Investors and Strategic Acquirers: Asymmetric upside sits with sealed-environment fabricators holding marine and offshore qualifications that filter competitor entry. Five-to-ten year viability favors suppliers with captive rare earth magnet sourcing or alternative capacitive sensing architectures. Watch for GB standards alignment completion as the signal indicating Chinese domestic OEM specification capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Pre-Certification | Compresses OEM validation cycles under ISO 13849 PLd requirements. |
| Hall Effect Sensor Backward Integration | Captures neodymium supply chain leverage against Chinese processor concentration. |
| Wireless Protocol Specialization | Positions for ISA100.11a and Bluetooth Low Energy convergence in port equipment. |
| Indian PLI Localization | Secures domestic content compliance for excavator and material handler OEM assembly. |
| Force-Feedback R&D Investment | Targets German automotive ergonomic retrofit programs and collaborative robot deployments. |
Methodological Framework
Bottom-up construction equipment and robotics application modeling reconciled against top-down sensor technology and regional production tracking forms the analytical core of this study. Primary interviews with OEM procurement teams, aftermarket service directors, plant engineers at rental fleet operators, and Hall Effect sensor manufacturing specialists combined with secondary validation from SEC filings of listed industrial component suppliers, customs trade data for rare earth magnet flows, ISO certification registry databases, and EU machinery directive implementation reports. Triangulation across these sources calibrated volume estimates and pricing tier distributions.
Historical trendline analysis of replacement cycle patterns and cabin retrofit penetration rates anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, application vertical, end-user industry, and technology sensor architecture, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs derived from equipment production forecasts, electrification adoption curves, and functional safety mandate phase-in schedules. Industry-specific inputs incorporated OEM specification upgrade timelines and rental fleet age distributions.
Several conditions sit outside the modeled scope, including geopolitical disruption to rare earth supply chains, accelerated pneumatic control substitution in static industrial settings, and wireless protocol standard fragmentation beyond ISA100.11a and Bluetooth Low Energy convergence. Forecasts reflect assumptions about regulatory enforcement consistency and OEM electrification commitment durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Global Integrated Drive Systems Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Europe Tempered Glass Cutting Machine Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Actuators Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Vertical Centrifugal Separator Market
Industrial Equipment
Laser Cleaning Market
Industrial Equipment
Global Servo Presses Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Global Temperature Control Units (TCU) Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Global Cryostat Market