
 Global Integrated Drive Systems Market | 2026-2036
Global Integrated Drive Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Integrated Drive Systems Market Intelligence
Silicon carbide power modules are realigning cost structures across integrated drive architectures by cutting switching losses and shrinking thermal management footprints. Siemens AG leverages captive semiconductor sourcing to secure supply continuity for high-frequency inverter platforms. Bosch Rexroth AG anchors its position through deep backward integration into linear motion and drive electronics. Yaskawa Electric Corporation dominates precision servo applications in Asian machine tool supply chains.
An integrated drive system combines motor, inverter, gearbox, and control electronics into a unified electromechanical unit engineered for coordinated torque, speed, and position regulation, typically achieving positional accuracy below one arcminute in servo configurations. The assembly serves to eliminate mechanical couplings, reduce cabinet footprint, and synchronize multi-axis motion through embedded fieldbus or real-time Ethernet protocols. Servo drives and vector drives command the dominant share of product value, reflecting their penetration in applications requiring dynamic load response and regenerative energy handling. Ethernet/IP and fieldbus architectures remain the prevailing connectivity layers, though migration toward single-cable servo solutions is redistributing engineering investment across OEM and Tier-1 Supplier channels.
The US Department of Energy enforces minimum efficiency standards through NHTSA-aligned industrial motor rules, while the EU Green Deal and Ecodesign directives mandate regenerative capability and loss reduction in new drive installations. China's GB standards and dual carbon goals impose parallel efficiency tiers on domestic and imported equipment. Stakeholders must weigh regional certification divergence against platform standardization economics when configuring global product portfolios.
Market Dynamics
Silicon carbide power modules are compressing thermal footprints and switching losses across integrated drive architectures, forcing incumbents to reconfigure inverter platforms or cede share to semiconductor-integrated specialists.
Growth Catalysts
- EU Ecodesign Directives:Mandates on regenerative capability and loss reduction in new drive installations are accelerating retrofit cycles across German automotive component factories and Italian packaging machinery OEMs.
- Packaging Equipment Lines:OEMs pursuing tighter motion control integration are specifying embedded servo drives with single-cable encoder feedback, consolidating cabinet space and commissioning time.
- Japanese Precision Machinery Clusters:Concentrated demand from machine tool builders in Aichi and Kanagawa prefectures is pulling high-frequency inverter platforms through specialized distribution channels.
Market Restraints
- Silicon Carbide Substrate Concentration:Wafer supply concentrates among a handful of substrate growers, exposing inverter OEMs to allocation risk during capacity ramps.
- IEC Energy-Efficiency Certification Friction:Divergent testing protocols between IEC 60034-30-1 and regional implementations create redundant compliance costs for global platform strategies.
- Linear Motion Backward Integration:Captive production of ball screws and rack-and-pinion systems by major drive suppliers limits third-party component vendors to price-competitive, lower-specification niches.
Strategic Opportunities
- India Machine Tool Retrofit:Underpenetrated installed base of conventional induction motor drives presents white space for integrated servo replacements as BIS efficiency tiers tighten.
- Single-Cable Servo Convergence:Integration of power and feedback into hybrid cables is redistributing engineering investment toward connector and cable specialists.
- US IRA Industrial Efficiency Credits:Tax incentives for equipment upgrades are compressing payback calculations for regenerative drive installations in metal stamping and material handling.
Industry Challenges
- Multi-Axis Synchronization Expertise:Shortage of engineers fluent in real-time Ethernet protocols and motion control tuning is extending commissioning timelines for complex packaging lines.
- Legacy Fieldbus Integration:Migrations from DeviceNet and Profibus to EtherCAT and PROFINET require middleware gateways that add latency and points of failure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Integrated Drive Systems Market |
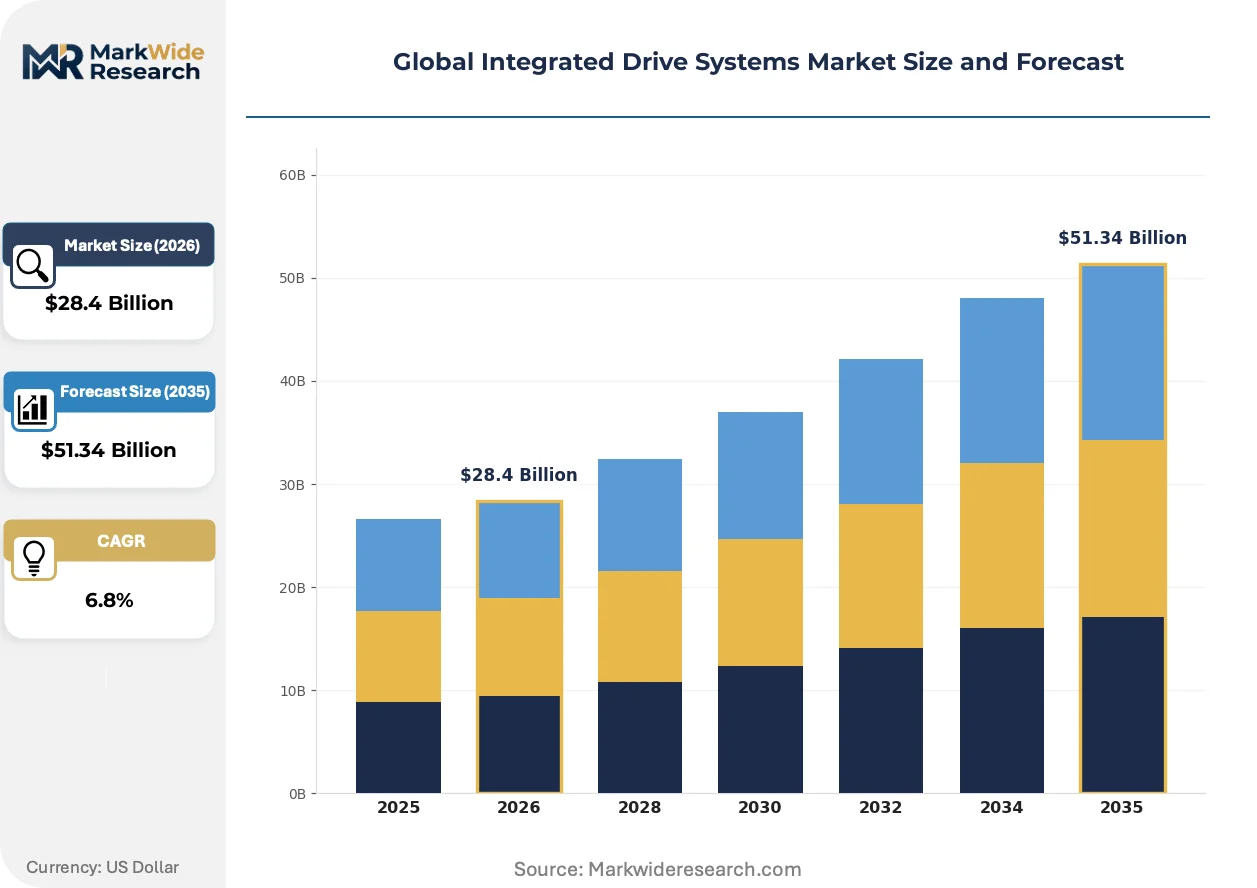
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servo Drives, Frequency Inverters, Stepper Drives, Vector Drives, Analog Drives Technology: Fieldbus, Ethernet/IP, CANopen, Profibus, Modbus, DeviceNet Application: Material Handling, Textile Machinery, Machine Tools, Packaging Equipment, Printing Machines End User: OEMs, Tier-1 Suppliers, Contract Manufacturers, Machinery Fabricators |
| Companies Covered | Siemens AG, ABB Ltd., Schneider Electric SE, Rockwell Automation, Inc., Bosch Rexroth AG, Mitsubishi Electric Corporation, Yaskawa Electric Corporation, Emerson Electric Co., TQ Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Integrated Drive Systems Market Strategic Shifts & Innovations
Power semiconductor materials, regulatory efficiency mandates, and procurement model compression are simultaneously reshaping product architecture, certification requirements, and channel economics across integrated drive supply chains.
Silicon carbide MOSFETs are absorbing switching losses previously dissipated through bulky heatsinks and forced-air cooling systems. Packaging machinery OEMs in Germany and Japan are specifying SiC-based inverters for multi-axis servo clusters where cabinet space commands premium pricing. The technology is absorbing thermal management component value into the power module itself, collapsing bill-of-material differentiation among inverter suppliers.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are pressuring drive manufacturers to eliminate PFAS-containing cooling fluids and potting compounds from high-power designs. Industrial motor and drive OEMs must reformulate thermal interface materials and sealing solutions to maintain IP ratings without restricted chemistry. German metalworking plant operators are prioritizing suppliers with verified substance compliance to avoid production line certification delays.
Machine builders are compressing supplier panels and consolidating motion control procurement around integrated drive specialists capable of delivering coordinated torque, speed, and position regulation from a single specification interface. Traditional motor-and-drive distributor networks are losing specification influence as OEM engineering teams engage directly with integrated platform vendors for application-optimized configurations. Japanese precision machinery clusters exhibit the most concentrated procurement consolidation, with Tier-1 machine tool builders reducing qualified supplier lists to three or fewer integrated drive partners.
Global Integrated Drive Systems Market Segmentation
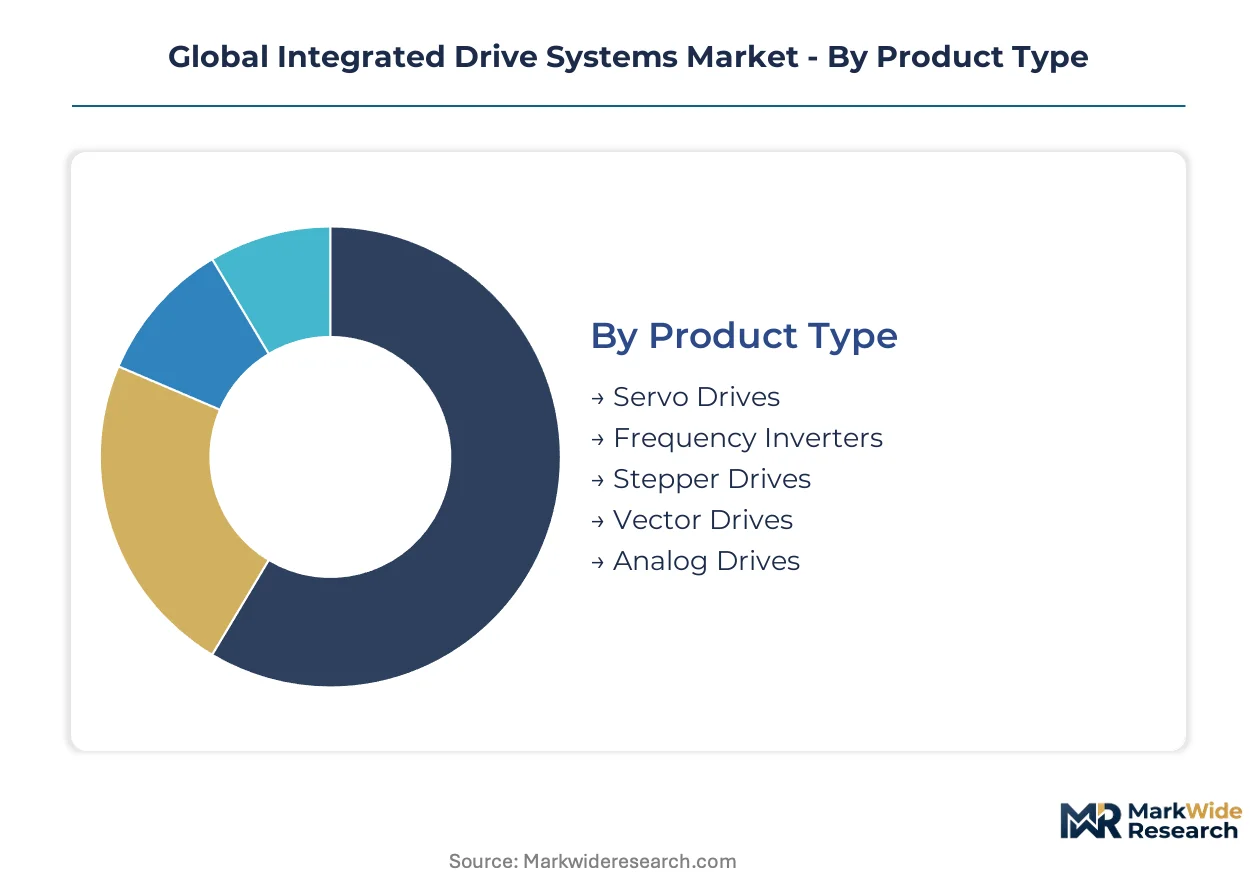
Integrated drive systems fragment across multiple technical and commercial dimensions. Product architecture determines thermal performance and positional accuracy. Connectivity protocols govern real-time synchronization capabilities. Application specificity shapes torque profiles and duty cycles. Procurement channel dictates engineering engagement depth and aftermarket service requirements.
Product Type:
Buyers differentiate by dynamic load response requirements and regenerative energy handling capacity.
- Servo Drives:Closed-loop systems achieve positional accuracy below one arcminute through embedded encoder feedback. German automotive component factories and Japanese precision machinery clusters in Aichi Prefecture specify these for multi-axis coordination where synchronization errors halt production lines.
- Vector Drives:Induction motor control with torque regulation independent of speed enables constant-tension winding and high-inertia positioning. Italian packaging machinery OEMs deploy these for material handling conveyors requiring smooth acceleration profiles under varying load conditions.
- Frequency Inverters:Variable-speed control for standard AC motors dominates retrofit installations where servo precision exceeds application requirements.
- Stepper Drives:Open-loop positioning systems serve cost-sensitive indexing applications with fixed step resolutions.
- Analog Drives:Legacy voltage-controlled units persist in installed base maintenance but face displacement by digital fieldbus alternatives.
Volume sits with Vector Drives; growth tilts toward Servo Drives.
Technology:
Connectivity selection hinges on determinism requirements and legacy infrastructure compatibility.
- Ethernet/IP:Industrial Ethernet protocol delivers deterministic motion control through CIP Sync time synchronization. US metal stamping plants prioritize this standard for integration with Rockwell Automation control architectures and IRA-funded efficiency upgrades.
- Fieldbus:Proprietary deterministic networks including Profibus-DP and DeviceNet retain installed base presence. German metalworking plants face migration pressure as EU Ecodesign directives mandate regenerative capability incompatible with legacy fieldbus power architectures.
- CANopen:Lightweight protocol dominates compact servo systems in European packaging machinery where node count exceeds 64 devices.
- Profibus:Process-fieldbus standard persists in process automation hybrids but loses share to Ethernet-based successors in discrete manufacturing.
- Modbus:Simple master-slave protocol serves cost-optimized applications with low real-time demands.
- DeviceNet:CAN-based network faces obsolescence as ODVA membership consolidates around Ethernet/IP and EtherNet/IP variants.
Installed base concentrates in Fieldbus; expansion concentrates in Ethernet/IP.
Application:
Motion complexity and axis count determine integrated drive specification intensity.
- Packaging Equipment:Multi-axis servo clusters coordinate forming, filling, and sealing operations through single-cable encoder feedback. German and Japanese OEMs specify embedded drives to compress cabinet footprint and commissioning time.
- Machine Tools:Spindle and axis drives demand sub-micron positioning with regenerative braking for energy recovery. Japanese precision machinery clusters in Kanagawa Prefecture pull high-frequency inverter platforms through specialized distribution.
- Material Handling:Conveyor and crane applications prioritize vector control for high-inertia acceleration.
- Textile Machinery:Winding and tensioning drives require constant torque regulation across speed ranges.
- Printing Machines:Register control and web handling specify precision servo synchronization.
Revenue concentrates in Machine Tools; fastest share gain occurs in Packaging Equipment.
End User:
Engineering integration depth separates procurement behaviors across the value chain.
- OEMs:Original equipment manufacturers engage integrated drive specialists directly for application-optimized configurations. Japanese machine tool builders have reduced qualified supplier lists to three or fewer partners, consolidating motion control procurement.
- Tier-1 Suppliers:Subsystem integrators specify drives for automotive component manufacturing lines where NHTSA-aligned efficiency rules apply.
- Contract Manufacturers:Build-to-print operators accept customer-specified drive architectures with limited configuration autonomy.
- Machinery Fabricators:Small-batch builders prioritize distributor availability and standard product configurations over application engineering.
Specification authority rests with OEMs; contract volume expands fastest among Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in German automotive component factories, Japanese precision machinery clusters, and US metal stamping plants retrofitting for IRA compliance. Regulatory divergence across IEC, NHTSA-aligned rules, and EU Ecodesign directives fragments certification pathways. Industrial clusters in Aichi, Kanagawa, and Bavaria pull high-specification servo platforms through specialized channels.
Germany
Automotive component factories in Bavaria and Baden-Württemberg specify embedded servo drives for multi-axis coordination. EU Ecodesign directives mandate regenerative capability and loss reduction in new installations. Metalworking plants in Stuttgart and Munich prioritize suppliers with verified REACH substance compliance to avoid certification delays.
Japan
Machine tool builders in Aichi and Kanagawa prefectures pull high-frequency inverter platforms through specialized distribution. METI efficiency standards and JIS certification requirements filter supplier qualification. Precision machinery clusters in Nagoya and Yokohama have consolidated qualified supplier lists to three or fewer integrated drive partners.
United States
Metal stamping plants and material handling operations retrofit drives to capture IRA industrial efficiency credits. NHTSA-aligned industrial motor rules enforce minimum efficiency standards through Department of Energy oversight. Midwest manufacturing corridors in Michigan and Ohio compress payback calculations for regenerative installations.
China
GB standards and dual carbon goals impose parallel efficiency tiers on domestic and imported equipment. MIIT regulations accelerate displacement of conventional induction motor drives in coastal manufacturing zones. Yangtze River Delta machinery builders specify integrated servo replacements as BIS-aligned efficiency benchmarks tighten procurement.
India
Underpenetrated installed base of conventional drives presents white space for integrated servo replacements. BIS efficiency tiers tighten compliance requirements for industrial motor installations. Machine tool retrofit demand concentrates in Maharashtra and Gujarat as fabricators upgrade for export competitiveness.
Global Integrated Drive Systems Market Key Industry Players
Backward integration into power semiconductors and linear motion components dominates the current landscape as incumbents defend margin positions against semiconductor-integrated specialists. The vendor base stratifies across three tiers: diversified industrial conglomerates with captive semiconductor sourcing, motion control specialists with deep mechanical integration, and emerging power electronics firms leveraging SiC substrate advantages. Two competitive moves define current positioning: captive production of ball screws and rack-and-pinion systems to lock in specification authority, and direct OEM engineering engagement to bypass traditional distributor networks.
Within the diversified industrial tier, Siemens AG and Bosch Rexroth AG exemplify archetypes of backward integration into drive electronics and linear motion respectively. Yaskawa Electric Corporation anchors the precision servo specialist position across Asian machine tool supply chains. These three entities represent contrasting strategic postures—captive semiconductor security, mechanical-electrical fusion, and regional channel dominance—without implying specific market share or financial performance.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Schneider Electric SE |
| Rockwell Automation, Inc. |
| Bosch Rexroth AG |
| Mitsubishi Electric Corporation |
| Yaskawa Electric Corporation |
| Emerson Electric Co. |
| TQ Group GmbH |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists in German and Japanese industrial clusters anchor supply continuity through in-house production of ball screws and linear motion components, translating captive manufacturing depth into pricing discipline that resists commoditization pressure from semiconductor-integrated entrants.
Pricing Analysis
Volume concentrates in vector drives while margin tilts toward servo configurations. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified regenerative platforms from basic induction motor retrofits. Pricing pressure stems from silicon carbide substrate allocation constraints compressing inverter OEM margins. Contract manufacturers exhibit highest price sensitivity; Japanese precision machinery clusters prioritize specification authority over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle specification-intensive demand from German automotive component factories and Japanese machine tool builders. Silicon carbide wafers draw from US, Japanese, and German substrate growers; rare earth magnets for high-torque motors rest on Chinese processing concentration. Single-source vulnerability in SiC epitaxy equipment exposes inverter platforms to allocation risk. Distribution runs through specialized motion control integrators with embedded engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a vertical-integration race where captive semiconductor sourcing and linear motion backward integration determine margin defense against SiC-native power electronics specialists.
For Market Incumbents: Extend specification authority by deepening backward integration into encoder feedback systems and thermal interface materials. Lock in OEM engineering relationships through direct application support teams that bypass traditional distributor networks. Counter semiconductor-integrated entrants by emphasizing motion control tuning expertise and multi-axis synchronization capabilities that require decades of accumulated know-how. For New Entrants and Emerging Players: Specialized cable and connector manufacturers represent the most penetrable channel partner type for single-cable servo convergence. Target Indian machine tool retrofit demand in Maharashtra and Gujarat where BIS efficiency tier enforcement creates replacement urgency. Pursue white-space positioning through SiC-based inverter platforms that absorb thermal management value into power modules, collapsing incumbent BOM differentiation. For Investors and Strategic Acquirers: Distressed-cycle entries favor motion control software specialists with real-time Ethernet protocol expertise in German and Japanese industrial clusters. Five-to-ten year viability hinges on regulatory efficiency mandates hardening into procurement requirements rather than optional certifications. Watch for IEC certification friction resolving into harmonized testing protocols as the inflection signal for platform consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Sourcing | Siemens AG secures SiC supply continuity for high-frequency inverter platforms against allocation risk. |
| Linear Motion Backward Integration | Bosch Rexroth AG locks in specification authority through in-house ball screw and rack-and-pinion production. |
| Single-Cable Servo Convergence | Hybrid cable integration redistributes engineering investment toward connector specialists in German packaging OEM supply chains. |
| Direct OEM Engineering Engagement | Japanese machine tool builders consolidate procurement around three qualified integrated drive partners, bypassing distributors. |
| Regulatory Certification Pre-Positioning | REACH substance compliance and EU Ecodesign regenerative capability secure specification priority in German metalworking plants. |
Research Approach
Independent corroboration across OEM procurement directors, plant engineers at German automotive component factories, and aftermarket service heads at Japanese precision machinery clusters underwrites the qualitative findings. Secondary validation draws from IEC 60034-30-1 certification databases, EU Ecodesign directive implementation reports, and SEC filings of diversified industrial conglomerates. Bottom-up demand modeling triangulates against top-down supply-side capacity assessments.
Comparable-period anchoring to historical efficiency regulation adoption curves shapes the projection horizon across servo drive, vector drive, and frequency inverter segments. Deployment intensity varies by application complexity: packaging equipment multi-axis clusters, machine tool spindle positioning, and material handling conveyor systems each carry distinct duty cycle assumptions. CAGRs emerge from segment-level unit economics blended with regulatory compliance cost trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruption to SiC wafer supply, abrupt harmonization of IEC testing protocols, and technology substitution by direct-drive linear motor architectures. Forecasts reflect assumptions about regulatory enforcement consistency and OEM procurement consolidation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Laser Cleaning Market
Industrial Equipment
Europe Fusion Splicer Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
Case Handling Machines Market
Industrial Equipment
Battery Power Tools Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Micro Motor Market
Industrial Equipment
Industrial Refrigeration Systems Market
Industrial Equipment
Global High Speed Dispenser Market
Industrial Equipment
Fume Extractor Market
Industrial Equipment
Glass Engraving Machines Market