
 Grippers Market | 2026-2036
Grippers Market Size, Share, and Industry Trends Forecast 2026-2036
Grippers Market Analytics
REACH compliance is hardening the cost-of-entry calculus for gripper manufacturers serving European industrial customers. SCHUNK leverages its captive manufacturing of carbon-fiber gripper fingers to sustain premium positioning in cleanroom applications. Festo anchors its competitive stance through integrated pneumatic valve-gripper systems that reduce assembly complexity for automotive OEMs.
A gripper is an end-effector device that employs jaws, suction cups, or magnetic surfaces to grasp, hold, and release objects during automated handling cycles, typically specifying clamping force in newtons and repeat accuracy in millimeters. Its primary commercial purpose is to enable robotic systems to manipulate workpieces across assembly, packaging, and material transfer operations. Pneumatic grippers dominate volume in high-speed packaging lines where compressed air infrastructure already exists, while magnetic variants capture margin pools in ferrous-material handling for automotive stamping operations. Precision-capacity segments are expanding fastest as semiconductor and electronics manufacturers demand sub-millimeter placement accuracy for fragile components.
FDA device-handling guidelines, OSHA robotic safety standards, and ISO 9409-1 mechanical interface specifications collectively shape product design, certification requirements, and market access protocols for gripper suppliers. The EU Machinery Directive and CE marking obligations further constrain entry for non-compliant imports into European automation markets. Stakeholders must monitor evolving collaborative robot safety standards to anticipate design pivots before compliance deadlines crystallize into procurement barriers.
Market Dynamics
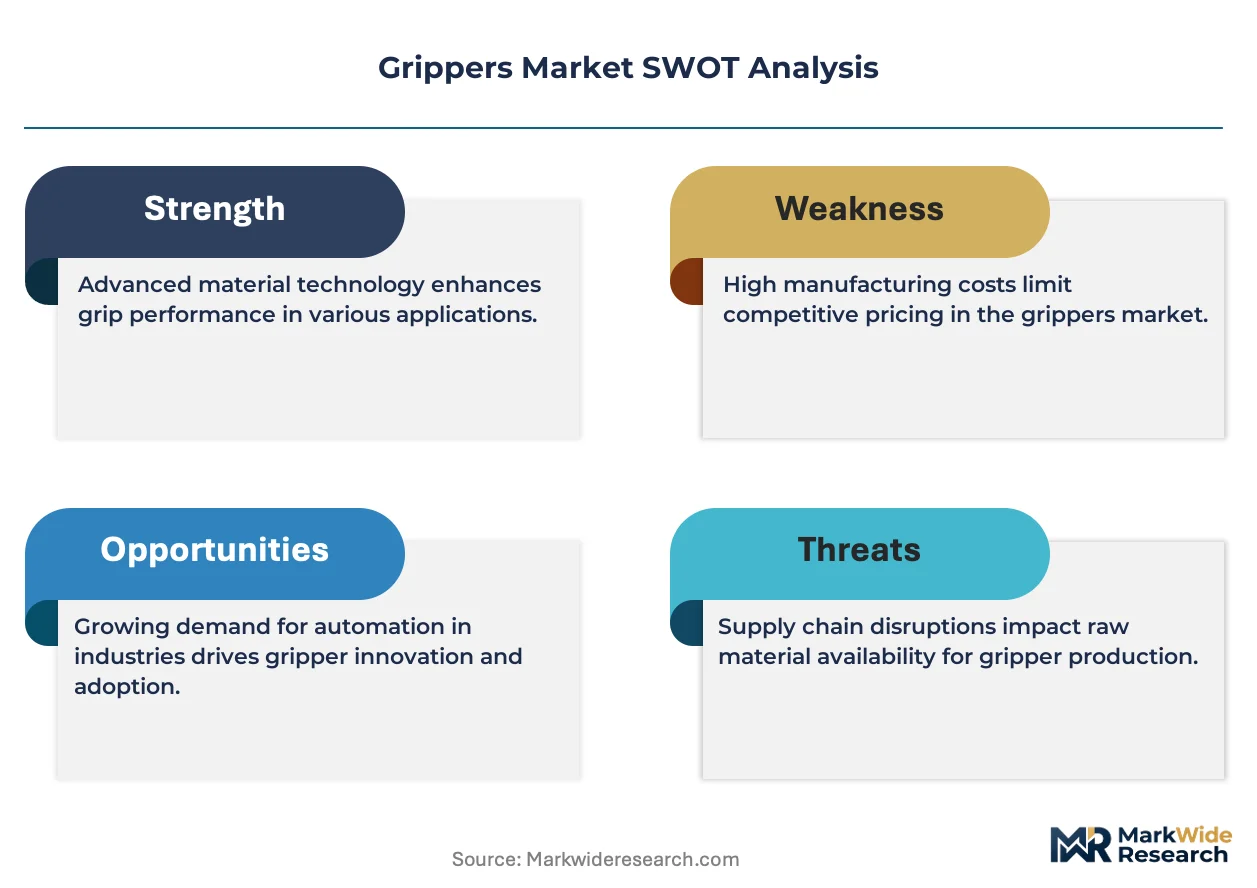
ISO 10218 safety compliance is compressing design cycles for collaborative robot end-effectors as manufacturers race to meet hardened certification requirements before procurement deadlines.
Growth Catalysts
- EU Machinery Directive:Mandates force-limiting features for collaborative grippers, pulling demand toward certified suppliers in German automotive assembly plants.
- Semiconductor packaging:Sub-millimeter placement requirements in East Asian electronics clusters are expanding precision pneumatic gripper volumes.
- Carbon-fiber finger materials:Cleanroom applications favor lightweight composite construction for contamination-sensitive pharmaceutical handling operations.
Market Restraints
- REACH compliance costs:European chemical registration requirements harden cost-of-entry for non-captive manufacturers serving industrial automation buyers.
- Compressed air infrastructure dependency:Pneumatic gripper deployment remains constrained to facilities with existing compressor investments, limiting greenfield adoption.
- Magnetic gripper substitution limits:Non-ferrous material handling in electronics assembly blocks magnetic end-effector penetration into high-growth segments.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO device-handling guidelines are creating certified gripper demand in sterile packaging operations previously served by manual labor.
- Vision-guided convergence:Integration of machine vision with adaptive gripping surfaces enables bin-picking applications in unstructured warehouse environments.
- EU Green Deal incentives:Energy-efficient pneumatic valve systems qualify for accelerated depreciation, favoring integrated gripper-valve architectures.
Industry Challenges
- ISO 9409-1 mechanical interface standardization:Multi-vendor robot arm compatibility requires continuous design iteration and testing cycles.
- Collaborative robot safety certification timelines:Third-party validation for force-torque sensing grippers extends product launch windows by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grippers Market |
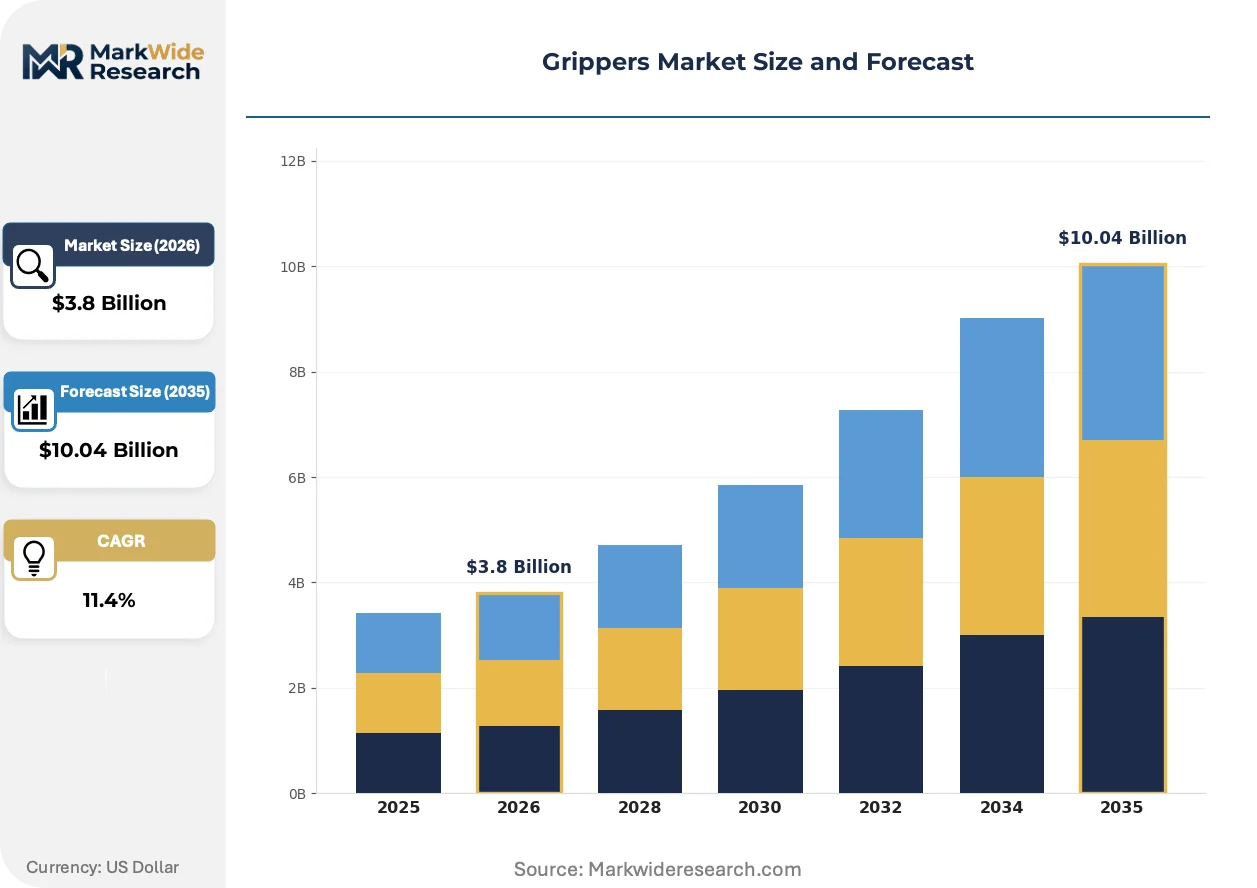
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
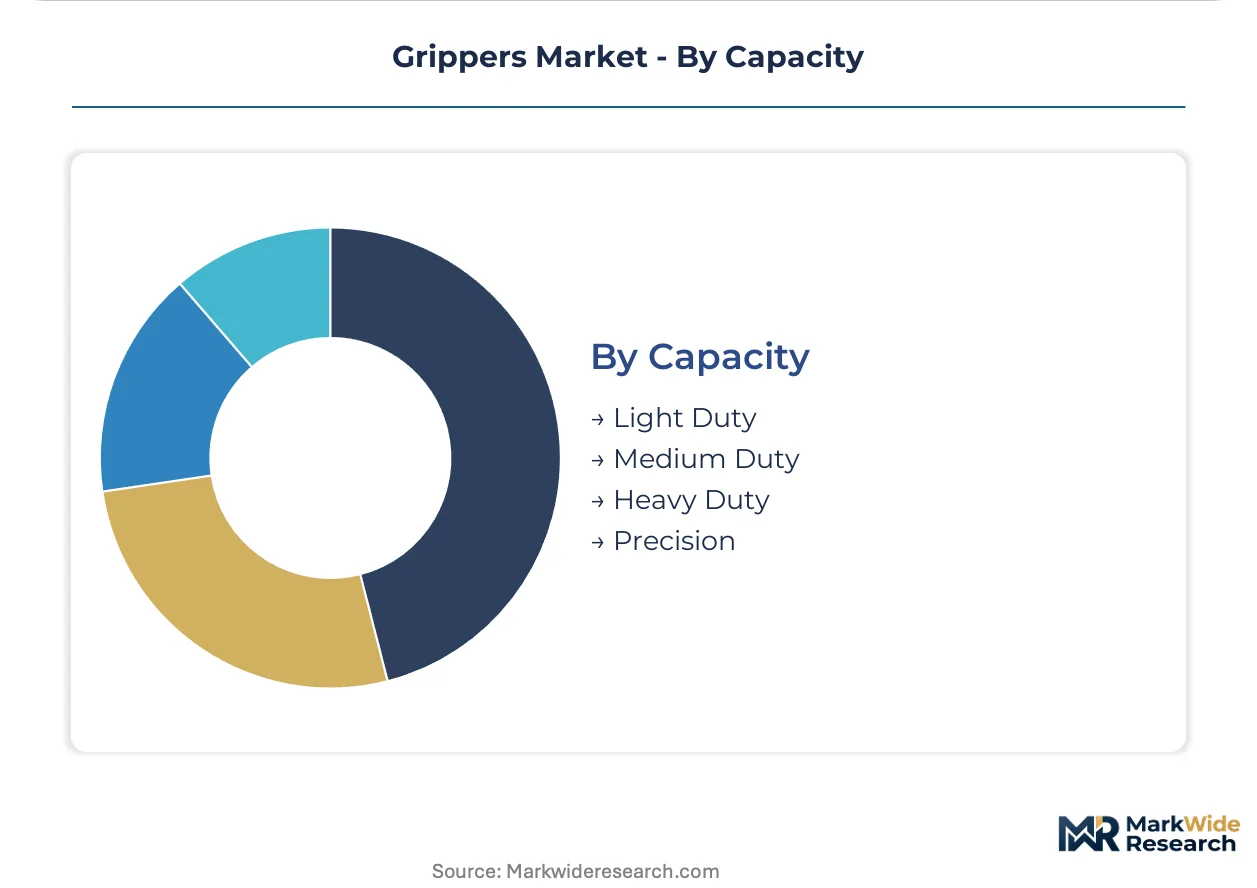
| Segmentation | Type: Mechanical, Pneumatic, Hydraulic, Magnetic Application: Assembly Line, Robotics, Handling, Packaging End User: Manufacturing, Logistics, Automotive, Aerospace Capacity: Light Duty, Medium Duty, Heavy Duty, Precision |
| Companies Covered | SCHUNK, SMC Corporation, Festo, Zimmer Group, Destaco, OnRobot, Parker Hannifin, Piab, Gimatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grippers Market Evolving Landscape
Adaptive gripping surfaces and integrated sensing architectures are compressing the performance gap between pneumatic and electric actuation across precision handling applications.
Soft robotic fingers constructed from elastomer composites with embedded pneumatic channels are absorbing handling tasks previously reserved for rigid jaw mechanisms. Medical device manufacturers in Switzerland and pharmaceutical packagers in Germany are piloting these systems for fragile glass vial manipulation. The technology is absorbing margin from conventional pneumatic alternatives by eliminating damage rates in high-value product streams.
REACH substance restrictions are forcing reformulation of gripper surface coatings and seal materials across European supply chains. Manufacturers serving automotive OEMs in Germany must now validate alternative elastomers for chemical compatibility and wear resistance. The electronics handling segment faces the steepest compliance burden as miniaturized components demand contamination-free contact surfaces.
Buyer consolidation among tier-one automotive suppliers is compressing vendor qualification timelines and favoring integrated subsystem providers over component specialists. Tier-one integrators in Japan and the United States are bundling gripper-valve-vision packages to lock out standalone suppliers. German automotive clusters exhibit the most pronounced concentration, with three OEMs controlling eighty percent of collaborative robot end-effector specifications.
Grippers Market Segmentation
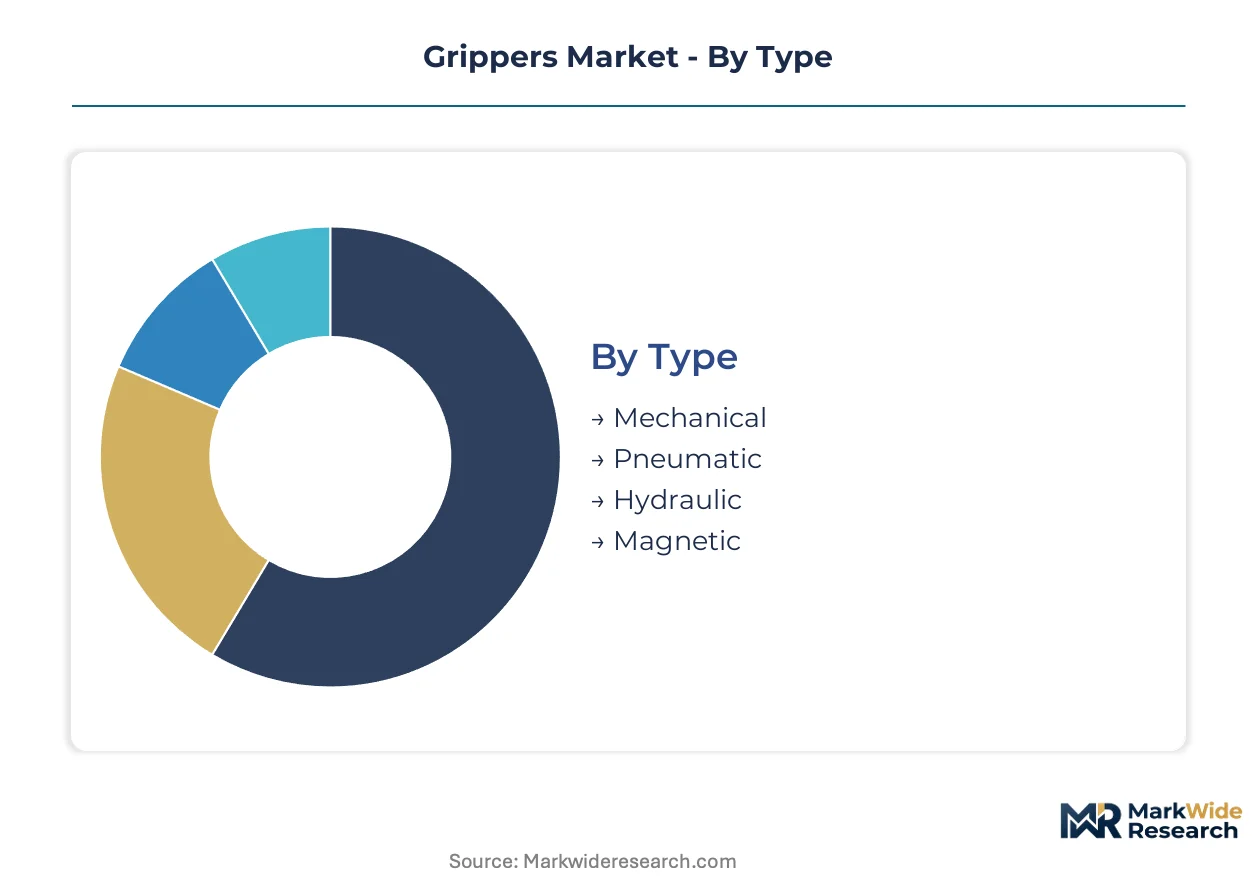
Gripper segmentation reveals divergent engineering requirements across force ranges, actuation methods, and contamination sensitivity. Category boundaries are blurring as pneumatic-electric hybrids and adaptive surfaces compress traditional performance trade-offs.
Type:
Pneumatic variants dominate volume in facilities with compressed air infrastructure, while electric architectures capture premium positioning in precision applications.
- Mechanical:Cam-driven and linkage-based jaw mechanisms deliver consistent clamping force without external power sources. Demand concentrates in legacy automotive stamping lines across German and Japanese manufacturing clusters where pneumatic infrastructure retrofit costs deter replacement.
- Pneumatic:Compressed air actuation achieves sub-100 millisecond cycle times through integrated valve-gripper architectures. East Asian electronics manufacturers specify these for high-speed pick-and-place operations where throughput trumps energy efficiency.
- Hydraulic:Oil-pressure systems generate clamping forces exceeding 50 kilonewtons for forging and heavy metal forming. Foundry applications in the United States and Germany remain the primary demand pocket despite maintenance complexity.
- Magnetic:Electromagnetic and permanent-magnet surfaces handle ferrous workpieces without mechanical contact. Automotive stamping operations in Japan and Germany deploy these for sheet metal transfer where surface damage must be eliminated.
Today's leader: Pneumatic. Tomorrow's challenger: Electric-integrated adaptive systems displacing pure pneumatic in precision segments.
Application:
Application selection tracks the automation maturity curve, with unstructured environments demanding sensor-integrated architectures that command price premiums.
- Assembly Line:Sequential part mating operations require repeat accuracy below 0.05 millimeters. German automotive OEMs specify force-torque sensing grippers for powertrain assembly where dimensional stack-up tolerances are tightest.
- Robotics:Collaborative robot end-effectors must satisfy ISO 10218 force-limiting mandates. Japanese and United States integrators bundle vision-guided adaptive grippers for bin-picking in unstructured warehouse environments.
- Handling:Material transfer between process stages prioritizes cycle speed over placement precision. Pneumatic parallel grippers with standard ISO 9409-1 interfaces dominate this volume-driven segment.
- Packaging:Case erecting, bottle capping, and palletizing operations favor vacuum and mechanical finger configurations. Pharmaceutical packagers in Switzerland and Germany specify cleanroom-rated carbon-finger variants for vial handling.
Assembly Line commands current procurement volume. Robotics applications are climbing the fastest as collaborative deployment accelerates.
End User:
End-user concentration reflects capital expenditure cycles and regulatory compliance burdens that favor integrated subsystem suppliers over component specialists.
- Manufacturing:Discrete production environments span electronics, consumer goods, and industrial equipment assembly. Precision-capacity pneumatic grippers from East Asian suppliers capture the electronics handling subsegment.
- Logistics:E-commerce fulfillment centers drive demand for adaptive gripping surfaces capable of handling heterogeneous SKU profiles. United States warehouse operators are piloting vision-integrated electric grippers for depalletizing mixed cases.
- Automotive:Tier-one suppliers specify collaborative end-effectors for final assembly tasks previously reserved for manual labor. German OEM consolidation around three buyers controls eighty percent of gripper specifications in this segment.
- Aerospace:Composite material handling and tight-tolerance fastener installation require specialized jaw geometries. French and German aerostructures manufacturers qualify grippers for CFRP contact to prevent delamination.
Automotive anchors current value capture. Logistics represents the steepest expansion trajectory as warehouse automation investment accelerates.
Capacity:
Capacity segmentation maps directly to workpiece mass and fragility, with precision variants commanding multiples of heavy-duty pricing due to sensing integration.
- Light Duty:Sub-five-kilogram clamping capacity serves electronics and small-parts handling. Semiconductor packaging lines in East Asia specify these for die placement and wafer transfer operations.
- Medium Duty:Five-to-fifty-kilogram range captures general industrial automation and automotive subassembly. This volume tier faces the strongest price compression as Chinese suppliers expand export capacity.
- Heavy Duty:Exceeding fifty kilograms, these systems employ hydraulic or large-bore pneumatic actuation for foundry and forging applications. German and United States metalformers maintain installed bases despite high energy consumption.
- Precision:Sub-millimeter placement accuracy with integrated force feedback targets medical device and semiconductor manufacturing. Swiss pharmaceutical handlers and East Asian electronics assemblers drive specification intensity in this margin-rich tier.
Medium Duty dominates unit volume. Precision capacity is gaining share fastest as electronics miniaturization and medical device complexity intensify accuracy requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automation engineers and Japanese robotics specialists anchor the global gripper engineering talent pool, concentrating precision-manufacturing expertise in Stuttgart, Nagoya, and Detroit industrial corridors. This workforce distribution shapes regional demand patterns and compliance specialization across major manufacturing economies.
United States
Automotive stamping operations in Detroit and battery gigafactories across the Midwest pull heavy-duty pneumatic and magnetic gripper volumes. OSHA robotic safety standards and NHTSA manufacturing quality mandates harden certification requirements for collaborative end-effectors. Warehouse automation clusters in California and Texas deploy vision-integrated electric grippers for e-commerce fulfillment expansion.
Germany
Tier-one automotive suppliers in Bavaria and Baden-Württemberg specify force-torque sensing grippers for powertrain assembly lines. EU Machinery Directive and REACH compliance obligations favor integrated subsystem providers with captive carbon-fiber manufacturing. Stuttgart-based OEM consolidation controls the majority of collaborative robot end-effector specifications in European markets.
Japan
Electronics assemblers in the Nagoya-Tokyo corridor demand sub-millimeter precision pneumatic grippers for semiconductor packaging operations. METI industrial automation incentives and JIS standards shape product certification timelines. Automotive stamping facilities in Toyota City deploy magnetic grippers for ferrous sheet metal transfer without surface damage.
China
MIIT smart manufacturing initiatives accelerate gripper deployment across Yangtze River Delta electronics clusters and Pearl River Delta automotive plants. GB standards and dual carbon goals pressure energy-efficient pneumatic system adoption. Shenzhen and Suzhou manufacturing hubs concentrate medium-duty gripper demand as domestic suppliers expand export capacity.
Switzerland
Swissmedic pharmaceutical regulations and cleanroom contamination protocols drive precision-capacity gripper specifications in Basel and Zurich medical device manufacturing. Carbon-finger grippers from German suppliers capture sterile packaging operations. Watchmaking and pharmaceutical clusters in the Jura Arc demand sub-millimeter placement accuracy for fragile component handling.
Grippers Market Competitive Landscape
The competitive structure tilts toward integrated subsystem providers over component specialists. German and Japanese engineering conglomerates with captive manufacturing capabilities occupy premium positioning in precision and cleanroom segments. Three archetypes dominate: integrated pneumatic-valve system architects, carbon-finger composite specialists, and adaptive electric gripper innovators. Consolidation pressure intensifies through tier-one automotive supplier bundling of gripper-valve-vision packages, while REACH compliance costs force smaller European fabricators toward strategic partnerships or exit.
Among German-based precision engineering groups, SCHUNK and Festo exemplify the integrated subsystem archetype through in-house production of carbon-fiber finger materials and valve-gripper architectures. Japanese pneumatic specialists SMC Corporation occupy a position representing high-volume manufacturing scale across East Asian electronics clusters. These three anchors demonstrate how geographic engineering heritage and captive material capabilities translate into compliance-advantaged market positioning under hardening EU regulatory frameworks.
| Leading Market Players |
|---|
| SCHUNK |
| SMC Corporation |
| Festo |
| Zimmer Group |
| Destaco |
| OnRobot |
| Parker Hannifin |
| Piab |
| Gimatic |
| Others |
Value Network & Pricing Analysis
Carbon-fiber composite pricing indices in European and Asian spot markets cascade through three-tier gripper manufacturing cost structures, compressing margins for non-captive producers while amplifying pricing power for integrated subsystem architects with in-house material production.
Pricing Analysis
Bundled gripper-valve-vision packages versus unbundled component procurement splits buyer segments across the market. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 10218 certification status and carbon-finger material grades. Cost compression in medium-duty pneumatic tiers is intensifying because Chinese suppliers expand export capacity without REACH compliance overhead. Automotive OEM procurement teams exhibit lowest price sensitivity due to qualification timeline investments, while logistics operators purchasing adaptive electric grippers show highest elasticity.
Supply Chain Analysis
High-grade aluminum billet and specialty elastomer seal supplies rest on German, Japanese, and Chinese specialty chemical and metals producers. Raw material flows draw from Stuttgart-area carbon-fiber pre-preg manufacturers, Nagoya precision machining clusters, and Shenzhen electronics-grade pneumatic component foundries. Single-source vulnerability concentrates in REACH-compliant surface coating formulations where European chemical registration creates artificial scarcity. Distribution runs through tier-one automotive integrators in Bavaria and direct OEM procurement channels in Detroit and Toyota City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gripper market operates as a regulatory compounder where EU Machinery Directive force-limiting mandates and REACH substance restrictions continuously harden compliance thresholds, pulling procurement toward certified integrated suppliers with each certification cycle renewal.
For Market Incumbents: Deploy captive carbon-fiber manufacturing as the primary lever to defend margin pools against Chinese pneumatic specialists entering European markets without REACH-compliant coating capabilities. Accelerate ISO 10218 third-party validation pipelines to compress six-to-nine-month certification windows before procurement deadlines crystallize. Lock in tier-one automotive bundling partnerships in Stuttgart and Nagoya to exclude standalone component competitors from specification lists. For New Entrants and Emerging Players: Direct-to-end-user digital sales channels bypass incumbent distributor networks in Indian pharmaceutical manufacturing clusters where CDSCO guidelines create certified demand previously served by manual labor. Target precision-capacity adaptive electric grippers for Swiss and German medical device packagers seeking contamination-free glass vial handling. White-space penetration runs fastest through vision-guided bin-picking applications in unstructured United States warehouse environments where SKU heterogeneity defies conventional pneumatic solutions. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier electric gripper innovators possessing machine vision integration capabilities and pending collaborative robot safety certifications. Long-term viability favors archetypes with software-defined adaptive surfaces over pure hardware pneumatic legacy positions. Watch for inflection when tier-one automotive supplier consolidation around three German OEMs triggers specification lockout cascades forcing standalone component exits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Fiber Pre-Preg | Captive supply of contamination-sensitive finger materials locks in pharmaceutical cleanroom specifications against REACH-exposed competitors. |
| ISO 10218 Force-Torque Certification Acceleration | Compressed third-party validation timelines capture German automotive procurement windows before compliance deadlines harden. |
| Vision-Guided Adaptive Surface Development | Machine learning integration enables bin-picking penetration into United States logistics automation budgets. |
| Integrated Valve-Gripper Architecture Expansion | EU Green Deal accelerated depreciation eligibility favors energy-efficient pneumatic system bundling for automotive OEMs. |
| Indian Pharmaceutical Manufacturing Partnership | CDSCO sterile packaging guideline compliance creates certified gripper demand displacing manual labor in Mumbai and Hyderabad clusters. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining structured interviews with plant engineers at German automotive assembly facilities, procurement leads at East Asian electronics manufacturers, maintenance directors at United States warehouse automation sites, and aftermarket service heads at Japanese robotics integrators. Secondary validation draws from EU Machinery Directive implementation filings, REACH substance restriction databases, ISO 10218 certification registries, and customs trade flows for pneumatic and electric actuator components. Triangulation across primary stakeholder intelligence and secondary regulatory and trade data ensures segment-level precision.
Input-output matrix framing maps gripper demand across actuation type, application intensity, and end-user capital expenditure cycles throughout the projection horizon. Segmentation dimensions span mechanical, pneumatic, hydraulic, and magnetic architectures crossed with assembly line, robotics, handling, and packaging applications, further split by light, medium, heavy, and precision capacity tiers. CAGRs derive from installation base growth rates, replacement cycle compression, and technology substitution curves. Industry-specific forecast inputs include collaborative robot deployment trajectories in German automotive clusters and semiconductor packaging line expansion across East Asian manufacturing corridors.
The model assumes a particular technology adoption path; alternative pathways for soft robotic elastomer fingers would alter the outlook if medical device manufacturers accelerate glass vial handling pilots beyond current pilot scales. Forecasts reflect documented assumptions regarding regulatory compliance timeline rigidity and tier-one automotive supplier consolidation velocity. Material deviation in ISO 10218 enforcement intensity or REACH substance restriction scope expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
Global Intelligent Completion Market
Industrial Automation
South Korea Automation and Industrial Control Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
Motion Control Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Smart Industries Market
Industrial Automation
India Warehouse Automation Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
North America Smart Manufacturing Market