
 US Smart Manufacturing Market | 2026-2036
US Smart Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
US Smart Manufacturing Market Insights
Aftermarket service revenue is narrowing the profitability gap against hardware sales as industrial automation vendors shift toward recurring software and support contracts. Rockwell Automation leverages its FactoryTalk platform ecosystem to capture lifecycle value from plant operators. Siemens sustains competitive pressure through its digital twin portfolio and deep integration with machine builders. Honeywell International Inc. anchors its position in process industries with distributed control systems that extend into predictive analytics layers.
US Smart Manufacturing encompasses cyber-physical production systems that integrate industrial IoT sensors, edge computing nodes, and AI-driven analytics to enable real-time process optimization and autonomous decision-making on the factory floor. These systems typically operate with sub-50 millisecond latency requirements for safety-critical control loops and aim to maximize Overall Equipment Effectiveness while minimizing unplanned downtime. Artificial Intelligence and IoT Devices represent the fastest-expanding technology categories as manufacturers deploy computer vision for defect detection and sensor networks for condition monitoring. Process Automation and Predictive Maintenance command the deepest margin pools within application segments because they deliver quantifiable reductions in operational expenditure and catastrophic failure risk. System Integration services occupy a structurally critical position in the value chain, bridging legacy brownfield equipment with cloud-native architectures.
NIST's Smart Manufacturing Systems framework and the Cybersecurity and Infrastructure Security Agency's industrial control system guidance shape baseline architecture standards and security postures for domestic deployments. The Department of Energy's Better Plants program creates compliance-linked incentives for energy-intensive facilities to adopt intelligent monitoring and optimization platforms. OSHA's evolving machine guarding and lockout-tagout enforcement priorities push manufacturers toward sensor-based safety systems that integrate with operational technology networks. Stakeholders must weigh capital deployment timing against the risk of stranded automation investments as interoperability standards and AI governance frameworks continue to crystallize.
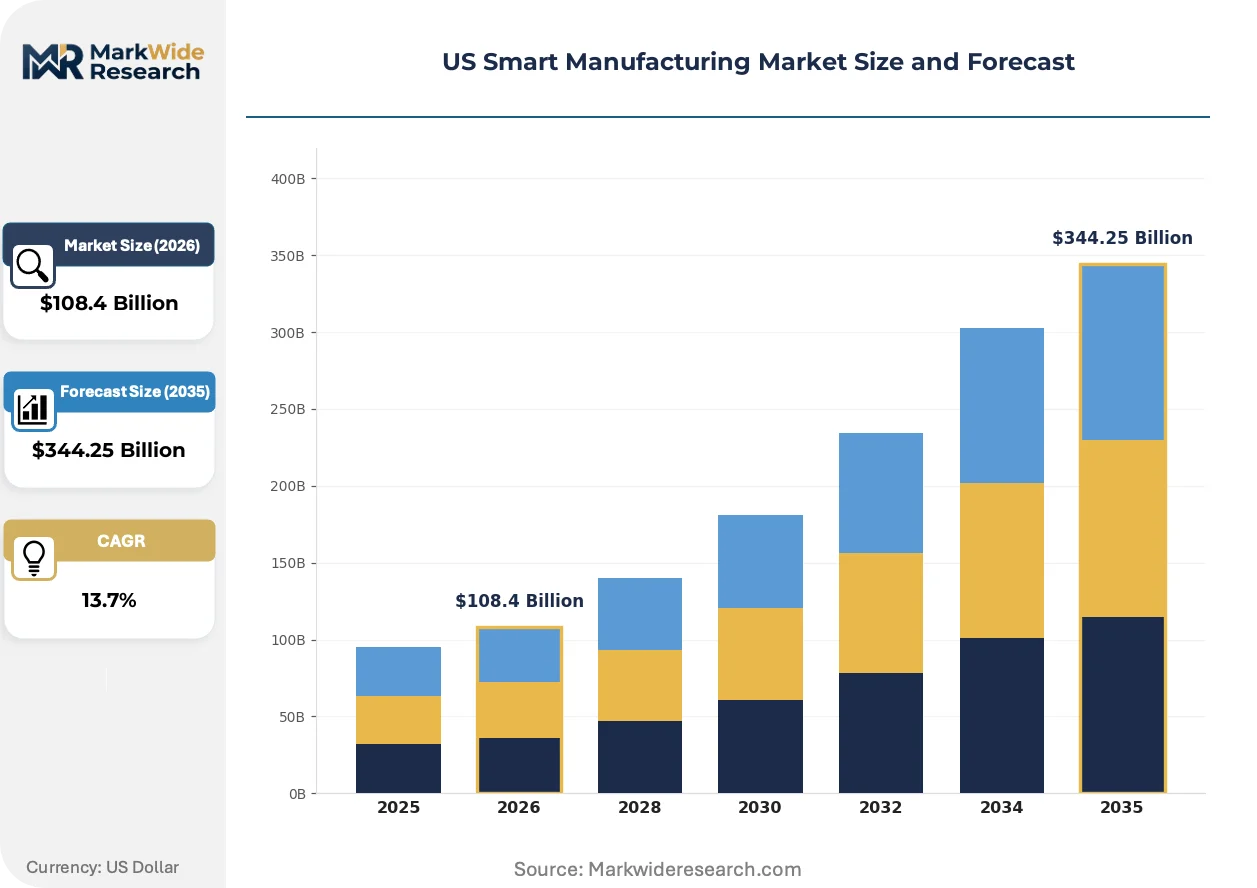
Market Dynamics
Capital deployment timing for brownfield automation projects is compressing as the CHIPS and Science Act accelerates domestic semiconductor fabrication construction and NIST interoperability standards mature.
Growth Catalysts
- Industrial IoT sensor networks:Automotive manufacturers in Michigan's production corridor are retrofitting connected production lines to capture real-time Overall Equipment Effectiveness data and minimize unplanned downtime.
- OSHA machine guarding enforcement:The agency's evolving lockout-tagout priorities are pushing metal fabrication and food processing facilities toward sensor-based safety systems that integrate with operational technology networks.
- Department of Energy Better Plants program:Energy-intensive steel and chemical facilities face compliance-linked incentives to adopt intelligent monitoring platforms that optimize thermal efficiency and reduce carbon intensity.
Market Restraints
- Legacy equipment interoperability:Brownfield plants operating Programmable Logic Controllers from the 1990s face technical limitations in edge computing integration without complete control system replacement.
- Cybersecurity infrastructure costs:CISA's industrial control system guidance mandates segmented network architectures that require substantial capital expenditure for air-gapped operational technology environments.
- Semiconductor component lead times:Concentrated fabrication capacity in East Asia creates supply risk for edge computing nodes and industrial sensors essential to smart manufacturing deployments.
Strategic Opportunities
- Texas advanced manufacturing clusters:Emerging semiconductor and battery production facilities near Austin and Dallas present greenfield automation opportunities without legacy equipment constraints.
- Predictive maintenance software convergence:Artificial intelligence and digital twin technologies are creating new service revenue models as hardware vendors shift toward recurring analytics contracts.
- Process automation in pharmaceuticals:FDA's quality-by-design guidelines are driving biologics manufacturers toward continuous manufacturing platforms with embedded process analytical technology.
Industry Challenges
- Operational technology cybersecurity skills:Plant engineering teams lack personnel trained in CISA's industrial control system security frameworks and secure remote access protocols.
- Integration complexity with proprietary protocols:Machine builders' non-standard communication interfaces create friction in system integration projects bridging legacy equipment with cloud-native architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Smart Manufacturing Market |
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $344.25 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Devices, Artificial Intelligence, Cloud Computing, Robotics Application: Predictive Maintenance, Quality Control, Inventory Management, Process Automation End User: Automotive Manufacturers, Aerospace Companies, Electronics Makers, Textile Producers Service Type: Consulting Services, System Integration, Maintenance Services, Training Services |
| Companies Covered | Rockwell Automation, Siemens, Honeywell International Inc., Emerson Electric Co., General Electric Company, ABB Ltd., Schneider Electric, PTC, Cisco Systems, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Smart Manufacturing Market Trends and Innovations
Edge computing architectures are hybridizing with cloud platforms to enable sub-50 millisecond control loops while preserving data sovereignty requirements for defense and critical infrastructure suppliers.
Digital twin technology is hybridizing physics-based simulation with machine learning inference to optimize production scheduling and quality control. Automotive tier-one suppliers in Michigan and Ohio are deploying these systems at scale for stamping and welding operations. This convergence is compressing commissioning timelines for new production lines and reducing physical prototyping requirements.
OSHA's updated machine guarding standards are forcing discrete manufacturers to replace mechanical interlocks with networked safety instrumented systems. The regulation's 2024 enforcement priorities target metalworking and robotics integration hazards most severely. Food processing and packaging facilities are responding fastest due to existing sanitation requirements that already demanded frequent equipment washdowns incompatible with legacy guarding.
Aftermarket service unbundling is separating predictive analytics subscriptions from original hardware purchases. Industrial automation buyers in Texas and the Southeast are demanding consumption-based pricing for condition monitoring rather than perpetual licenses. This shift is most visible among automotive battery manufacturers scaling production rapidly and unwilling to commit capital to software assets with uncertain utilization curves.
US Smart Manufacturing Market Segmentation
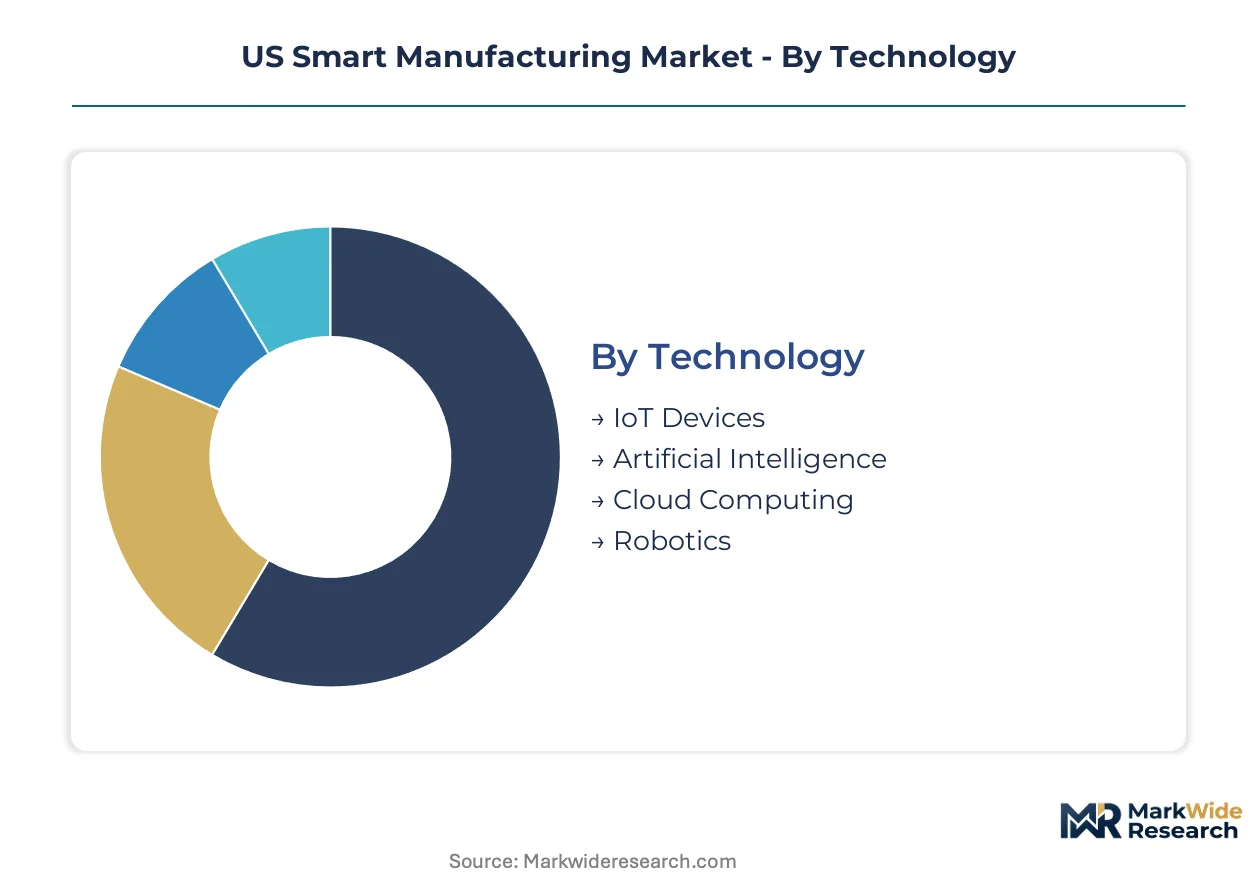
Segmentation in US Smart Manufacturing reveals distinct margin profiles and service attachment rates across technology layers. Vendors configure pricing and partnership strategies differently depending on whether buyers prioritize capital efficiency, operational uptime, or regulatory compliance.
Technology:
After-sales service intensity varies sharply across technology categories, with software-heavy segments generating recurring revenue streams while hardware-centric segments depend on replacement cycles.
- Artificial Intelligence:Machine learning models for defect detection and process optimization require continuous retraining and algorithm updates. Michigan automotive tier-one suppliers are deploying computer vision systems with mandatory vendor-managed model refresh contracts.
- IoT Devices:Industrial sensor networks combine edge hardware with telemetry subscription tiers. Texas battery manufacturers are standardizing on condition monitoring packages that bundle hardware depreciation with cloud connectivity fees.
- Cloud Computing:Manufacturing execution system hosting and data lake infrastructure for multi-site operations.
- Robotics:Collaborative robot arms and autonomous mobile robots with preventive maintenance schedules tied to operational hour thresholds.
By volume, IoT Devices leads. By growth pace, Artificial Intelligence is ahead.
Application:
Application segments stratify by measurable return-on-investment clarity, with buyers in capital-constrained environments favoring solutions with proven payback periods under 24 months.
- Process Automation:Distributed control systems and programmable logic controller programming for continuous manufacturing environments. Chemical facilities along the Gulf Coast are retrofitting batch operations with continuous processing platforms to capture Department of Energy efficiency incentives.
- Predictive Maintenance:Vibration analysis, thermal imaging, and oil debris monitoring algorithms that forecast equipment failure windows. Ohio metalworking shops are adopting these systems following OSHA's intensified enforcement on unplanned lockout incidents.
- Quality Control:Automated optical inspection and statistical process control software for defect traceability.
- Inventory Management:RFID tracking and warehouse orchestration systems for work-in-progress visibility.
Process Automation captures the largest installed base. Predictive Maintenance is expanding most quickly.
End User:
End-user concentration maps directly to regional manufacturing clusters, with procurement sophistication varying by industry maturity and regulatory exposure.
- Automotive Manufacturers:Full-stack smart manufacturing deployments spanning stamping, welding, and final assembly. Michigan's production corridor is retrofitting brownfield plants with connected production lines to capture real-time Overall Equipment Effectiveness metrics.
- Electronics Makers:Semiconductor fabrication and printed circuit board assembly with cleanroom-compatible automation. Texas emerging clusters are building greenfield facilities without legacy equipment constraints.
- Aerospace Companies:Precision machining and composite layup operations with stringent traceability requirements.
- Textile Producers:Dyeing and finishing automation with water and energy monitoring for sustainability reporting.
Automotive Manufacturers dominate current spending. Electronics Makers show the steepest expansion trajectory.
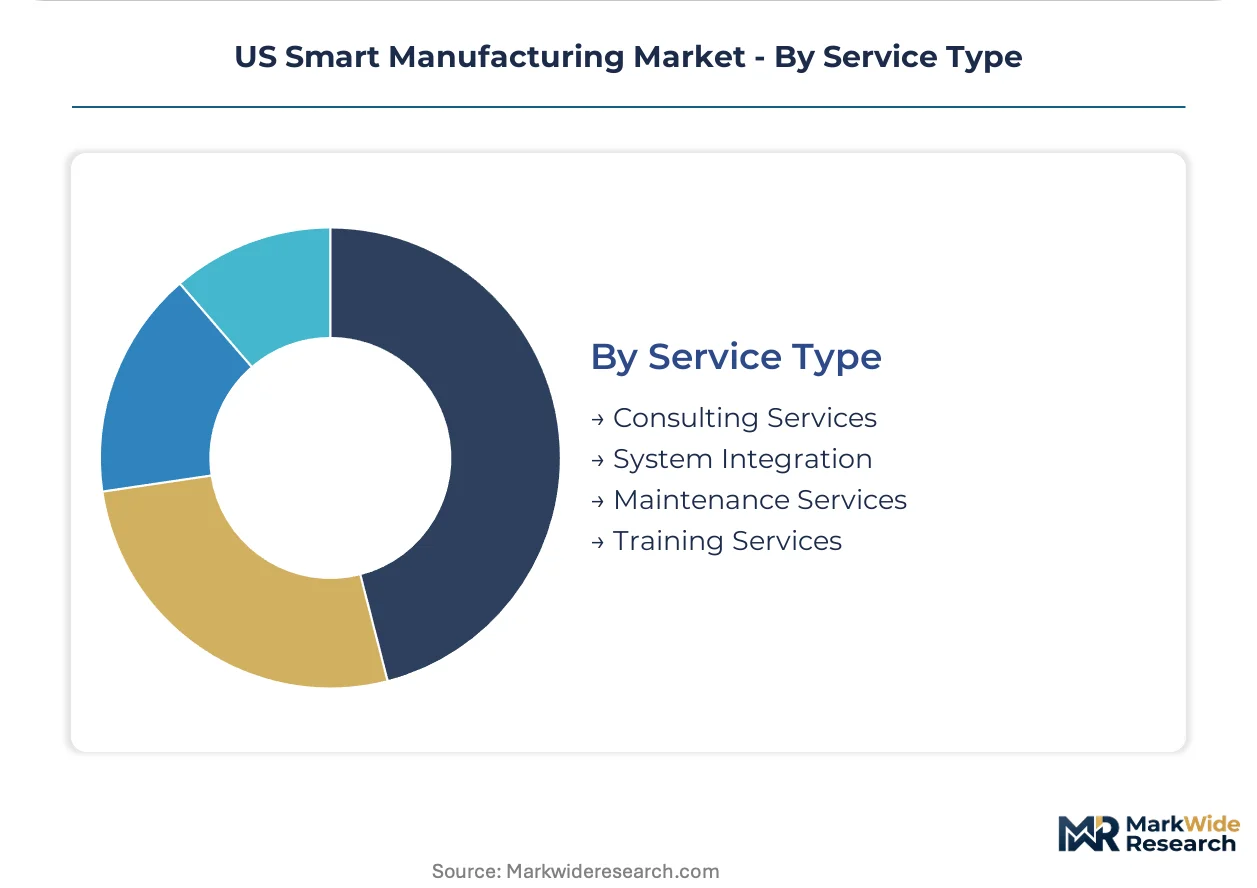
Service Type:
Service type mix reflects the technical complexity gap between legacy operational technology and cloud-native architectures, with buyers outsourcing integration risk to specialized providers.
- System Integration:Protocol translation, middleware deployment, and brownfield-greenfield bridging projects. Food processing facilities are engaging integrators to connect 1990s-era programmable logic controllers with modern manufacturing execution systems.
- Consulting Services:Digital transformation roadmapping, cybersecurity posture assessments, and workforce training program design. Steel producers are hiring consultants to navigate NIST Smart Manufacturing Systems framework compliance.
- Maintenance Services:On-site technician dispatch, spare parts logistics, and remote monitoring center operations.
- Training Services:Operator certification programs and control system programming courses for plant engineering teams.
System Integration commands the highest project values. Consulting Services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across US manufacturing corridors. Michigan automotive buyers prioritize uptime over capital efficiency, while Texas greenfield developers emphasize scalable deployment models without legacy constraints.
Michigan
Tier-one automotive suppliers dominate retrofit demand for connected production lines. OSHA's intensified machine guarding enforcement drives sensor-based safety system upgrades in Detroit-Warren-Dearborn metro stamping and welding facilities. Grand Rapids metalworking clusters are adopting predictive maintenance platforms following lockout-tagout incident penalties.
Texas
Semiconductor fabrication and battery manufacturing anchor greenfield automation investment without brownfield interoperability burdens. CHIPS and Science Act funding accelerates digital infrastructure deployment near Austin and Dallas. Samsung Taylor and Texas Instruments Sherman facilities represent the nation's largest advanced manufacturing construction pipeline.
Ohio
Precision machining and polymer processing facilities seek energy efficiency through Department of Energy Better Plants program incentives. Cleveland-Akron manufacturing corridors retrofit batch operations with continuous processing platforms. Youngstown metal fabrication shops deploy condition monitoring following OSHA's 2024 robotics integration enforcement priorities.
California
Aerospace and defense contractors require sub-50 millisecond latency control loops for precision manufacturing. NIST Smart Manufacturing Systems framework compliance shapes procurement specifications in Los Angeles-Long-Anaheim precision machining clusters. Bay Area industrial software vendors anchor predictive analytics service revenue models.
South Carolina
BMW Spartanburg and Michelin Greenville anchor automotive tire and vehicle assembly automation demand. Southeast automotive battery manufacturers standardize on consumption-based condition monitoring pricing. Charleston port logistics integration drives warehouse orchestration system deployment.
US Smart Manufacturing Market Competitive Landscape
Capability concentration sits with industrial automation incumbents possessing decades of operational technology integration expertise; scale advantage sits with diversified conglomerates with cross-sector digital portfolios. The market structure tiers into three archetypes: full-stack platform providers, specialized system integrators, and component-focused hardware vendors. Dominant competitive moves include strategic partnerships bridging legacy-brownfield gaps and portfolio diversification into recurring software revenue streams.
Among US-based industrial automation incumbents, Rockwell Automation and Honeywell International Inc. exemplify the platform-provider archetype, anchoring positions through factory-floor software ecosystems and process industry control systems respectively. Siemens, as a European-based conglomerate, occupies a position representing the diversified digital-industrial model with cross-border manufacturing execution capabilities. These three companies illustrate the competitive tension between geographic origin specialization and global-scale diversification in smart manufacturing solution deployment.
| Leading Market Players |
|---|
| Rockwell Automation |
| Siemens |
| Honeywell International Inc. |
| Emerson Electric Co. |
| General Electric Company |
| ABB Ltd. |
| Schneider Electric |
| PTC |
| Cisco Systems, Inc. |
| Others |
Pricing and Supply Chain Analysis
Semiconductor component lead time volatility from East Asian fabrication concentration compresses both pricing tier spreads and supply chain configuration choices for US automation buyers. Tariff exposure on edge computing hardware and industrial sensors forces vendors to absorb margin compression or pass through cost increases, while buyers face extended procurement cycles that reshape inventory strategies.
Pricing Analysis
Aftermarket service contracts and predictive analytics subscriptions now drive lifetime value capture for industrial automation vendors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by integration complexity and support intensity. Cost compression in hardware tiers is intensifying because semiconductor supply constraints limit volume discounts. Automotive battery manufacturers in Texas exhibit highest price sensitivity due to rapid capacity scaling with uncertain utilization curves, while Michigan automotive tier-one suppliers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Upstream feedstock for edge computing nodes and industrial IoT sensors draws from Taiwan, South Korea, and Japan for advanced semiconductors, with Mexico and Germany contributing precision mechanical components. Critical dependencies include silicon wafers, rare earth magnets for motor assemblies, and specialized industrial-grade memory modules. Single-source vulnerability around advanced node fabrication creates procurement risk for safety-critical control systems. Distribution runs through authorized distributor networks and direct OEM relationships, with system integrators serving as value-added intermediaries for brownfield retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in switching costs: once Rockwell Automation's FactoryTalk or Honeywell's distributed control systems embed into plant operations, replacement triggers production downtime measured in millions per hour.
For Market Incumbents: Entrench platform ecosystems by deepening software subscription attach rates and expanding predictive analytics capabilities that increase customer lifetime value. Acquire specialized cybersecurity firms to address CISA compliance requirements as industrial control system security becomes a procurement gate. Counter emerging cloud-native challengers by emphasizing sub-50 millisecond latency guarantees that pure software vendors cannot match. For New Entrants and Emerging Players: Mid-market food processing facilities in the Southeast represent the most penetrable entry point, as OSHA's 2024 machine guarding enforcement creates immediate replacement demand without incumbent lock-in. Greenfield semiconductor construction sites in Texas offer automation opportunities unburdened by legacy protocol translation. Lead with consumption-based pricing for condition monitoring to displace perpetual license models that strain capital-constrained buyers. For Investors and Strategic Acquirers: NIST Smart Manufacturing Systems framework finalization reshapes the acquisition landscape by elevating compliance-certified vendors above uncertified competitors. Five-to-ten-year viability favors platform providers with recurring revenue exceeding fifty percent of total sales. Target system integration specialists with proven brownfield-greenfield bridging capabilities. Watch CHIPS Act facility construction permitting velocity as the signal indicating demand inflection for domestic automation deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | FactoryTalk ecosystem expansion captures lifecycle value from plant operators through mandatory model refresh contracts. |
| Backward Integration | In-house edge computing hardware production reduces exposure to Taiwan semiconductor supply volatility. |
| Strategic Partnership | System integrator alliances bridge legacy PLC protocols with cloud-native manufacturing execution systems. |
| Acquisition of Specialist Firm | Industrial cybersecurity capabilities address CISA air-gap mandates and secure remote access requirements. |
| Geographic Expansion | Texas advanced manufacturing clusters offer greenfield deployment without brownfield interoperability constraints. |
Research Methodology
A standing panel of plant engineers, maintenance directors, OEM procurement managers, and aftermarket service heads provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with automation vendor executives and secondary validation against SEC 10-K filings, NIST technical publications, and Department of Energy Better Plants program disclosures. Bottom-up equipment shipment analysis and top-down manufacturing value-added estimates were triangulated to establish market sizing.
Scenario-bracketing framed demand projections across technology, application, end-user, and service type segmentation dimensions. Deployment model complexity and regional regulatory cluster adoption patterns shaped the analytical framework. CAGRs were derived from equipment replacement cycle analysis, capacity expansion announcements, and policy incentive quantification. Edge computing latency requirements and AI governance framework crystallization served as key forecast sensitivity inputs across the projection horizon.
Practitioners should monitor CHIPS Act construction permitting delays, NIST interoperability standard revisions, and OSHA enforcement priority shifts for early signals requiring forecast reassessment. Cross-checking against IHS Markit industrial automation equipment databases and MAPI manufacturing investment surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Middle East and Africa Process Automation Market
Industrial Automation
Intralogistics Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Linear Motion System Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Palletizing Systems Market