
 US and Europe Warehouse Automation Market | 2026-2036
US and Europe Warehouse Automation Market Size, Share, and Industry Trends Forecast 2026-2036
US and Europe Warehouse Automation Market Insights
Skilled maintenance technician availability is bifurcating the US and Europe warehouse automation landscape into sites that can sustain advanced robotics and those stuck with legacy conveyor infrastructure. Dematic leverages its North American service network to anchor large-scale e-commerce deployments. Swisslog competes through deep specialization in pharmaceutical cold-chain automation. KNAPP AG dominates piece-picking robotics for fashion and grocery verticals.
Warehouse automation encompasses the integrated hardware and software systems that execute material movement, storage, retrieval, and sortation with minimal human intervention, typically operating at throughput rates exceeding 10,000 picks per hour in high-density configurations. Robotics and automated guided vehicles now capture the fastest expansion as lithium-ion powertrains and AI-driven navigation slash deployment timelines. Software solutions and management systems sit at the margin core, since warehouse execution software locks in recurring revenue and raises switching costs for 3PL operators. E-commerce end users represent the dominant demand pool, though manufacturing retrofits are accelerating as just-in-time pressures resurface.
OSHA workplace safety mandates and the EU Machinery Directive shape equipment guarding, collaborative robot speed limits, and operator training protocols across both jurisdictions. The EU F-Gas Regulation and US EPA refrigerant rules are forcing cold-storage automation providers to redesign thermal systems around lower-GWP coolants. Stakeholders must weigh regulatory compliance timelines against automation refresh cycles to avoid stranded capital in facilities that cannot adapt to emerging carbon-accounting standards.
Market Dynamics
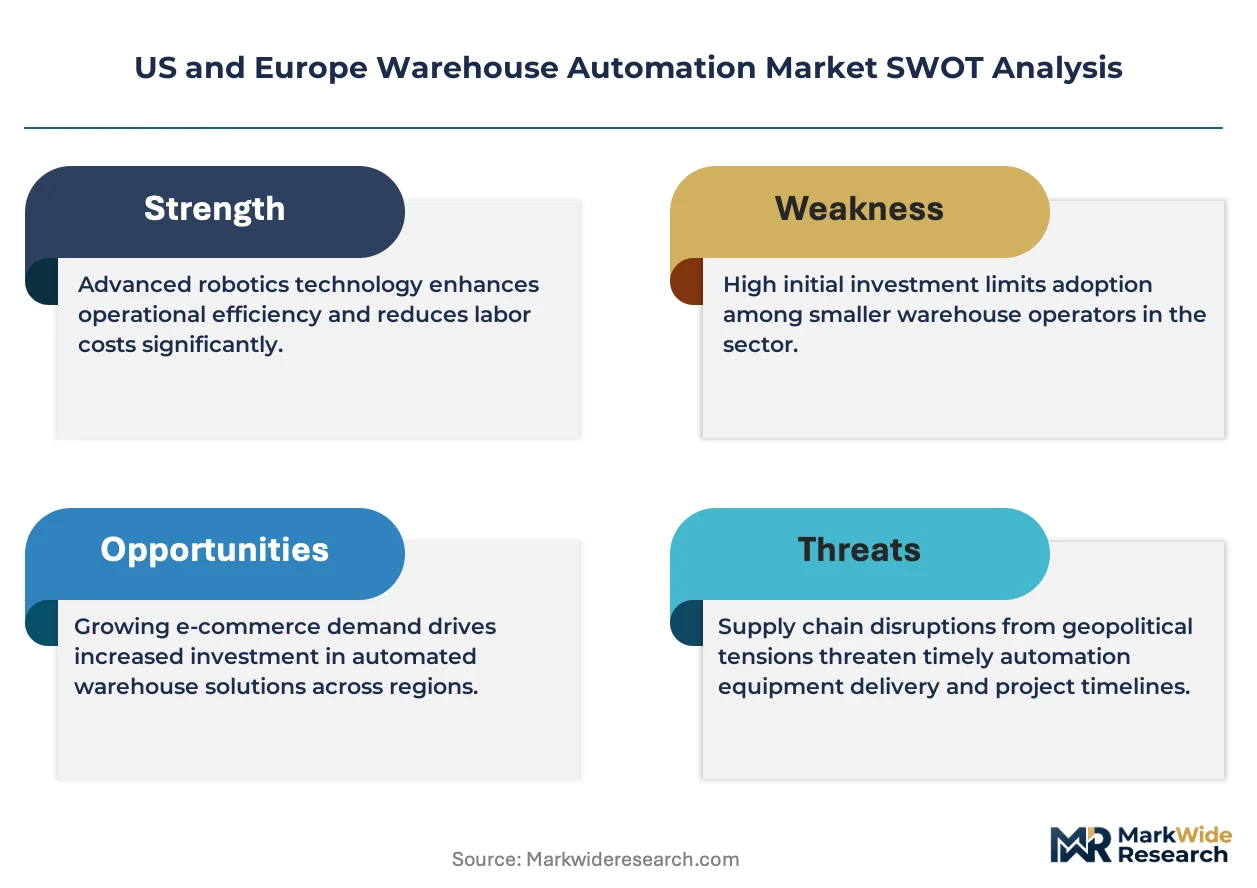
Labor scarcity across the US Midwest distribution belt and Germany's logistics corridor is compressing automation payback periods from 36 months to under 18 months, forcing capital allocation toward robotic piece-picking and autonomous mobile fleets.
Growth Catalysts
- EU Green Deal electrification mandates:The EU F-Gas Regulation and national carbon targets are accelerating lithium-ion forklift and AGV deployment across cold-chain facilities in the Netherlands and Belgium.
- E-commerce fulfillment density:Same-day delivery promises from fashion and grocery verticals are driving micro-fulfillment center construction in urban peripheries of Chicago and London.
- OSHA ergonomic enforcement:Workplace safety mandates around repetitive motion injuries are pushing 3PL operators toward collaborative robots with force-limiting controls.
Market Restraints
- Skilled technician scarcity:Maintenance workforce gaps in Poland and Ohio are extending mean-time-to-repair for advanced robotics beyond acceptable SLAs.
- Copper and rare-earth volatility:Motor and sensor input costs swing 15-40% quarterly, destabilizing project budgeting for mid-size warehouse retrofits.
- Legacy WMS integration friction:Proprietary software stacks from the 2010s resist API connectivity with modern orchestration layers.
Strategic Opportunities
- Pharmaceutical cold-chain specialization:EU GDP compliance requirements and US FDA traceability rules are opening premium automation tiers for temperature-validated robotics.
- Spain and Italy warehouse modernization:Underpenetrated southern European logistics infrastructure offers first-mover positioning for automated sortation systems.
- AI-driven predictive maintenance convergence:Machine learning overlays on existing sensor networks are creating software-only revenue streams without hardware replacement.
Industry Challenges
- Multi-vendor system integration:Heterogeneous robotic fleets from different OEMs require custom middleware development, extending commissioning timelines.
- CE marking and OSHA certification timelines:Safety validation protocols for collaborative applications add 4-6 months to deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US and Europe Warehouse Automation Market |
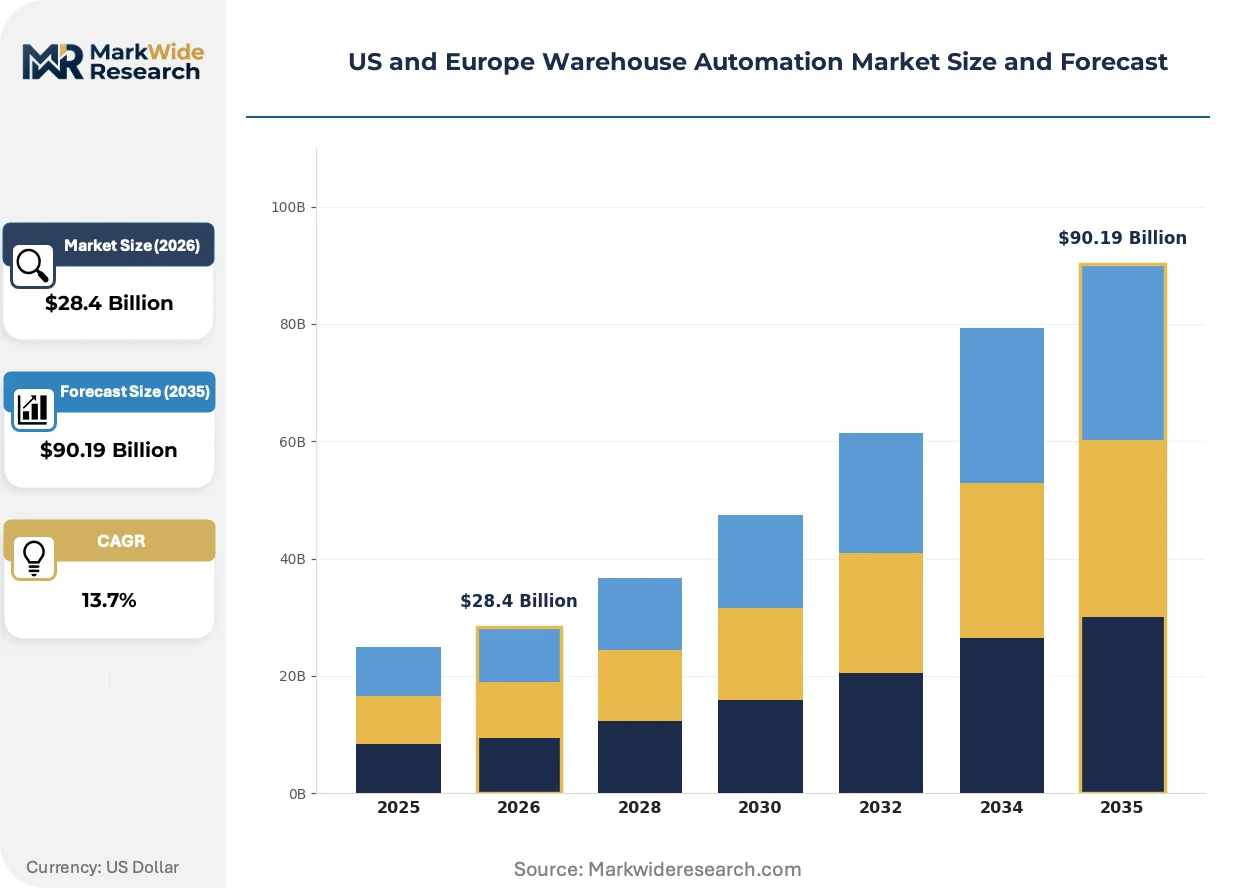
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $90.19 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Guided Vehicles, Conveyor Systems, Robotics, Sortation Systems Product Type: Software Solutions, Storage Systems, Automated Picking Equipments, Management Systems End User: E-commerce, Retail, Manufacturing, 3PL Installation Type: New Installations, Retrofits, Upgrades, Expandable Systems |
| Companies Covered | Dematic, Swisslog, SSI Schaefer, Jungheinrich AG, KNAPP AG, Honeywell International Inc, TGW Logistics Group, Vanderlande, Beumer Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US and Europe Warehouse Automation Market Trends and Innovations
Autonomous navigation and energy-dense powertrains are collapsing the boundary between fixed automation and flexible robotics, enabling warehouse layouts that reconfigure weekly rather than annually.
Vision-guided piece-picking robots with soft-grip end effectors are displacing manual induct stations in apparel and electronics fulfillment. E-commerce operators in the UK and Germany are deploying these systems at 200-unit scales per site. The technology is displacing traditional zone-picking labor pools while compressing training requirements from months to days.
The EU Machinery Directive's 2023 update on collaborative robot speed limits and safeguarding zones is forcing redesigns of human-robot work cells. Manufacturers must now certify dynamic separation distances rather than fixed light curtains. Pharmaceutical and grocery cold-storage facilities face the steepest compliance costs due to thermal enclosure constraints.
Third-party logistics buyers are unbundling automation hardware from software maintenance contracts, treating robotics as OpEx through leasing structures. German automotive suppliers and US consumer electronics distributors are driving this shift. The model is most visible in the Netherlands, where tax treatment favors operating leases over capital expenditure recognition.
US and Europe Warehouse Automation Market Segmentation
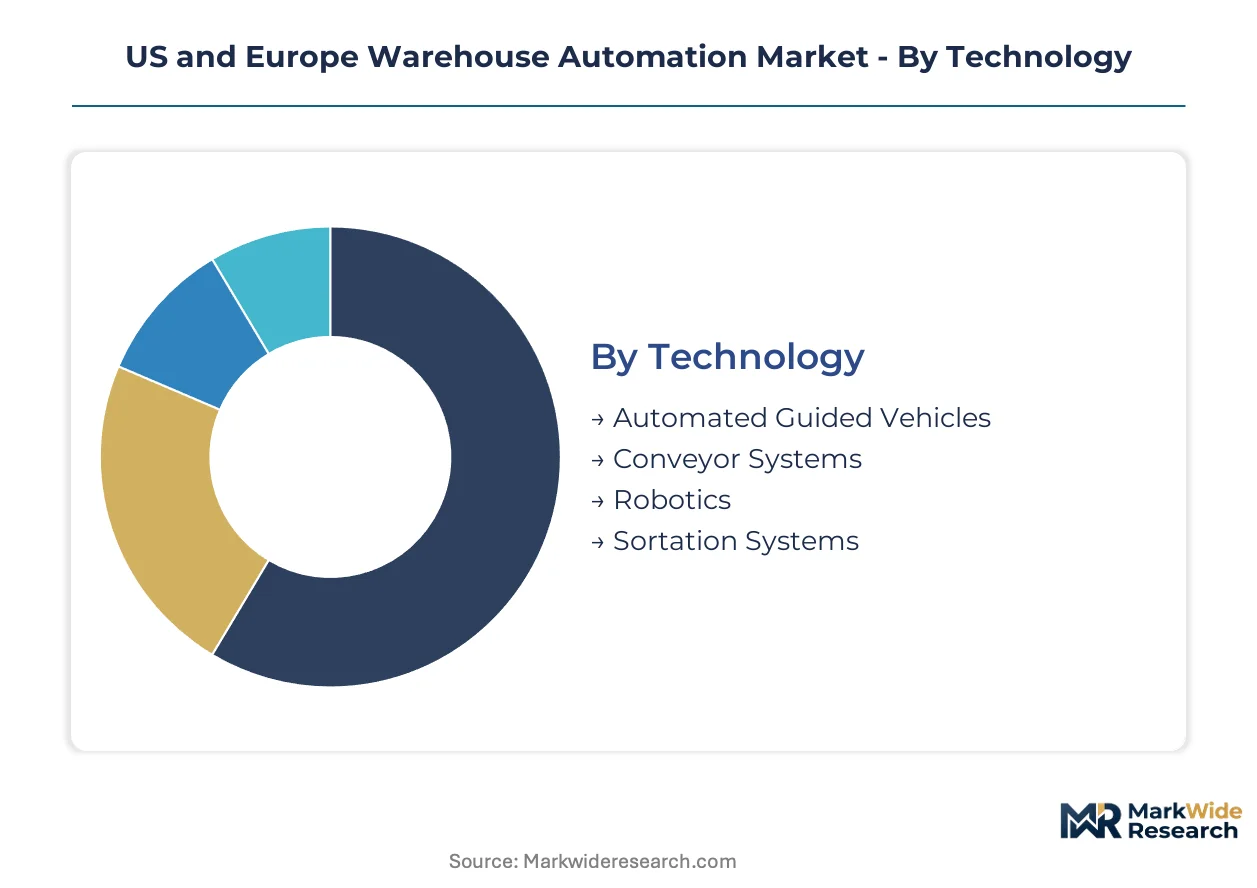
Warehouse automation procurement channels diverge sharply by technology maturity and capital deployment flexibility. E-commerce operators favor robotics-as-a-service arrangements while automotive manufacturers prefer turnkey integration contracts.
Technology:
Channel mix splits between capital-intensive fixed infrastructure and subscription-based mobile robotics fleets.
- Robotics:Vision-guided piece-picking systems with soft-grip end effectors now achieve 200-unit deployments per fulfillment site. German fashion retailers and UK grocery operators are compressing training cycles from months to days while displacing zone-picking labor pools.
- Automated Guided Vehicles:Lithium-ion powertrains and AI-driven navigation have collapsed deployment timelines for flexible material transport. Dutch cold-chain facilities and US Midwest distribution centers are leading AGV adoption under EU Green Deal electrification mandates.
- Conveyor Systems:Legacy belt infrastructure dominates brownfield retrofits where WMS integration friction limits modernization scope.
- Sortation Systems:Cross-belt and tilt-tray configurations anchor high-throughput parcel hubs in Chicago and London urban peripheries.
By volume, Conveyor Systems leads. By growth pace, Robotics is climbing the fastest.
Product Type:
Margin concentration sits with recurring-revenue software layers that raise switching costs for 3PL operators.
- Software Solutions:Warehouse execution systems orchestrate heterogeneous robotic fleets through API-native middleware. The unbundling of hardware from software maintenance contracts is accelerating in the Netherlands, where tax treatment favors operating leases.
- Management Systems:Real-time inventory visibility platforms integrate with ERP stacks to enable just-in-time manufacturing retrofits. Polish and Ohio maintenance workforce gaps are extending commissioning timelines for these deployments.
- Storage Systems:High-density shuttle systems and vertical lift modules maximize cube utilization in constrained urban logistics real estate.
- Automated Picking Equipments:Goods-to-person stations and robotic induction cells serve pharmaceutical cold-chain validation requirements under EU GDP compliance rules.
Software Solutions commands the highest recurring revenue share. Management Systems are gaining share fastest among manufacturing end users.
End User:
Application requirements dictate automation architecture more than facility scale or throughput targets.
- E-commerce:Same-day delivery promises from fashion and grocery verticals are driving micro-fulfillment center construction. UK and German operators deploy vision-guided robots at scale while OSHA ergonomic enforcement pushes collaborative robot adoption.
- 3PL:Multi-tenant facilities require rapid reconfiguration capabilities to serve shifting client portfolios. The sector leads treatment of robotics as OpEx through leasing structures.
- Manufacturing:Just-in-time pressures are accelerating retrofits of legacy conveyor infrastructure with autonomous mobile fleets.
- Retail:Store fulfillment and returns processing automation is concentrating in Spain and Italy warehouse modernization projects.
E-commerce leads absolute deployment volume. 3PL represents the steepest expansion trajectory as outsourcing accelerates.
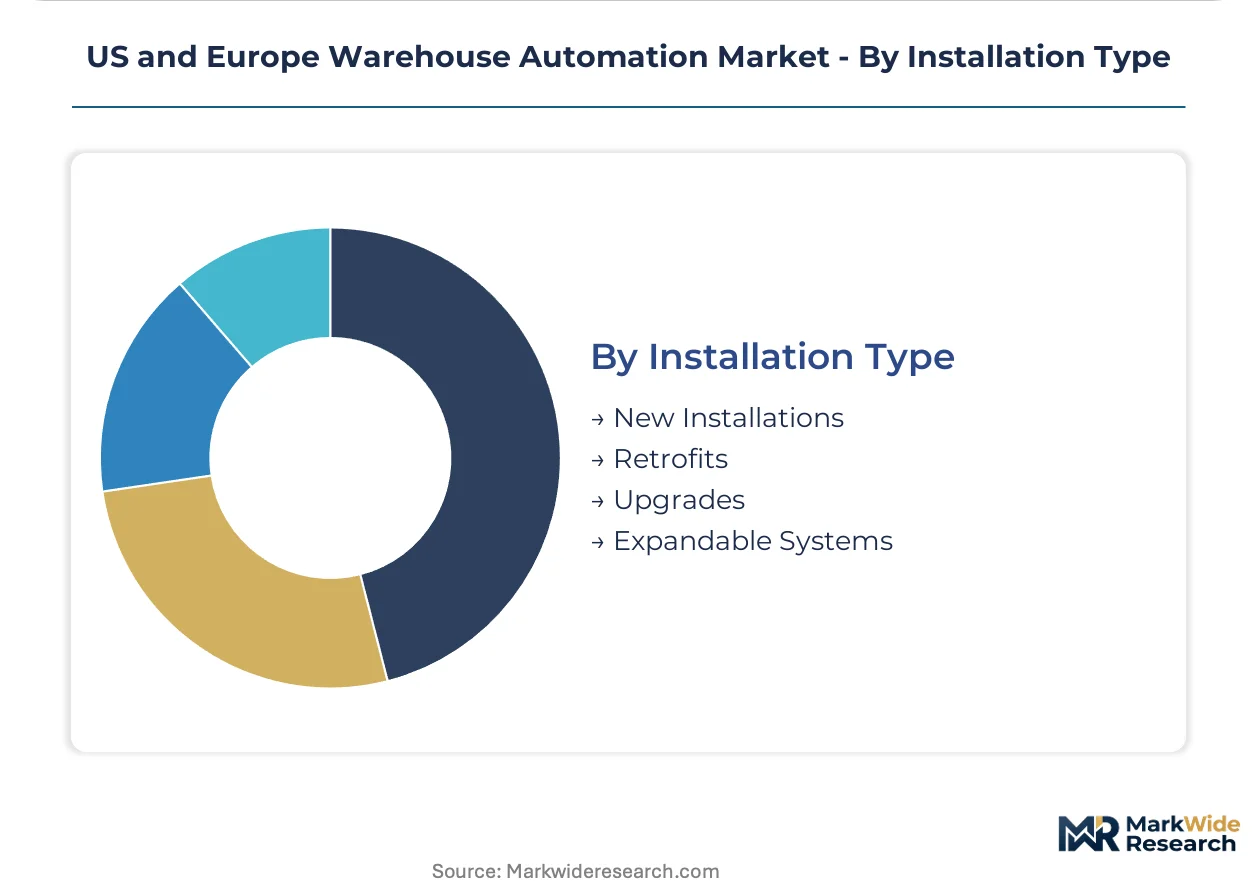
Installation Type:
Capital cycle timing determines whether operators pursue greenfield automation or incremental capability upgrades.
- Retrofits:Brownfield integration of AGV fleets and collaborative robots into existing conveyor infrastructure dominates mid-size warehouse projects. Legacy WMS integration friction from 2010s proprietary stacks resists API connectivity with modern orchestration layers.
- New Installations:Greenfield e-commerce fulfillment centers in Germany's logistics corridor and the US Midwest distribution belt specify fully integrated robotic systems from commissioning.
- Upgrades:Sensor network overlays and AI-driven predictive maintenance convergence create software-only revenue streams without hardware replacement.
- Expandable Systems:Modular shuttle and robotic cell architectures allow capacity scaling without operational disruption.
Retrofits dominate project volume. New Installations are expanding most quickly as urban periphery micro-fulfillment construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Midwest distribution centers prioritize autonomous mobile fleets and robotic piece-picking for e-commerce velocity, while German logistics corridors emphasize energy-dense electrification under EU Green Deal mandates. This consumption-mix differential reflects labor cost pressures in North America versus carbon-accounting compliance in Europe.
United States
OSHA ergonomic enforcement and repetitive motion injury mandates are accelerating collaborative robot deployment across Illinois and Ohio fulfillment hubs. The EPA refrigerant rules are forcing cold-storage providers toward lower-GWP thermal systems. Chicago's urban periphery anchors micro-fulfillment construction for same-day grocery and fashion delivery.
Germany
EU F-Gas Regulation compliance and national carbon targets are compressing lithium-ion forklift adoption timelines in Baden-Württemberg and North Rhine-Westphalia. The EU Machinery Directive's 2023 collaborative robot safeguarding updates are redesigning human-robot work cells. Duisburg's logistics corridor concentrates high-throughput sortation investments for cross-border e-commerce.
United Kingdom
Fashion and grocery verticals are deploying vision-guided robots at 200-unit scales per fulfillment site around London and the Midlands. GDPR data governance requirements shape warehouse execution software procurement for 3PL operators. Milton Keynes hosts dense clustering of autonomous mobile fleet pilot programs for retail distribution.
Netherlands
Tax treatment favoring operating leases over capital expenditure is driving robotics-as-a-service adoption among Dutch cold-chain operators. EU Green Deal electrification mandates accelerate AGV deployment in Rotterdam's port logistics zone. Venlo's distribution parks concentrate pharmaceutical GDP-compliant automation for EU-wide distribution.
Poland
Maintenance technician scarcity is extending mean-time-to-repair for advanced robotics beyond acceptable SLAs in Warsaw and Wrocław logistics hubs. The EU Machinery Directive's CE marking protocols add commissioning complexity for collaborative applications. Silesia's emerging distribution centers face workforce gaps that constrain robotic fleet scaling.
US and Europe Warehouse Automation Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that dominates niche verticals and regional service networks. The upper tier commands turnkey integration contracts for greenfield e-commerce fulfillment centers, while specialists anchor retrofit opportunities and aftermarket service revenue. Three archetypes define competitive positioning: full-stack system integrators with captive software stacks, component specialists with deep vertical expertise, and regional service providers leveraging proximity for maintenance response. M&A activity concentrates on software capability acquisition and geographic service network expansion, while strategic partnerships between robotics OEMs and battery suppliers are collapsing powertrain deployment timelines.
Among Germany-based fabricators, Jungheinrich AG and KNAPP AG occupy distinct positioning archetypes that exemplify the specialist-versus-integrator divide. Dematic leverages its North American service network density to anchor large-scale e-commerce deployments. Swisslog represents the pharmaceutical cold-chain specialization vector. These three names illustrate how geographic origin and vertical focus shape competitive differentiation without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Dematic |
| Swisslog |
| SSI Schaefer |
| Jungheinrich AG |
| KNAPP AG |
| Honeywell International Inc |
| TGW Logistics Group |
| Vanderlande |
| Beumer Group |
| Others |
Pricing and Supply Chain Analysis
CE marking and OSHA certification protocols gate both supplier qualification and price differentiation in warehouse automation, compressing margins for uncertified vendors while rewarding integrated players with captive compliance capabilities. EU Machinery Directive safeguarding updates and EPA refrigerant rules force simultaneous engineering redesigns and cost recertification, bifurcating the vendor base into price-takers and premium-positioned system integrators.
Pricing Analysis
Long-term service contracts and robotics-as-a-service subscriptions dominate procurement structures, with Dutch tax treatment favoring operating leases over capital expenditure recognition. Price differentiation separates pharmaceutical GDP-validated cold-chain systems from standard material handling equipment, while copper and rare-earth volatility in motor and sensor inputs intensifies cost compression across mid-size retrofit projects. E-commerce operators exhibit highest price sensitivity due to compressed payback period requirements, whereas pharmaceutical cold-chain buyers prioritize compliance-validated premiums over unit economics.
Supply Chain Analysis
Germany and China anchor precision fabrication of robotic end effectors and AGV drive systems, with South Korea supplying lithium-ion powertrain cells. The supply chain draws from rare-earth magnet processors in Asia-Pacific and sensor fabs in Taiwan, creating single-source vulnerability around neodymium procurement. Distribution runs through regional system integrators with captive service networks in the US Midwest and Germany's logistics corridor, limiting direct OEM access for smaller warehouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multi-tenant 3PL operators and large e-commerce platforms, fragmenting the vendor landscape as procurement scale tilts toward robotics-as-a-service aggregators. This consolidation among automation buyers compresses pricing leverage for component specialists lacking integrated software stacks.
For Market Incumbents: Consolidate software capability acquisition to lock in recurring revenue streams and raise switching costs for 3PL operators facing multi-vendor integration friction. Expand North American and German service network density to capture maintenance technician scarcity premiums, while backward integration into lithium-ion powertrain supply hedges against rare-earth volatility threatening margin stability in AGV deployments. For New Entrants and Emerging Players: Lead with AI-driven predictive maintenance overlays targeting Poland and Ohio logistics hubs where maintenance workforce gaps extend commissioning timelines. Spain and Italy warehouse modernization offers penetrable white-space for automated sortation systems, with pharmaceutical cold-chain specialization providing defensible entry against established German fabricators through GDP-compliant temperature validation capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-native orchestration layers as hardware unbundling accelerates, favoring asset-light platform models over captive manufacturing. Viable acquisition targets include regional service providers with maintenance response density in underpenetrated southern European corridors. Monitor EU F-Gas Regulation compliance timelines as inflection signal for stranded capital risk in legacy thermal system portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Software Capability Acquisition | Captive warehouse execution systems lock in 3PL recurring revenue and raise switching costs. |
| Regional Service Network Expansion | Proximity maintenance response captures technician scarcity premiums in Poland and Ohio. |
| Pharmaceutical Cold-Chain Specialization | GDP-compliant automation commands premium pricing under EU and FDA traceability mandates. |
| Lithium-Ion Powertrain Integration | EU Green Deal electrification timelines favor integrated battery-AGV deployment models. |
| AI-Driven Predictive Maintenance Development | Machine learning overlays create software-only revenue without hardware replacement cycles. |
Research Methodology
Operator-level perspectives from warehouse operations directors, 3PL procurement leads, AGV fleet managers, and aftermarket service heads anchored the qualitative base for this study. Primary fieldwork combined with secondary validation from SEC filings of listed automation vendors, EU Machinery Directive implementation guidance, OSHA enforcement databases, and customs trade data on material handling equipment imports. Bottom-up project pipeline analysis and top-down macroeconomic triangulation shaped volume and value estimates.
Sensitivity analysis tested forecast robustness across labor cost inflation scenarios, copper price volatility bands, and regulatory compliance timeline shifts over the projection horizon. Segmentation dimensions modeled include technology maturity, procurement channel structure, end-use vertical, installation type, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle compression, with e-commerce fulfillment density and EU carbon-accounting standards as industry-specific demand inputs.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce velocity, stable rare-earth supply, or unaltered OSHA and EU Machinery Directive enforcement would require recalibration. Forecasts reflect documented assumptions around labor scarcity persistence and electrification subsidy continuity. Recalibration cycles align with material shifts in EU Green Deal implementation pace and 3PL outsourcing adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Sortation Systems Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
India Warehouse Automation Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Motion Control Market
Industrial Automation
Asia Pacific Retail Automation Market
Industrial Automation
Grippers Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Factory Automation Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Industry 4.0 Market