
 Magnetic Coupler Market | 2026-2036
Magnetic Coupler Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Coupler Market Insights
Software-defined torque calibration is expanding how magnetic coupler vendors monetize hardware deployments. ABB leverages its digital twin platform to anchor recurring service revenue alongside unit sales. Siemens competes through in-house production of rare-earth-free magnet arrays, while MagnaDrive specializes in eddy-current configurations for marine pump applications.
A magnetic coupler transmits torque between rotating shafts through magnetic flux rather than mechanical contact, typically employing NdFeB or ferrite magnet arrays separated by a containment can rated for pressures exceeding 40 bar. This contactless architecture eliminates seal wear in corrosive fluid handling and isolates torsional vibration in precision drive trains. Permanent magnet couplings dominate installed base value owing to efficiency advantages in continuous-duty pumps and compressors, though resonant coupling architectures represent the fastest-growing technology segment as wireless power transfer demands scale in autonomous robotics. OEM procurement channels command the deepest margin pools due to specification influence during system design.
FDA 21 CFR Part 177 compliance governs magnetic coupler materials in US food and pharmaceutical processing equipment, while REACH restricts certain rare-earth processing chemicals in European supply chains. China's GB standards for explosion-proof electrical equipment constrain import pathways for offshore platform couplings. Stakeholders must monitor rare-earth export licensing shifts and magnet recycling mandates as these regulatory levers reshape total cost of ownership calculations and supplier qualification timelines.
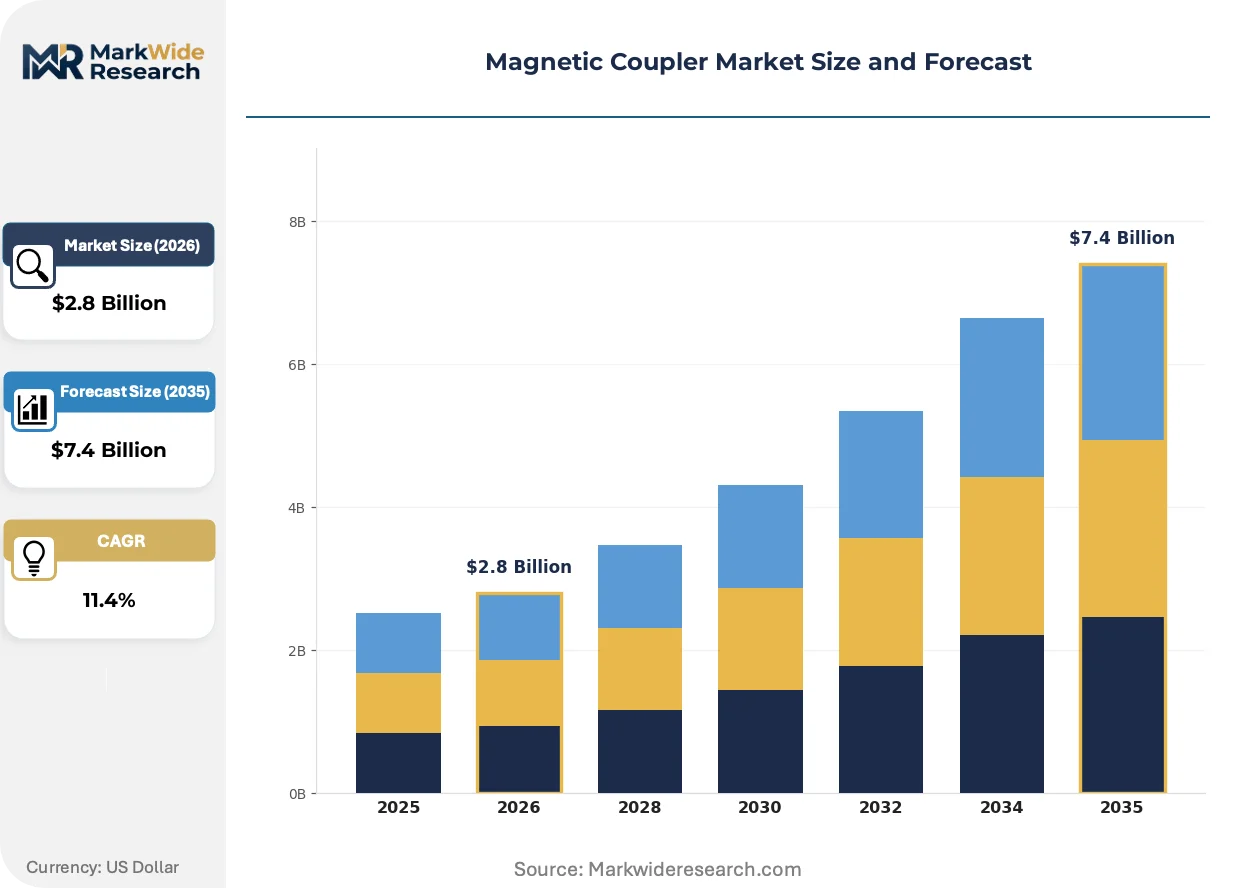
Market Dynamics
Permanent magnet designs are displacing mechanical couplings across fluid handling and precision drive applications, while rare-earth supply concentration and EU chemical regulations reshape procurement economics and supplier qualification timelines.
Growth Catalysts
- EU F-Gas Regulation:Refrigeration and HVAC system integrators accelerate adoption of hermetic magnetic couplings to eliminate mechanical seals and reduce fluorinated gas leakage risks.
- Renewable energy clusters:Germany, China, and the United States anchor procurement demand as wind turbine and solar thermal system builders specify contactless torque transmission for maintenance reduction.
- NdFeB magnet arrays:Continuous-duty pump OEMs favor permanent magnet configurations over eddy-current alternatives for efficiency gains in 24-hour process operations.
Market Restraints
- Rare-earth oxide volatility:Neodymium and dysprosium price swings compress margin predictability for manufacturers dependent on Chinese refined magnet feedstock.
- REACH chemical restrictions:European manufacturers face extended qualification timelines as ECHA-listed substances in rare-earth processing trigger supply chain reconfiguration costs.
- Mechanical coupling residual cost advantage:Standard gear and elastomeric couplings retain specification share in non-corrosive, low-precision applications where seal wear is tolerable.
Strategic Opportunities
- Autonomous robotics wireless power:Resonant magnetic coupling architectures penetrate mobile robot charging and tool-changing stations as factory automation density rises.
- Marine pump retrofits:Eddy-current configurations capture replacement demand in seawater ballast and cooling systems where corrosion-resistant containment cans outlast mechanical seals.
- China GB explosion-proof standards:Offshore platform coupling import pathways create localization incentives for domestic manufacturers serving CNOOC and Sinopec procurement.
Industry Challenges
- Magnet array calibration expertise:Shortage of engineers skilled in flux field modeling and torque ripple mitigation slows product development cycles for mid-tier suppliers.
- FDA 21 CFR Part 177 compliance:Food and pharmaceutical equipment manufacturers face 12-18 month material certification timelines for containment can alloys and surface coatings.
- Legacy pump fleet integration:Retrofit magnetic couplings onto existing ANSI and API pump footprints require custom adapter fabrication and torsional analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Coupler Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Permanent Magnet, Electromagnetic, Hybrid, Eddy Current Technology: Wireless Power Transfer, Magnetic Gear, Inductive Coupling, Resonant Coupling Application: Robotics, Aerospace Systems, Marine Equipment, Renewable Energy Systems End User: OEMs, Maintenance Providers, System Integrators, Equipment Distributors |
| Companies Covered | ABB, Altra Industrial Motion, Danfoss, EagleBurgmann, Ebara Corporation, KTR Systems, MagnaDrive, Rexnord, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Coupler Market Trends and Innovations
Software-defined torque calibration and digital twin integration are expanding how vendors monetize hardware deployments, while regulatory chemical restrictions and buyer consolidation reshape competitive positioning across supply chains.
Halbach array magnet configurations concentrate magnetic flux on one side of the coupling ring, delivering higher torque density per unit volume than conventional radial magnet arrangements. Pharmaceutical and semiconductor equipment builders in Switzerland and Germany adopt these arrays for compact vacuum pump drives. This geometry is expanding into medical device manufacturing where footprint constraints and precision torque control converge.
REACH authorization requirements for certain rare-earth processing chemicals force European manufacturers to qualify alternative magnet suppliers or invest in recycling feedstock streams. The restriction creates compliance cost tiering between integrated producers with captive magnet capacity and assembly-focused competitors. Food processing and fine chemical segments face the steepest supplier requalification burdens as ECHA substance evaluations proceed.
System integrators now bundle magnetic couplers with predictive maintenance subscriptions rather than discrete hardware transactions. Industrial automation clusters in Stuttgart, Shanghai, and Detroit drive this model as OEMs seek to reduce total cost of ownership calculations for end-users. The shift compresses traditional distribution margins while anchoring recurring revenue for vendors with embedded sensor and connectivity capabilities.
Magnetic Coupler Market Segmentation
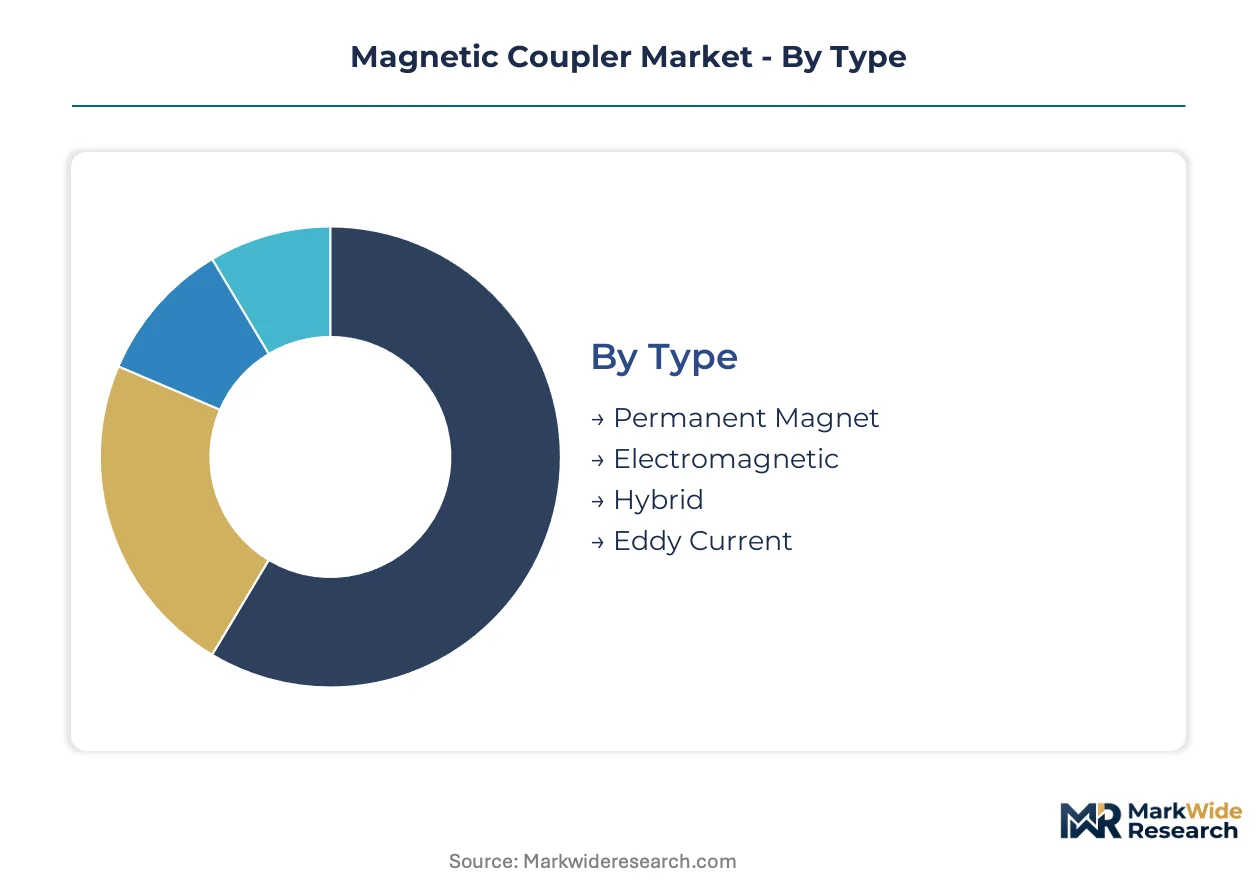
Magnetic coupler procurement patterns diverge sharply between standalone retrofit applications and embedded system architectures, with integration depth determining margin structures and supplier qualification requirements across industrial verticals.
Type:
Standalone magnetic couplers dominate replacement cycles in existing pump and compressor fleets, while embedded configurations anchor new system specifications where torque transmission integrates with motor-drive packages.
- Permanent Magnet:NdFeB or ferrite arrays transmit torque through fixed magnetic fields without electrical excitation, delivering efficiency above 95% in continuous-duty pumps. Demand clusters with German and Chinese process equipment OEMs specifying hermetic sealing for fluorinated gas containment under EU F-Gas Regulation.
- Eddy Current:Conductive disks generate torque through electromagnetic induction, tolerating larger air gaps and misalignment than synchronous alternatives. Marine pump retrofits in United States coastal facilities drive adoption where seawater corrosion accelerates mechanical seal failure.
- Electromagnetic:Field windings enable variable torque transmission through current modulation, suited to dynamic load matching in test bench applications.
- Hybrid:Combines permanent magnet bias with electromagnetic control for programmable slip characteristics in precision positioning systems.
Volume placements concentrate in Permanent Magnet; the faster expansion belongs to Eddy Current.
Technology:
Cost tiering separates mature inductive architectures from emerging resonant designs, with wireless power transfer commanding premium positioning in battery-dependent mobile systems.
- Inductive Coupling:Near-field energy transfer through coupled coils dominates industrial fluid handling where containment can pressure ratings exceed 40 bar. Standard configurations anchor mid-market pricing in chemical processing and HVAC applications.
- Resonant Coupling:Tuned LC circuits enable efficient power transfer across larger air gaps, critical for autonomous robotics charging stations. Factory automation density in Stuttgart and Detroit accelerates specification as mobile robot fleets expand.
- Wireless Power Transfer:High-frequency magnetic field architectures penetrate medical device and consumer electronics manufacturing where galvanic isolation is mandatory.
- Magnetic Gear:Pole-pair modulation achieves speed conversion without mechanical contact, finding niche adoption in offshore wind turbine drivetrains.
Inductive Coupling retains the largest installed base; Resonant Coupling is climbing the fastest as wireless charging infrastructure scales.
Application:
Customer type determines procurement channel selection, with OEM specifications locking in multi-year supply agreements while maintenance providers drive spot-market transactions.
- Renewable Energy Systems:Wind turbine pitch drives and solar thermal tracking systems specify contactless couplings for maintenance reduction in remote installations. Procurement concentrates with system integrators serving German and Chinese energy clusters.
- Marine Equipment:Seawater ballast and cooling pumps employ corrosion-resistant containment cans to eliminate seal wear. United States shipyard retrofits and Chinese offshore platform builds under GB explosion-proof standards anchor demand.
- Robotics:Collaborative and mobile robot joints require compact torque transmission with zero backlash for precision positioning.
- Aerospace Systems:Fuel pump and actuator applications leverage magnetic isolation in explosive atmosphere environments.
Renewable Energy Systems generate the deepest specification influence; Marine Equipment is gaining share fastest from mechanical seal replacement cycles.
End User:
Supply concentration varies by buyer sophistication, with integrated OEMs qualifying captive magnet sources while distributors aggregate fragmented maintenance demand.
- OEMs:Pump, compressor, and turbine manufacturers embed magnetic couplings during original system design, capturing margin through specification control. FDA 21 CFR Part 177 compliance requirements in United States food and pharmaceutical equipment extend qualification timelines to 12-18 months.
- System Integrators:Automation and process engineering firms bundle couplers with predictive maintenance subscriptions, shifting revenue from hardware to recurring service models.
- Maintenance Providers:Independent service contractors source replacement couplings for ANSI and API pump retrofits, requiring custom adapter fabrication.
- Equipment Distributors:Regional industrial supply houses aggregate spot demand from smaller process plants with limited in-house engineering.
OEMs command the highest margin pools; System Integrators are expanding most quickly through outcome-based contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates magnet production while Germany and the United States anchor consumption in precision manufacturing and renewable energy systems. This geographic split creates procurement complexity as buyers navigate rare-earth supply chains and regional certification requirements.
United States
FDA 21 CFR Part 177 compliance requirements extend material qualification timelines to 12-18 months for food and pharmaceutical equipment manufacturers. Marine pump retrofits along Gulf Coast shipyards drive eddy-current coupling demand where seawater corrosion accelerates mechanical seal failure. Detroit-area automation clusters specify resonant coupling architectures for mobile robot charging infrastructure.
Germany
EU F-Gas Regulation accelerates hermetic magnetic coupling adoption in refrigeration and HVAC systems to eliminate fluorinated gas leakage risks. REACH authorization requirements for rare-earth processing chemicals force manufacturers to requalify alternative magnet suppliers. Stuttgart industrial automation clusters bundle couplers with predictive maintenance subscriptions, shifting revenue from hardware to recurring service models.
China
GB standards for explosion-proof electrical equipment constrain import pathways for offshore platform couplings, creating localization incentives for domestic manufacturers. NdFeB magnet array production concentrates in Inner Mongolia and Jiangxi provinces, supplying global pump OEMs. CNOOC and Sinopec procurement programs favor domestic suppliers meeting dual carbon goals and MEE environmental compliance.
Japan
METI industrial efficiency standards promote contactless torque transmission in precision drive trains for semiconductor and medical device manufacturing. JIS certification requirements govern containment can pressure ratings in chemical processing applications. Nagoya-area automotive suppliers specify magnetic couplings for electric vehicle thermal management systems.
Switzerland
Swissmedic pharmaceutical equipment regulations align with FDA standards, streamlining export pathways to United States markets. Halbach array configurations penetrate vacuum pump drives for semiconductor manufacturing in Basel and Zurich clusters. Fine chemical processors face steep REACH compliance burdens as ECHA substance evaluations proceed.
Magnetic Coupler Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the magnetic coupler value chain. Integrated manufacturers with captive magnet capacity command margin predictability advantages over assembly-focused competitors dependent on spot-market rare-earth feedstock. Three archetypes dominate: diversified industrial conglomerates with digital service platforms, specialized coupling fabricators with marine and chemical process expertise, and magnet array producers backward-integrated into coupling assembly. Competitive moves center on strategic partnerships with system integrators and geographic expansion into Chinese offshore platform procurement.
Among diversified industrial conglomerates, ABB and Siemens occupy positions anchoring digital twin and rare-earth-free magnet strategies respectively. MagnaDrive exemplifies the specialized fabricator archetype with concentrated expertise in eddy-current marine applications. KTR Systems and Rexnord represent mid-tier mechanical power transmission players extending portfolios into contactless architectures.
| Leading Market Players |
|---|
| ABB |
| Altra Industrial Motion |
| Danfoss |
| EagleBurgmann |
| Ebara Corporation |
| KTR Systems |
| MagnaDrive |
| Rexnord |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Pump and compressor OEM procurement concentration in Germany, China, and the United States anchors contract-based long-term offtake pricing with volume-scaled discounts, while rare-earth feedstock volatility forces continuous renegotiation of magnet array cost pass-through clauses.
Pricing Analysis
Margin tightening in standard permanent magnet configurations reflects NdFeB oxide price swings from Chinese refined feedstock. Three-tier pricing structure across premium Halbach arrays, standard synchronous couplings, and economy ferrite designs separates FDA-certified pharmaceutical tiers from industrial process grades. Cost-down pressure on mid-tier suppliers accelerates as system integrators bundle predictive maintenance subscriptions, compressing discrete hardware margins. Maintenance providers exhibit highest price sensitivity due to spot-market procurement patterns, while OEMs lock in multi-year agreements with captive magnet sources.
Supply Chain Analysis
Refurbishment flows for containment cans and magnet arrays remain underdeveloped, though REACH chemical restrictions are forcing European manufacturers toward recycling feedstock streams. NdFeB magnet production concentrates in China, Germany, and Japan, with conductive disk fabrication for eddy-current variants drawing from United States and South Korean specialty steel mills. Single-source vulnerability in Chinese rare-earth oxide refining creates exposure to export licensing shifts. Distribution runs through OEM direct channels for new system specifications, while aftermarket demand aggregates via regional industrial distributors and maintenance contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic coupler competition is consolidating around backward integration into magnet array production and forward integration into digital service platforms, with rare-earth supply security and predictive maintenance software emerging as the decisive capability differentiators.
For Market Incumbents: Lock in captive NdFeB supply through long-term offtake agreements with Inner Mongolia and Jiangxi producers, or qualify rare-earth-free ferrite alternatives to hedge Chinese export restrictions. Expand digital twin deployment to anchor recurring service revenue and defend against system integrators disintermediating hardware margins. Prioritize FDA 21 CFR Part 177 pre-certification to extend qualification timelines as a competitive moat against mid-tier challengers. For New Entrants and Emerging Players: Enter via marine pump retrofit channels where eddy-current expertise gaps exist among incumbent mechanical coupling specialists, particularly United States Gulf Coast shipyards and Chinese offshore platforms under GB explosion-proof standards. Target autonomous robotics wireless charging as the fastest-expanding specification segment with lower incumbent lock-in. Lead with resonant coupling engineering services rather than hardware manufacturing to bypass capital-intensive magnet array fabrication. For Investors and Strategic Acquirers: The window for entry favors specialized coupling fabricators with marine and chemical process expertise over diversified industrial conglomerates with stagnant contactless torque R&D. Mid-tier players with Halbach array IP and system integrator partnerships present acquisition appeal as OEMs consolidate supplier bases. Monitor ECHA substance evaluation timelines for REACH-listed rare-earth processing chemicals as an inflection signal for European supply chain reconfiguration costs and domestic recycling infrastructure investment triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Array Production | Captive NdFeB supply from Inner Mongolia secures margin predictability against Chinese export licensing volatility. |
| Digital Twin Platform Deployment | ABB's predictive maintenance subscriptions shift revenue from hardware transactions to recurring service contracts. |
| REACH-Compliant Recycling Infrastructure | European manufacturers requalify alternative magnet suppliers as ECHA restrictions trigger supply chain reconfiguration. |
| Marine Pump Retrofit Channel Expansion | United States coastal facilities and Chinese offshore platforms drive eddy-current replacement demand. |
| Resonant Coupling R&D Investment | Stuttgart and Detroit automation clusters specify wireless charging for mobile robot fleet expansion. |
Research Methodology
Document review covered customs and trade data for magnetic component flows, SEC filings from diversified industrial conglomerates, and ECHA substance evaluation databases, complemented by interviews with pump OEM procurement directors, marine maintenance contractors, system integrator automation engineers, and rare-earth magnet trading specialists. Secondary validation drew from GB standards documentation for explosion-proof equipment, FDA 21 CFR Part 177 material certification records, and EU F-Gas Regulation implementation reports. Bottom-up unit economics for coupling configurations triangulated against top-down market sizing from industrial automation capital expenditure disclosures.
Segment-level projections across the modeling period incorporated permanent magnet versus eddy-current technology splits, OEM versus system integrator channel dynamics, and renewable energy versus marine application demand trajectories. CAGRs derived from regression analysis of historical rare-earth oxide price elasticity and pump OEM order backlogs. Industry-specific inputs included REACH chemical restriction implementation timelines and Chinese dual carbon policy enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden NdFeB export licensing restrictions or accelerated EU magnet recycling mandates. Practitioners should monitor ECHA authorization list updates and CNOOC domestic procurement preference shifts for early signals of supply chain reconfiguration velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Total Containment Vessels Market
Valves
Sliding Sleeves Market
Valves
Middle East and Africa Machined Seals Market
Valves
North America Irrigation Valves Market
Valves
North America High Voltage Switchgear Market
Valves
Dense Phase Vessels Market
Valves
Subsea Valves Market
Valves
North America Industrial Valves Market
Valves
Choke Valves Market
Valves
Gate Impellers Market
Valves
Actuators and Valves Market
Valves
Flanges Market
Valves
Pipeline Pigging Equipment Market
Valves
Liner Regulators Market
Valves
Pneumatic Positioner Market
Valves
Sanitary Valves Market