
 Acetum Market | 2026-2036
Acetum Market Size, Share, and Industry Trends Forecast 2026-2036
Acetum Market Outlook
Fermentation process digitization is rewriting how acetum producers control acidity profiles and batch consistency. Acetum S.p.A. leverages its Modena-rooted supply chain to dominate aged balsamic production. Mizkan Holdings Co., Ltd. anchors Asian rice vinegar supply through captive brewing infrastructure. The Kraft Heinz Company competes in North American retail channels with standardized acidity vinegars for mass-market condiment lines.
Acetum denotes fermented ethanol-derived liquid containing acetic acid, typically at four to eight percent acidity by volume, produced through sequential alcoholic and acetic acid fermentation of carbohydrate substrates. Its primary commercial purpose spans food preservation, flavor modulation, and pH control across industrial and culinary applications. Wine vinegar and balsamic vinegar command premium positioning in European and North American specialty retail, while rice vinegar sustains faster volume growth through Asian cuisine globalization and food manufacturing integration. Distribution through supermarkets captures the broadest household reach, though specialty stores concentrate margin pools for aged and denomination-protected grades.
EU Regulation 1169/2011 and the FDA's Food Safety Modernization Act shape acetum labeling, allergen disclosure, and import verification requirements across the Atlantic. REACH compliance for processing aids and EFSA evaluations of fermentation-derived compounds further filter market access for non-European suppliers. Stakeholders must monitor evolving denomination-of-origin enforcement and acetic acid threshold harmonization between Codex Alimentarius and national food codes.
Market Dynamics
Fermentation process digitization is compressing batch-to-batch variation in acetic acid production, forcing traditional acetum houses to retool legacy equipment or cede share to precision-controlled competitors.
Growth Catalysts
- Clean-label mandate acceleration:EU Regulation 1169/2011 tightens ingredient disclosure thresholds, compelling food manufacturers to reformulate with recognizable acetum rather than synthetic acidulants.
- Asian cuisine globalization:Rice vinegar demand concentrates in North American and European foodservice channels as sushi and fermentation-based diets expand beyond ethnic enclaves.
- Denominazione di Origine Protetta enforcement:Italy's balsamic vinegar geographic indication rules harden, creating scarcity premiums that pull investment into aged stockpiling and certified aging facilities.
Market Restraints
- Input cost volatility:Wine grape supply fluctuations in France and Spain transmit directly to wine vinegar feedstock pricing, compressing margins for non-integrated producers.
- Supply concentration risk:Premium aged balsamic production clusters in Modena and Reggio Emilia provinces, exposing buyers to single-region climate and labor disruption.
- Acetic acid threshold harmonization delays:Divergent Codex Alimentarius and national food code standards create formulation complexity for exporters serving multiple jurisdictions.
Strategic Opportunities
- Functional beverage white space:Apple cider vinegar wellness positioning unlocks ready-to-drink formats in North American and European convenience retail.
- Bioplastics feedstock pivot:Polyhydroxyalkanoate manufacturers are sourcing fermentation-derived acetic acid as a renewable monomer input, creating industrial off-take agreements.
- E-commerce direct-to-chef channels:Specialty aged grades bypass traditional wholesale tiers through platform sales to restaurant purchasing managers seeking provenance documentation.
Industry Challenges
- Microbiologist talent scarcity:Acetobacter strain management and contamination control require specialized fermentation expertise that outpaces vocational training pipeline output.
- Legacy equipment retrofit costs:Traditional wooden barrel aging systems resist sensor integration, forcing capital-intensive parallel infrastructure builds for digitized inventory tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetum Market |
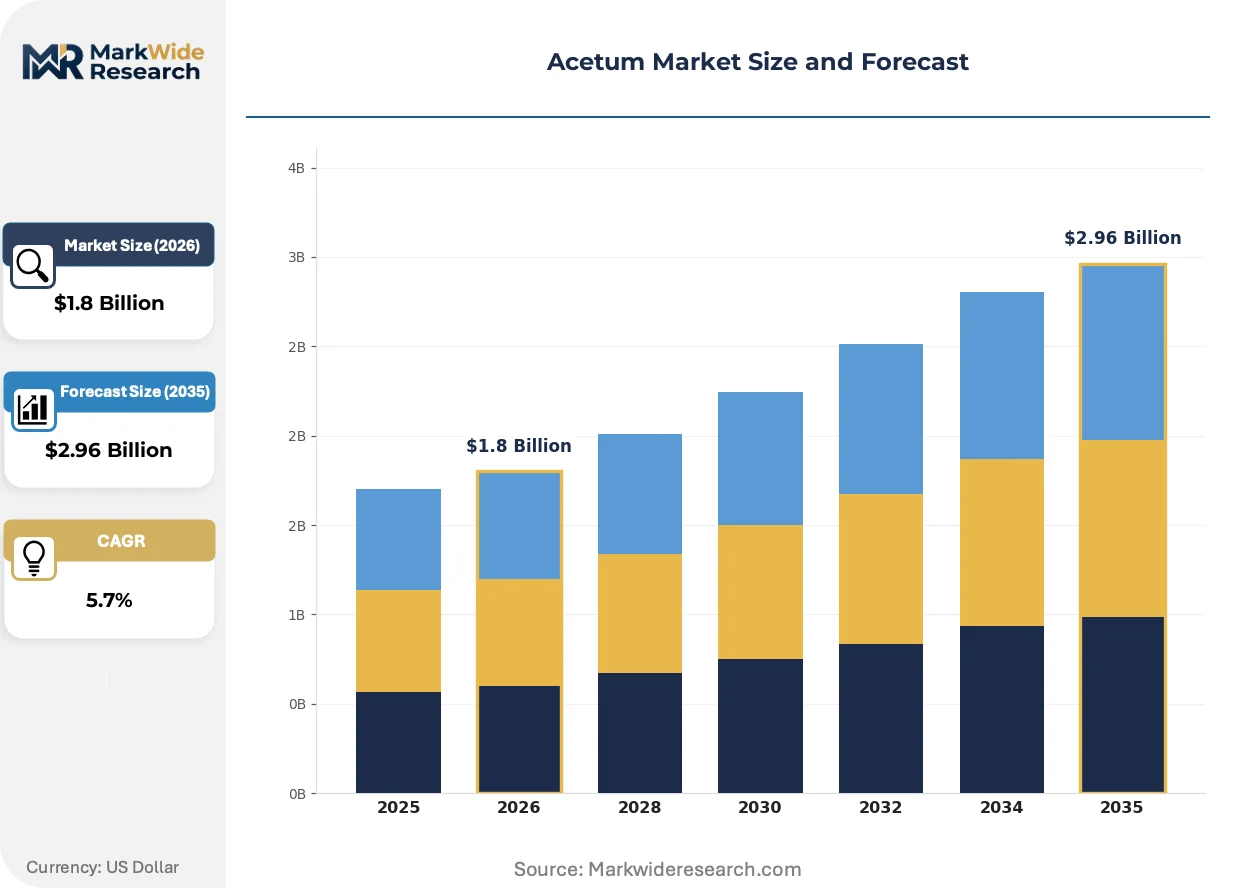
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wine Vinegar, Balsamic Vinegar, Cider Vinegar, Rice Vinegar Application: Food Industry, Beverage Industry, Cosmetic Industry, Pharmaceutical Industry Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Customer Type: Households, Restaurants, Food Manufacturers, Retail Chains |
| Companies Covered | Acetum S.p.A., The Kraft Heinz Company, Mizkan Holdings Co., Ltd., Burg Group B.V., Ponti S.p.A., Shanxi Shuita Vinegar Co., Ltd., Carl Kühne KG, Kikkoman Corporation, Aspall Cyder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetum Market Strategic Shifts
Acetum production is bifurcating between artisanal heritage methods and precision-controlled industrial systems, with regulatory compliance and traceability demands accelerating technology adoption across both tiers.
Continuous fermentation monitoring using dissolved oxygen and pH sensor arrays is digitizing acidity profile control in large-scale acetum facilities. North American condiment manufacturers are adopting these systems fastest, driven by FSMA lot-traceability mandates. Real-time data streams compress quality assurance cycles from weeks to hours while reducing out-of-specification batch destruction rates.
EFSA evaluations of fermentation-derived compounds are tightening novel processing aid approvals across European Union member states. The regulatory friction is forcing non-European suppliers to pre-validate alternative bacterial strains and nutrient media before market entry. Italian and Spanish denomination-protected producers benefit from grandfathered traditional process exemptions that newer competitors cannot replicate.
Food manufacturers are consolidating vinegar procurement through qualified supplier programs rather than spot-market purchasing. Large European retail chains now require blockchain-traceable supply documentation for private-label condiments. This specification creep concentrates volume with integrated producers capable of certifying grape origin, fermentation duration, and acidity stability across multi-year contracts.
Acetum Market Segmentation
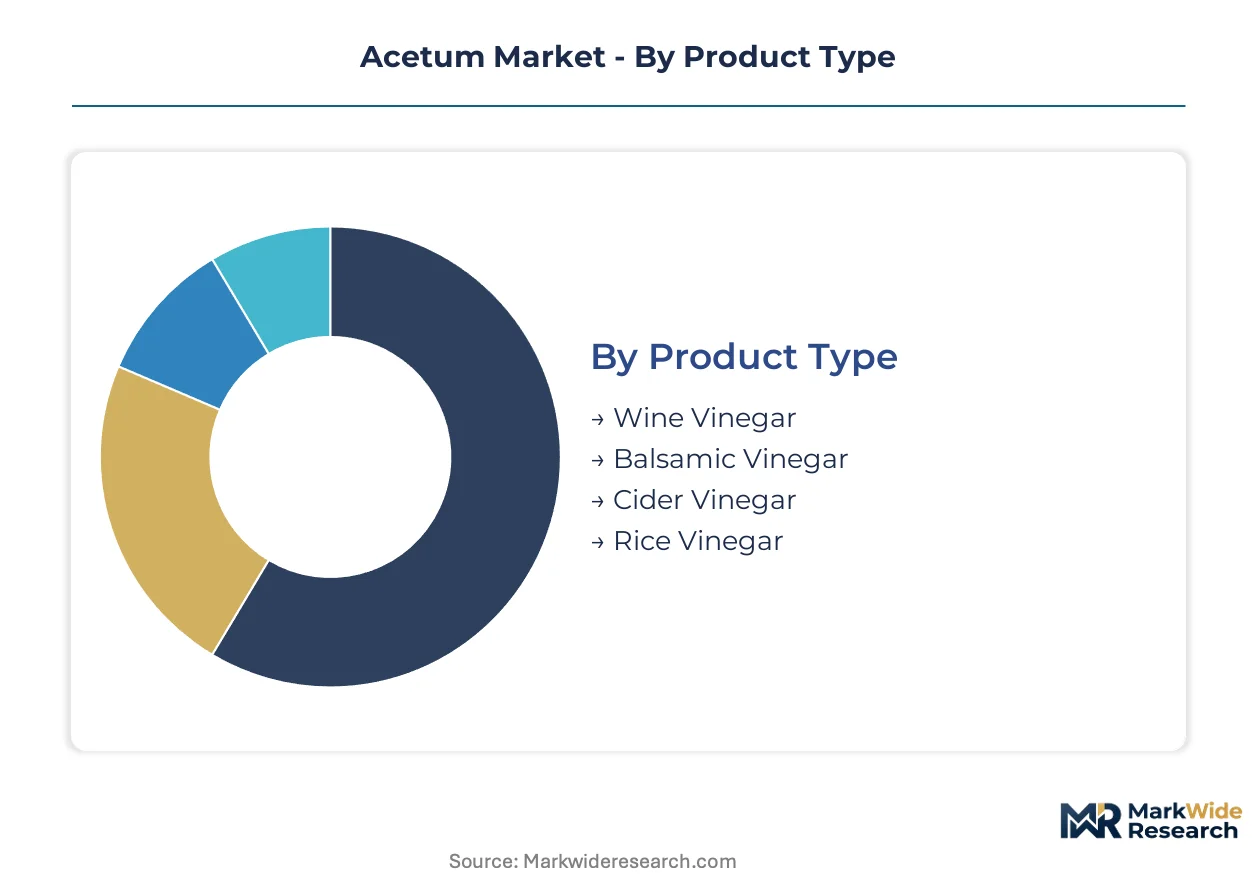
Acetum demand fragments across distinct quality tiers and procurement channels that shape pricing power and margin capture. Manufacturers must calibrate fermentation scale, aging investment, and certification compliance to serve each segment profitably.
Product Type:
Cost tier determines capital intensity and margin structure across acetum categories, separating commodity acidulants from denomination-protected specialties.
- Wine Vinegar:Fermented grape ethanol yielding 6-8% acetic acid concentration, produced through submerged or surface acetification methods. French and Spanish wine vinegar demand concentrates in food manufacturing acidulant procurement, constrained by grape supply volatility in Languedoc and La Rioja regions.
- Balsamic Vinegar:Cooked grape must aged in wooden barrels for minimum 12 years under Denominazione di Origine Protetta rules, achieving 1.24-1.36 density and complex polyphenol profiles. Modena and Reggio Emilia production clusters command scarcity premiums through certified aging facility investments and geographic indication enforcement.
- Cider Vinegar:Apple-derived fermentation product with 5-6% acidity, gaining functional beverage positioning in North American wellness retail.
- Rice Vinegar:Japanese and Chinese brewing traditions producing mild 4-5% acidity through koji mold saccharification, expanding through Asian cuisine globalization in European and North American foodservice.
Wine vinegar commands the established base. The steepest expansion runs through rice vinegar.
Application:
End-use specifications diverge sharply between industrial pH control requirements and culinary authenticity demands.
- Food Industry:Bulk acidulant procurement for sauce, dressing, and preservation applications requiring consistent 5% acidity and neutral flavor profiles. EU Regulation 1169/2011 clean-label mandates are displacing synthetic acidulants with fermented acetum in processed food formulations.
- Beverage Industry:Functional drink formulations leveraging apple cider vinegar's acetic acid content for wellness positioning, constrained by FDA fermentation byproduct disclosure requirements and stability challenges in ready-to-drink formats.
- Cosmetic Industry:pH balancing and antimicrobial applications in natural skincare, regulated by REACH processing aid compliance for fermentation-derived compounds.
- Pharmaceutical Industry:Excipient and topical antiseptic applications requiring pharmacopeial-grade acetic acid purity certification.
Food industry absorption represents the dominant volume anchor. Beverage applications are climbing the fastest.
Distribution Channel:
Channel selection dictates margin retention and provenance documentation requirements across customer tiers.
- Supermarkets:Mass-market condiment placement capturing household volume through standardized acidity private-label programs, with European retail chains now mandating blockchain-traceable supply documentation.
- Specialty Stores:Premium and denomination-protected grade concentration where aged balsamic and single-varietal wine vinegars achieve 3-4x supermarket price multiples through provenance storytelling.
- Online Retail:Direct-to-chef and subscription formats bypassing wholesale tiers, enabling small-batch producers to certify fermentation duration and grape origin digitally.
- Direct Sales:Food manufacturer and foodservice contract supply through multi-year qualified supplier programs, consolidating volume with integrated producers capable of certifying acidity stability.
Supermarkets retain the volume base. Online retail is gaining share fastest.
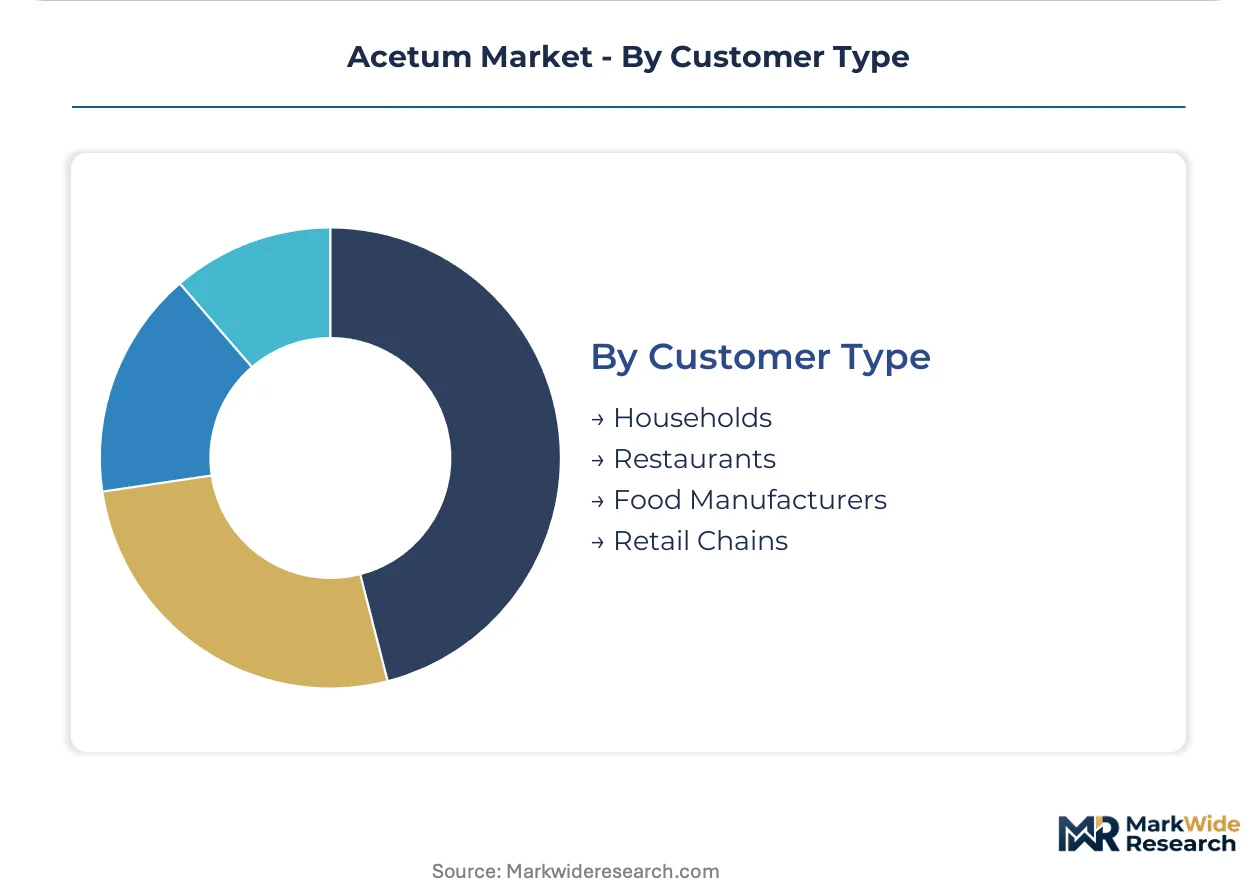
Customer Type:
Procurement sophistication separates spot-market purchasers from contract-integrated buyers with traceability requirements.
- Food Manufacturers:Large-scale acidulant procurement for reformulation programs, consolidating supply through qualified supplier frameworks rather than spot-market purchasing to satisfy clean-label mandates.
- Restaurants:Chef-driven demand for denomination-protected and single-origin grades, sourcing through specialty distributors and direct e-commerce platforms with provenance documentation requirements.
- Households:Supermarket and online retail purchasing of standardized acidity condiments, with premium migration limited by price sensitivity.
- Retail Chains:Private-label program development requiring multi-year acidity stability guarantees and blockchain-traceable grape origin certification.
Food manufacturers anchor contract volume. Restaurant procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian balsamic vinegar flows into German retail chains and French food manufacturing plants, anchoring Europe's premium acetum trade corridor while Asian rice vinegar shipments expand through North American foodservice distributors.
Italy
Denominazione di Origine Protetta enforcement hardens geographic indication rules for Modena and Reggio Emilia aged balsamic production. EU Regulation 1169/2011 clean-label mandates accelerate vinegar procurement from certified aging facilities. Emilia-Romagna's wooden barrel cooperatives concentrate investment into traceable stockpiling infrastructure.
United States
Apple cider vinegar wellness positioning drives functional beverage formulation in convenience retail channels. FDA Food Safety Modernization Act lot-traceability requirements compress quality assurance cycles for condiment manufacturers. California's fermentation technology clusters adopt dissolved oxygen sensor arrays fastest among domestic producers.
Japan
Rice vinegar demand concentrates in foodservice channels as sushi cuisine expands beyond ethnic enclaves into European and North American markets. METI standards for fermentation-derived processing aids shape import verification protocols for foreign suppliers. Kansai region's koji mold saccharification facilities sustain captive brewing infrastructure for mild acidity output.
China
Shanxi province's aged vinegar traditions supply domestic food manufacturing acidulant demand while industrial acetic acid production scales for bioplastics feedstock agreements. SAMR food safety standards tighten fermentation byproduct disclosure requirements for export-oriented facilities. Zhenjiang and Shanxi production clusters diversify into pharmacopeial-grade purity certification for pharmaceutical excipient applications.
Spain
Wine vinegar production in La Rioja and Catalonia faces grape supply volatility transmitting directly to feedstock pricing for non-integrated acidulant suppliers. EFSA evaluations of fermentation-derived compounds filter market access for non-European competitors. Andalusian sherry vinegar denomination protections create scarcity premiums through certified aging facility investments.
Acetum Market Competitive Environment
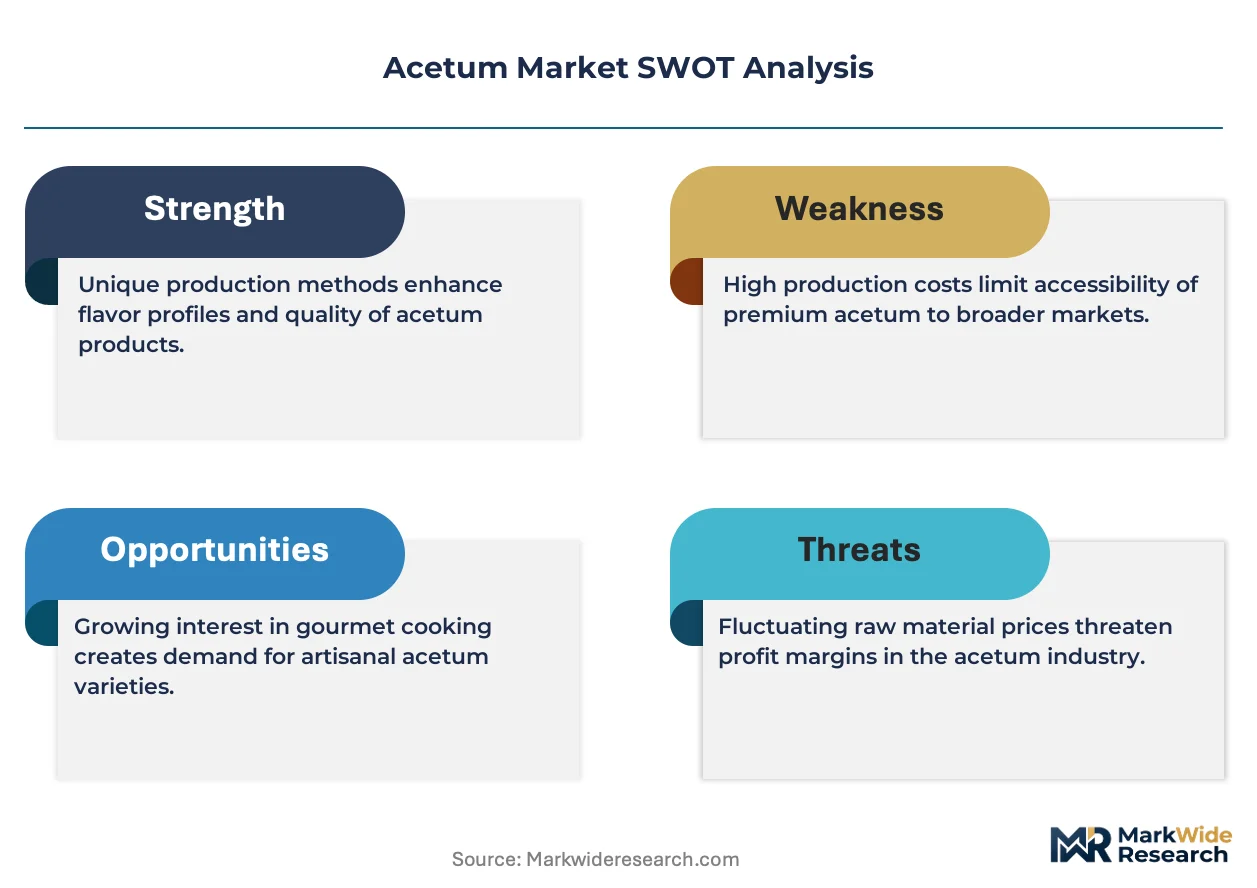
On the supply side, the industry is bifurcating between heritage wooden barrel houses and precision-controlled industrial facilities, with regulatory compliance demands accelerating consolidation around integrated producers capable of blockchain-traceable documentation. Three strategic archetypes dominate: denomination-protected aging specialists, mass-market acidulant manufacturers, and Asian fermentation tradition holders. Competitive moves concentrate on qualified supplier program enrollment and captive raw material sourcing.
Within the European heritage tier, Acetum S.p.A. and Ponti S.p.A. exemplify Modena-rooted supply chain control, while Mizkan Holdings Co., Ltd. anchors Asian rice vinegar positioning through Japanese brewing infrastructure. The Kraft Heinz Company occupies standardized acidity mass-market placement in North American retail channels. These three represent distinct geographic and tier specializations rather than overlapping competitive terrain.
| Leading Market Players |
|---|
| Acetum S.p.A. |
| The Kraft Heinz Company |
| Mizkan Holdings Co., Ltd. |
| Burg Group B.V. |
| Ponti S.p.A. |
| Shanxi Shuita Vinegar Co., Ltd. |
| Carl Kühne KG |
| Kikkoman Corporation |
| Aspall Cyder |
| Others |
Value Chain & Pricing Dynamics
Modena and Reggio Emila's wooden barrel cooperatives concentrate aged balsamic production, anchoring scarcity premiums that pull margin pools toward denomination-protected grades while commodity wine vinegar competes on feedstock efficiency.
Pricing Analysis
Heritage-generation wooden barrel aging commands 3-4x premiums over precision-controlled industrial acetification, while next-generation digitized fermentation systems compress batch-to-batch variation costs. Three-tier pricing structure across Denominazione di Origine Protetta, qualified supplier program, and spot-market commodity levels stratifies the market. Pricing pressure stems from wine grape supply volatility in Languedoc and La Rioja transmitting directly to non-integrated producers. Food manufacturers show highest price sensitivity through qualified supplier consolidation, while restaurant purchasers accept premiums for provenance documentation.
Supply Chain Analysis
Contract fermentation capacity concentrates with Acetum S.p.A., Mizkan Holdings, and The Kraft Heinz Company across Italy, Japan, and North American production hubs. Raw material flows draw from Emilia-Romagna grape must, Kansai region koji mold saccharification, and California apple orchards. Single-region climate disruption in Modena province poses structural vulnerability to aged stockpiles. Distribution runs through supermarket private-label programs, specialty retail tiers, and direct-to-chef e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetum market fragmentation creates niche opportunities as clean-label mandates displace synthetic acidulants and Asian cuisine globalization diversifies rice vinegar demand beyond traditional foodservice channels.
For Market Incumbents: Harden denomination-protected inventory positions through certified aging facility expansion in Modena and Reggio Emila provinces. Acquire blockchain-traceable documentation capabilities to secure qualified supplier program enrollment against precision-controlled competitors. Invest in dissolved oxygen sensor arrays to compress quality assurance cycles for FSMA compliance.
For New Entrants and Emerging Players: Pursue functional beverage white space in North American apple cider vinegar ready-to-drink formats. Target bioplastics feedstock off-take agreements with polyhydroxyalkanoate manufacturers seeking fermentation-derived acetic acid. Deploy direct-to-chef e-commerce channels with digital provenance certification to bypass wholesale tier concentration.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated producers combining captive raw material sourcing with multi-jurisdiction certification compliance over a 5-10 year viability window. Prioritize acquisition targets with grandfathered traditional process exemptions under EFSA evaluation frameworks. Monitor EU Regulation 1169/2011 enforcement intensity as inflection indicator for clean-label reformulation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Aging Facility Investment | Denominazione di Origine Protetta compliance secures scarcity premiums in Modena and Reggio Emilia provinces. |
| Blockchain Traceability Integration | European retail chains now mandate supply documentation for private-label condiment program enrollment. |
| Functional Beverage Formulation | Apple cider vinegar wellness positioning unlocks ready-to-drink distribution in North American convenience retail. |
| Bioplastics Feedstock Pivot | Polyhydroxyalkanoate manufacturers source fermentation-derived acetic acid for renewable monomer agreements. |
| Direct-to-Chef E-Commerce Launch | Specialty aged grades bypass wholesale tiers through platform sales to restaurant purchasing managers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, customs trade data, and food manufacturing procurement databases. Interviews with fermentation plant managers, retail category buyers, restaurant purchasing managers, and regulatory affairs specialists informed supply chain and pricing dynamics. Secondary validation drew from EFSA evaluation records, FDA Food Safety Modernization Act guidance documents, and denomination-of-origin enforcement case files. Bottom-up volume modeling triangulated against top-down macroeconomic consumption patterns.
Forecast inputs span product type tiering, application end-use specifications, distribution channel concentration, and customer procurement sophistication across the projection horizon. Segmentation dimensions modeled include acidity grade, aging certification status, geographic origin protection, and customer contract integration level. CAGRs derived from regression analysis of historical consumption trajectories adjusted for regulatory mandate implementation timelines and cuisine globalization penetration rates. Wine grape harvest variability and acetic acid threshold harmonization progress served as key scenario modifiers.
Sensitivities concentrate around EU Regulation 1169/2011 enforcement acceleration, Codex Alimentarius standard convergence delays, and single-region climate disruption in Emilia-Romagna. Forecasts reflect documented assumptions on clean-label reformulation pace and Asian foodservice expansion trajectories. Quarterly review of grape must pricing indices, EFSA processing aid approval timelines, and retail chain traceability mandate adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Erucic Acid Market
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
Colloidal Silver Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Electrical Insulating Varnish for Motor Vehicle Market
Specialty Chemicals
Cellulose Ether Market